
 Smart Personal Protective Equipment Market | 2026-2036
Smart Personal Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Personal Protective Equipment Market Outlook
Modular sensor kits bundled with base protective gear is hardening as the dominant procurement pattern for industrial buyers. 3M Company leverages its materials science heritage to anchor premium smart respirator lines with embedded biometric tracking. Honeywell International Inc. competes through integrated gas detection and connectivity platforms that extend its traditional safety franchise into data-driven offerings. Vuzix Corporation specializes in augmented reality visor systems that differentiate its portfolio from commodity PPE suppliers.
Smart personal protective equipment denotes conventional safety gear augmented with embedded sensors, wireless communication modules, and edge-processing capability to deliver real-time hazard alerts and physiological monitoring, typically manufactured through cleanroom assembly of microelectronic components onto textile or polymer substrates and sealed to IP67 ingress standards for harsh environments. Helmets with integrated IoT connectivity and multi-sensor arrays represent the leading product configuration, capturing the largest installed base across heavy industry. Augmented reality-enabled visors and wearable tech layers are expanding fastest as utilities and emergency services adopt heads-up display guidance for high-risk procedures. Fall protection and respiratory protection applications concentrate margin pools where predictive analytics reduce incident liability and insurance premiums.
OSHA mandates in the United States, CE marking requirements under the EU Machinery Directive, and Japan's METI industrial safety standards collectively shape product certification pathways and cross-border market access for smart PPE manufacturers. China's GB standards for electrical safety equipment and India's BIS certification for protective textiles add further compliance layers that filter supplier participation in Asia-Pacific procurement. Stakeholders must monitor evolving interoperability standards between connected safety platforms and enterprise asset management systems as the decisive factor for long-term contract viability.
Market Dynamics
OSHA's tightened workplace safety monitoring requirements are compressing procurement cycles as construction firms across the United States accelerate replacement of legacy helmets and vests with sensor-embedded alternatives. Federal infrastructure spending is pulling connected PPE into standard jobsite equipment lists faster than supplier capacity can expand.
Growth Catalysts
- OSHA mandates:The United States is tightening real-time hazard monitoring requirements, forcing construction and heavy industry to upgrade legacy protective gear with embedded biometric and environmental sensors.
- Federal infrastructure spending:Union-mandated safety upgrades on federally funded projects are creating a concentrated demand pull for connected helmets and vests as standard equipment.
- Sensor miniaturization:Advances in low-power microelectronics and edge-processing capability are enabling multi-sensor arrays to be sealed to IP67 standards without compromising wearer comfort.
Market Restraints
- Semiconductor supply concentration:Critical sensor and wireless communication modules depend on concentrated East Asian foundry capacity, exposing procurement timelines to geopolitical friction.
- Battery chemistry volatility:Lithium-ion cell costs fluctuate with raw material extraction constraints, compressing margins on rechargeable smart PPE product lines.
- Interoperability fragmentation:Absence of unified data protocols between connected safety platforms and enterprise asset management systems creates integration friction for industrial buyers.
Strategic Opportunities
- Emergency services AR adoption:Augmented reality-enabled visors for heads-up display guidance during high-risk procedures remain underpenetrated in municipal fire and rescue departments.
- India's BIS certification pathway:Protective textile standards are evolving to accommodate sensor-embedded fabrics, opening procurement channels for exporters meeting localized electrical safety requirements.
- Predictive analytics bundling:Convergence of fall protection hardware with incident liability reduction software creates subscription revenue models that insurers are beginning to subsidize.
Industry Challenges
- Embedded systems engineering talent:Cleanroom assembly of microelectronic components onto textile substrates requires scarce cross-functional expertise combining materials science with RF engineering.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of OSHA compliance, CE marking under the EU Machinery Directive, and Japan's METI industrial safety standards extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Personal Protective Equipment Market |
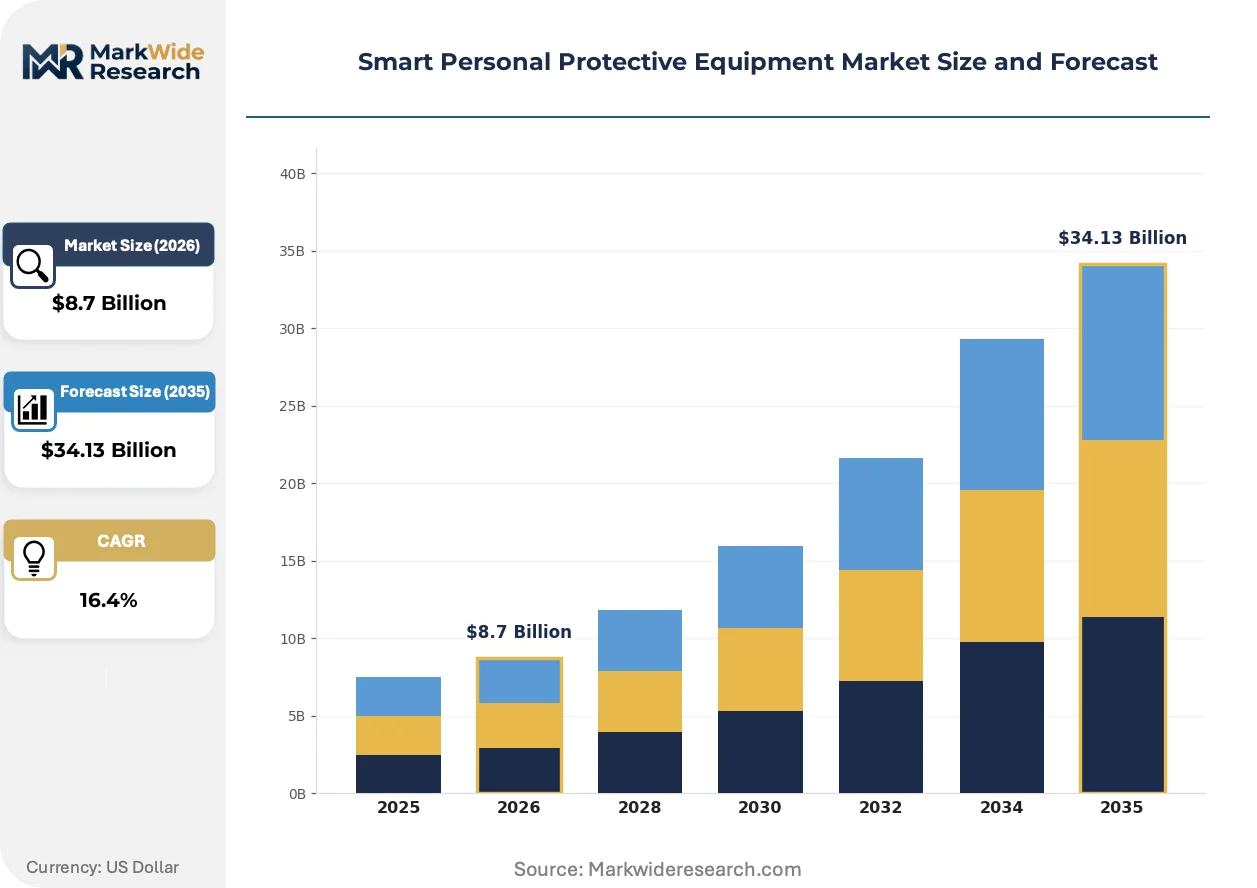
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Gloves, Vests, Gaiters Technology: IoT Integration, Sensors, Wearable Tech, Augmented Reality End User: Construction, Manufacturing, Healthcare, Emergency Services Application: Fall Protection, Respiratory Protection, Electrical Safety, Thermal Protection |
| Companies Covered | Ansell Ltd., Uvex Group, 3M Company, Vuzix Corporation, DuPont, Honeywell International Inc., Delta Plus Group, MCR Safety, MSA Safety Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Personal Protective Equipment Market Strategic Shifts
Modular sensor architecture is displacing monolithic smart PPE designs as industrial buyers demand upgrade paths that protect capital investment. Platform interoperability is becoming the decisive specification criterion in long-term supply contracts.
Edge-processing capability within helmet-mounted sensor arrays is consolidating hazard detection and alert generation at the point of use, reducing dependency on cloud connectivity in remote construction environments. Mining operators in Australia and Canada are deploying these systems in underground operations where network infrastructure remains sparse. The consolidation of compute onto the device itself is compressing response latency from seconds to milliseconds, directly impacting incident prevention efficacy.
The EU AI Act's risk classification framework is reshaping procurement specifications for machine-learning-enabled hazard prediction in European industrial settings. Connected PPE incorporating algorithmic decision-making now faces mandatory conformity assessments that extend certification timelines. German automotive manufacturers and French energy utilities are front-loading compliance investment to secure preferred supplier status ahead of enforcement deadlines.
Industrial buyers are unbundling hardware procurement from data analytics subscriptions, treating sensor-embedded helmets and vests as capital equipment while purchasing predictive safety software through annual licenses. This bifurcation is displacing bundled lifetime-value contracts that dominated early smart PPE commercialization. The shift is most visible in United States construction markets where union training funds and contractor insurance pools operate as separate budget lines with distinct approval cycles.
Smart Personal Protective Equipment Market Segmentation
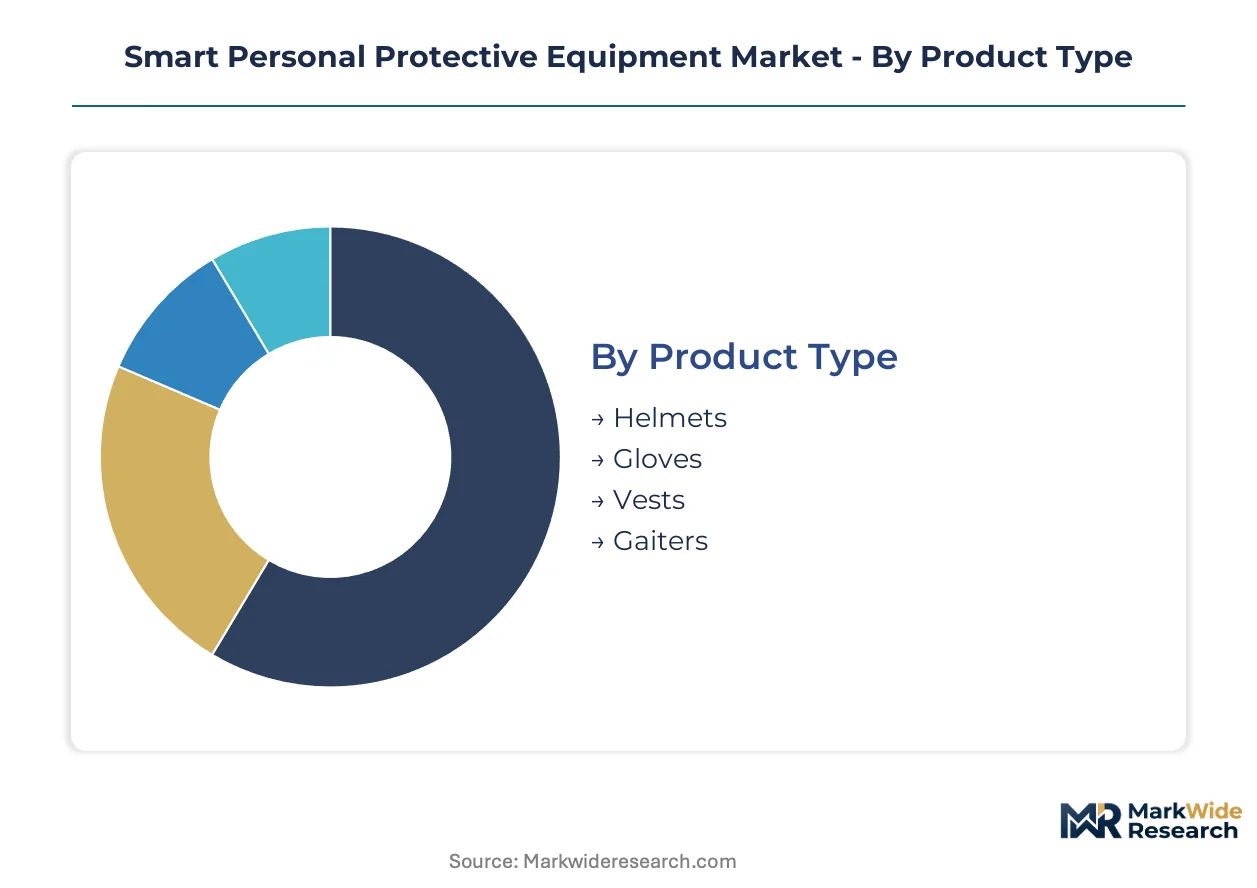
Smart PPE procurement patterns diverge sharply across product configurations, sensor architectures, and hazard-specific applications. Understanding these fault lines reveals where supplier R&D investments concentrate and which end-use verticals drive premium pricing.
Product Type:
Supply concentration in helmet manufacturing creates procurement bottlenecks as foundry capacity for embedded sensor modules tightens.
- Helmets:Hard hats integrating multi-sensor arrays for impact detection, proximity alerts, and biometric monitoring dominate installed bases across heavy construction and mining operations. United States federal infrastructure projects now specify connected helmets as standard equipment, pulling demand ahead of supplier capacity expansion.
- Vests:Sensor-embedded high-visibility garments incorporating GPS tracking, heat stress monitors, and fall-detection accelerometers are gaining share fastest among unionized construction crews where real-time worker location tracking reduces incident response times. OSHA compliance timelines are compressing procurement cycles for these units.
- Gloves:Haptic feedback and force-sensing capabilities embedded in cut-resistant materials address precision manufacturing and electrical work hazards.
- Gaiters:Lower-limb protective gear with environmental monitoring sensors serves niche applications in hazardous material handling and cold-weather extraction industries.
Today's leader: Helmets. Tomorrow's challenger: Vests.
Technology:
Cost tier stratification separates capital-intensive augmented reality systems from commoditized sensor modules.
- IoT Integration:Wireless connectivity platforms enabling real-time data transmission to enterprise asset management systems form the backbone of connected safety architectures. Construction firms in the United States prioritize interoperability with existing site management software over standalone functionality.
- Augmented Reality:Heads-up display visors overlaying procedural guidance and hazard warnings command premium pricing in emergency services and utility maintenance where hands-free information access prevents fatal errors. Municipal fire departments remain underpenetrated, creating expansion headroom.
- Sensors:Discrete biometric and environmental monitoring components embedded across multiple PPE categories.
- Wearable Tech:Consumer-derived form factors adapted for industrial durability standards.
IoT Integration anchors current procurement volumes. Augmented Reality offers the steepest expansion trajectory.
End User:
Application-specific certification requirements fragment supplier participation across vertical markets.
- Construction:Union-mandated safety upgrades and OSHA hazard monitoring mandates are accelerating replacement of legacy protective gear with sensor-embedded alternatives. Federal infrastructure spending concentrates demand pull in the United States market.
- Emergency Services:Fire departments and rescue units are adopting AR-enabled visors for high-risk procedure guidance, though budget constraints slow municipal procurement relative to private industrial buyers.
- Manufacturing:Automotive and electronics assembly lines deploy haptic-enabled gloves and proximity-sensing vests for repetitive strain and collision prevention.
- Healthcare:Biometric monitoring PPE for infectious disease containment and clinician fatigue management remains nascent outside specialized hospital systems.
Construction commands current volume leadership. Emergency Services present the most underpenetrated expansion opportunity.
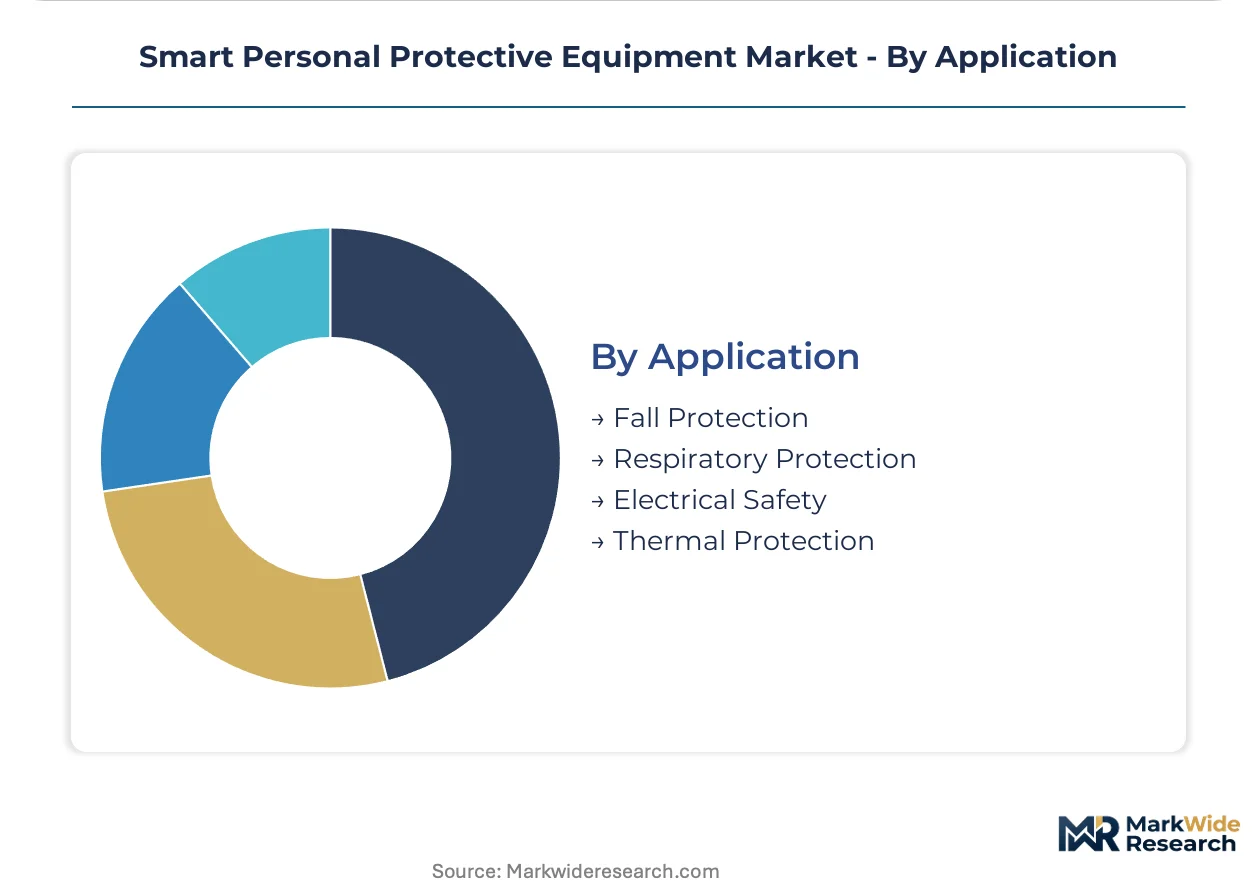
Application:
Margin pools concentrate where predictive analytics demonstrably reduce incident liability and insurance premiums.
- Fall Protection:Harness-integrated accelerometers and anchor-point sensors enabling real-time elevation tracking and automatic alert generation capture the largest share of predictive safety software bundling. Insurers are beginning to subsidize these systems where historical claims data validates risk reduction.
- Respiratory Protection:Smart respirators with embedded biometric tracking and filter saturation monitoring address confined space entry and hazardous atmosphere work, with premium pricing sustained by materials science differentiation in sealing and breathability.
- Electrical Safety:Arc-flash detection and voltage proximity sensing integrated into gloves and face shields.
- Thermal Protection:Heat stress monitoring and burn-prevention sensors for foundry, smelting, and firefighting applications.
Fall Protection leads in data-driven subscription revenue models. Respiratory Protection maintains the most defensible technology moats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart personal protective equipment industry traces its commercial origins to United States industrial safety regulations that first mandated real-time worker monitoring in hazardous construction environments. Early sensor-embedded helmets and vests emerged from American mining and petrochemical safety programs before spreading to European and Asia-Pacific markets. Geographic expansion now follows divergent regulatory timelines and infrastructure investment cycles.
United States
Federal infrastructure spending and union-mandated safety upgrades are pulling connected PPE into standard jobsite equipment lists faster than supplier capacity can expand. OSHA's tightened workplace safety monitoring requirements are compressing procurement cycles for sensor-embedded helmets and vests. Construction firms in Texas and California are accelerating replacement of legacy protective gear with biometric-enabled alternatives ahead of compliance deadlines.
Germany
Automotive manufacturers and energy utilities are front-loading compliance investment to secure preferred supplier status ahead of EU AI Act enforcement deadlines. The EU AI Act's risk classification framework is reshaping procurement specifications for machine-learning-enabled hazard prediction. Industrial clusters in Bavaria and Baden-Württemberg are deploying AR-enabled visors for precision manufacturing and maintenance procedures.
China
GB standards for electrical safety equipment and protective textiles are adding compliance layers that filter supplier participation in domestic procurement. Mining operators in Shanxi and Inner Mongolia are deploying edge-processing helmet systems in underground operations where network infrastructure remains sparse. Local foundry capacity for sensor modules is tightening as domestic demand accelerates.
Japan
METI industrial safety standards are shaping product certification pathways for exporters seeking access to precision manufacturing and utility maintenance sectors. Automotive assembly lines in Aichi Prefecture are deploying haptic-enabled gloves and proximity-sensing vests for repetitive strain and collision prevention. Aging workforce demographics are driving demand for biometric fatigue monitoring in heavy industry.
Australia
Mining operators in Western Australia and Queensland are deploying edge-processing helmet-mounted sensor arrays in remote extraction environments where cloud connectivity is unreliable. The consolidation of compute onto the device itself is compressing response latency from seconds to milliseconds in underground operations. Resource sector capital expenditure cycles are pulling connected safety equipment into standard procurement specifications.
Smart Personal Protective Equipment Market Competitive Environment
Premium-margin players sit above commodity-margin players across materials science differentiation and integrated data platform capabilities. The market structure stratifies into three tiers: diversified industrial conglomerates with safety divisions, specialized connected device manufacturers, and component suppliers seeking downstream integration. Two dominant competitive moves are reshaping positioning: modular sensor architecture partnerships that protect buyer capital investment, and predictive analytics software bundling that creates subscription revenue streams.
Within the diversified industrial tier, 3M Company and Honeywell International Inc. exemplify scale-driven platform strategies that leverage existing safety equipment distribution channels. Vuzix Corporation occupies a position among specialized augmented reality device manufacturers focused on heads-up display differentiation. Ansell Ltd. and MSA Safety Inc. represent safety-equipment specialists extending traditional protective gear portfolios with embedded connectivity. These archetypes reflect divergent R&D investment patterns: materials science heritage versus microelectronics integration versus optical systems engineering.
| Leading Market Players |
|---|
| Ansell Ltd. |
| Uvex Group |
| 3M Company |
| Vuzix Corporation |
| DuPont |
| Honeywell International Inc. |
| Delta Plus Group |
| MCR Safety |
| MSA Safety Inc. |
| Others |
Value Chain & Pricing Dynamics
Cleanroom microelectronic assembly onto textile substrates is displacing conventional sealed-unit manufacturing, simultaneously compressing unit economics and concentrating production among foundries with certified cleanroom capacity in Taiwan, South Korea, and Japan. This dual shift tightens supplier pricing power while forcing buyers into longer contract terms to secure allocation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AR-enabled visor systems from modular sensor kits and basic connected helmets. Price differentiation rests on certification grade and after-sales analytics bundling. Cost compression in the economy tier is intensifying because semiconductor module supply tightens. Municipal fire departments exhibit highest price sensitivity; mining operators in Australia and Canada show lowest.
Supply Chain Analysis
Freight costs from East Asian sensor foundries to North American assembly plants are amplifying landed cost volatility for lithium-ion cells and RF communication modules. Supply concentrates in Taiwan for edge-processing chips, South Korea for display components, and China for battery cells. Single-source vulnerability in MEMS accelerometer supply exposes procurement timelines. Distribution runs through industrial safety distributors with certified technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in smart PPE rests on sensor miniaturization cost curves and the shift toward subscription-based predictive analytics bundling that captures recurring revenue from capital equipment sales.
For Market Incumbents: Deploy modular sensor architecture partnerships to protect buyer capital investment and extend replacement cycles. Deepen backward integration into MEMS foundry relationships to secure allocation against fabless entrants. Counter interoperability fragmentation by pre-certifying connectivity with dominant enterprise asset management platforms. For New Entrants and Emerging Players: Municipal emergency services departments represent the most penetrable buyer archetype, with AR-enabled visor adoption running years behind private industrial deployment. Target India's evolving BIS certification pathway for protective textiles as a regulatory moat against established exporters. Lead with predictive analytics software licensing to bypass hardware margin compression. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers with captive cleanroom assembly capability and dormant safety equipment distribution channels. Five-to-ten-year viability favors platforms with demonstrated interoperability across OSHA, CE marking, and METI compliance frameworks. Watch for insurer subsidy programs for fall protection analytics as the decisive demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Sensor Architecture Partnerships | Protects buyer capital investment while locking in long-term component supply contracts with construction firms. |
| Predictive Analytics Software Bundling | Creates subscription revenue streams that insurers subsidize where claims data validates incident reduction. |
| Multi-Jurisdiction Certification Pre-Investment | Secures preferred supplier status ahead of EU AI Act enforcement deadlines for algorithmic hazard prediction. |
| Edge-Processing Capability Integration | Reduces cloud dependency for mining operators in remote extraction environments with sparse network infrastructure. |
| AR Visor Platform Standardization | Accelerates municipal fire department procurement by reducing training costs and interoperability friction. |
Study Parameters
Multiple input streams — primary interviews with safety equipment procurement managers, embedded systems engineers, and industrial insurance underwriters; secondary validation through OSHA regulatory filings, EU Machinery Directive conformity databases, and customs trade records for sensor module imports — were reconciled through bottom-up and top-down triangulation.
Historical shipment data was cross-referenced against panel input from connected safety platform vendors to anchor projections across the analysis window. Segmentation dimensions modeled include product configuration, sensor architecture tier, end-use vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating federal infrastructure spending cycles and compliance deadline phasing.
Underlying measurement precision varies by segment; construction and mining applications carry tighter precision than healthcare and emergency services given data availability. Forecasts reflect assumptions about semiconductor supply normalization and interoperability standard adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market