
 Europe Urban Security Screening Market | 2026-2036
Europe Urban Security Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Urban Security Screening Market Analytics
Buyer concentration across European transportation authorities is shifting from fragmented municipal procurement toward centralized framework agreements at the national level. Smiths Detection Group Ltd. leverages its established presence in aviation security to extend into urban transit screening contracts. Thales Group anchors its competitive position through deep integration with French national rail operator systems. L3Harris Technologies Inc. competes on the strength of its millimeter-wave body scanner portfolio adapted for crowded public venues.
Urban security screening encompasses the deployment of detection and identification systems at access points to intercept weapons, explosives, and unauthorized materials in densely populated environments. X-ray machines with dual-energy imaging capability differentiate organic from inorganic substances at throughput rates exceeding 2,000 bags per hour. Metal detectors retain the largest installed base across European public transportation nodes, though explosives trace detectors represent the fastest-expanding technology segment as operators address evolving threat profiles. Fixed installations dominate capital expenditure, while mobile units capture growing share among venue operators managing rotating event calendars.
CE marking under the EU Machinery Directive and compliance with the EU AI Act govern biometric scanner deployment, while national regulators such as Germany's KBA and France's ANSM enforce data protection standards for passenger information collection. REACH restrictions on hazardous substances in manufacturing constrain component sourcing and elevate compliance costs for equipment suppliers. Stakeholders must weigh interoperability requirements against proprietary system lock-in as cross-border transit corridors demand unified screening protocols.
Market Dynamics
Centralized procurement frameworks across European transportation authorities are consolidating demand power and accelerating technology refresh cycles, compressing vendor negotiation timelines and favoring integrated system providers over point-solution specialists.
Growth Catalysts
- EU AI Act compliance mandates:Biometric-enabled detection platforms require algorithmic transparency and risk classification, forcing transit operators to upgrade legacy screening infrastructure to certified systems.
- Millimeter-wave body scanners:Crowded public venues including stadiums and concert halls deploy passive screening arrays that eliminate passenger bottlenecks while maintaining threat detection accuracy.
- Germany's federal rail modernization:Deutsche Bahn's infrastructure investment program prioritizes passenger safety systems at major hub stations, creating concentrated demand for integrated screening solutions.
Market Restraints
- GDPR data processing constraints:Biometric data retention limits and purpose restrictions complicate passenger screening database architecture and elevate legal compliance overhead.
- Sensor component concentration:Specialized semiconductor supply for millimeter-wave arrays concentrates among Asian foundries, exposing European equipment manufacturers to geopolitical supply disruptions.
- Dual-energy X-ray technical ceilings:Organic-inorganic differentiation accuracy degrades with composite threat materials, creating detection gaps that adversaries exploit.
Strategic Opportunities
- Poland and Eastern European transit expansion:EU cohesion fund investments in urban rail networks create greenfield deployment opportunities absent legacy system integration burdens.
- Mobile screening unit rental services:Venue operators managing rotating event calendars shift from capital purchase to operational expenditure models, opening recurring revenue streams.
- AI Act conformity assessment harmonization:Standardized certification pathways reduce vendor market entry friction and accelerate cross-border procurement standardization.
Industry Challenges
- Interoperability with legacy metal detector networks:Fixed installations using proprietary communication protocols resist integration with modern biometric and millimeter-wave platforms.
- Explosives trace detection calibration expertise:Specialized technician shortages delay deployment timelines and elevate service contract costs for transportation authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Urban Security Screening Market |
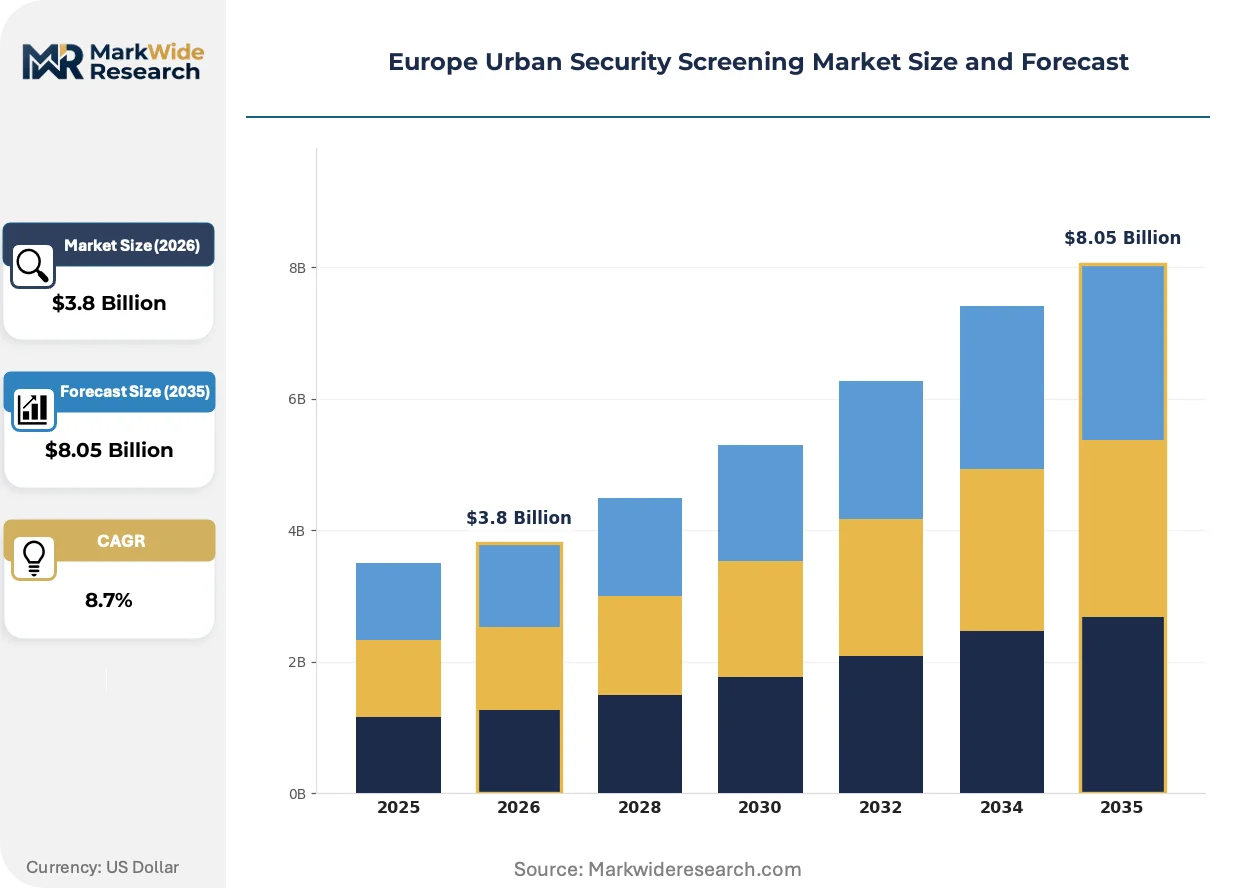
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-ray Machines, Metal Detectors, Explosives Trace Detectors, Biometric Scanners Application: Public Transportation, Airports, Shopping Malls, Special Events End User: Government Agencies, Private Security Firms, Transportation Authorities, Venue Operators Deployment: Fixed Installations, Mobile Units, Temporary Setups, Integrated Systems |
| Companies Covered | Smiths Detection Group Ltd., Leidos Holdings Inc., OSI Systems Inc., Teledyne Technologies, Thales Group, L3Harris Technologies Inc., 3DX-Ray Ltd, Teledyne ICM SA, Rapiscan Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Urban Security Screening Market Evolving Landscape
Edge computing architectures are redistributing processing load from central servers to screening device endpoints, enabling real-time threat classification without network latency dependencies. This shift compresses response times and reduces infrastructure investment requirements for distributed transit networks.
Passive millimeter-wave imaging is decentralizing security checkpoint architecture by eliminating passenger throughput bottlenecks. French national rail operators deploy walk-through screening corridors at Gare du Nord and Lyon Part-Dieu, replacing single-file metal detector queues. The technology compresses facility footprint requirements while maintaining detection sensitivity against concealed threats.
REACH substance restrictions on hazardous materials in manufacturing constrain component sourcing flexibility for European equipment suppliers. The regulation elevates compliance costs for sensor housings and electronic assemblies containing restricted phthalates and heavy metals. German manufacturers respond by accelerating supplier qualification programs and redesigning product architectures around compliant material substitutes.
Framework agreements are consolidating buyer power across municipal and national transportation authorities. United Kingdom rail franchise operators now procure screening systems through centralized Department for Transport contracts rather than individual station negotiations. The model compresses vendor margins while demanding extended service commitments and technology refresh guarantees.
Europe Urban Security Screening Market Segmentation
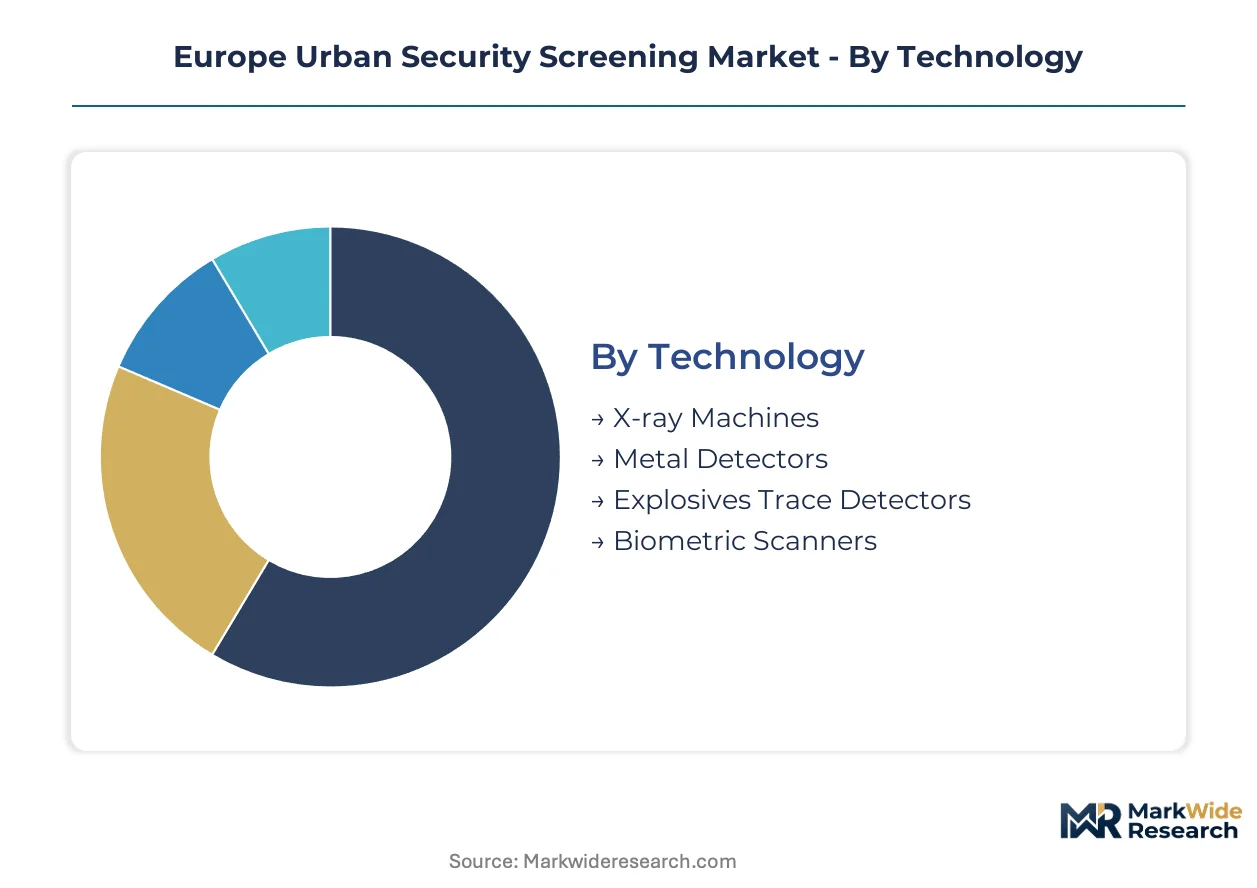
Segmentation reveals how certification burdens, procurement scale, and threat profiles concentrate demand across distinct equipment categories. Transportation authorities and venue operators face divergent compliance pathways and capital deployment timelines.
Technology:
CE marking under the EU Machinery Directive governs all four technology segments, though biometric scanners face additional EU AI Act algorithmic transparency requirements. Dual-energy X-ray systems require notified body assessment under stricter radiation safety protocols.
- X-ray Machines:Dual-energy imaging systems differentiate organic from inorganic materials at throughput rates exceeding 2,000 bags per hour. Deutsche Bahn's hub modernization program in Germany concentrates demand for integrated baggage screening tunnels at major rail terminals.
- Metal Detectors:Electromagnetic induction arrays retain the largest installed base across European transit nodes but face displacement pressure from passive screening alternatives. France's SNCF maintains extensive walk-through detector networks at secondary stations where upgrade budgets lag primary hubs.
- Explosives Trace Detectors:Ion mobility spectrometry and chemiluminescence devices address evolving threat profiles against concealed energetic materials. United Kingdom counter-terrorism grants accelerate procurement for Underground and national rail platforms.
- Biometric Scanners:Facial recognition and behavioral analysis platforms require GDPR data protection impact assessments and EU AI Act high-risk system registration. Dutch and Belgian transit operators pilot identity-verification corridors at Schengen border stations.
Leading the category by volume: Metal Detectors. Growing fastest: Explosives Trace Detectors.
Application:
Procurement scale and contract duration separate high-volume recurring purchasers from event-driven spot buyers. Framework agreement eligibility varies sharply across these four deployment contexts.
- Public Transportation:National rail operators and municipal transit authorities deploy layered screening at hub stations with passenger volumes exceeding 50,000 daily. Germany's federal-state procurement consortia consolidate demand across 16 Länder for rolling stock and station infrastructure.
- Airports:Aviation security regulations mandate certified hold baggage and passenger screening under stricter EASA oversight than urban transit. Major hubs in France, Germany, and the United Kingdom operate dedicated procurement teams with multi-year capital planning cycles.
- Shopping Malls:Private facility managers prioritize visible deterrence over comprehensive threat detection at entry points. Italian and Spanish retail complexes favor rapid-deployment metal detector arrays during high-traffic seasonal periods.
- Special Events:Rotating venue calendars drive rental and temporary installation demand rather than capital purchase. Polish and Czech event security contractors source mobile screening fleets through operational expenditure models.
Dominating procurement value: Public Transportation. Expanding most quickly: Special Events.
End User:
Budget authority and compliance liability distribute differently across public and private procurement entities. Government agencies carry sovereign risk tolerance; private operators demand service-level guarantees.
- Government Agencies:National police and interior ministries coordinate counter-terrorism screening at critical infrastructure and diplomatic venues. United Kingdom Home Office grants fund local authority transit security upgrades through competitive bidding rounds.
- Private Security Firms:Contracted venue protection services source equipment through lease-to-own arrangements with technology refresh clauses. Scandinavian markets consolidate around three major integrated security providers with captive screening divisions.
- Transportation Authorities:State-owned rail and metro operators maintain dedicated engineering departments for system integration and lifecycle management. RATP in France and Trenitalia in Italy operate centralized procurement with vendor pre-qualification registries.
- Venue Operators:Stadium and concert hall managers prioritize throughput speed to minimize entry friction and concession revenue loss. German Bundesliga clubs deploy millimeter-wave corridors at high-capacity football grounds.
Controlling largest installed base: Transportation Authorities. Gaining share fastest: Private Security Firms.
Deployment:
Capital intensity and technical integration requirements create distinct margin profiles across installation types. Fixed systems demand civil works coordination; mobile units require logistics optimization.
- Fixed Installations:Hardwired screening lanes with dedicated power and data infrastructure dominate hub station deployments. Austria's ÖBB embeds detection arrays into permanent architectural elements during major reconstruction projects.
- Mobile Units:Trailer-mounted and vehicle-portable systems serve rotating event calendars and emergency response protocols. Eastern European markets source rapid-deployment fleets for border crossing flexibility.
- Temporary Setups:Rapid-install configurations deploy for construction periods, summit conferences, or threat-level escalations. Brussels and Strasbourg activate supplemental screening during European Parliament plenary sessions.
- Integrated Systems:Multi-technology platforms combining X-ray, biometric, and trace detection into unified command interfaces command premium pricing. Switzerland's SBB pilots corridor-style walk-through screening at Zurich Hauptbahnhof.
Generating highest revenue concentration: Fixed Installations. Climbing the fastest: Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German semiconductor fabrication clusters supply millimeter-wave sensor arrays to screening equipment manufacturers across the continent. Dutch precision optics foundries produce dual-energy X-ray detector modules. French systems integration houses anchor biometric algorithm development for transit applications.
Germany
Deutsche Bahn's infrastructure investment program drives concentrated procurement of integrated baggage screening tunnels at major rail terminals. Germany's KBA enforces data protection standards for passenger information collection alongside EU AI Act compliance mandates. Bavaria hosts engineering centers where millimeter-wave corridor systems undergo pre-deployment testing for federal rail operator acceptance.
France
SNCF deploys passive millimeter-wave screening corridors at Gare du Nord and Lyon Part-Dieu to eliminate passenger bottlenecks. France's ANSM and CNIL jointly oversee biometric data processing impact assessments for facial recognition platforms. Paris-based systems integrators maintain deep relationships with national rail operator procurement divisions.
United Kingdom
Department for Transport framework agreements consolidate screening system procurement across rail franchise operators. United Kingdom Home Office counter-terrorism grants accelerate explosives trace detector deployment for Underground and national rail platforms. London's major hub stations serve as testbeds for multi-technology integrated command interfaces.
Netherlands
Dutch transit operators pilot identity-verification corridors at Schengen border stations using biometric-enabled detection platforms. GDPR data protection impact assessments govern algorithmic transparency requirements for passenger screening databases. Eindhoven's precision manufacturing cluster supplies dual-energy X-ray detector modules to European equipment vendors.
Poland
EU cohesion fund investments in urban rail networks create greenfield deployment opportunities without legacy system integration burdens. Polish event security contractors source mobile screening fleets through operational expenditure models for rotating venue calendars. Warsaw and Kraków metropolitan transit authorities issue consolidated tenders for station modernization programs.
Europe Urban Security Screening Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in mobile rental services and AI Act conformity consulting. The vendor base stratifies across three tiers: integrated system providers commanding framework agreement eligibility, point-solution specialists serving spot procurement needs, and regional fabricators capturing temporary installation demand. Two strategic archetypes dominate: aviation-security incumbents extending into urban transit contracts, and national champions leveraging sovereign rail operator relationships. Competitive moves concentrate on portfolio diversification into biometric platforms and geographic expansion through EU harmonized certification pathways.
Within the integrated-system-provider tier, Smiths Detection Group Ltd. and Thales Group exemplify contrasting geographic anchoring strategies. L3Harris Technologies Inc. occupies a position representing millimeter-wave specialization adapted for crowded public venues. Smiths Detection leverages aviation security heritage toward urban transit framework agreements. Thales anchors competitive positioning through French national rail system integration depth. L3Harris exemplifies technology-portfolio diversification into passive screening arrays for stadium and concert hall deployment.
| Leading Market Players |
|---|
| Smiths Detection Group Ltd. |
| Leidos Holdings Inc. |
| OSI Systems Inc. |
| Teledyne Technologies |
| Thales Group |
| L3Harris Technologies Inc. |
| 3DX-Ray Ltd |
| Teledyne ICM SA |
| Rapiscan Systems |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EU AI Act-compliant biometric platforms and legacy metal detector systems manifests in both pricing stratification and supply chain sourcing patterns. Premium-tier vendors command extended service commitments and technology refresh guarantees under centralized framework agreements, while commodity-tier point-solution specialists compete on unbundled equipment pricing with limited after-sales support.
Pricing Analysis
Warranty and service-bundling arrangements differentiate integrated system providers from point-solution vendors, with framework agreement eligibility commanding 15-20% pricing premiums over spot procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, algorithmic transparency compliance, and data protection architecture complexity. Cost compression in standard-tier metal detector replacements is intensifying because transportation authorities consolidate procurement through national consortia. Municipal transit authorities exhibit highest price sensitivity due to constrained capital budgets, while national rail operators demonstrate lowest sensitivity given sovereign risk tolerance and counter-terrorism funding access.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Deutsche Bahn and SNCF, while distribution runs through systems integrators for mid-tier transportation authorities and venue operators. German semiconductor fabrication clusters, Dutch precision optics foundries, and French systems integration houses anchor European supply concentration. Millimeter-wave sensor arrays, dual-energy X-ray detector modules, and biometric algorithm processing units constitute critical component dependencies. Single-source vulnerability in specialized semiconductor supply from Asian foundries exposes equipment manufacturers to geopolitical disruption. Authorized distributor networks with pre-qualified installer certifications dominate downstream structure for compliance-heavy deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Urban Security Screening Market operates as a cost-of-compliance story where EU AI Act algorithmic transparency mandates erect substantial barrier-to-entry moats favoring incumbent integrated system providers with established conformity assessment pathways.
For Market Incumbents: Cement framework agreement eligibility through extended technology refresh guarantees and multi-country service coverage. Deepen backward integration into millimeter-wave sensor production to offset Asian foundry concentration risk. Counter emerging mobile screening rental specialists by embedding operational expenditure flexibility into traditional capital purchase contracts.
For New Entrants and Emerging Players: Enter via AI Act conformity consulting and certification facilitation services for mid-tier transportation authorities lacking internal compliance expertise. Poland and Eastern European urban rail greenfield deployments offer most penetrable geography absent legacy integration burdens. Pursue lease-to-own arrangements with Polish event security contractors as specific go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with biometric algorithm developers possessing EU AI Act high-risk system registration and GDPR data protection impact assessment capabilities given accelerating compliance-driven procurement. Long-term viability centers on vendors with demonstrated interoperability across proprietary legacy networks and modern integrated platforms. Watch for Deutsche Bahn and SNCF framework agreement award announcements as inflection indicator for vendor consolidation momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment Investment | High-risk system registration unlocks framework agreement eligibility with Deutsche Bahn and SNCF procurement divisions. |
| Millimeter-Wave Corridor Deployment Partnership | Walk-through screening arrays at Gare du Nord demonstrate throughput compression without detection sensitivity trade-offs. |
| Mobile Screening Fleet Rental Service Launch | Operational expenditure models capture Polish and Czech event security contractor demand outside capital budget cycles. |
| Biometric-GDPR Compliance Architecture Development | Data protection impact assessment capabilities differentiate vendors for Dutch and Belgian Schengen border station pilots. |
| Eastern European Distribution Channel Expansion | EU cohesion fund visibility through Warsaw and Kraków metropolitan transit tenders accelerates greenfield penetration. |
Research Methodology
Regulatory filings from ECHA, KBA, and ANSM, transportation authority procurement databases, and EU funding disclosure records formed the secondary backbone for market sizing and compliance pathway mapping. Primary interviews with Deutsche Bahn engineering directors, SNCF procurement leads, Dutch transit operator data protection officers, and Polish event security contractors validated technology adoption timelines and framework agreement structures. Bottom-up equipment shipment analysis and top-down transportation infrastructure investment tracking were triangulated against segmentation outputs.
Historical trendline analysis of national rail modernization program expenditures and urban transit security grant allocations established baseline growth trajectories across the projection horizon. The analytical framework modeled technology type, application context, end-user budget authority, and deployment configuration as core segmentation dimensions. CAGRs were derived from equipment procurement pipeline visibility and regulatory compliance deadline clustering. Forecast inputs incorporated EU AI Act implementation phase transitions and REACH substance restriction compliance cost pass-through assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical semiconductor supply disruption or accelerated GDPR enforcement action scenarios. Periodic stress-testing of base assumptions is recommended given regulatory implementation timeline uncertainty and transportation authority budget reallocation flexibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Middle East and Africa Cargo and Vehicle Screening Market
Security and Surveillance
Integrated Security Solutions Market
Security and Surveillance
Global Bot Security Market
Security and Surveillance
Global Physical Security Software Market
Security and Surveillance
North America Security Services Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
North America Urban Security Screening Market
Security and Surveillance
Air Cargo Security and Screening Systems Market
Security and Surveillance
Vietnam Private Security Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Global Intrusion Detection System Market
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
Explosive Vapour Detector Market