
 Public Safety Drones Market | 2026-2036
Public Safety Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Public Safety Drones Market Analysis
Chinese component manufacturing is rebalancing after export controls on advanced semiconductors. Skydio leverages domestic silicon supply chains to sustain autonomous flight software development. AeroVironment anchors military-to-public-safety technology transfer with fixed-wing endurance platforms. BRINC Drones specializes in tactical indoor systems with integrated two-way communication for hostage negotiations.
Public safety drones are uncrewed aerial vehicles engineered for first-responder missions, typically incorporating thermal imaging sensors, GPS stabilization, and flight endurance exceeding thirty minutes for search operations. Rotary-wing configurations dominate municipal procurement due to vertical takeoff flexibility in dense urban corridors, while fixed-wing systems capture disaster management applications requiring extended range. Thermal imaging technology commands premium positioning within the technology stack, as fire services and search-and-rescue units prioritize heat-signature detection through smoke and darkness.
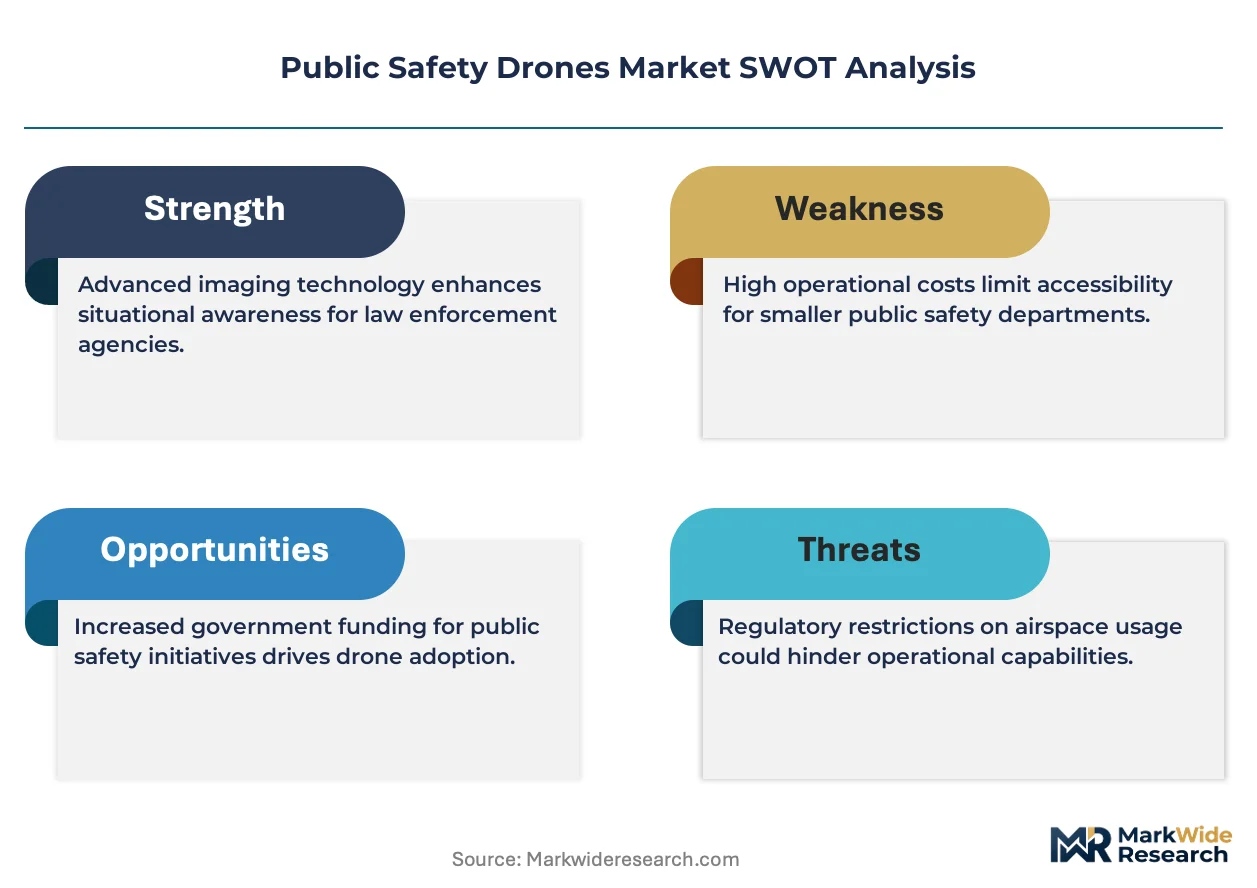
The FAA governs commercial drone operations through Part 107 certification and emerging beyond-visual-line-of-sight rulemaking, directly constraining fleet scalability for police departments. The EU AI Act imposes algorithmic transparency requirements on autonomous flight systems, compelling manufacturers to document decision-making protocols for emergency deployment scenarios. Stakeholders must monitor regulatory divergence between jurisdictions to avoid platform certification delays that strand procurement budgets.
Market Dynamics
The FAA's Part 107 expansion for beyond-visual-line-of-sight operations is compressing procurement cycles as police departments accelerate fleet modernization ahead of rule finalization.
Growth Catalysts
- FAA Beyond-Visual-Line-of-Sight Rulemaking:The FAA's pending BVLOS framework eliminates waiver bottlenecks for first-responder fleets, enabling continuous perimeter monitoring without visual observers.
- Thermal Imaging Sensor Integration:Fire services and search-and-rescue units prioritize heat-signature detection through smoke and darkness, driving premium positioning for FLIR-equipped rotary-wing platforms.
- Urban Density Patterns:Municipal procurement concentrates in metropolitan corridors where vertical takeoff flexibility outweighs fixed-wing endurance advantages for tactical response.
Market Restraints
- Advanced Semiconductor Export Controls:Chinese component manufacturing rebalancing disrupts autopilot processor supply chains, forcing manufacturers toward domestic silicon alternatives.
- EU AI Act Algorithmic Transparency:The EU AI Act imposes documentation requirements on autonomous flight decision protocols, extending certification timelines for emergency deployment scenarios.
- Lithium-Polymer Battery Chemistry:Flight endurance remains capped by energy density limitations, constraining sustained search operations beyond thirty-minute thresholds.
Strategic Opportunities
- Indoor Tactical Penetration:Hostage negotiation and barricade response applications create demand for integrated two-way communication systems in confined urban structures.
- Federal Grant Pipeline:United States municipal programs access Department of Justice and FEMA funding streams specifically earmarked for uncrewed aerial vehicle acquisition.
- AI-Computer Vision Convergence:Real-time object recognition layered with thermal overlay enables automated victim location in disaster zones without operator intervention.
Industry Challenges
- Pilot Certification Bottlenecks:Part 107 remote pilot licensing throughput limits fleet scaling velocity for agencies seeking rapid deployment capabilities.
- Legacy System Integration:Computer-aided dispatch and records management platforms require API development for seamless drone telemetry ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Safety Drones Market |
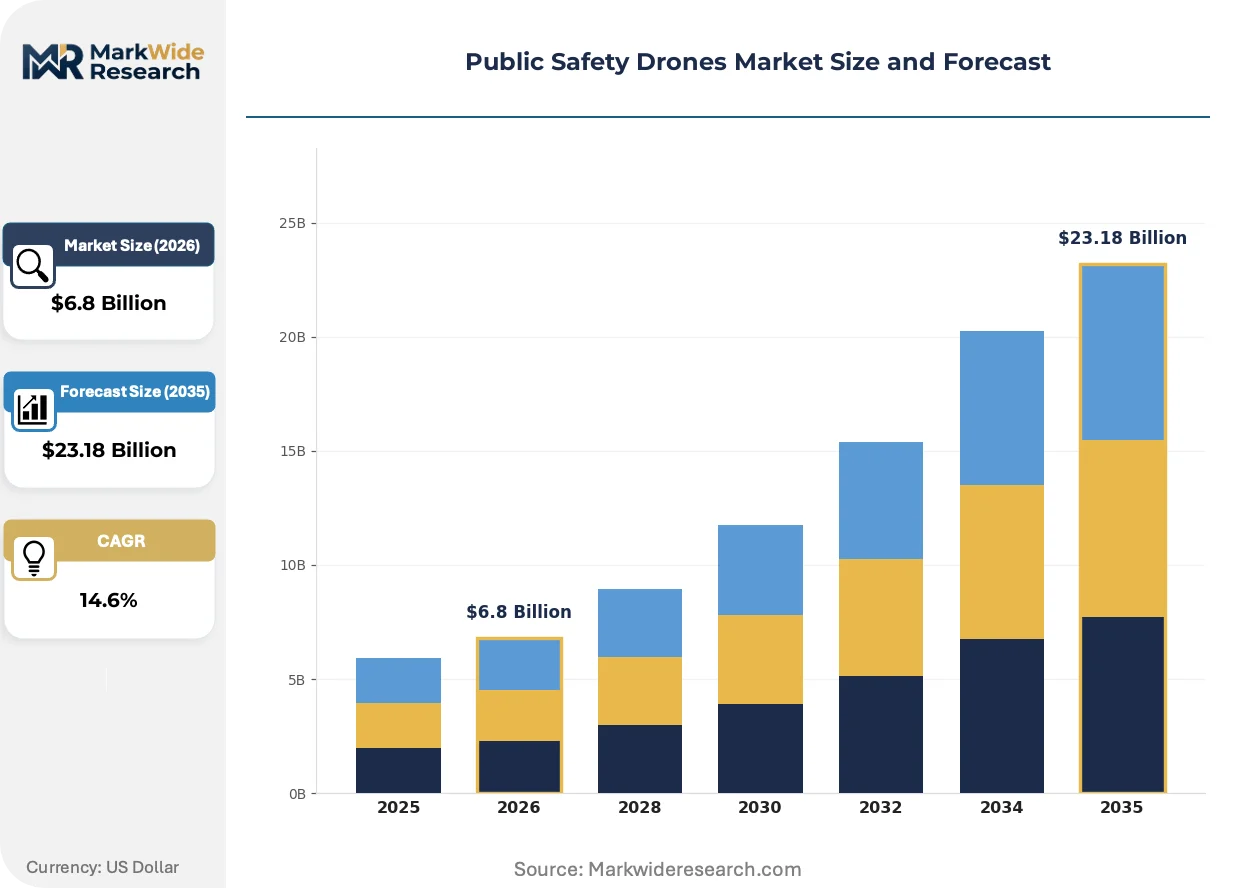
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Multirotor End User: Law Enforcement, Fire Services, Emergency Medical Services, Search and Rescue Technology: Infrared, Thermal Imaging, GPS, LiDAR Application: Surveillance, Disaster Management, Crowd Control, Traffic Monitoring |
| Companies Covered | Elistair, Teal Drones, Skydio, Draganfly, Inspired Flight, Parrot, AeroVironment, Vantage Robotics, BRINC Drones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Safety Drones Market Emerging Trajectories
Autonomous flight software is compressing operator-to-aircraft ratios while thermal payload miniaturization expands mission profiles beyond traditional surveillance.
Edge-based artificial intelligence is overtaking ground-station processing for real-time threat detection. Police departments in high-crime municipalities deploy onboard neural networks for immediate person-of-interest recognition without bandwidth-dependent cloud transmission. This shift is overtaking centralized command-center architectures, reducing latency-critical response times from seconds to milliseconds.
The EU AI Act mandates algorithmic transparency documentation for autonomous systems operating in emergency scenarios. Manufacturers must submit decision-tree protocols to national regulators before platform certification. Fire services across Germany and France face deployment delays as engineering teams retrofit existing fleets with auditable logging systems.
Agency purchasing departments now bundle training and maintenance into multi-year fleet contracts rather than acquiring hardware through separate capital appropriations. This consolidation displaces piecemeal procurement through municipal surplus channels. The pattern is most visible in mid-sized United States police departments seeking predictable operational expenditure structures.
Public Safety Drones Market Segmentation
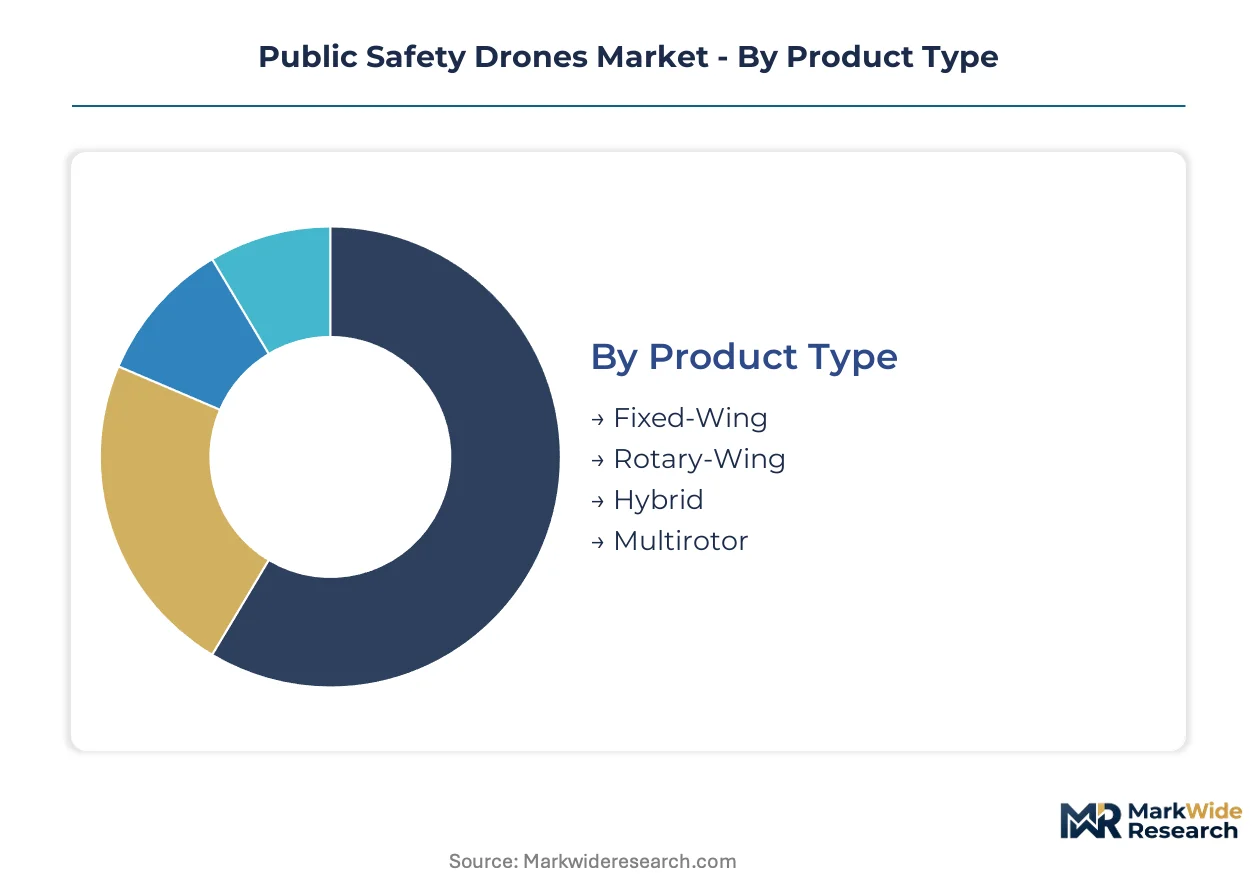
Public safety agencies select drone configurations based on mission duration, payload requirements, and operational environment constraints. Segmentation reveals how procurement priorities diverge between urban tactical response and rural search coverage.
Product Type:
Agency fleet modernization cycles favor platforms that extend mission endurance without sacrificing deployment flexibility in constrained airspace.
- Rotary-Wing:Vertical takeoff capability enables rooftop and confined-street deployment without runway infrastructure. Municipal police departments in dense United States metropolitan corridors prioritize these systems for real-time situational awareness during active shooter response.
- Fixed-Wing:Extended range and endurance suit perimeter monitoring and disaster zone mapping where loiter time exceeds rotary-wing battery limits. Fire services deploy these for wildfire front tracking across extended rural jurisdictions.
- Hybrid:Combines VTOL flexibility with fixed-wing cruise efficiency for agencies requiring multi-mission capability without fleet diversification. Emerging procurement interest centers on platforms that transition between hover and forward flight modes.
- Multirotor:Redundant rotor configurations provide stability for precision payload positioning in urban canyons with turbulent wind patterns.
Volume placements concentrate in Rotary-Wing; the faster expansion belongs to Hybrid.
End User:
First-responder budgets reflect incident frequency and federal grant eligibility rather than population density alone.
- Law Enforcement:Patrol support, evidence documentation, and suspect pursuit drive the largest procurement volumes. United States municipal departments access Department of Justice funding streams specifically earmarked for uncrewed aerial vehicle acquisition.
- Fire Services:Thermal-equipped platforms penetrate smoke-filled structures and identify hotspot persistence after suppression. Search coverage in collapsed buildings demands maneuverable systems with heat-signature detection.
- Emergency Medical Services:Defibrillator and blood product delivery trials are expanding mission profiles beyond observation into intervention logistics.
- Search and Rescue:Extended-range fixed-wing systems with automated grid patterns accelerate victim location in wilderness and maritime environments.
Law Enforcement dominates current placements; Emergency Medical Services is climbing the fastest as medical payload integration matures.
Technology:
Sensor payload selection determines per-unit pricing tiers and operational utility across lighting and atmospheric conditions.
- Thermal Imaging:Detects heat signatures through smoke, darkness, and vegetation canopy. Fire services and search-and-rescue units prioritize FLIR-equipped platforms for victim location in low-visibility environments.
- Infrared:Night-vision capability supports covert surveillance operations without active illumination that compromises officer safety.
- GPS:Stabilization and waypoint navigation form the baseline positioning layer for all certified public safety platforms.
- LiDAR:Three-dimensional mapping generates post-incident reconstruction models for forensic analysis and training simulation.
Thermal Imaging commands premium positioning; LiDAR is gaining share fastest as post-incident documentation requirements expand.
Application:
Mission type dictates flight pattern complexity, sensor integration depth, and regulatory coordination requirements.
- Surveillance:Continuous perimeter monitoring and suspect tracking demand BVLOS-capable platforms with encrypted video downlink. FAA rulemaking expansion is accelerating procurement for persistent overwatch without visual observer requirements.
- Disaster Management:Rapid damage assessment and supply route identification require extended-range systems with automated mapping pipelines. FEMA grant programs fund these acquisitions for state-level emergency management agencies.
- Crowd Control:Overhead situational awareness reduces ground officer exposure during civil unrest and mass gathering monitoring.
- Traffic Monitoring:Accident reconstruction and congestion pattern analysis leverage automated flight paths along highway corridors.
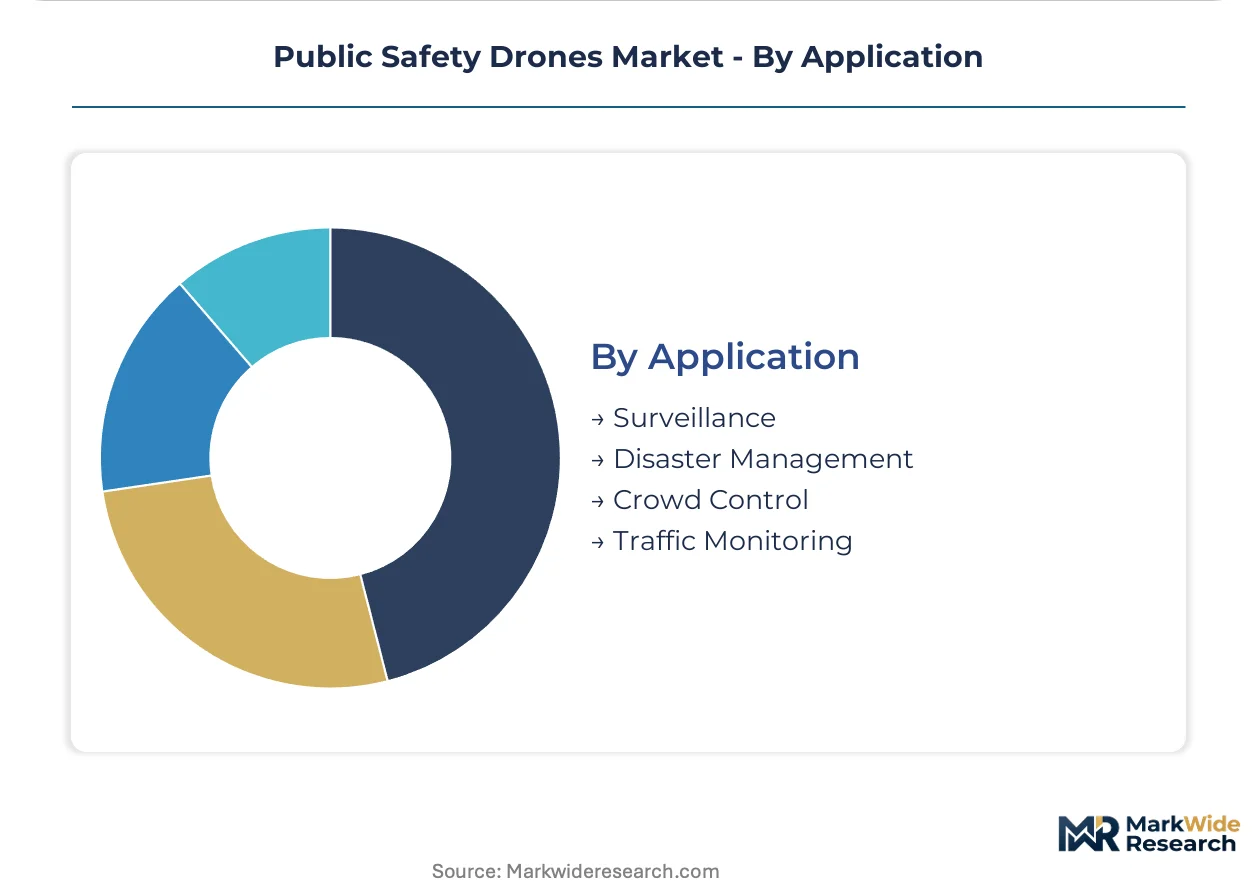
Surveillance accounts for dominant placement volume; Disaster Management shows the steepest expansion trajectory as climate-related incident frequency rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-polymer cell manufacturing clusters in Shenzhen and Dongguan supply power systems for rotary-wing platforms deployed across municipal first-responder fleets worldwide.
United States
Federal grant programs through the Department of Justice and FEMA accelerate municipal procurement cycles for law enforcement and fire services. The FAA's pending beyond-visual-line-of-sight rulemaking eliminates waiver bottlenecks for continuous perimeter monitoring. Los Angeles County and Dallas-Fort Worth metropolitan agencies lead fleet modernization with thermal-equipped rotary-wing deployments.
China
Domestic silicon supply chains sustain autonomous flight software development despite advanced semiconductor export controls. The Ministry of Industry and Information Technology governs unmanned aerial vehicle certification for public security applications. Shenzhen's component manufacturing ecosystem rebalances toward domestic autopilot processor alternatives.
Germany
Fire services prioritize thermal-equipped platforms for smoke-filled structure penetration and hotspot persistence detection. The EU AI Act mandates algorithmic transparency documentation for autonomous systems in emergency scenarios. Bavarian engineering teams retrofit existing fleets with auditable logging systems to satisfy certification requirements.
France
Search-and-rescue units demand heat-signature detection through vegetation canopy for wilderness victim location. ANSM and CNIL oversight extends to autonomous decision protocols for emergency deployment. The Provence-Alpes-Côte d'Azur region concentrates maritime rescue drone trials with automated grid pattern systems.
United Kingdom
Police departments in high-crime municipalities deploy onboard neural networks for immediate person-of-interest recognition. The Civil Aviation Authority coordinates with Home Office procurement for encrypted video downlink standards. Greater London agencies compress operator-to-aircraft ratios through edge-based artificial intelligence adoption.
Public Safety Drones Market Vendor Landscape
Global majors compete with regional champions across technology transfer pathways and domestic supply chain anchoring. The vendor base stratifies between military-heritage platforms, autonomous software specialists, and tactical indoor system fabricators. Three archetypes dominate: fixed-wing endurance providers, rotary-wing autonomy developers, and confined-space penetration specialists. Consolidation pressures favor multi-year fleet contracts bundling training and maintenance over piecemeal hardware acquisition.
Among autonomy-focused developers, Skydio exemplifies domestic silicon supply chain leverage for real-time obstacle avoidance. AeroVironment occupies a position representing military-to-public-safety technology transfer with extended-range platforms. BRINC Drones sits within the tactical indoor tier, anchoring hostage negotiation applications with integrated two-way communication systems.
| Leading Market Players |
|---|
| Elistair |
| Teal Drones |
| Skydio |
| Draganfly |
| Inspired Flight |
| Parrot |
| AeroVironment |
| Vantage Robotics |
| BRINC Drones |
| Others |
Supply Flow & Price Mechanics
Backward integration into domestic silicon fabrication anchors supply security for autonomous flight processors while compressing margin structures for manufacturers seeking to offset semiconductor export control premiums. This integration pattern concentrates pricing power among vendors with captive chip supply, forcing competitors toward bundled service contracts to defend unit economics.
Pricing Analysis
Extended warranty and pilot training bundling now dominates municipal procurement, displacing bare-hardware transactions. Three-tier pricing structure across premium FLIR-equipped platforms, standard visible-spectrum systems, and economy trainer units separates fire service budgets from patrol department appropriations. Cost compression in the economy tier intensifies as Shenzhen-sourced components flood surplus channels. Law enforcement agencies exhibit highest price sensitivity due to grant-dependent capital cycles, while federal emergency management units absorb premium positioning for disaster response specifications.
Supply Chain Analysis
Refurbishment flows for lithium-polymer battery packs and gimbal assemblies now feed secondary municipal markets, extending platform lifecycles beyond original manufacturer support. Component manufacturing concentrates in China, South Korea, and Taiwan, with Shenzhen anchoring power system fabrication and Taichung housing precision servo motor production. Domestic autopilot processor alternatives in the United States draw from Qualcomm and NVIDIA supply chains to circumvent export restrictions. Single-source vulnerability in thermal sensor modules threatens fleet readiness. Distribution runs through federal grant administrators and regional emergency equipment cooperatives rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-based artificial intelligence is displacing ground-station processing architectures, compressing response latency from seconds to milliseconds while rewriting procurement specifications for onboard compute capacity.
For Market Incumbents: Acquire specialized autonomy software stacks to counter emerging pure-play AI developers. Secure FAA certification pre-approvals for beyond-visual-line-of-sight platforms ahead of rule finalization. Establish in-house thermal payload manufacturing to reduce FLIR dependency and capture margin from integrated sensor-drone bundles.
For New Entrants and Emerging Players: Enter via indoor tactical penetration systems for hostage negotiation units, where BRINC Drones has demonstrated viable product-market fit but concentration risk persists. Target emergency medical services payload integration, the fastest-climbing end-user segment with minimal incumbent saturation. Pursue direct relationships with state-level emergency management agencies bypassing municipal procurement fragmentation.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by military-heritage platforms seeking public safety diversification. Long-term viability hinges on algorithmic transparency compliance for EU market access and domestic silicon supply chain anchoring for US federal contracts. Monitor FAA beyond-visual-line-of-sight rulemaking publication as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Silicon Supply Anchoring | Mitigates export control exposure for autopilot processor procurement. |
| BVLOS Certification Pre-Approval | Positions vendors for FAA rule finalization without waiver bottlenecks. |
| Thermal Payload Vertical Integration | Captures FLIR-equivalent margin through in-house sensor fabrication. |
| Federal Grant Pipeline Access | Locks multi-year revenue visibility through Department of Justice funding streams. |
| Edge AI Compute Architecture | Enables millisecond-latency threat detection without bandwidth-dependent cloud transmission. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with police aviation unit commanders, fire service technology officers, FAA certification specialists, and municipal procurement directors combined with secondary validation from FCC equipment authorization databases, FAA Part 107 waiver filings, and Department of Justice grant disbursement records. Bottom-up fleet deployment tallies triangulated against top-down federal funding appropriations.
Shipment volume reconciliation against grant obligation data and manufacturer delivery disclosures calibrated the analytical framework across the projection horizon. Segmentation dimensions modeled include platform configuration, end-user agency type, sensor payload technology, and application mission profile. CAGRs derived from fleet replacement cycle analysis and federal budget trajectory assumptions. Industry-specific inputs incorporated lithium-polymer energy density improvement curves and thermal sensor cost decline trajectories.
Revisions become necessary when FAA rulemaking delays, semiconductor export control expansion, or EU AI Act enforcement intensity materialize beyond baseline assumptions. Practitioners should monitor BVLOS waiver approval velocity and domestic silicon foundry capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Crowd Management System Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
Global Public Safety and Security Market
Public Safety
Europe Road Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
Safe City Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Public Safety LTE Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Solution Market
Public Safety
Global Wireless Broadband in Public Safety Market