
 Rigid Transparent Plastic Market | 2026-2036
Rigid Transparent Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Transparent Plastic Market Analysis
China's petrochemical corridor is fragmenting as new polycarbonate and acrylic capacity comes online from domestic producers and joint ventures. SABIC leverages its integrated feedstock position in Saudi Arabia to supply Asian converters with cost-competitive resin. Covestro AG anchors European demand through specialized optical-grade polycarbonate production for automotive glazing and medical optics. Chi Mei Corporation dominates Taiwan's acrylic sheet exports, sustaining margin through vertical control over PMMA monomer supply.
Rigid transparent plastic denotes thermoplastic materials processed into dimensionally stable forms with light transmission typically exceeding 85%, manufactured via injection molding, extrusion, or thermoforming to achieve precise optical clarity and surface hardness. These polymers serve critical functions in applications requiring visibility, sterilizability, or impact resistance alongside structural integrity. Polycarbonate leads automotive component demand where impact strength and thermal stability outweigh scratch susceptibility, while acrylic commands premium pricing in optical and display applications for its superior clarity and UV resistance. PET packaging remains the highest-volume category but faces margin compression from recycled-content mandates, whereas electronic housings represent the fastest-growing application segment driven by transparent device aesthetics and 5G signal transparency requirements.
FDA biocompatibility standards and EPA emissions frameworks govern medical and packaging applications in the United States, while REACH and RoHS compliance in Europe restrict certain additives and monomer residuals in consumer-facing products. China's GB standards and evolving MEE environmental enforcement are raising barriers for imported resin while accelerating domestic substitution programs. Stakeholders must monitor regulatory divergence between jurisdictions as divergent recycling infrastructure investments and extended producer responsibility schemes reshape competitive access across major demand centers.
Market Dynamics
Medical device sterilization requirements are compressing certification timelines for polycarbonate and acrylic suppliers, while automotive glazing specifications pull optical-grade resin toward higher thermal stability thresholds.
Growth Catalysts
- Medical Sterilization Mandates:FDA biocompatibility standards for sterilizable transparent housings are accelerating resin qualification programs among device manufacturers seeking durable, autoclavable enclosures.
- REACH Compliance Deadlines:ECHA restrictions on residual monomers in consumer-facing products are forcing formulation upgrades that favor premium optical-grade polycarbonate over commodity alternatives.
- 5G Signal Transparency:Telecommunications infrastructure deployment requires thermoplastics with minimal dielectric interference, driving specification wins in base station and small cell enclosures.
Market Restraints
- Bisphenol A Feedstock Volatility:Polycarbonate producers face margin pressure from benzene and phenol price swings tied to refinery output decisions in the US Gulf Coast.
- Acrylic Scratch Susceptibility:Surface hardness limitations prevent PMMA penetration in automotive interior touchpoints where polycarbonate dominates despite inferior optical clarity.
- Recycled Content Mandate Friction:EU Green Deal packaging targets create technical barriers for PET sheet processors struggling to maintain optical clarity above 85% with post-consumer flake.
Strategic Opportunities
- India Medical Device Localization:CDSCO production-linked incentive schemes invite transparent housing manufacturers to establish sterilizable component supply within domestic medtech corridors.
- Optical Coating Convergence:Anti-fog and anti-reflective surface treatments applied during injection molding are opening premium pricing tiers in surgical visualization equipment.
- Direct Converter Platforms:Resin suppliers bypassing traditional distribution layers to serve automotive Tier 1 molders through vendor-managed inventory programs capture specification influence.
Industry Challenges
- Optical Metrology Talent Scarcity:Injection molders struggle to recruit technicians proficient in haze and light transmission testing protocols required for automotive glazing qualification.
- Multi-Jurisdiction Certification Burden:Simultaneous FDA, REACH, and GB standard compliance stretches quality assurance resources for medical packaging converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Transparent Plastic Market |
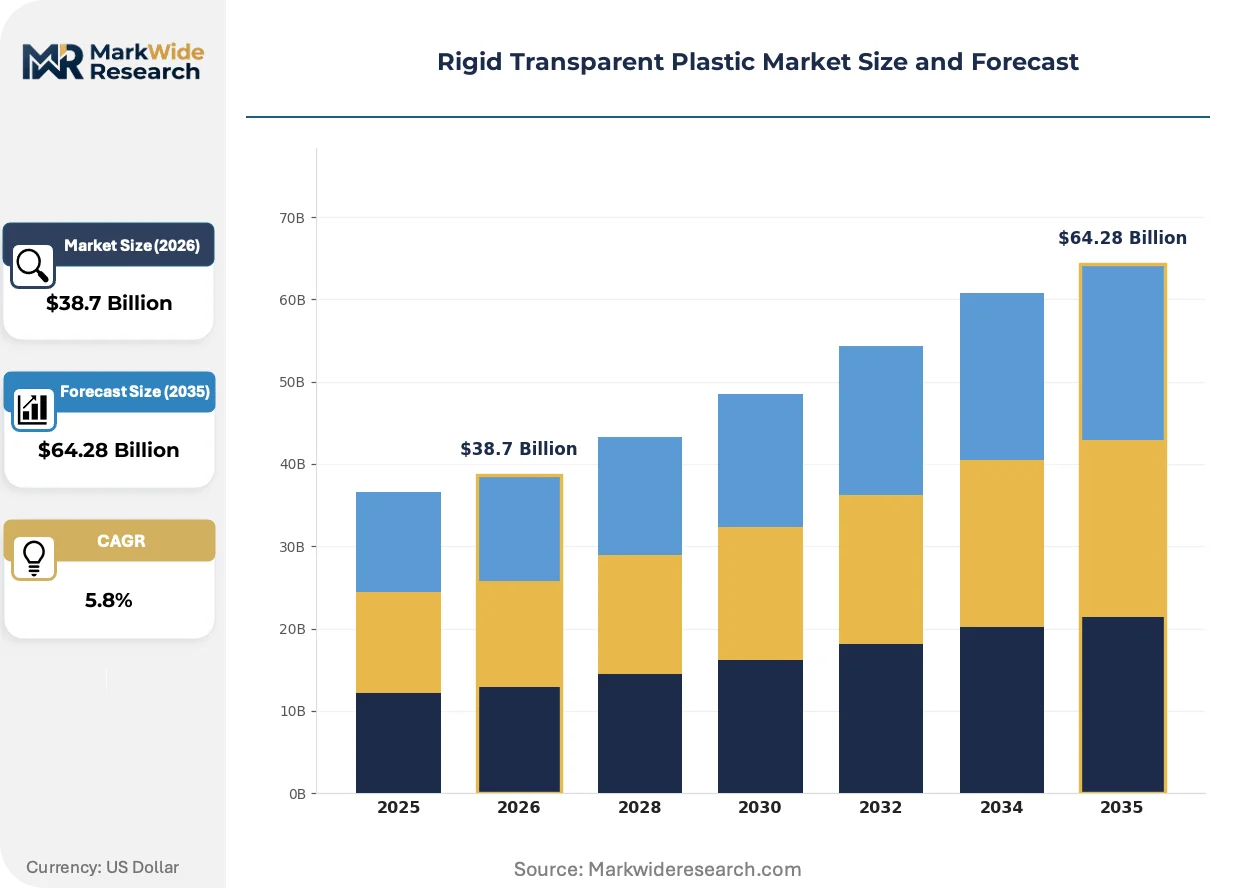
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polycarbonate, Polystyrene, PET Application: Packaging, Automotive Components, Electronic Housings, Medical Devices End User: Consumer Goods, Healthcare, Automotive, Electronics Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | LOTTE Chemical Corporation, INEOS, SABIC, DuPont, DOW, BASF SE, Covestro AG, Chi Mei Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Transparent Plastic Market Emerging Trajectories
Process control technologies and regulatory disclosure requirements are rewriting competitive differentiation in transparent polymer supply chains.
Digital twin simulation of injection molding parameters is digitizing quality assurance workflows for optical-grade polycarbonate production. Automotive Tier 1 suppliers in Germany's precision manufacturing corridor are deploying these systems to reduce haze variability below 1%. Real-time cavity pressure monitoring is compressing scrap rates and accelerating lot release timelines.
EU CSRD sustainability reporting mandates now require granular disclosure of Scope 3 emissions from petrochemical feedstock. Medical device OEMs sourcing transparent housings are demanding certified carbon footprint data from resin suppliers. REACH-registered substances face heightened scrutiny in extended producer responsibility schemes.
Specification-driven procurement now dominates medical optics purchasing, with buyers prioritizing ISO 10993 biocompatibility documentation over unit cost. Traditional spot-market resin purchasing is contracting in favor of multi-year supply agreements with embedded certification guarantees. German automotive OEMs pioneered this shift, extending it to Asian manufacturing affiliates.
Rigid Transparent Plastic Market Segmentation
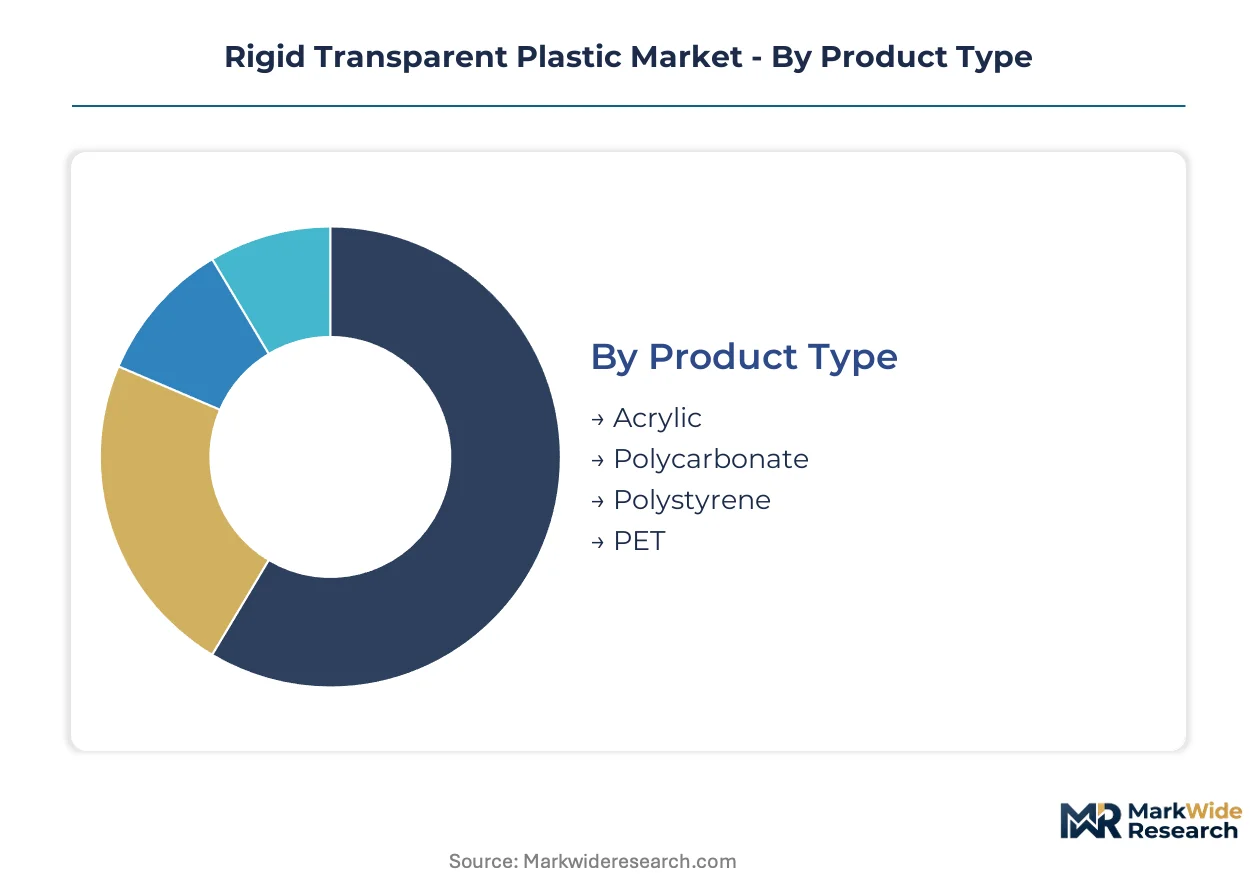
Segmentation in rigid transparent plastics reveals how material properties, regulatory requirements, and supply chain configurations create distinct commercial battlegrounds. Each dimension exposes different margin structures and certification barriers that reshape competitive positioning across medical, automotive, and electronics verticals.
Product Type:
After-sales service intensity varies sharply across polymer chemistries, with optical-grade polycarbonate requiring technical support for haze troubleshooting and acrylic demanding coating compatibility guidance.
- Acrylic:PMMA delivers superior light transmission above 92% and exceptional UV stability for outdoor signage and display applications. Chi Mei Corporation's vertical control over monomer supply in Taiwan sustains margin in optical sheet exports to precision manufacturers in Germany. Scratch susceptibility limits penetration in automotive interior touchpoints where hardness requirements exceed 2H pencil rating.
- Polycarbonate:Bisphenol A-based resin achieves impact strength 250x greater than glass while maintaining thermal stability to 135°C. SABIC leverages integrated Saudi feedstock to supply Asian automotive glazing converters facing REACH compliance deadlines for residual monomer restrictions. Bayer's optical-grade production in Germany anchors medical device sterilizable housing specifications.
- Polystyrene:General-purpose crystal grades offer lowest-cost transparency for disposable packaging and display applications. BIS certification requirements in India create friction for imported resin in food-contact applications.
- PET:Crystallizable copolyesters dominate rigid packaging volume with clarity exceeding 85% in thin-wall injection stretch blow molding. EU Green Deal recycled-content mandates compress margins for sheet processors struggling to maintain optical performance with post-consumer flake.
Polycarbonate holds the largest share; momentum sits with acrylic in premium optical coating convergence.
Application:
Application segmentation exposes diverging cost-to-serve economics, with medical devices demanding lot-level biocompatibility documentation and automotive components requiring geometric dimensioning tolerance support.
- Packaging:PET rigid containers and thermoformed trays constitute highest-volume consumption for food, beverage, and pharmaceutical blister packs. FDA 21 CFR compliance for indirect food additives and evolving EPA emissions frameworks govern US converter operations. Optical clarity degradation with recycled-content incorporation creates technical barriers under extended producer responsibility schemes.
- Automotive Components:Polycarbonate glazing, interior trim, and lighting lenses require thermal stability to 120°C continuous service temperature. Germany's precision manufacturing corridor concentrates specification influence through OEM direct material approval programs. KBA type approval requirements govern windshield replacement part certification.
- Electronic Housings:Transparent enclosures for 5G small cells, routers, and consumer devices demand dielectric constants below 3.0 at 2.4 GHz. MIIT equipment certification in China accelerates domestic resin substitution for imported optical-grade polycarbonate.
- Medical Devices:Sterilizable transparent housings for surgical equipment and diagnostic instruments require ISO 10993 biocompatibility documentation. CDSCO production-linked incentive schemes in India invite component localization for domestic medtech corridors. Autoclave resistance to 134°C steam sterilization cycles eliminates acrylic from most surgical applications.
Packaging holds the largest share; electronic housings are expanding most quickly on 5G infrastructure deployment.
End User:
End-user concentration determines pricing power, with healthcare procurement consolidating through group purchasing organizations and automotive maintaining specification lock-in through multi-year platform agreements.
- Healthcare:Medical device OEMs and hospital systems prioritize sterilizability documentation over unit cost in transparent housing procurement. FDA biocompatibility standards and MDR technical documentation requirements in Europe stretch quality assurance resources. German manufacturers pioneered specification-driven purchasing with embedded certification guarantees.
- Automotive:Tier 1 molders and OEM glazing divisions drive resin selection through direct material approval programs. REACH-registered substances face heightened scrutiny in sustainability reporting under CSRD mandates. Vendor-managed inventory programs from Saudi-supplied resin producers capture specification influence.
- Electronics:Telecommunications equipment manufacturers and consumer device brands demand signal transparency with minimal dielectric interference. GB standards compliance in China raises barriers for imported resin while accelerating domestic substitution.
- Consumer Goods:Retail packaging buyers and household product manufacturers prioritize unit economics and optical shelf appeal. FSSAI food-contact regulations in India and evolving MEE environmental enforcement in China reshape competitive access.
Automotive holds the largest share; healthcare is gaining share fastest on sterilization mandate expansion.
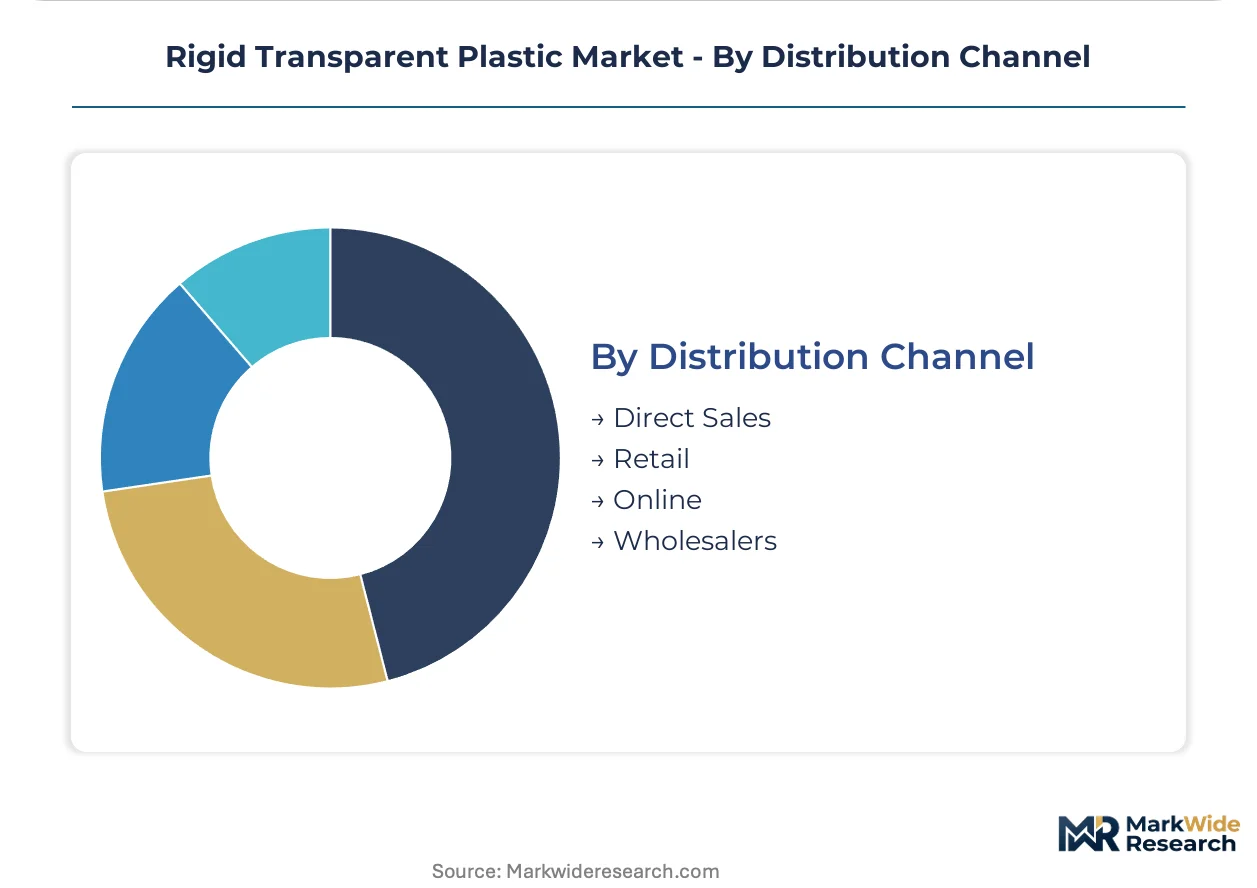
Distribution Channel:
Channel structure reflects technical complexity gradients, with direct sales dominating specification-influential accounts and wholesalers serving commoditized packaging converters.
- Direct Sales:Resin producers bypass distribution layers to serve automotive Tier 1 molders and medical device OEMs through technical service agreements. Vendor-managed inventory programs in Germany's precision manufacturing corridor embed specification influence.
- Wholesalers:Regional distributors stock commodity grades for packaging converters and general-purpose fabricators. Inventory carrying costs and credit terms determine competitive positioning in price-sensitive segments.
- Retail:Specialty plastics retailers serve hobbyist, prototyping, and small-batch fabrication demand. Acrylic sheet dominates this channel for display and signage applications.
- Online:E-commerce platforms aggregate small-lot procurement for research institutions and startup manufacturers. Digital product data sheets and certification document access influence purchase decisions.
Direct sales holds the largest share; online channels are climbing the fastest on small-lot prototyping demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical complexes in Saudi Arabia, South Korea, and Germany concentrate resin supply, while demand clusters in precision manufacturing corridors where automotive and medical OEMs co-locate. Regulatory divergence between FDA, REACH, and GB standards fragments certification requirements across major consumption centers.
United States
Medical device sterilization mandates from FDA biocompatibility standards accelerate polycarbonate qualification programs for autoclavable surgical housings. EPA emissions frameworks govern packaging converter operations in the US Gulf Coast petrochemical corridor. Automotive glazing specifications in Detroit's manufacturing cluster pull optical-grade resin toward higher thermal stability thresholds.
Germany
REACH compliance deadlines from ECHA restrictions on residual monomers force formulation upgrades favoring premium optical-grade polycarbonate. KBA type approval requirements govern windshield replacement part certification for automotive suppliers. The precision manufacturing corridor concentrates specification influence through OEM direct material approval programs in Bavaria and Baden-Württemberg.
China
MIIT equipment certification for 5G telecommunications infrastructure accelerates domestic resin substitution for imported optical-grade polycarbonate. GB standards and evolving MEE environmental enforcement raise barriers for imported resin while accelerating domestic substitution programs. The Yangtze River Delta petrochemical corridor fragments as new polycarbonate and acrylic capacity comes online from domestic producers.
India
CDSCO production-linked incentive schemes invite transparent housing manufacturers to establish sterilizable component supply within domestic medtech corridors. BIS certification requirements create friction for imported resin in food-contact packaging applications. Maharashtra and Gujarat's industrial corridors concentrate medical device OEM procurement consolidating through group purchasing organizations.
Saudi Arabia
SABIC leverages integrated feedstock position to supply Asian converters with cost-competitive resin amid benzene and phenol price volatility. SFDA medical device regulations align with international standards to facilitate export-oriented production. The Eastern Province petrochemical complex anchors supply-side concentration for polycarbonate resin serving European REACH compliance markets.
Rigid Transparent Plastic Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream capturing margin through specification lock-in with automotive Tier 1 molders and medical device OEMs. The vendor base stratifies across petrochemical conglomerates with captive feedstock, specialized optical-grade producers, and regional sheet extruders serving commoditized packaging segments. Three archetypes dominate: integrated resin-to-sheet producers, precision optical compounders, and distribution-anchored converters. Competitive moves concentrate on backward integration into monomer supply and vendor-managed inventory programs embedding specification influence.
Among integrated petrochemical conglomerates, SABIC and BASF SE exemplify the feedstock-anchored archetype leveraging captive benzene and phenol supply. Covestro AG occupies a position within the European precision optical tier, while Chi Mei Corporation represents the vertically controlled acrylic specialist segment. These three names anchor the competitive structure without exhausting the field.
| Leading Market Players |
|---|
| LOTTE Chemical Corporation |
| INEOS |
| SABIC |
| DuPont |
| DOW |
| BASF SE |
| Covestro AG |
| Chi Mei Corporation |
| Arkema |
| Others |
Supply Flow & Price Mechanics
Saudi Arabia's Eastern Province petrochemical complex anchors polycarbonate resin supply, with SABIC's captive benzene and phenol feedstock creating pricing power that cascades through Asian converter markets amid volatile bisphenol A input costs.
Pricing Analysis
REACH compliance deadlines dictate the pricing tier structure across European medical and automotive segments. Three-tier pricing structure across optical-grade certified, industrial-grade, and commodity-grade polycarbonate separates sterilizable medical housings from standard packaging sheet. Price differentiation rests on ISO 10993 biocompatibility certification tier and volume scale commitments in multi-year offtake agreements. Cost compression in commodity PET sheet is intensifying because EU Green Deal recycled-content mandates degrade optical clarity performance. Packaging converters show highest price sensitivity, while medical device OEMs prioritize certification guarantees over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced optical metrology equipment limit flows of haze-testing instrumentation to precision molders in Germany and Japan. Supply concentrates in Saudi Arabia, South Korea, and Germany, with polycarbonate resin production drawing from captive benzene and phenol derivatives. Raw material dependencies center on refinery-linked aromatics, methyl methacrylate monomer, and high-purity optical additives. Single-source vulnerability runs through Taiwan's PMMA monomer supply controlled by Chi Mei Corporation. Distribution runs through direct technical service agreements for automotive Tier 1 molders and medical device OEMs, with regional wholesalers serving commoditized packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as automotive glazing specification wins and 5G infrastructure deployment restart capital expenditure programs paused during feedstock volatility.
For Market Incumbents: Entrench specification lock-in through vendor-managed inventory programs in Germany's precision manufacturing corridor. Deepen backward integration into optical-grade compounding capacity to defend margin against Saudi-fed cost-competitive resin. Prioritize ISO 10993 certification investment as FDA biocompatibility standards tighten sterilizable housing requirements. Channel control through direct converter platforms captures influence over automotive Tier 1 molders facing REACH compliance deadlines. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO production-linked incentive corridors for sterilizable medical device components. White-space targets include optical coating convergence for surgical visualization equipment and 5G small cell enclosures requiring dielectric constants below 3.0. The most penetrable segment sits in electronic housings where MIIT certification accelerates domestic substitution. A go-to-market angle through research institution partnerships leverages small-lot prototyping demand migrating to online channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core optical-grade polycarbonate assets stranded by portfolio rationalization. Long-term viability favors precision compounders with captive certification capabilities and direct OEM relationships. Watch for inflection signals in benzene-phenol spread compression that would force feedstock-integrated players to restructure downstream asset deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Chi Mei's captive PMMA production in Taiwan sustains margin through vertical control over optical sheet exports. |
| Optical-Grade Capacity Expansion | Covestro's specialized polycarbonate production in Germany anchors automotive glazing specifications requiring sub-1% haze variability. |
| Vendor-Managed Inventory Programs | SABIC's direct converter platforms embed specification influence with Asian automotive Tier 1 molders facing REACH deadlines. |
| Medical Device Certification Investment | ISO 10993 documentation capabilities separate sterilizable housing suppliers from commodity resin converters in FDA-regulated markets. |
| Joint Venture for 5G Infrastructure Resin | MIIT equipment certification in China accelerates domestic substitution partnerships for optical-grade polycarbonate in base station enclosures. |
Methodological Framework
The analysis maps polycarbonate, acrylic, polystyrene, and PET sub-sectors, each validated through procurement managers at medical device OEMs, automotive Tier 1 molders, resin technical directors, and distribution channel partners. Primary interviews with these stakeholders combined with secondary validation from customs trade data, SEC filings of petrochemical conglomerates, REACH registration databases, and FDA 510(k) submissions. Bottom-up resin consumption estimates triangulated against top-down end-use industry demand models.
Assumptions held fixed include regulatory compliance timelines and feedstock cost pass-through mechanisms, while variables included recycled-content incorporation rates and 5G infrastructure deployment pace. The projection horizon spans material-grade segmentation by certification tier, end-use industry vertical, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand curves incorporating automotive content-per-vehicle trends and medical device sterilization mandate expansion. Forecast inputs included benzene-phenol spread volatility and optical clarity degradation curves for post-consumer PET flake.
Sensitivities concentrate around REACH monomer restriction enforcement intensity and MIIT domestic substitution acceleration in China. Forecasts reflect these documented assumptions and modeled elasticity parameters. Material shifts in FDA biocompatibility standard timelines or EU Green Deal recycled-content mandate technical thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Rigid Food Containers Market