
 Spain Rigid Plastic Packaging Market | 2026-2036
Spain Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Rigid Plastic Packaging Market Insights
Small-batch artisanal food producers is collapsing as a demand anchor as large-scale beverage bottlers and pan-European retail private-label programs capture procurement volume. ALPLA Group leverages its blow-molding technology leadership to supply high-volume PET bottle lines for Spanish mineral water and soft drink brands. COEXPAN S.A.U. anchors regional thermoforming capacity through its integrated sheet extrusion and tray manufacturing operations in Madrid and Barcelona. Berry Global, Inc. competes across multi-material jar and container platforms, sustaining investment in barrier-enhanced polypropylene solutions for shelf-stable food applications.
Rigid plastic packaging denotes formed polymer structures—typically injection-molded, blow-molded, or thermoformed—with fixed shapes that resist deformation under normal handling stress, commonly specified with wall thicknesses between 0.25 mm and 2.5 mm depending on application load requirements. These structures protect contents from mechanical damage, moisture ingress, and gas permeation throughout distribution chains. Bottles dominate value generation in the Spanish market due to their ubiquity in beverage and personal care distribution, while trays represent the fastest-expanding format as fresh produce retailers adopt modified-atmosphere packaging for extended shelf-life presentation. Polyethylene maintains volume leadership across industrial and household chemical containers, though PET continues displacing glass in premium beverage segments where clarity and lightweighting deliver logistics savings.
Spain's national packaging regulator enforces EU Packaging and Packaging Waste Directive targets, while the Spanish Ministry for Ecological Transition administers extended producer responsibility schemes that obligate rigid plastic producers to incorporate recycled content thresholds. BIS-equivalent standardization bodies in Spain align with EN norms for food-contact materials, restricting certain additive chemistries and mandating migration testing protocols. Stakeholders must monitor how forthcoming EU-wide recycled content mandates for PET beverage bottles reshape raw material sourcing economics and converter investment timelines.
Market Dynamics
Extended producer responsibility mandates under EU circular economy frameworks are forcing Spanish converters to reconfigure material sourcing and recycling infrastructure ahead of 2025 compliance deadlines.
Growth Catalysts
- EU Packaging and Packaging Waste Directive targets:Spain's Ministry for Ecological Transition enforces recycled content thresholds that oblige rigid plastic producers to expand post-consumer feedstock procurement.
- Modified-atmosphere packaging adoption:Fresh produce retailers across Catalonia and Madrid are specifying thermoformed trays with oxygen barrier layers to extend shelf-life presentation.
- Lightweighting imperatives:Beverage logistics operators are specifying thinner-wall PET bottle designs to reduce transport costs and meet corporate carbon reduction commitments.
Market Restraints
- Post-consumer rPET supply scarcity:Spain's collection infrastructure generates insufficient food-grade recycled flake to meet converter demand, forcing reliance on imported bales.
- Natural gas price volatility:Polymer extrusion and blow-molding operations face margin compression from feedstock energy costs tied to European benchmark pricing.
- Glass displacement limits in premium spirits:Brand owners in Andalusia and Rioja wine regions maintain glass bottle specifications for heritage positioning, capping PET penetration.
Strategic Opportunities
- Underpenetrated pharmaceutical blister packs:Thermoformers can target Andalusia's expanding generic drug manufacturing cluster with barrier-enhanced PVC alternatives.
- Reuse system integration:The EU Green Deal's emphasis on packaging reuse creates openings for durable polypropylene container pooling services in Catalonia's foodservice distribution.
- Digital watermarking convergence:Combining AI-powered sorting with embedded tracer technologies enables converters to certify recycled content claims for ESG reporting.
Industry Challenges
- Migration testing backlog:EN-compliant food-contact certification timelines stretch 14-18 weeks, delaying new barrier additive formulations from reaching Spanish bottlers.
- Multi-material separation complexity:Barrier-enhanced containers combining PET, EVOH, and polyolefin layers complicate mechanical recycling streams and contaminate rPET output quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Rigid Plastic Packaging Market |
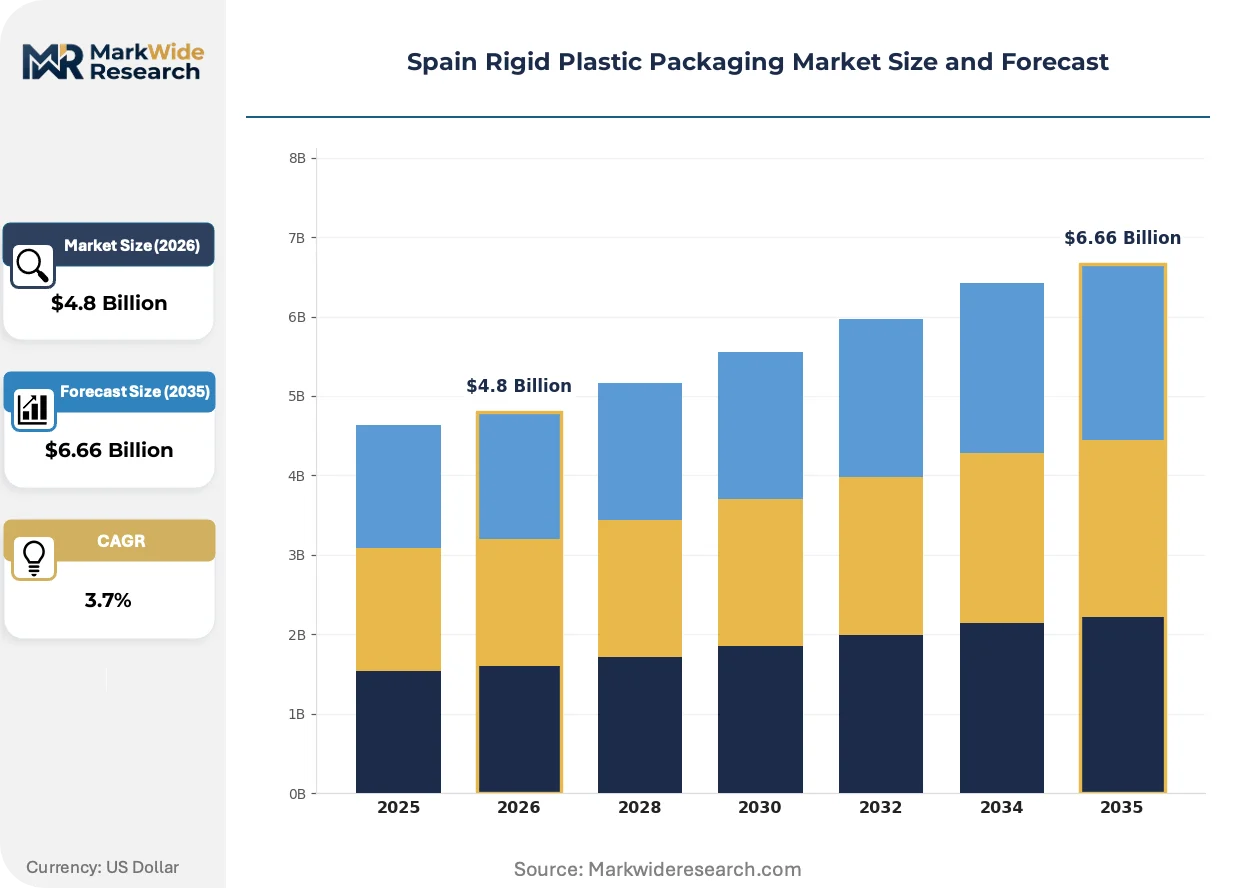
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Trays End User: Food, Beverages, Personal Care, Household Material: Polyethylene, Polypropylene, PET, PVC Application: Aerospace, Automotive, Electronics, Medical |
| Companies Covered | ALPLA Group, Berry Global, Inc., Berlin Packaging, Sonoco Products Company, Plastipak Holdings, Inc., COEXPAN S.A.U., ITC Packaging, Graham Packaging, Amcor PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Rigid Plastic Packaging Market Trends and Innovations
Active barrier technologies and digital traceability systems are redefining competitive differentiation in Spanish rigid plastic packaging, shifting value capture from commodity volume to certified circularity performance.
Mono-material barrier structures are replacing multi-layer laminates in shelf-stable food trays. Converters in Barcelona's industrial corridor are adopting plasma-enhanced chemical vapor deposition to apply silicon oxide coatings directly onto polypropylene substrates. This deposition process is miniaturizing equipment footprints, enabling mid-scale thermoformers to enter barrier packaging segments previously dominated by capital-intensive multi-national operators.
Spain's alignment with ECHA restrictions on per- and polyfluoroalkyl substances is accelerating fluorine-free barrier chemistry development. The Spanish Agency for Food Safety and Nutrition is coordinating with EN standardization bodies to validate alternative oxygen scavenger additives for dairy applications. Thermoformed cheese packaging in Castile-La Mancha is the first segment facing reformulation deadlines, with converters sourcing bio-based barrier coatings to maintain shelf-life specifications.
Retail private-label programs are consolidating procurement decisions into centralized category management functions. Pan-European grocery operators are specifying uniform packaging specifications across their Spanish, French, and Portuguese store networks, displacing regionally customized designs. This concentration is most visible in Valencia's citrus juice bottling cluster, where three retail buying groups now account for the majority of PET bottle contract awards.
Spain Rigid Plastic Packaging Market Segmentation
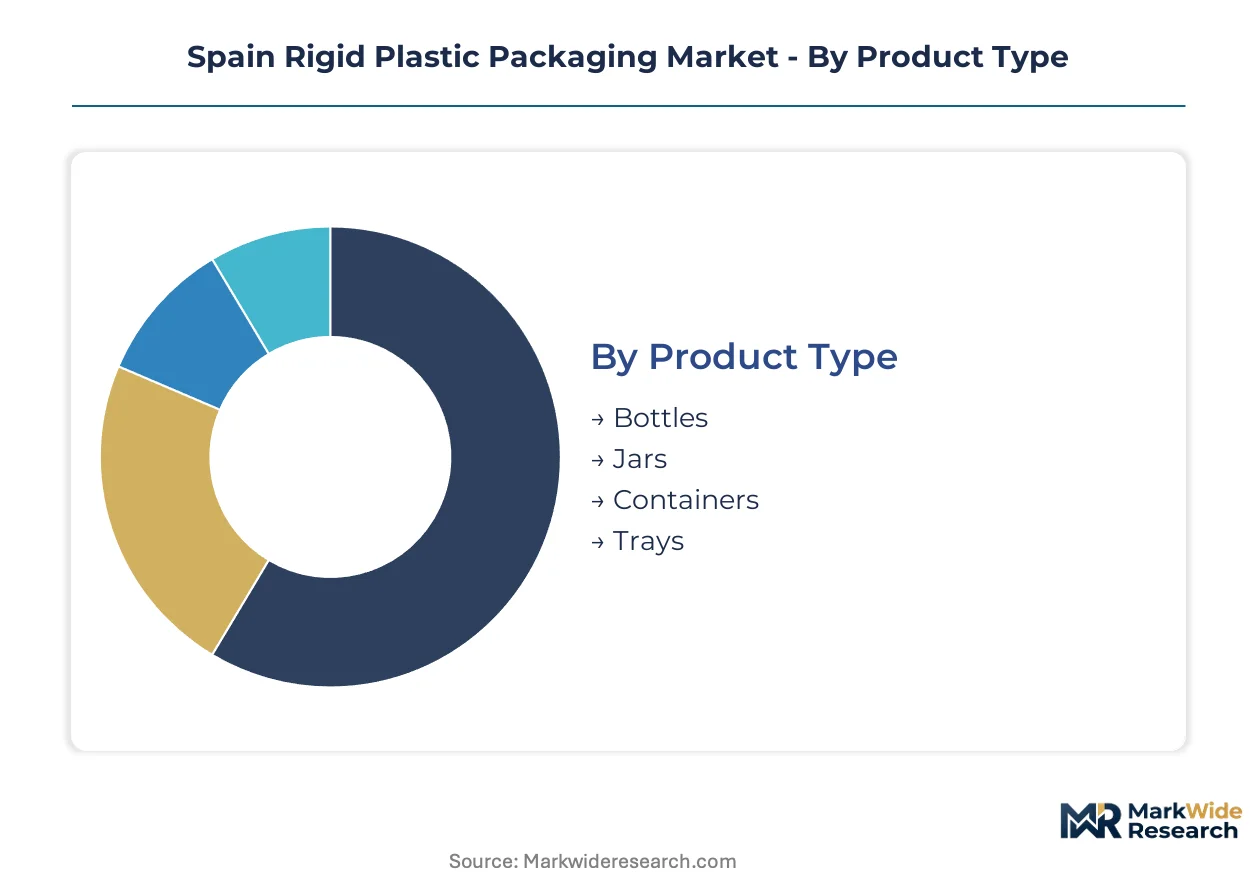
Segmentation in Spain's rigid plastic packaging market reveals how converter investments and procurement priorities diverge across material specifications, end-use requirements, and product formats. Understanding these divisions exposes where margin pools concentrate and where structural shifts are reshaping competitive positioning.
Product Type:
Premium margin capture concentrates in formats requiring barrier engineering and precision molding capabilities rather than commodity extrusion.
- Bottles:Blow-molded PET and HDPE structures dominate beverage and personal care distribution, with wall thickness optimization and lightweighting specifications driving converter R&D spend. Catalan bottling corridors around Barcelona generate concentrated demand for high-output rotary blow-molding lines serving mineral water and soft drink brands.
- Trays:Thermoformed structures with modified-atmosphere barrier layers are expanding fastest in fresh produce retail, particularly in Madrid and Valencia distribution networks where shelf-life extension commands procurement premiums. Oxygen scavenger integration and EVOH coextrusion separate tier-one suppliers from commodity thermoformers.
- Jars:Wide-mouth injection-molded containers serve shelf-stable food and personal care segments, with polypropylene and PET variants competing on clarity and microwaveability specifications.
- Containers:Industrial and household chemical packaging in polyethylene formats emphasizes stackability and chemical resistance, with UN certification requirements filtering supplier bases.
The dominant share belongs to bottles, while trays are closing the gap fastest as fresh produce retailers retrofit distribution infrastructure.
End User:
Procurement scale and specification complexity separate end-use segments, with food and beverage buyers commanding converter capacity through volume commitments and barrier performance requirements.
- Food:Thermoformed trays and injection-molded containers for dairy, meat, and prepared meals require migration-compliant formulations and extended shelf-life engineering. Castile-La Mancha cheese processors and Catalan meatpackers are consolidating supplier lists around converters with in-house barrier coating capabilities.
- Beverages:PET bottle demand from Spanish mineral water brands and retail private-label soft drink programs absorbs the majority of domestic blow-molding capacity. Lightweighting mandates and recycled content thresholds are reshaping resin sourcing economics for bottlers.
- Personal Care:Premium positioning in cosmetics and toiletries drives specification for clarity, decoration compatibility, and dispensing functionality in jars and bottles.
- Household:Industrial chemical and cleaning product containers prioritize chemical resistance and child-resistant closure compatibility over aesthetic properties.
Food and beverage together command converter priority, though personal care is expanding most quickly as premium positioning justifies higher unit margins.
Material:
Recycled content mandates and ECHA regulatory timelines are forcing material transition decisions that separate early movers from compliance laggards.
- PET:Clarity, lightweighting potential, and established recycling infrastructure make this the default for beverage bottles and food trays. Spanish converters face acute food-grade rPET scarcity as collection rates lag EU recycled content thresholds.
- Polypropylene:Barrier-enhanced grades with silicon oxide or bio-based coatings are displacing multi-layer structures in shelf-stable food applications. Madrid thermoformers are investing in plasma deposition equipment to capture this transition.
- Polyethylene:HDPE and LDPE variants retain cost advantages in industrial and household chemical containers where clarity is secondary to chemical resistance and impact strength.
- PVC:Pharmaceutical blister packs and specific medical applications sustain demand despite environmental pressure, with alternative materials gaining share in food contact.
PET holds the installed base advantage, while polypropylene is climbing the fastest as barrier engineering unlocks premium food packaging applications.
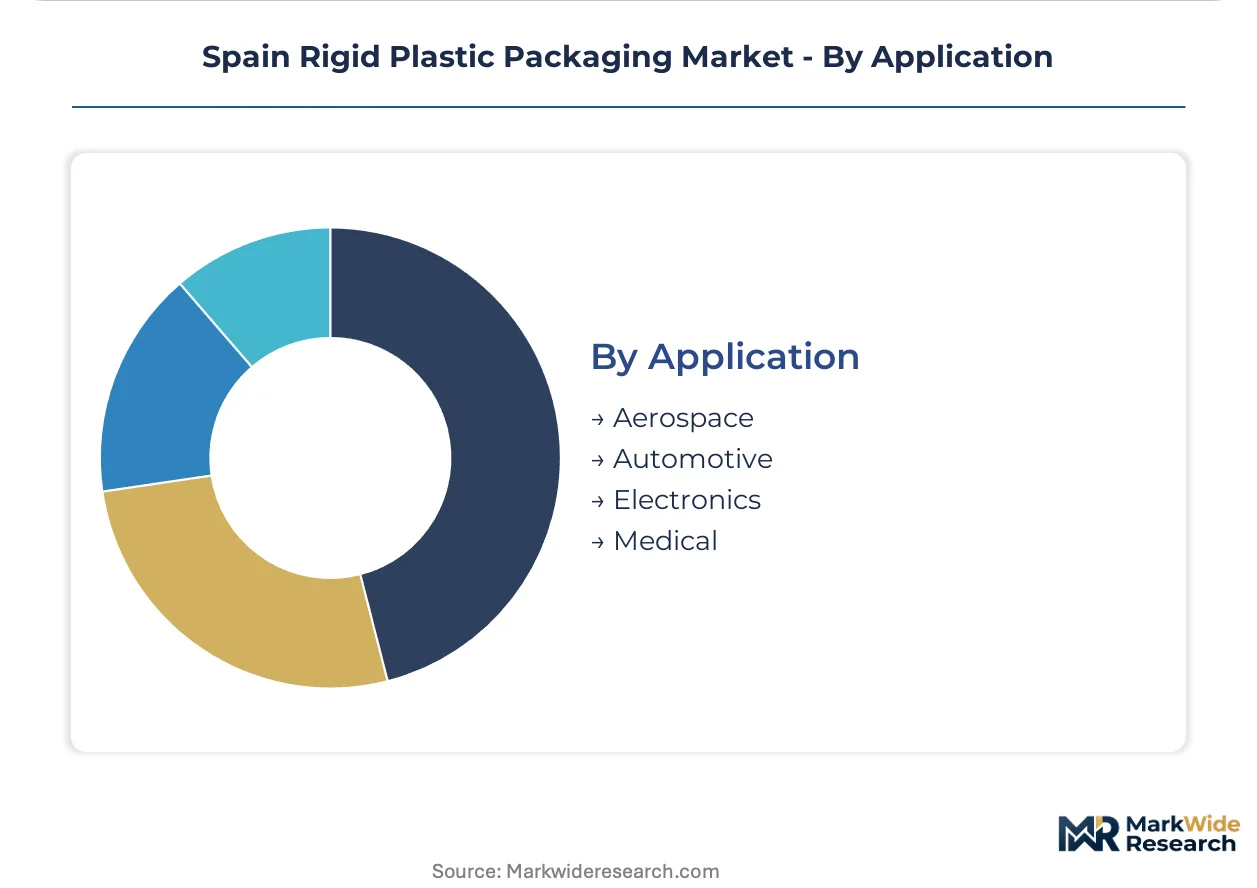
Application:
Specification stringency and certification burden vary dramatically across industrial end-uses, with medical and aerospace segments filtering supplier bases through quality system requirements.
- Medical:Sterile barrier systems, blister packs, and device housings demand ISO 13485 quality systems and validated sterilization compatibility. Andalusia's expanding generic drug manufacturing cluster is attracting thermoformer investment in barrier-enhanced PVC alternatives.
- Automotive:Fluid reservoirs, battery components, and interior trim applications specify engineering polymers with thermal and chemical resistance beyond standard packaging grades.
- Electronics:ESD-sensitive component trays and protective housings require conductive or dissipative formulations with precision molding tolerances.
- Aerospace:Cabin interior components and logistical packaging face flammability and weight specifications that limit viable material options.
Medical applications dominate rigid plastic packaging value capture outside consumer sectors, with automotive gaining share fastest as electric vehicle battery packaging requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish rigid plastic packaging exports flow primarily toward Portugal and France, with Catalonia's industrial corridor serving as the dominant production and logistics hub for Iberian distribution networks.
Catalonia
Beverage bottlers and fresh produce packagers in Barcelona's metropolitan area drive concentrated demand for PET bottles and thermoformed trays. The regional government enforces Catalonia's Waste Prevention and Management Law, which mandates higher recycled content thresholds than national baselines. Conversion operations cluster around Martorell and Vilafranca del Penedès, where blow-molding and thermoforming facilities supply pan-European retail private-label programs.
Madrid
Central Spain's food processing industry generates procurement volume for shelf-stable dairy and meat packaging formats. The Ministry for Ecological Transition administers national extended producer responsibility schemes from Madrid, setting compliance timelines that converters nationwide must meet. Thermoforming capacity concentrates in Alcalá de Henares and surrounding industrial zones, with sheet extrusion operations feeding tray manufacturing for retail distribution networks.
Valencia
Citrus juice bottlers and agricultural cooperatives in Spain's eastern seaboard specify rigid containers for export-oriented food products. Valencian regional authorities coordinate with EU-funded circular economy programs to expand post-consumer plastic collection infrastructure. The port city's logistics connectivity supports container manufacturing for Mediterranean shipping routes, with particular strength in industrial chemical packaging.
Andalusia
Generic pharmaceutical manufacturers in Seville and Málaga generate emerging demand for barrier-enhanced blister packs and medical device housings. The Spanish Agency for Food Safety and Nutrition validates alternative barrier chemistries for regional dairy and olive oil applications. Thermoformer investment is targeting Córdoba and Granada industrial parks to serve both medical and food contact segments with migration-compliant formulations.
Basque Country
Specialty chemical and automotive component manufacturers in Bilbao and San Sebastián specify engineering-grade rigid plastics for industrial applications. ECHA-aligned regional environmental agencies enforce strict polymer additive restrictions that filter supplier qualification. Injection molding operations concentrate around Vitoria-Gasteiz, serving both domestic industrial demand and cross-border French manufacturing customers.
Spain Rigid Plastic Packaging Market Competitive Landscape
Player mix skews toward integrated multinational converters with blow-molding and thermoforming capabilities. Three structural tiers separate capital-intensive rotary blow-molding specialists from regional thermoformers and commodity injection molders. Dominant competitive moves include capacity expansion in barrier-enhanced formats and strategic partnerships with retail private-label buying groups.
Within the integrated multinational tier, ALPLA Group and Berry Global, Inc. exemplify scale-driven positioning across PET bottle and multi-material container platforms. COEXPAN S.A.U. occupies a distinctive position as a regional thermoforming specialist with integrated sheet extrusion capabilities. These three anchors represent how converter investment strategies diverge between high-volume beverage supply and barrier-engineered food packaging segments.
| Leading Market Players |
|---|
| ALPLA Group |
| Berry Global, Inc. |
| Berlin Packaging |
| Sonoco Products Company |
| Plastipak Holdings, Inc. |
| COEXPAN S.A.U. |
| ITC Packaging |
| Graham Packaging |
| Amcor PLC |
| Others |
Pricing and Supply Chain Analysis
Fourteen-week migration testing backlogs for EN-compliant food-contact certification concentrate pricing power among converters with in-house laboratory capabilities, while smaller thermoformers absorb margin compression from extended certification timelines and rPET feedstock scarcity.
Pricing Analysis
Current-generation plasma-enhanced barrier coating equipment commands substantial premiums over conventional extrusion lines, while prior-generation multi-layer coextrusion systems face accelerated depreciation as ECHA fluorine-free mandates approach. Three-tier pricing structure across premium barrier-enhanced, standard food-grade, and economy industrial grades separates converters by certification tier and volume commitment scale. Cost compression in standard PET bottle segments is intensifying because retail private-label buying groups consolidate procurement across Iberian networks. Pan-European grocery operators exhibit lowest price sensitivity due to specification uniformity requirements, while small-batch artisanal food producers face highest sensitivity as supplier lists narrow.
Supply Chain Analysis
Inventory buffers for food-grade rPET flake have compressed to six-week coverage as Spanish collection infrastructure fails to match converter demand, forcing dependence on imported bales from Germany, France, and Italy. Virgin PET resin sourcing draws from Saudi Arabian and Belgian petrochemical complexes, with natural gas price volatility transmitting directly to polymer extrusion cost structures. Single-source vulnerability concentrates in EVOH barrier layer supply, where Kuraray and Mitsubishi Chemical anchor European distribution. Distribution runs through Catalonia's Martorell-Vilafranca corridor for beverage bottlers and Madrid's Alcalá de Henares hub for food thermoforming.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier engineering capabilities—specifically plasma deposition equipment and migration-compliant formulation expertise—have become the binding constraint separating tier-one converters from commodity competitors, with only three Spanish thermoformers currently qualified for ECHA-aligned fluorine-free dairy packaging.
For Market Incumbents: Compound barrier technology leadership through captive plasma coating equipment installation in Barcelona's industrial corridor, while securing long-term offtake agreements with pan-European retail buying groups to lock volume against emerging regional thermoformers. ECHA's accelerating per- and polyfluoroalkyl substance restrictions threaten multi-layer laminate portfolios, demanding urgent reformulation investment. For New Entrants and Emerging Players: Anchor in Andalusia's pharmaceutical blister pack segment, where ISO 13485 certification scarcity and generic drug manufacturing expansion create qualified supplier deficits. Córdoba and Granada industrial parks offer lower facility costs than Catalonia, with Seville's medical device cluster providing anchor demand for barrier-enhanced PVC alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across barrier-enhanced polypropylene segments as plasma deposition equipment minimums exclude sub-scale competitors, favoring acquisition of Madrid thermoformers with existing sheet extrusion integration. Watch for EU-wide recycled content mandate enforcement as the signal indicating rPET procurement economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Deposition Capacity Expansion | Enables mid-scale thermoformers to enter barrier packaging segments previously reserved for multinational operators. |
| Backward Integration into Sheet Extrusion | COEXPAN's Madrid-Barcelona integrated model demonstrates margin capture from resin pellet to finished tray. |
| Fluorine-Free Barrier Chemistry Development | ECHA restriction timelines force reformulation investment to maintain Castile-La Mancha dairy packaging contracts. |
| Retail Private-Label Procurement Consolidation | Valencia citrus juice bottlers now depend on three buying groups controlling majority PET bottle contract awards. |
| Digital Watermarking and AI Sorting Integration | Certifies recycled content claims for ESG reporting while addressing post-consumer rPET supply scarcity. |
Research Methodology
A spread of perspectives from blow-molding plant managers, retail category buyers, polymer procurement leads at beverage bottlers, and ECHA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews across Catalonia's Martorell corridor and Madrid's Alcalá de Henares hub with secondary validation through Spanish Ministry for Ecological Transition filings, EU Packaging and Packaging Waste Directive implementation documents, and EN standardization body migration testing protocols. Bottom-up capacity assessments at converter facilities were triangulated against top-down demand modeling from pan-European retail procurement data.
Segmentation dimensions modeled span product type (bottles, trays, jars, containers), material specification (PET, polypropylene, polyethylene, PVC), end-use vertical (food, beverage, personal care, household, medical), and regional production cluster (Catalonia, Madrid, Valencia, Andalusia, Basque Country). CAGRs were derived from elasticity-adjusted volume projections incorporating lightweighting imperatives and recycled content mandate compliance curves. Forecast inputs included natural gas price transmission coefficients to polymer extrusion costs and ECHA restriction timeline probabilities for barrier chemistry reformulation.
Decision-makers should treat outputs as directional under assumptions of sustained EU circular economy enforcement and no catastrophic disruption to Iberian natural gas supply; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market