
 Latin America Rigid Plastic Packaging Market | 2026-2036
Latin America Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Rigid Plastic Packaging Market Insights
Buyer concentration among Latin American food and beverage processors is shifting toward larger multinational bottlers and regional dairy cooperatives seeking standardized rigid container supply. Amcor Group GmbH leverages its blow-molding footprint across Brazil and Mexico to anchor volume contracts with these consolidated buyers. Berry Global Inc. competes through specialized dairy jar and pharmaceutical bottle lines that meet ANVISA compliance tiers. Silgan Holdings Inc. dominates the metal-and-plastic hybrid closure segment that food processors specify for shelf-stable formats.
Latin America Rigid Plastic Packaging comprises injection-molded, blow-molded, or thermoformed plastic structures with wall thickness exceeding 0.010 inches, engineered to protect contents from moisture, oxygen, and mechanical damage during distribution across tropical climates. PET bottles lead volume due to carbonated soft drink and bottled water demand, while polypropylene containers capture margin pools in hot-fill dairy and retort food applications where temperature resistance exceeds 85 degrees Celsius. Polyethylene drums and intermediate bulk containers sustain industrial chemical logistics across the region's petrochemical corridor.
ANVISA governs pharmaceutical primary packaging integrity and child-resistant closure standards in Brazil, while Mexico's COFEPRIS aligns with US FDA bioequivalence protocols for exported drug products. Brazil's CONAMA Resolution 362 mandates post-consumer resin incorporation thresholds that reshape virgin polymer procurement for rigid food containers. Stakeholders must monitor pending extended producer responsibility legislation across Colombia, Chile, and Argentina that will determine recycling infrastructure investment viability and resin qualification costs for multinational suppliers.
Market Dynamics
ANVISA pharmaceutical traceability mandates and Brazil's CONAMA Resolution 362 post-consumer resin thresholds are forcing rigid packaging converters to requalify material streams and reconfigure blow-molding lines across São Paulo's industrial corridor.
Growth Catalysts
- Hot-fill dairy expansion:Polypropylene containers rated above 85 degrees Celsius are capturing retort food applications as Mexican dairy cooperatives consolidate bottling operations around Monterrey.
- ANVISA compliance tier differentiation:Pharmaceutical primary packaging integrity standards are creating premium qualification pools for child-resistant closure systems in Brazil's generics export sector.
- Petrochemical corridor logistics:Polyethylene intermediate bulk containers sustain industrial chemical distribution across Brazil's southeastern manufacturing cluster.
Market Restraints
- Virgin polymer price volatility:Ethylene and propylene feedstock swings compress converter margins on fixed-price beverage contracts.
- Recycling infrastructure gaps:Colombia, Chile, and Argentina lack mechanical recycling capacity to meet pending extended producer responsibility resin qualification thresholds.
- Metal closure substitution:Aluminum cans and steel aerosols displace rigid PET in shelf-stable beverage segments where oxygen barrier demands exceed blow-molding economics.
Strategic Opportunities
- Colombian EPR legislation:Pending extended producer responsibility frameworks will determine first-mover recycling infrastructure investment viability in Bogotá's manufacturing zone.
- Digital watermark traceability:Machine-readable packaging markers converge with ANVISA pharmaceutical serialization requirements to enable granular supply chain visibility.
- Argentina dairy cold-chain:Underpenetrated ultrahigh-temperature milk bottling creates demand for multilayer barrier rigid containers in Buenos Aires province.
Industry Challenges
- Blow-molding requalification timelines:Post-consumer resin incorporation mandates require 18-24 month material validation cycles that disrupt existing production schedules.
- Multilayer delamination:Barrier layer separation in hot-fill polypropylene containers creates quality control complexity for retort food processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Rigid Plastic Packaging Market |
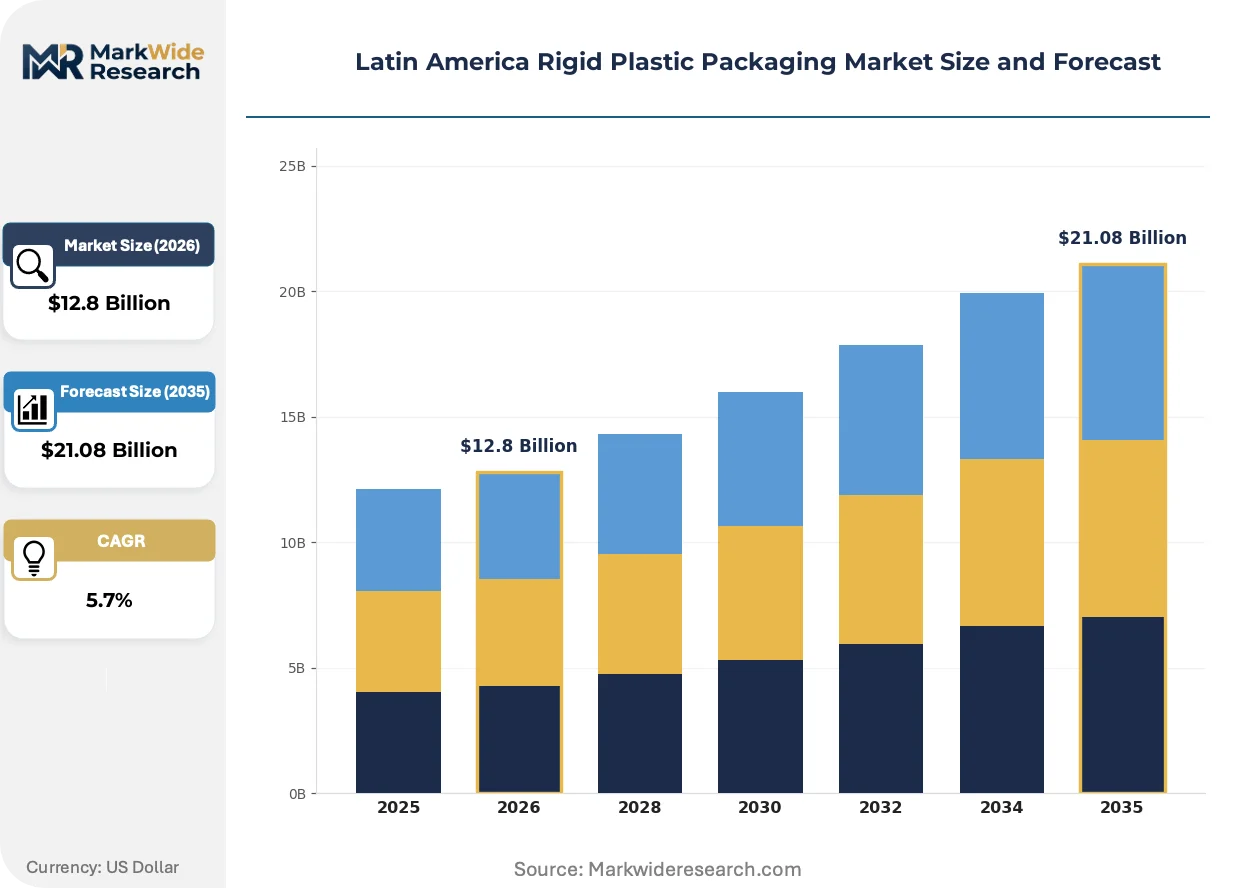
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays Material: Polyethylene, Polypropylene, Polyvinyl Chloride, PET End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Packaging Type: Rigid Containers, Drums, Boxes, Clamshells |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., Silgan Holdings Inc., Plastipak Holding Inc., Sonoco Products Company, Alpla Werke Alwin Lehner GmbH & Co KG, Sealed Air Corporation, Albea Group, Greiner Packaging International GmbH, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Rigid Plastic Packaging Market Trends and Innovations
Digital printing and smart packaging markers are compressing batch customization lead times while regulatory serialization demands reshape pharmaceutical and food-grade container specifications across Latin American converter networks.
Digital direct-to-object printing is expanding into blow-molded PET beverage bottles, enabling lot-specific variable data and promotional versioning without label substrate costs. Brazilian multinational bottlers in São Paulo state are adopting this technology for seasonal SKU proliferation. The capability is expanding into short-run pharmaceutical bottles where ANVISA traceability codes previously required secondary label application.
CONAMA Resolution 362 mandates minimum post-consumer recycled content thresholds for rigid food containers sold in Brazil, compelling converters to requalify rPET streams for direct food contact. The regulation forces virgin resin substitution in carbonated soft drink bottles while creating supply competition with Mexico's export-oriented recycling collectors. Pharmaceutical packaging remains exempt, preserving virgin polymer pools for bioequivalence-critical drug products.
Buyer concentration among regional dairy cooperatives is compressing supplier negotiation cycles from annual to quarterly terms. Monterrey manufacturing clusters now specify blow-molding capacity reservations rather than spot volume commitments. This pattern is most visible in hot-fill polypropylene jar contracts where temperature resistance certification creates switching costs.
Latin America Rigid Plastic Packaging Market Segmentation
Rigid plastic packaging converters across Latin America configure production lines around specific resin rheology and cavity tooling requirements. Segment boundaries determine capital allocation priorities across São Paulo's blow-molding corridor and Monterrey's injection-molding clusters.
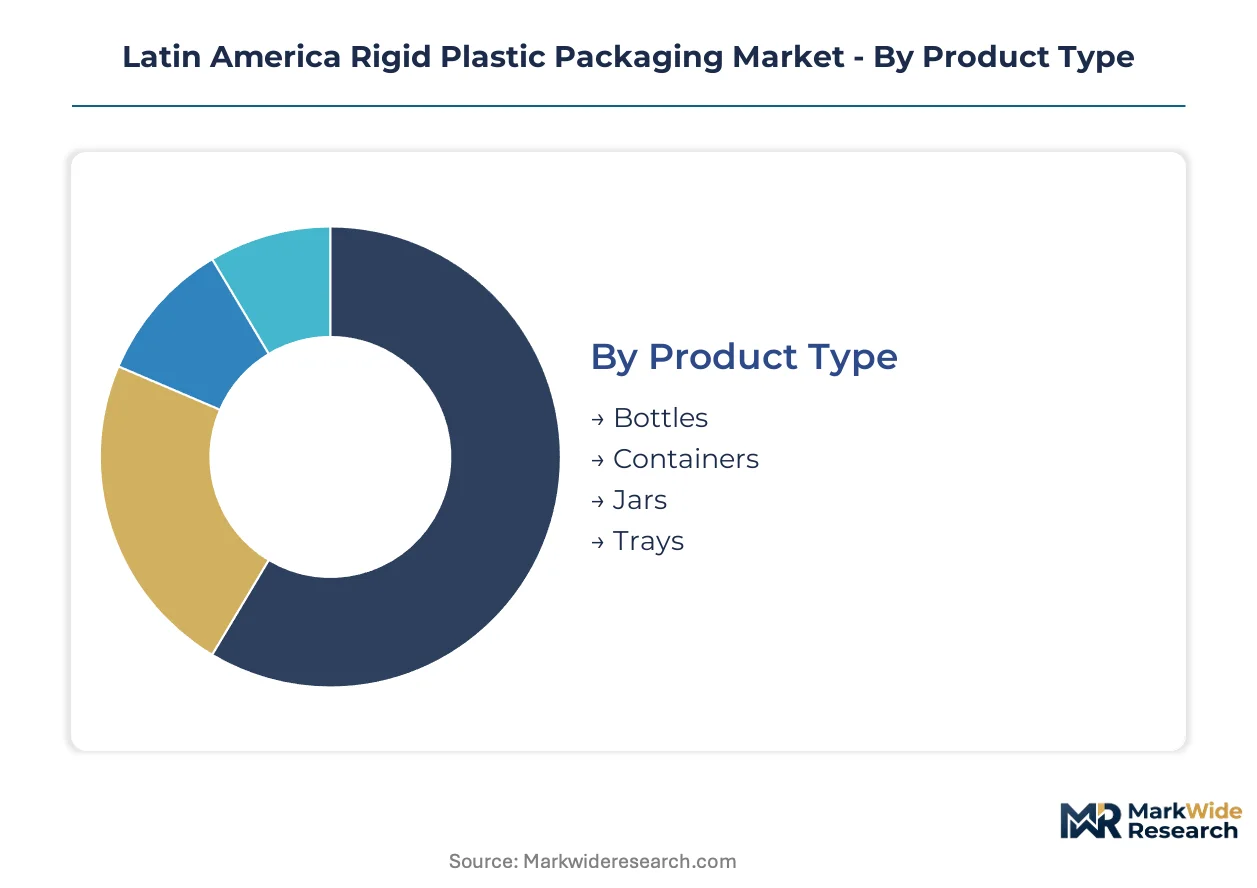
Product Type:
Capital intensity peaks with stretch-blow molding equipment for thin-walled carbonated beverage formats, while thermoforming lines for clamshells demand lower upfront investment but higher per-unit labor content.
- Bottles:Stretch-blow molded PET structures with biaxial orientation achieve carbonation retention below 0.1% CO2 loss per month. Demand concentrates among multinational soft drink bottlers in São Paulo state where seasonal SKU proliferation drives digital printing adoption.
- Containers:Injection-molded polypropylene tubs and pails with hot-fill stability above 85 degrees Celsius serve retort food processors. Mexican dairy cooperatives around Monterrey specify these for ultrahigh-temperature milk distribution where barrier integrity determines shelf life.
- Jars:Wide-mouth polyethylene terephthalate or polypropylene formats with continuous-thread or lug finishes target mayonnaise and sauce categories.
- Trays:Thermoformed polystyrene or PET structures for fresh produce display and meat packaging applications.
Most installed capacity flows through Bottles. Expansion is steepest in Containers.
Material:
Resin selection dictates processing temperature windows, barrier performance, and compliance with Brazil's CONAMA post-consumer recycled content mandates.
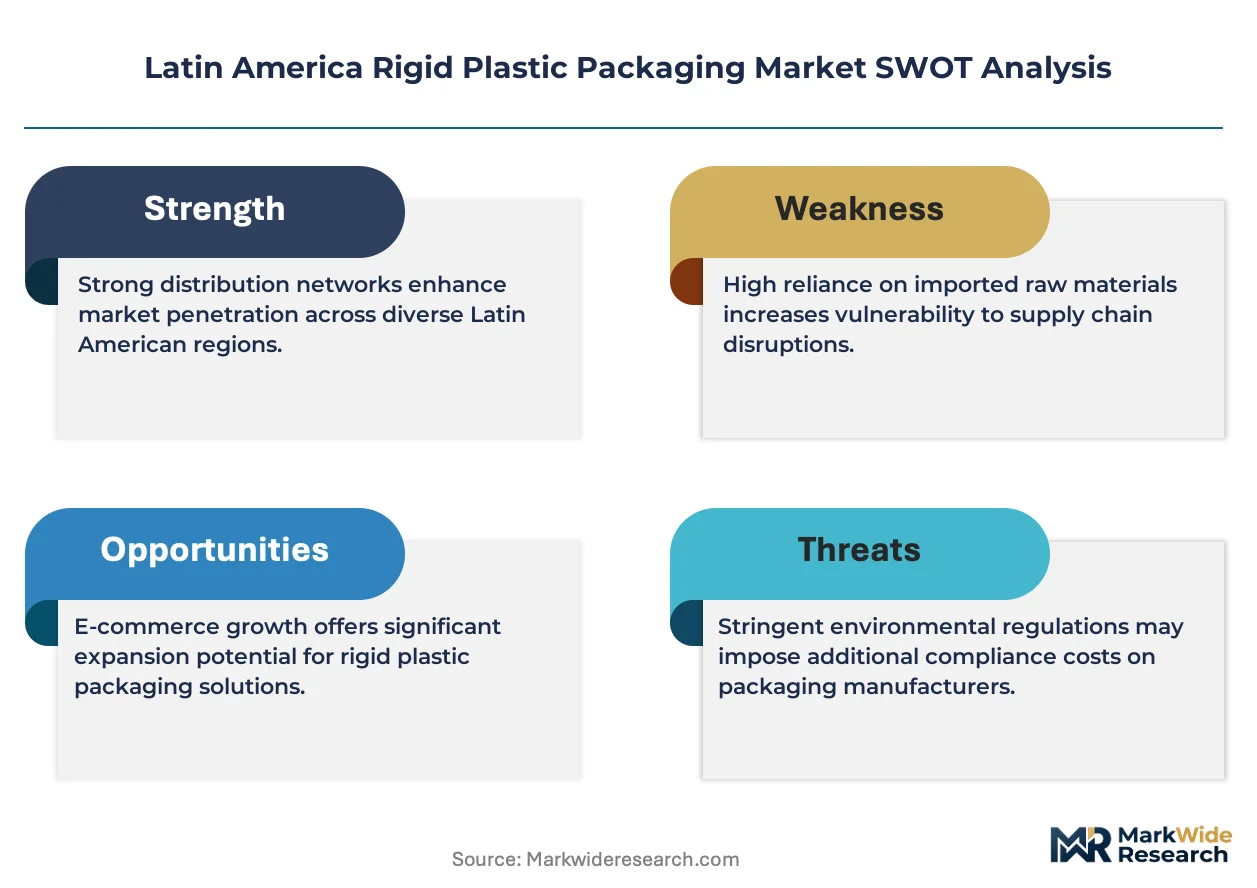
- Polyethylene:High-density and low-density grades extrude into drums and intermediate bulk containers for industrial chemical logistics. Brazil's petrochemical corridor in São Paulo state supplies captive ethylene feedstock to regional converters serving agrochemical distributors.
- PET:Bottle-grade polyethylene terephthalate with intrinsic viscosity 0.80-0.85 dL/g dominates carbonated soft drink and bottled water categories. ANVISA pharmaceutical packaging standards exempt virgin PET from recycled content mandates, preserving material pools for bioequivalence-critical drug products.
- Polypropylene:Homopolymer and random copolymer grades withstand hot-fill temperatures above 85 degrees Celsius in dairy and retort applications.
- Polyvinyl Chloride:Rigid PVC compounds with tin or calcium-zinc stabilizers serve blister packs and pharmaceutical primary packaging where clarity and thermoformability outweigh environmental scrutiny.
Polyethylene commands the largest installed base. PET is gaining share fastest in food-contact applications.
End User:
Customer concentration patterns split between multinational volume contracts and regional specialty qualification requirements.
- Food & Beverage:Carbonated soft drink, bottled water, dairy, and processed food categories drive blow-molded PET and hot-fill polypropylene demand. Brazil's multinational bottlers and Mexico's dairy cooperatives anchor procurement with quarterly capacity reservations rather than annual spot contracts.
- Pharmaceuticals:Primary packaging for oral solid dose and liquid medications requires ANVISA traceability compliance and child-resistant closure certification. Generic drug exporters in São Paulo state specify virgin polymer streams to meet US FDA bioequivalence protocols.
- Personal Care:Shampoo, conditioner, and lotion bottles in polyethylene terephthalate or high-density polyethylene serve mass-market and premium positioning tiers.
- Household Products:Cleaning chemical containers in polyethylene or polypropylene withstand surfactant and solvent exposure.
Food & Beverage absorbs the majority of converter throughput. Pharmaceuticals delivers the highest margin per kilogram.
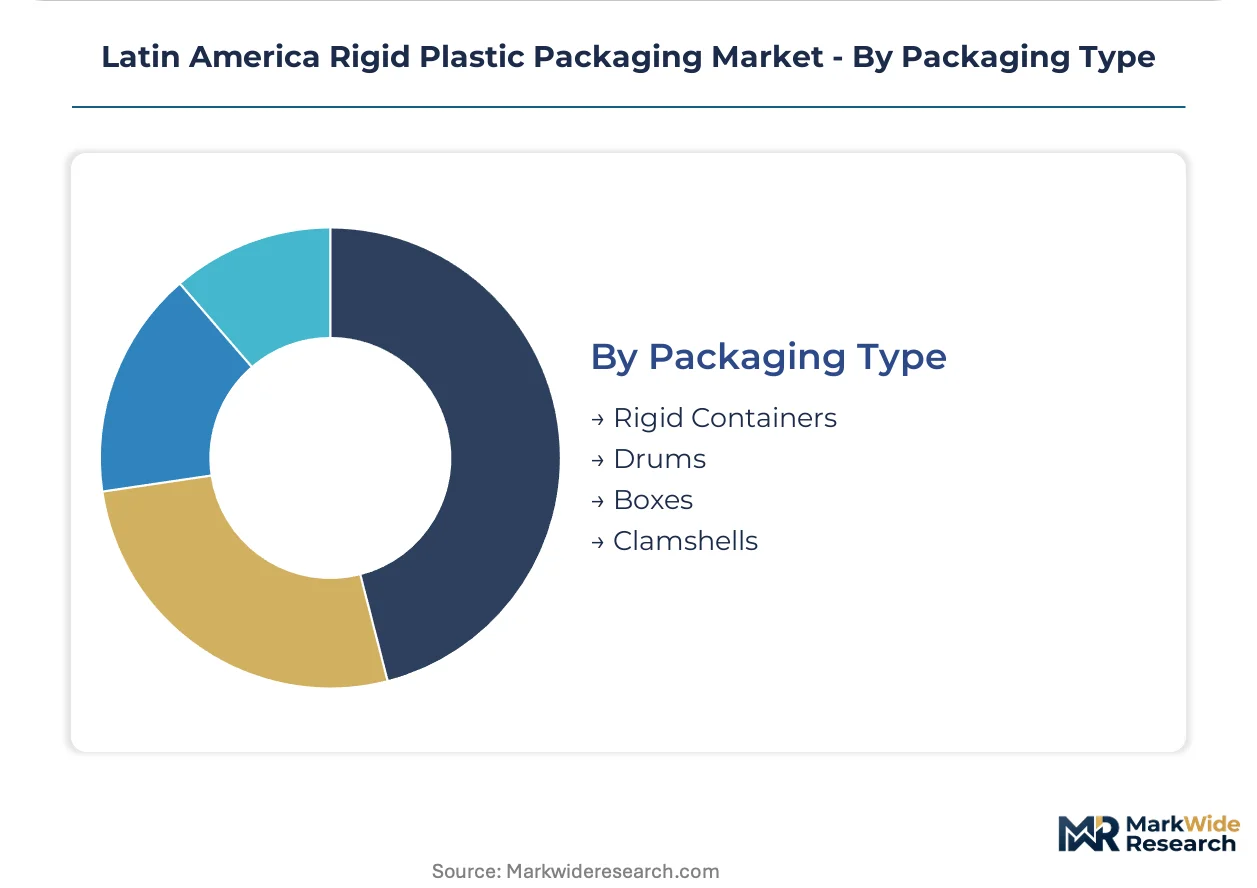
Packaging Type:
Structural format determines logistics efficiency and retail display economics across Latin American distribution networks.
- Rigid Containers:Injection-molded or blow-molded enclosed structures with integral handles or stacking features serve food, chemical, and pharmaceutical applications. São Paulo's industrial corridor hosts the densest concentration of multi-cavity tooling for these formats.
- Drums:High-density polyethylene or steel-reinforced plastic intermediate bulk containers handle industrial chemical and edible oil logistics. Brazil's southeastern manufacturing cluster generates demand for 200-liter formats in agrochemical and lubricant distribution.
- Boxes:Injection-molded polypropylene or polyethylene totes with interlocking lids target automotive parts and electronics component transport.
- Clamshells:Thermoformed PET or polystyrene hinged structures protect fresh produce and consumer electronics through retail display.
Drums retain the most stable demand profile. Rigid Containers show the steepest expansion trajectory in pharmaceutical and dairy qualification tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and Mexico diverge in regulatory intensity despite anchoring comparable converter throughput volumes. Brazil's ANVISA pharmaceutical mandates and CONAMA recycling thresholds impose steeper compliance costs than Mexico's COFEPRIS-aligned export protocols.
Brazil
São Paulo state's industrial corridor hosts the densest concentration of stretch-blow molding capacity for carbonated beverage bottles. ANVISA Resolution RDC 430 governs pharmaceutical primary packaging integrity and traceability serialization requirements. CONAMA Resolution 362 mandates post-consumer resin thresholds that force virgin polymer requalification across converters in the ABC Paulista manufacturing zone.
Mexico
Monterrey's manufacturing cluster anchors hot-fill polypropylene container demand from consolidating dairy cooperatives. COFEPRIS aligns with US FDA bioequivalence protocols for generic drug exports to the United States. The Nuevo León petrochemical corridor supplies captive propylene feedstock to regional injection molders serving retort food processors.
Argentina
Buenos Aires province presents underpenetrated ultrahigh-temperature milk bottling demand for multilayer barrier rigid containers. The country's national food safety regulator enforces cold-chain integrity standards for dairy distribution. Greater Buenos Aires hosts emerging converter investments targeting dairy cooperatives with hot-fill polypropylene jar capacity.
Chile
Santiago's central valley agribusiness sector drives thermoformed clamshell demand for fresh produce export packaging. Pending extended producer responsibility legislation will reshape resin qualification costs for converters serving Valparaíso's port logistics cluster. The regulatory framework remains under legislative review with implementation timelines uncertain.
Colombia
Bogotá's manufacturing zone attracts first-mover recycling infrastructure investment ahead of anticipated extended producer responsibility mandates. The national environmental ministry oversees post-consumer collection targets that will determine mechanical recycling capacity viability. Antioquia Department's Medellín metro area hosts secondary packaging converters supplying Andean beverage distributors.
Latin America Rigid Plastic Packaging Market Competitive Landscape
Brazilian and Mexican producers anchor the volume-contract tier; European and North American specialists hold premium qualification positions in pharmaceutical and dairy segments. Market structure consolidates around multinational converters with blow-molding footprints spanning multiple countries alongside regional mid-caps with ANVISA compliance specialization. Three archetypes dominate: integrated resin-to-container operators, compliance-tier specialists, and logistics-format drum manufacturers. Competitive dynamics center on capacity reservation contracting and post-consumer resin stream requalification timelines.
Within the multinational integrated tier, Amcor Group GmbH and Berry Global Inc. exemplify scale-driven positioning across São Paulo and Monterrey manufacturing corridors. Silgan Holdings Inc. occupies a specialized position in closure systems that bridge metal and plastic hybrid formats. These three entities represent distinct strategic postures: resin integration breadth, dairy-pharmaceutical compliance depth, and metal-plastic hybrid technology respectively.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| Plastipak Holding Inc. |
| Sonoco Products Company |
| Alpla Werke Alwin Lehner GmbH & Co KG |
| Sealed Air Corporation |
| Albea Group |
| Greiner Packaging International GmbH |
| Others |
Pricing and Supply Chain Analysis
Certification-tier bifurcation between ANVISA-compliant pharmaceutical packaging and commodity food-grade containers splits pricing power across São Paulo's converter corridor. Premium qualification pools command resin allocation priority while CONAMA-mandated recycled content thresholds compress margins on standardized beverage contracts.
Pricing Analysis
Capacity additions in Brazil's ABC Paulista zone are reshaping price floors for injection-molded polypropylene containers. Three-tier pricing structure across ANVISA-certified, food-grade virgin, and post-consumer resin tiers separates pharmaceutical buyers from dairy cooperatives from mass-market bottlers. Cost compression in rPET-blended beverage formats is intensifying because Mexican export collectors compete for limited recycled feedstock. Multinational soft drink bottlers show lowest price sensitivity; regional dairy cooperatives negotiate quarterly capacity reservations with switching-cost leverage.
Supply Chain Analysis
Dual-sourcing mandates from Monterrey dairy cooperatives and São Paulo pharmaceutical exporters require converters to qualify backup blow-molding lines across multiple facilities. Geographic supply concentration centers on Brazil, Mexico, and Argentina for resin conversion, with virgin PET feedstock anchored in Brazil's southeastern petrochemical corridor. Raw material dependencies rest on ethylene and propylene monomer supply, imported additive packages for barrier enhancement, and qualified post-consumer resin streams. Single-source vulnerability runs through rPET collection infrastructure gaps in Colombia and Chile. Distribution runs through converter-direct contracts with multinational bottlers rather than distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America rigid plastic packaging functions as a geographic-arbitrage play where Brazil's CONAMA compliance costs exceed Mexico's COFEPRIS-aligned export economics by a full certification tier.
For Market Incumbents: Hedge resin cost exposure through backward integration into São Paulo-state rPET collection infrastructure before Colombian EPR mandates activate. Defend ANVISA qualification moats by accelerating child-resistant closure R&D aluminum can substitution threatens shelf-stable PET volumes in Brazilian beverage segments.
For New Entrants and Emerging Players: Enter via Buenos Aires province ultrahigh-temperature dairy bottling where incumbent capacity reservations have not penetrated. Target hot-fill polypropylene jar segments in Argentina's underdeveloped cold-chain infrastructure. Lead with digital watermark traceability as a bundled qualification service for ANVISA serialization mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where post-consumer resin requalification timelines exceed 18 months and smaller converters lack validation laboratory access. Five-to-ten year viability favors integrated resin-to-container operators with captive recycling infrastructure over standalone blow-molding assets. Watch ANVISA pharmaceutical serialization enforcement intensity as the inflection signal for premium-tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| rPET Stream Requalification | CONAMA Resolution 362 compliance locks in virgin resin substitution timelines across São Paulo converters. |
| Digital Watermark Integration | Machine-readable markers converge with ANVISA pharmaceutical serialization for supply chain visibility. |
| Hot-Fill Capacity Expansion | Monterrey dairy cooperatives specify temperature-resistant polypropylene for UHT milk distribution. |
| Backward Integration into Collection | Captive rPET feedstock secures margin protection against Mexican export competition. |
| Child-Resistant Closure R&D | ANVISA compliance tiers create premium qualification pools for generic drug exporters. |
Research Methodology
Direct dialogue with blow-molding plant managers, ANVISA regulatory affairs leads, dairy cooperative procurement officers, and petrochemical distribution channel partners grounded qualitative findings. Secondary validation drew from customs and trade data, SEC 10-K filings of listed packaging converters, ANVISA regulatory bulletins, and CONAMA resolution texts. Bottom-up capacity utilization surveys across São Paulo and Monterrey manufacturing clusters were triangulated against top-down resin consumption estimates from regional petrochemical associations.
Bottom-up modeling of installed blow-molding and injection-molding capacity across product type, material grade, and end-user industry dimensions fed into value projections over the analysis window. CAGRs were derived from segment-level volume trajectories weighted by resin price assumptions. Industry-specific forecast inputs included ANVISA pharmaceutical serialization rollout pace and CONAMA post-consumer resin threshold implementation schedules.
Inputs from converter facility surveys and regulatory filing databases were available through the study window; gaps in real-time rPET spot pricing and pending EPR legislative drafts in Colombia and Chile introduce uncertainty bands around recycling infrastructure investment assumptions. Deviation in ANVISA enforcement intensity or CONAMA threshold acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market