
 Transparent Plastic Packaging Market | 2026-2036
Transparent Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Plastic Packaging Market Analytics
Asset-light leasing models for extrusion and thermoforming equipment are narrowing the capital barrier for mid-sized converters entering the transparent packaging space. Amcor leverages its global film manufacturing footprint to sustain supply agreements with multinational food brands. Berry Global anchors North American rigid container demand through controlled distribution into dairy and ready-meal channels. Klöckner Pentaplast specializes in pharmaceutical-grade blister films, occupying a premium niche with stringent clean-room requirements.
Transparent plastic packaging denotes visibly clear polymer structures—typically PET, PP, or PVC between 50 and 500 microns—engineered for product visibility, barrier protection, and shelf-life extension across retail and institutional channels. The category serves primary functions in containment, preservation, and consumer communication through optical clarity. Flexible packaging and shrink films lead volume throughput due to their compatibility with high-speed form-fill-seal operations and e-commerce logistics. Rigid containers command stronger margin pools in dairy and personal care applications where dimensional stability and reclosability justify material intensity. Blister packs compete on tamper-evidence and unit-dose precision, differentiating pharmaceutical compliance packaging from commodity formats.
The FDA governs food-contact notification pathways for virgin and recycled polymers used in transparent packaging, while the EPA administers emissions standards for extrusion and solvent-based coating operations. The EU Green Deal and REACH restrict certain phthalate plasticizers and mandate recyclability design criteria, redirecting converter R&D toward mono-material solutions. China's SAMR enforces GB standards for food-contact plastics, shaping export compliance for Asian suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to internalize recycling infrastructure or partner with specialized reclaimers.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing converters to redesign multi-layer structures into mono-material formats, compressing R&D timelines and reshaping supplier qualification criteria across European food-contact applications.
Growth Catalysts
- EU Green Deal mandates:Recycled-content quotas in food-grade rPET are accelerating converter investment in decontamination and extrusion lines.
- E-commerce logistics expansion:High-clarity shrink films for unitization and damage reduction are seeing stepped-up procurement from third-party fulfillment operators.
- Pharmaceutical serialization requirements:Tamper-evident blister formats with track-and-trace compatibility are displacing older push-through designs in regulated markets.
Market Restraints
- Feedstock volatility:Purified terephthalic acid and ethylene glycol pricing swings compress margin predictability for PET film extruders.
- Collection infrastructure gaps:Post-consumer rigid container recovery rates in the United States lag European benchmarks, limiting closed-loop supply.
- Barrier performance ceilings:Mono-material PP structures struggle to match metallized or EVOH coextruded oxygen transmission rates for sensitive proteins.
Strategic Opportunities
- India's organized retail expansion:Modern trade penetration in tier-two cities is creating first-mover openings for preformed tray and lidding film suppliers.
- Bio-based polymer maturation:PLA and PHA clarity grades are approaching optical haze thresholds viable for fresh produce overwrap applications.
- Deposit-return scheme rollouts:Germany and Scandinavian markets are building predictable post-consumer PET bottle flows for food-grade recycling investments.
Industry Challenges
- Food-contact notification timelines:FDA pre-market clearance for novel recycled-content resins stretches 12-18 months, delaying product launches.
- Extrusion technician scarcity:Specialized knowledge in flat-die calibration and chill-roll polishing is retiring faster than vocational programs replace it.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Plastic Packaging Market |
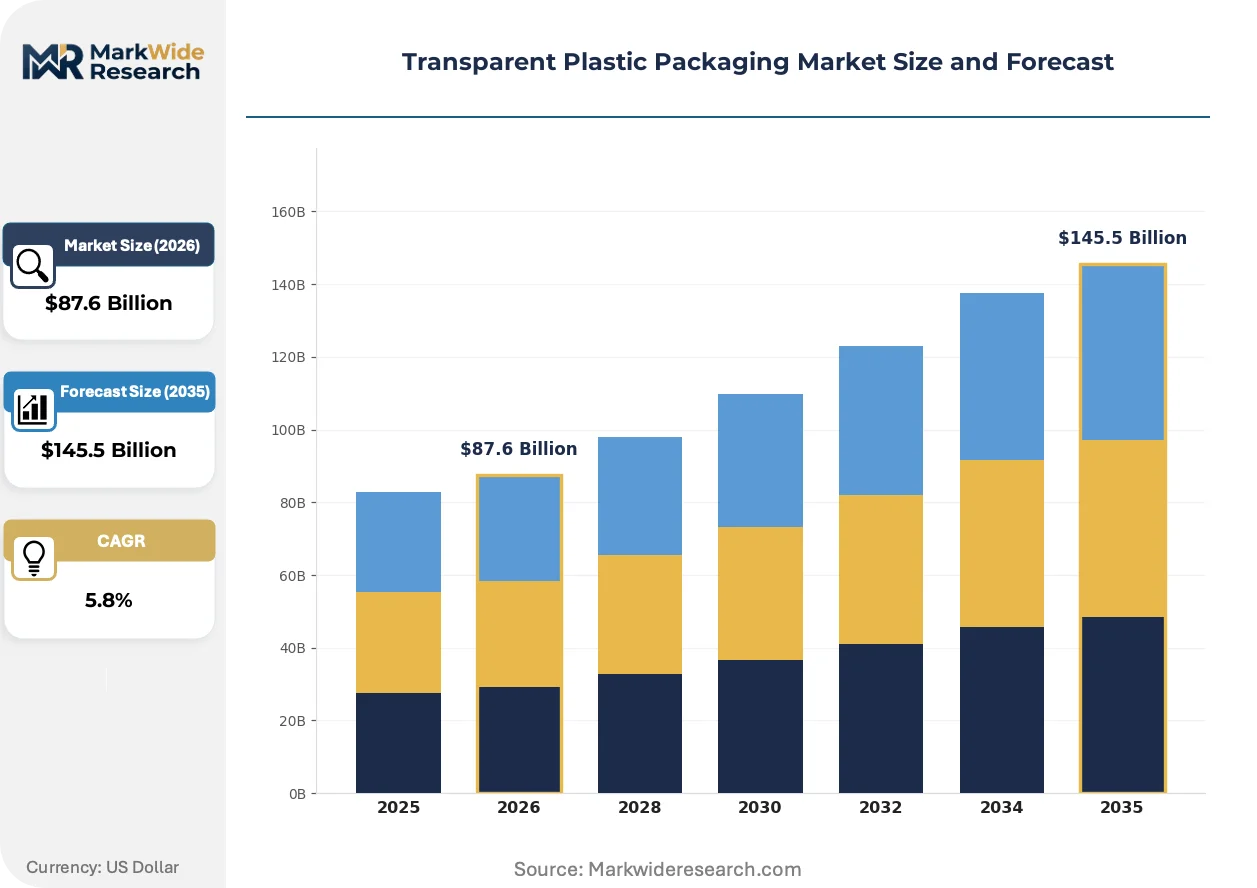
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $145.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Containers, Flexible Packaging, Shrink Films, Blister Packs Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Form: Roll Stock, Pouches, Bottles, Trays |
| Companies Covered | SABIC, Constantia Flexibles, Amcor, Toyobo Packaging, Klöckner Pentaplast, Berry Global, Huhtamaki, BASF, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Plastic Packaging Market Evolving Landscape
Material science advances and regulatory design rules are converging to redefine optical clarity specifications, barrier architectures, and end-of-life pathways for transparent packaging formats.
Digital printing integration with thermoformed trays is migrating from premium cosmetic applications into mid-volume dairy and ready-meal segments. Brand owners in Germany and the United Kingdom are adopting plateless decoration to compress SKU-launch cycles from months to weeks. This shift is compressing minimum order quantities and enabling regionalized graphic versioning without cylinder inventory.
REACH restrictions on intentionally added microplastics are compelling film producers to reformulate slip and anti-fog additives. The European Chemicals Agency's 2023 guidance is driving substitution of conventional erucamide with bio-based alternatives in cast PP films. Food exporters to the EU are reformulating ahead of enforcement to avoid customs detention at Rotterdam and Hamburg.
Retailers are consolidating primary packaging specifications to simplify in-store recycling communication. Lidl and Aldi in Germany are pushing suppliers toward single-polymer tray-lid combinations, eliminating PS-PET laminations. This specification tightening is visible across Central European private-label supply chains and is propagating into co-packer qualification requirements.
Transparent Plastic Packaging Market Segmentation
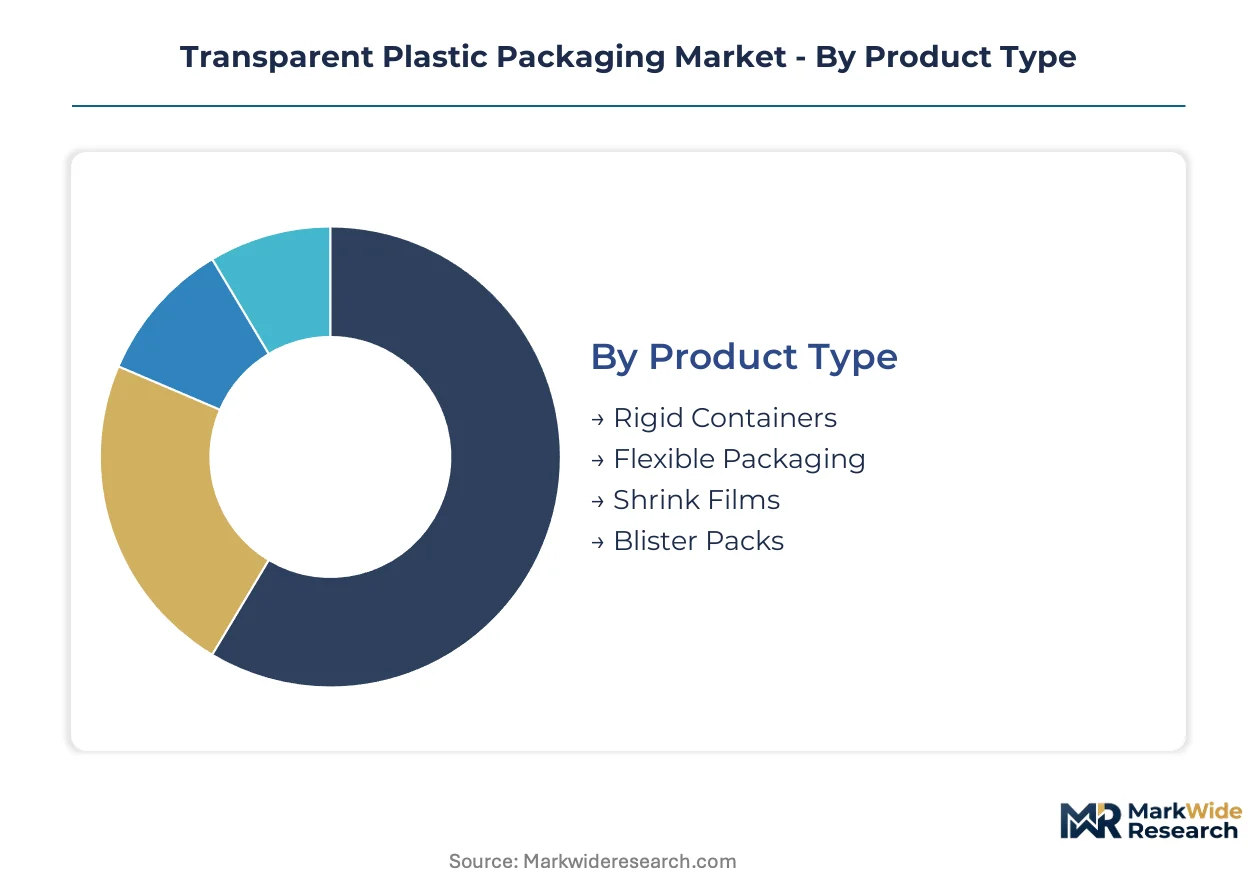
Transparent plastic packaging segments diverge sharply by performance requirements, regulatory exposure, and capital intensity. Understanding these divisions reveals where converter investments concentrate and which material-form combinations command pricing power.
Product Type:
Mature formats dominate volume throughput while emerging structures capture specification-driven premiums.
- Flexible Packaging:Cast and oriented films between 12-150 microns enable high-speed form-fill-seal operations for snack foods and fresh produce. Demand concentrates in Germany and the United States where retail consolidation favors lightweight, logistics-efficient formats over rigid alternatives.
- Shrink Films:Biaxially oriented polyolefin and PET-G films provide unitization and damage protection for e-commerce fulfillment. Third-party logistics operators in China are scaling procurement for automated packaging lines, though film gauge standardization remains unresolved across carrier specifications.
- Rigid Containers:Injection-stretch blow molded PET and thermoformed PP structures serve dairy, beverages, and ready-meals with dimensional stability requirements. Reclosability features and in-mold labeling compatibility sustain margin premiums against flexible alternatives.
- Blister Packs:Thermoformed PVC, PET, or PP cavities with lidding foil deliver tamper-evidence and unit-dose precision for pharmaceutical compliance. Clean-room manufacturing requirements and EMA serialization mandates create qualification barriers that protect specialized converters.
Flexible packaging retains volume leadership; shrink films hold the steepest expansion curve.
Material:
Cost tiers separate commodity resins from specification grades facing regulatory substitution pressure.
- Polyethylene:LDPE and LLDPE clarity grades dominate shrink film and flexible pouch applications through excellent processability and seal integrity. FDA food-contact notification pathways for post-consumer recycled PE remain underdeveloped, constraining closed-loop adoption.
- Polypropylene:Cast and oriented PP films offer moisture barrier and optical haze performance for fresh produce overwrap. ECHA microplastic restrictions are forcing reformulation of conventional slip additives ahead of enforcement timelines.
- Polyvinyl Chloride:Rigid PVC and PVDC coextrusions provide oxygen and moisture barriers for pharmaceutical blister and meat tray applications. REACH phthalate restrictions and EU Green Deal recyclability criteria are accelerating substitution toward PET and PP alternatives.
- Polystyrene:Crystal PS and oriented polystyrene sheet serve thermoformed trays and clamshells with high stiffness-to-weight ratios. German retailer consolidation toward mono-material specifications is displacing PS-PET laminations in private-label supply chains.
Polyethylene dominates raw material consumption; polypropylene faces the most acute regulatory-driven substitution pressure.
End User:
Application requirements dictate barrier specifications, sterilization compatibility, and labeling sophistication.
- Food & Beverage:Modified atmosphere packaging for proteins and high-clarity bottles for beverages drive rPET and bio-based polymer adoption. EU recycled-content mandates are compressing converter qualification timelines for food-grade decontamination processes.
- Pharmaceuticals:Blister packs, vials, and infusion containers demand USP Class VI compliance, child-resistant features, and EMA serialization integration. Track-and-trace mandates are displacing older push-through designs in regulated European markets.
- Personal Care:Cosmetic jars, tubes, and dispensing closures prioritize aesthetic clarity and chemical resistance to surfactants. Digital printing integration is compressing SKU-launch cycles for mid-volume regional brands.
- Household Products:Trigger sprayers, refill pouches, and cleaning wipe canisters emphasize chemical compatibility and child-safety mechanisms. Concentrate and refill formats are shifting volume from rigid bottles toward flexible structures.
Food & beverage commands the broadest material diversity; pharmaceuticals extract the highest specification premiums.
Form:
Supply chain configuration separates converter-controlled formats from brand-owner specified structures.
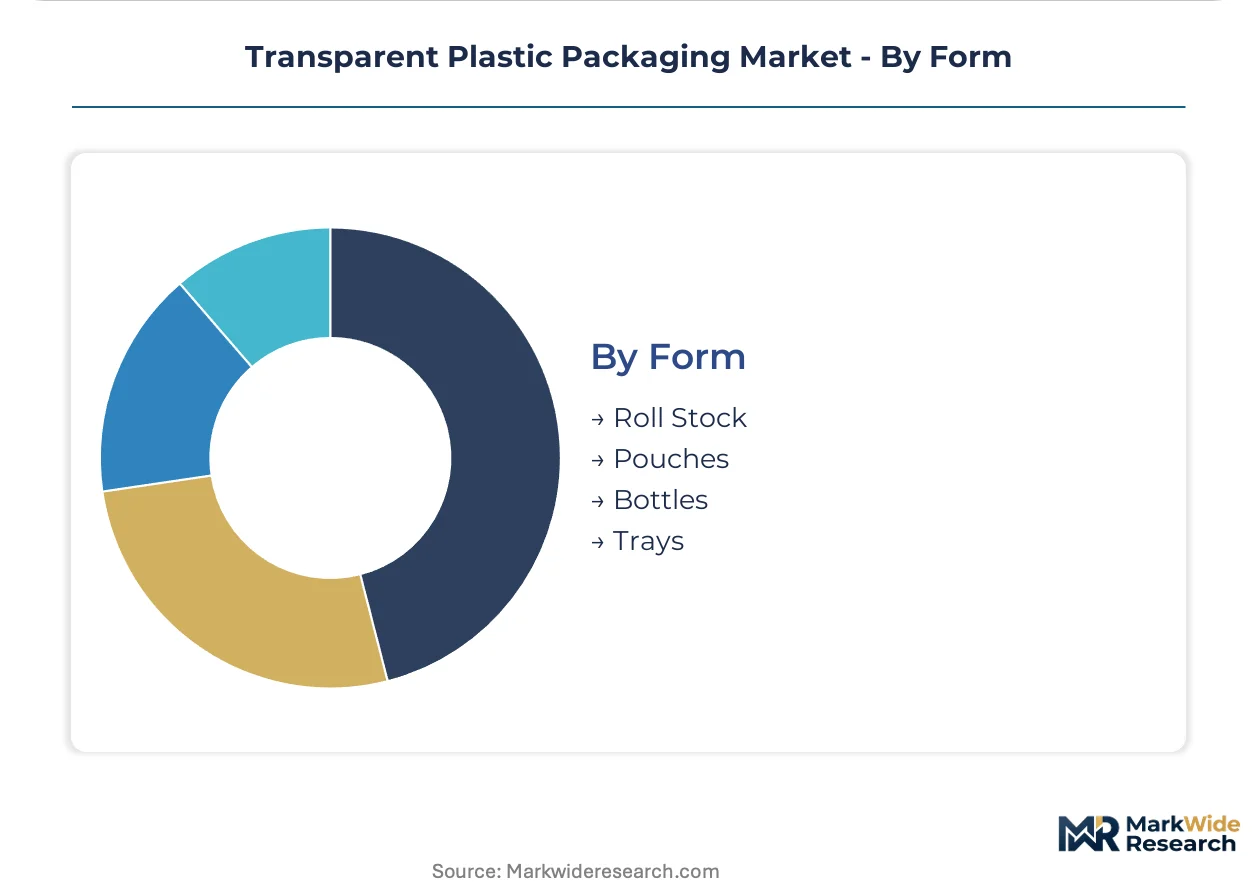
- Roll Stock:Unconverted film and sheet delivered to co-packers and brand-owner finishing operations enables graphic versioning flexibility. Digital printing adoption is narrowing minimum order quantities for mid-volume dairy and ready-meal applications.
- Pouches:Preformed or form-fill-seal flexible structures with spouts, zippers, or fitments serve snacks, pet food, and liquid concentrates. E-commerce damage reduction requirements are accelerating specification of puncture-resistant laminations.
- Bottles:Injection-stretch blow molded and extrusion blow molded containers for beverages, personal care, and pharmaceuticals. Deposit-return schemes in Germany and Scandinavia are building predictable post-consumer PET flows for food-grade recycling investments.
- Trays:Thermoformed PET, PP, and CPET structures for ready-meals, fresh produce, and medical devices. Retailer consolidation toward single-polymer tray-lid combinations is eliminating multi-material specifications across Central European supply chains.
Roll stock retains converter margin control; pouches are climbing the fastest on e-commerce logistics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Packaging and Packaging Waste Regulation is redirecting converter investments toward mono-material lines and food-grade recycling infrastructure across multiple jurisdictions. Germany's deposit-return schemes and China's dual carbon goals are creating divergent but equally consequential compliance environments for transparent packaging suppliers.
Germany
Deposit-return schemes for PET bottles generate predictable post-consumer feedstock flows that converters refine into food-grade rPET sheet. The country's national packaging regulator enforces strict mono-material specifications for private-label supply chains. Industrial clusters around Hamburg and Cologne host specialized decontamination and extrusion facilities serving Central European dairy and ready-meal brands.
China
E-commerce logistics operators in the Yangtze River Delta are scaling procurement of high-clarity shrink films for automated fulfillment lines. The State Administration for Market Regulation enforces GB standards for food-contact plastics that shape export compliance for Asian suppliers. Converter investments in Zhejiang and Jiangsu provinces concentrate on biaxially oriented polyolefin capacity for domestic and export markets.
United States
Food and beverage brands are advancing clear-format packaging specifications for shelf appeal and recyclability alignment with retailer sustainability commitments. The FDA governs food-contact notification pathways for virgin and recycled polymers used in transparent structures. Converter activity clusters in the Midwest and Southeast where dairy and ready-meal channels sustain rigid container demand.
India
Modern trade penetration in tier-two cities is creating first-mover openings for preformed tray and lidding film suppliers serving organized retail expansion. The Food Safety and Standards Authority of India regulates food-contact materials for domestic and export compliance. Industrial corridors in Maharashtra and Gujarat are attracting thermoforming and extrusion investments from domestic and multinational packaging groups.
Japan
Pharmaceutical serialization requirements are accelerating specification of tamper-evident blister formats with track-and-trace compatibility. The Pharmaceuticals and Medical Devices Agency mandates compliance packaging standards that displace older push-through designs. Manufacturing concentration in the Kanto and Kansai regions supports specialized clean-room operations for regional and export pharmaceutical supply.
Transparent Plastic Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around converters with integrated film manufacturing and global qualification capabilities. Tiered competitive dynamics separate multinational material-science conglomerates from regional specialists and equipment-leasing intermediaries. Three archetypes dominate: integrated resin-to-package conglomerates, specialized pharmaceutical-grade film producers, and asset-light contract converters. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with brand-owner sustainability programs.
Among integrated packaging conglomerates, Amcor and Berry Global exemplify scale-driven positions spanning flexible films and rigid containers across multiple end-use segments. Klöckner Pentaplast occupies a specialization tier focused on pharmaceutical-grade blister films with stringent clean-room manufacturing requirements. These three entities represent contrasting strategic postures—global supply assurance, North American channel control, and premium niche compliance—within a market where converter qualification timelines and regulatory navigation capabilities determine competitive viability.
| Leading Market Players |
|---|
| SABIC |
| Constantia Flexibles |
| Amcor |
| Toyobo Packaging |
| Klöckner Pentaplast |
| Berry Global |
| Huhtamaki |
| BASF |
| Sealed Air Corporation |
| Others |
Value Network & Pricing Analysis
Feedstock volatility in purified terephthalic acid and ethylene glycol compresses margin predictability while simultaneously widening pricing tier spreads between integrated resin producers and toll-converting operations, forcing supply chain participants toward long-term offtake contracts or backward integration into compounding capabilities.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade blister films and commodity flexible packaging, with USP Class VI compliance and EMA serialization readiness commanding substantial premiums over standard food-contact grades. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation in barrier performance, optical haze specifications, and clean-room manufacturing investment. Cost compression in standard-grade flexible films is intensifying because of rPET feedstock competition from beverage bottle applications. Brand-owner sustainability programs exhibit the lowest price sensitivity, while private-label dairy and ready-meal channels remain most responsive to unit cost fluctuations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic planning for biaxially oriented polyolefin capacity investments, redirecting procurement toward Southeast Asian film extrusion alternatives. Manufacturing concentrates in Germany, China, and the United States, with industrial clusters around Hamburg, the Yangtze River Delta, and the American Midwest anchoring converter activity. Raw material sourcing draws from Saudi Arabian and Asian purified terephthalic acid producers, European ethylene glycol suppliers, and regional rPET reclaimers. Single-source vulnerability in pharmaceutical-grade PVC resin creates qualification bottlenecks for blister pack manufacturers. Distribution runs through converter-controlled roll stock channels for flexible formats and brand-owner direct procurement for rigid containers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as EU Packaging and Packaging Waste Regulation compliance deadlines force replacement demand for multi-layer legacy structures, compressing converter qualification timelines and accelerating capital deployment into mono-material lines.
For Market Incumbents: Pre-empt substitution pressure from bio-based PLA and PHA clarity grades by accelerating in-house production of food-grade rPET sheet capacity in Germany and the United States. Secure backward integration into post-consumer bottle collection infrastructure through partnerships with deposit-return scheme operators, defending margin position against toll-converting competitors exposed to feedstock volatility.
For New Entrants and Emerging Players: India's tier-two city organized retail expansion represents the most penetrable entry point for preformed tray and lidding film suppliers, with Maharashtra and Gujarat industrial corridors offering favorable investment conditions. Mid-volume dairy and ready-meal segments in Central Europe present secondary white-space opportunity given incumbent focus on multinational brand-owner contracts. Digital printing integration for plateless decoration offers a differentiated go-to-market angle compressing SKU-launch cycles.
For Investors and Strategic Acquirers: Specialized pharmaceutical-grade film producers with EMA serialization capabilities and clean-room manufacturing assets offer the strongest long-term viability through the projection horizon, given regulatory qualification barriers and displacement of older push-through blister designs. Monitor FDA food-contact notification clearance timelines for novel recycled-content resins as the critical inflection indicator for rPET capacity investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Food-Grade rPET Capacity Expansion | EU recycled-content mandates accelerate converter investment in decontamination and extrusion lines serving dairy brands. |
| Mono-Material Line Conversion | Redesign of multi-layer structures into single-polymer formats responds to German retailer specification tightening. |
| Digital Printing Integration | Plateless decoration adoption compresses minimum order quantities for mid-volume regional brand owners. |
| Deposit-Return Scheme Partnership | Predictable post-consumer PET flows from German and Scandinavian markets secure closed-loop feedstock supply. |
| Bio-Based Polymer Qualification | PLA and PHA clarity grade development targets fresh produce overwrap applications approaching optical haze thresholds. |
Research Methodology
A standing panel of extrusion operations managers, brand-owner packaging engineers, food-contact regulatory consultants, and pharmaceutical compliance officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from FDA food-contact notification databases, ECHA REACH guidance documents, EU Packaging and Packaging Waste Regulation impact assessments, and customs trade flow data. Bottom-up capacity and demand modeling triangulated against top-down market sizing from resin consumption patterns and converter equipment installation records.
Scenario-bracketing framed the analytical approach, with baseline, accelerated regulatory compliance, and delayed infrastructure investment cases tested across the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-use application, and regional regulatory cluster. CAGRs derived from annualized growth rate calculations applied to volume and value baselines, incorporating industry-specific inputs such as rPET decontamination line commissioning schedules and e-commerce logistics procurement trends.
Macroeconomic conditions sit as an overlay; deviation in energy costs, resin feedstock pricing, or currency exchange rates would shift the trajectory of converter investment decisions and brand-owner specification timelines. Forecasts reflect assumptions regarding regulatory enforcement consistency, collection infrastructure development, and bio-based polymer technical maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Plastic Bottle Recycling Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Compostable Plastic Packaging Material Market
Plastic Packaging
Plastic Cutlery Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
Global Returnable Plastic Crates Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Polyethylene Mailers Market