
 North America Rigid Bulk Packaging Market | 2026-2036
North America Rigid Bulk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rigid Bulk Packaging Market Insights
Skilled blow-molding technicians and rotational-molding specialists are redrawing competitive boundaries across the North America Rigid Bulk Packaging Market. Mauser Packaging Solutions leverages captive reconditioning networks to sustain circular-economy service revenues. Greif Inc. anchors North American drum supply through integrated steel and plastic production lines. ORBIS Corporation differentiates via reusable bulk container programs that reduce per-trip packaging costs for automotive and food processors.
Rigid bulk packaging encompasses high-capacity, structurally reinforced containers—typically 55-gallon drums, intermediate bulk containers exceeding 1,000 liters, and bulk bins fabricated from high-density polyethylene, cold-rolled steel, or fiber-reinforced composites—engineered to withstand stacking loads, forklift impact, and chemical exposure during intermodal transit. Plastic drums lead material demand due to corrosion resistance and lightweight handling economics, while metal pails retain share in solvent and flammable liquid applications where UN DOT certification governs market access. Composite crates represent the fastest-expanding segment as agricultural exporters adopt collapsible, returnable systems to cut single-use fiberboard expenditure.
EPA hazardous waste manifest requirements, DOT 49 CFR hazardous materials regulations, and FDA 21 CFR food-contact substance provisions collectively shape product design, material selection, and labeling protocols across the value chain. OSHA workplace safety standards further constrain drum handling equipment specifications, pushing distributors toward ergonomic, stack-optimized geometries. Stakeholders must monitor evolving state-level extended producer responsibility legislation in California and New York, as these frameworks threaten to impose cradle-to-grave tracking obligations that would restructure collection and reconditioning economics.
Market Dynamics
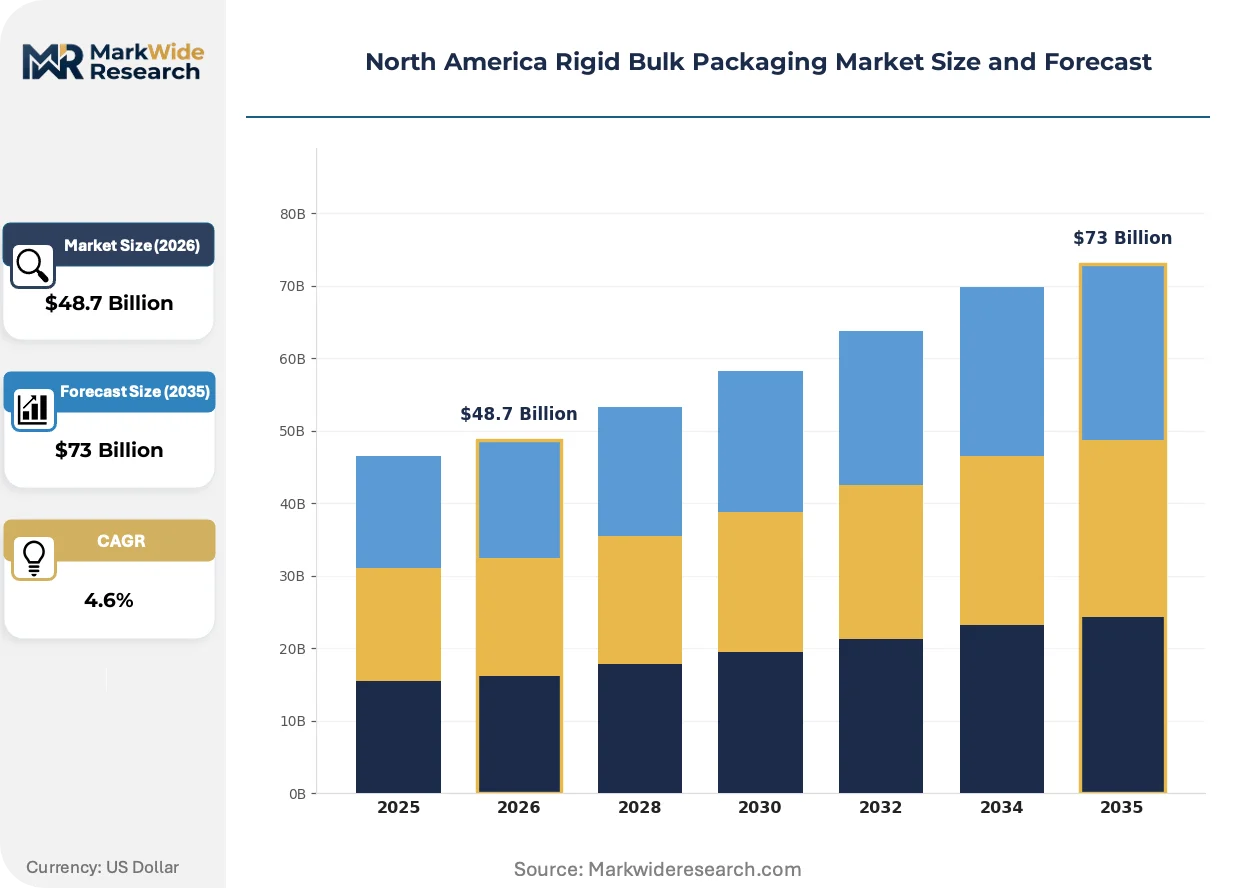
EPA hazardous waste manifest mandates and DOT 49 CFR certification requirements are forcing Gulf Coast petrochemical processors to replace non-compliant container fleets, creating immediate replacement demand for UN-certified intermediate bulk containers and steel drums.
Growth Catalysts
- EPA hazardous material handling mandates:Gulf Coast chemical processors must upgrade to UN-certified intermediate bulk containers for cross-border export compliance.
- Texas-Louisiana petrochemical corridor expansion:Export-oriented producers require certified packaging for international shipment volumes.
- High-density polyethylene drum adoption:Corrosion resistance and lightweight handling economics displace legacy steel in non-flammable liquid applications.
Market Restraints
- Steel scrap price volatility:Cold-rolled steel drum production faces margin compression from fluctuating raw material input costs.
- HDPE resin supply concentration:Gulf Coast petrochemical feedstock disruptions create regional packaging material shortages.
- Flammable liquid metal pail retention:UN DOT certification requirements prevent plastic substitution in solvent handling applications.
Strategic Opportunities
- California extended producer responsibility legislation:Cradle-to-grave tracking obligations create reconditioning and circular-economy service revenue streams.
- Agricultural collapsible composite crates:Returnable systems cut single-use fiberboard expenditure for produce exporters.
- FDA 21 CFR food-contact compliance:Food processors seek certified bulk bins for ingredient handling and storage.
Industry Challenges
- Blow-molding technician scarcity:Specialized rotational-molding expertise concentrates among legacy operators, constraining capacity expansion.
- OSHA ergonomic drum handling specifications:Stack-optimized geometry redesigns require capital investment in mold retooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rigid Bulk Packaging Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Containers, Pails, Crates Material: Plastic, Metal, Glass, Composite End User: Food & Beverage, Chemicals, Pharmaceuticals, Agriculture Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | U.S. Coexcell Inc., Mauser Packaging Solutions, ORBIS Corporation, Steel King Industries Inc., Myers Container, Greif Inc., BASCO, Inc., Containers Plus, Mondi PLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rigid Bulk Packaging Market Trends and Innovations
Material substitution, regulatory compliance automation, and circular-economy service models are compressing traditional product lifecycles and reshaping competitive positioning across container categories.
Composite fiber-reinforced bulk bins are fragmenting the agricultural export packaging segment. These collapsible, returnable systems eliminate single-use fiberboard expenditure for produce shippers. California and Florida agricultural exporters are adopting at accelerated pace. The technology is fragmenting demand away from corrugated bulk containers toward reusable asset pools.
DOT 49 CFR hazardous materials regulations are tightening certification timelines for cross-border shipments. Mexican and Canadian border facilities now require manifest-compatible container tracking. Texas and Louisiana petrochemical exporters are consolidating supplier relationships to ensure compliance continuity.
Reusable bulk container pooling programs are compressing per-trip packaging costs for automotive and food processors. Leasing models displace capital-intensive container ownership. The shift concentrates procurement authority among national account managers at OEM assembly plants.
North America Rigid Bulk Packaging Market Segmentation
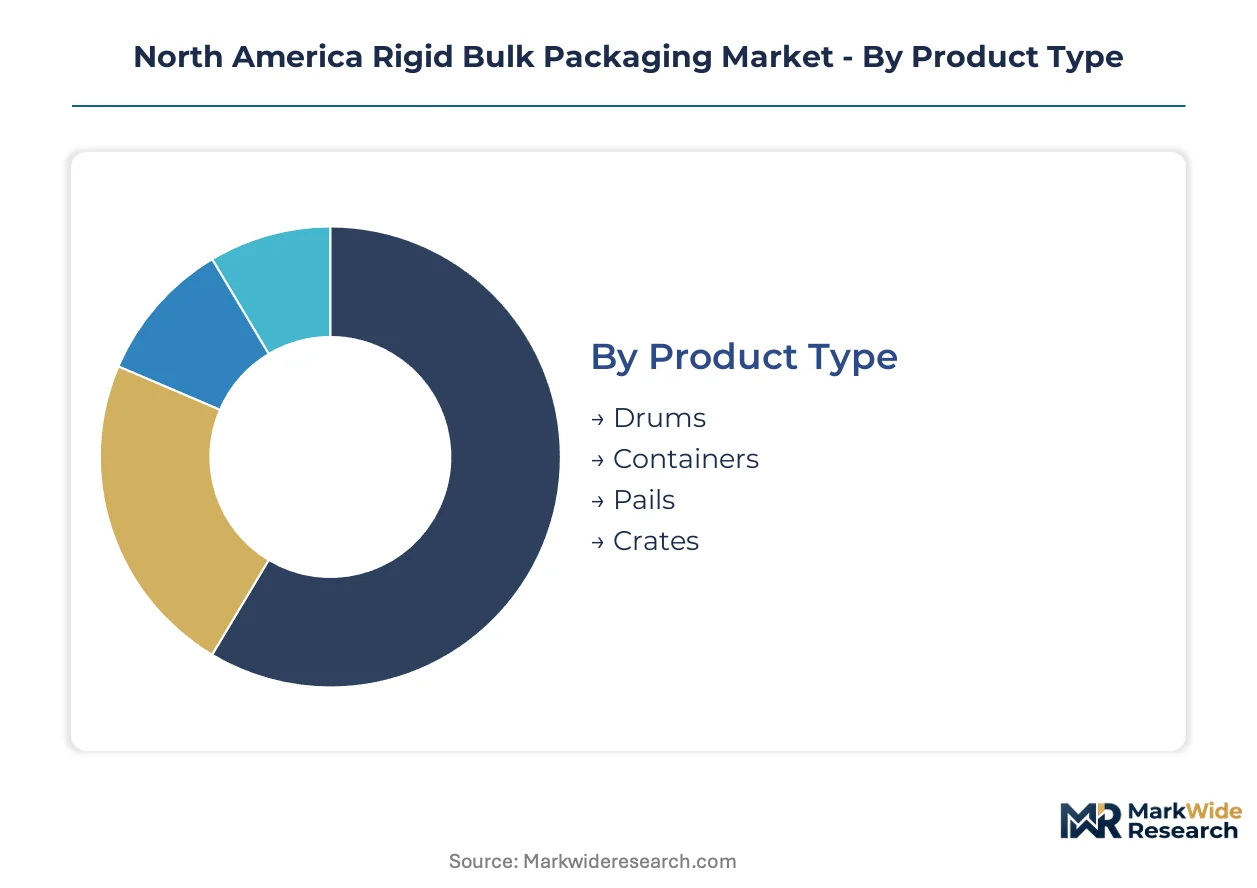
EPA hazardous waste manifest requirements and DOT 49 CFR certification protocols create divergent compliance burdens across container categories. Material selection and distribution channel access vary sharply by end-use regulatory exposure.
Product Type:
Regulatory certification tiers separate commodity drums from specialized intermediate bulk containers in hazardous material applications.
- Drums:Standard 55-gallon steel and high-density polyethylene vessels dominate chemical and petroleum logistics. Gulf Coast petrochemical corridors drive replacement demand as EPA mandates force fleet upgrades to UN-certified specifications.
- Containers:Intermediate bulk containers exceeding 1,000 liters command premium positioning in cross-border chemical shipments. Texas and Louisiana export-oriented producers require DOT-compatible tracking systems for Mexican and Canadian border crossings.
- Pails:Smaller-capacity metal vessels retain mandatory share in solvent and flammable liquid handling where UN DOT certification prohibits plastic substitution.
- Crates:Collapsible fiber-reinforced systems penetrate agricultural export channels through returnable pooling economics.
Established volume favors Drums; emerging adoption favors Containers.
Material:
Cost-to-weight ratios and corrosion resistance profiles determine substitution patterns across end-use applications.
- Plastic:High-density polyethylene formulations displace legacy steel in non-flammable liquid applications through lightweight handling economics and chemical resistance. Food and beverage processors favor FDA 21 CFR-compliant resin grades for ingredient storage.
- Metal:Cold-rolled steel retains dominance in hazardous waste and flammable solvent containment where structural integrity under thermal stress governs specification. Scrap price volatility compresses drum manufacturing margins.
- Glass:Limited pharmaceutical and specialty chemical niche where inert surface properties outweigh fragility constraints.
- Composite:Fiber-reinforced bulk bins expand fastest in California and Florida agricultural export corridors through collapsible, returnable system economics.
Plastic captures volume leadership; Composite climbs the fastest on agricultural pooling demand.
End User:
Customer procurement authority concentrates among national account managers at volume-intensive processing facilities.
- Food & Beverage:FDA 21 CFR food-contact substance compliance drives bulk bin specification for ingredient handling and storage. Major processors consolidate supplier relationships to ensure audit continuity.
- Chemicals:Gulf Coast petrochemical producers generate concentrated demand for UN-certified intermediate bulk containers and steel drums under EPA hazardous waste manifest mandates.
- Pharmaceuticals:Stringent container closure integrity requirements favor specialized drum and pail configurations with documented supply chain traceability.
- Agriculture:California and Florida produce exporters adopt collapsible composite crates to eliminate single-use fiberboard expenditure in cross-country and export shipments.
Chemicals anchor procurement volume; Agriculture offers the steepest expansion trajectory on returnable system adoption.
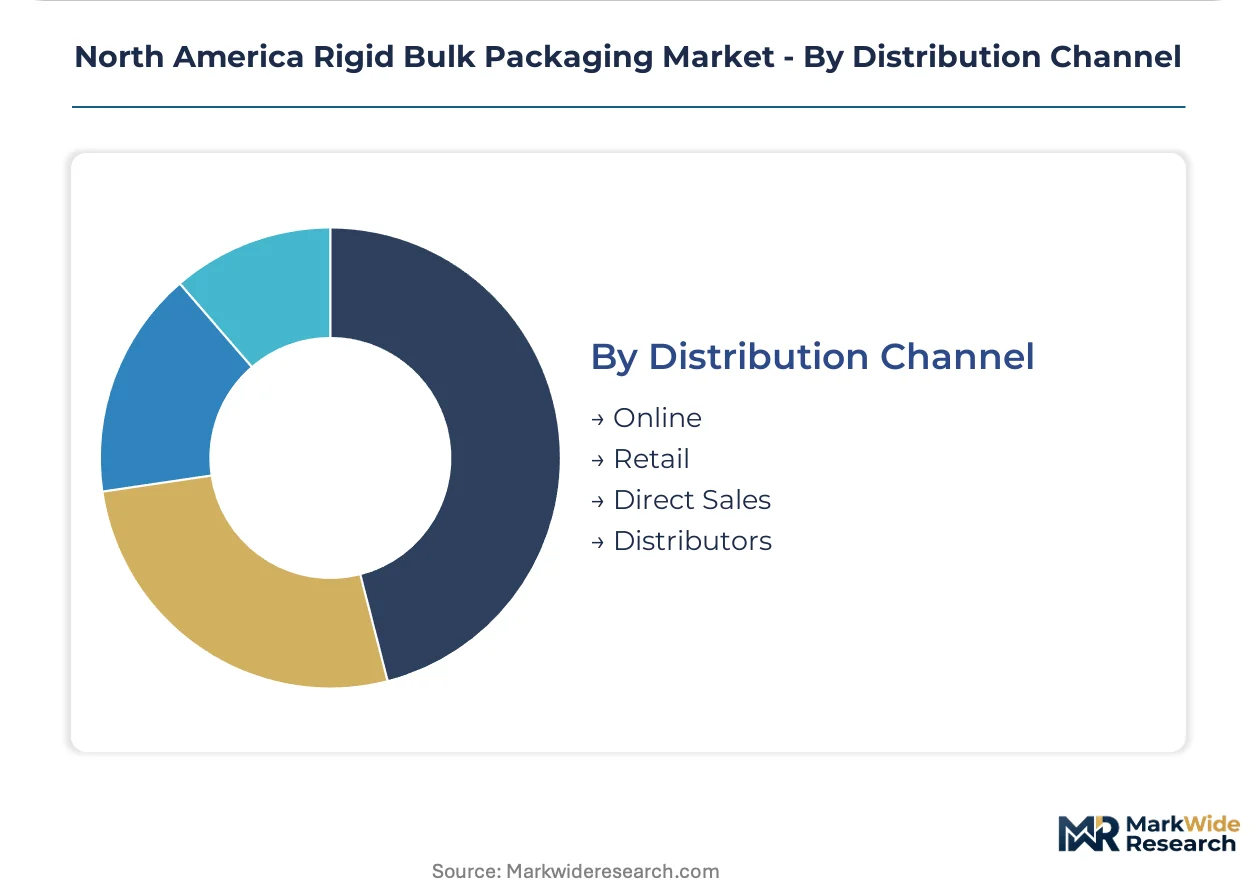
Distribution Channel:
Channel selection reflects container standardization versus customization requirements and replenishment velocity.
- Online:Standardized drum and pail specifications move through digital procurement platforms serving mid-tier chemical and food processors with predictable demand patterns.
- Retail:Limited to small-volume pail and drum sales for maintenance chemicals and specialty lubricants through industrial supply chains.
- Direct Sales:National account relationships dominate intermediate bulk container and reusable bulk bin leasing programs for automotive and food processing OEMs.
- Distributors:Regional stocking locations service Gulf Coast petrochemical corridors with rapid-turn drum and container replenishment under just-in-time logistics contracts.
Direct Sales concentrates high-value contracts; Distributors capture frequency-driven replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA hazardous waste manifest mandates anchor demand concentration across North America. Texas and Louisiana petrochemical corridors generate replacement cycles for UN-certified intermediate bulk containers. Cross-border export compliance requirements reshape procurement patterns from Canadian oil sands to Mexican maquiladora districts.
United States
Gulf Coast chemical processors and California agricultural exporters drive divergent container specifications. EPA hazardous material handling mandates force fleet upgrades to DOT 49 CFR-certified intermediate bulk containers in Texas and Louisiana corridors. FDA 21 CFR food-contact compliance shapes bulk bin demand among Midwest food processors clustered around Chicago and Minneapolis.
Canada
Alberta oil sands producers and Ontario automotive parts manufacturers sustain drum and reusable container demand. Health Canada and PMRA chemical handling guidelines align with EPA cross-border shipment protocols. Toronto-Windsor manufacturing corridor concentrates just-in-time packaging procurement for integrated North American supply chains.
Mexico
Maquiladora assembly plants in Nuevo León and Baja California generate reusable bulk container pooling demand. PROFEPA hazardous waste regulations and SEMARNAT environmental standards tighten container traceability requirements. Mexico City industrial belt sustains steel drum consumption for petroleum derivatives and solvent distribution.
North America Rigid Bulk Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in North America rigid bulk packaging. Mauser Packaging Solutions and Greif Inc. anchor the upper tier through captive reconditioning networks and integrated steel-plastic production lines. Mid-cap specialists concentrate in regional drum fabrication and agricultural crate pooling. Competitive moves center on circular-economy service expansion and ergonomic geometry redesigns for OSHA compliance.
Within the integrated reconditioning tier, Mauser Packaging Solutions and Greif Inc. represent asset-heavy models that combine manufacturing with closed-loop collection systems. ORBIS Corporation exemplifies the reusable pooling archetype through bulk container programs that compress per-trip costs for automotive and food processors. These three entities anchor distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| U.S. Coexcell Inc. |
| Mauser Packaging Solutions |
| ORBIS Corporation |
| Steel King Industries Inc. |
| Myers Container |
| Greif Inc. |
| BASCO, Inc. |
| Containers Plus |
| Mondi PLC |
| Others |
Pricing and Supply Chain Analysis
Sixty-day HDPE resin inventory cycles at Gulf Coast converters anchor pricing power for rotational-molding specialists while exposing drum fabricators to petrochemical feedstock volatility. This lead-time band concentrates procurement leverage among integrated producers with captive resin supply, compressing margins for independent molders reliant on spot market purchases.
Pricing Analysis
Texas-Louisiana corridor pricing diverges from Midwest food-grade premiums by fifteen to twenty points on UN-certified intermediate bulk containers. Three-tier pricing structure across premium UN-certified, standard industrial-grade, and economy non-certified levels separates chemical processors by compliance exposure. Cost compression in steel drum fabrication is intensifying because cold-rolled scrap volatility erodes fixed-contract margins. National account managers at Gulf Coast petrochemical clusters demonstrate lowest price sensitivity due to regulatory non-compliance penalties; independent agricultural distributors exhibit highest sensitivity to per-unit freight differentials.
Supply Chain Analysis
Houston Ship Channel congestion periodically chokes resin delivery schedules for rotational-molding plants serving automotive and food processing OEMs. Manufacturing gravity centers on Texas, Louisiana, and Ohio where blow-molding capacity clusters near downstream chemical and food processing demand. Raw material flows draw from Gulf Coast ethylene crackers, Great Lakes steel mills, and recycled HDPE pellet processors. Single-source vulnerability concentrates in specialty resin grades for FDA 21 CFR food-contact certification. Distribution runs through regional stocking locations in Chicago, Dallas, and Toronto servicing just-in-time replenishment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California extended producer responsibility mandates are disrupting traditional container ownership models, creating circular-economy service revenue pools that favor asset-heavy operators with reconditioning infrastructure.
For Market Incumbents: Consolidate reconditioning network density in California and New York corridors ahead of cradle-to-grave tracking mandate implementation. Acquire rotational-molding specialists in the Great Lakes region to capture automotive OEM reusable container pooling contracts. Vertical integration into HDPE resin compounding buffers margin compression from Gulf Coast feedstock volatility. For New Entrants and Emerging Players: Anchor in collapsible composite crate pooling for California and Florida agricultural exporters where returnable system economics displace single-use fiberboard. Target mid-tier chemical distributors in the Ohio River Valley lacking UN-certified container sourcing relationships. Pursue direct sales models emphasizing per-trip cost reduction metrics against capital-intensive ownership alternatives. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because regulatory tailwinds in extended producer responsibility jurisdictions restructure collection and reconditioning economics toward asset-heavy operators. Prioritize targets with integrated reconditioning networks and FDA or UN certification portfolios. Watch for EPA hazardous waste manifest enforcement acceleration as inflection signal for replacement demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Reconditioning Network Expansion | Captures California EPR-mandated container return flows ahead of competitor infrastructure deployment. |
| Backward Integration into Resin Compounding | Secures FDA 21 CFR food-contact grade supply for Midwest dairy and ingredient processors. |
| Reusable Container Pooling Platform | Compresses per-trip packaging costs for Detroit automotive assembly plants below ownership economics. |
| Ergonomic Geometry Redesign | Aligns drum specifications with OSHA stack-optimized handling mandates for chemical distributor compliance. |
| Cross-Border Certification Harmonization | Enables Texas petrochemical exporters to satisfy DOT 49 CFR and PROFEPA tracking requirements simultaneously. |
Research Methodology
Initial hypotheses were tested against primary input from blow-molding plant managers, chemical procurement leads at Gulf Coast petrochemical facilities, automotive packaging engineers, and agricultural distributor operations heads and refined through secondary validation against ACC industry statistics, EPA enforcement action databases, SEC 10-K filings from integrated packaging producers, and Canadian customs trade records. Bottom-up capacity modeling and top-down demand segmentation were triangulated to resolve variance in regional replacement cycle assumptions.
Variance decomposition across product type, material formulation, end-use regulatory exposure, and distribution channel structure informed the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by price-band mix. Forecast inputs incorporated HDPE resin price band movements, EPA enforcement priority shifts, and automotive production cluster location decisions.
Decision-makers should treat outputs as directional under stable regulatory enforcement intensity and resin supply continuity assumptions; material deviation in Gulf Coast petrochemical feedstock availability or accelerated EPR mandate expansion would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
GCC Rigid Plastic Packaging Market