
 India Rigid Plastic Packaging Market | 2026-2036
India Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Rigid Plastic Packaging Market Foresight
Maharashtra is fragmenting rigid plastic packaging capacity as Mumbai-Pune belt converters add blow-molding and injection-stretch lines to serve western India FMCG demand. Mold-Tek Packaging Limited leverages its decorated in-mold labeling capabilities to anchor premium personal care contracts. Manjushree Technopack Limited sustains one of India's largest PET preform and bottle manufacturing footprints. Amcor Rigid Plastics India Private Limited competes through multinational technical standards and food-contact compliance systems.
India rigid plastic packaging comprises thermoformed or molded polymer structures—typically polyethylene terephthalate, high-density polyethylene, or polypropylene—fabricated through extrusion blow molding, injection molding, or thermoforming processes to provide dimensional stability, moisture barriers, and shelf visibility for consumer and industrial goods. Bottles dominate volume throughput in edible oils and carbonated soft drinks where lightweighting and clarity standards matter. Containers capture expanding share in pharmaceuticals and household chemicals where child-resistant closures and chemical compatibility requirements create specification barriers. Polypropylene grades are displacing polystyrene in dairy cups as microwaveability and recycling code advantages reshape material selection.
BIS certification requirements and FSSAI food-contact safety standards govern raw material approval and migration testing protocols for domestic rigid packaging. The Plastic Waste Management Rules enforce extended producer responsibility, pushing converters toward recycled content verification and design-for-recycling formats. India's PLI scheme for specialty chemicals indirectly supports domestic polymer additive and masterbatch capacity. Stakeholders must monitor how state-level plastic ban implementations and EPR compliance deadlines alter specification roadmaps and capital allocation priorities.
Market Dynamics
Extended producer responsibility mandates under India's Plastic Waste Management Rules are forcing converters to redesign formats for recyclability while simultaneously certifying recycled content claims, compressing margin structures across Maharashtra and Gujarat processing clusters.
Growth Catalysts
- FSSAI food-contact safety standards:Migration testing protocols for PET and HDPE bottles are tightening quality benchmarks, locking in compliant converters with dairy and edible oil manufacturers seeking supply security.
- Maharashtra polymer processing concentration:Mumbai-Pune belt blow-molding capacity expansion is shortening logistics loops for western India FMCG distribution, reducing working capital cycles for brand owners.
- Polypropylene microwaveable dairy cups:Material substitution from polystyrene is accelerating as recycling code advantages and heat resistance specifications align with modern retail shelf requirements.
Market Restraints
- Crude-linked resin volatility:PET and polypropylene pricing swings tied to naphtha and propylene feedstock costs are compressing converter margins and complicating annual contract negotiations with food manufacturers.
- Domestic virgin polymer supply concentration:Reliance Industries and Indian Oil Corporation control the majority of domestic PET resin and polypropylene output, creating procurement leverage asymmetries for mid-scale packaging converters.
- Mechanical recycling quality degradation:rPET flake contamination rates and IV drop during reprocessing are limiting food-grade closed-loop applications to non-contact layers or secondary packaging.
Strategic Opportunities
- Karnataka-Tamil Nadu corridor underpenetration:Southern India dairy and beverage filling capacity is expanding faster than local rigid packaging supply, creating white space for converters with BIS-certified operations.
- Pharmaceutical child-resistant closure demand:CDSCO packaging integrity requirements for oral solid dosages are opening specification-driven contracts for converters with injection-molding and assembly capabilities.
- PLI scheme for specialty chemicals:Domestic masterbatch and additive capacity expansion is reducing import dependence for UV stabilizers and oxygen scavengers used in barrier PET bottles.
Industry Challenges
- BIS certification timeline compression:Raw material approval and migration testing protocols are extending new product qualification cycles, delaying contract awards for converters without pre-approved polymer grades.
- Multi-layer barrier structure delamination:EPR compliance is forcing design-for-recycling simplification that conflicts with oxygen and moisture barrier performance requirements in edible oil and pharmaceutical applications.
- Skilled blow-molding technician scarcity:Process optimization for lightweighting and in-mold labeling defect reduction requires specialized training that outpaces vocational institute output in Gujarat and Maharashtra.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Rigid Plastic Packaging Market |
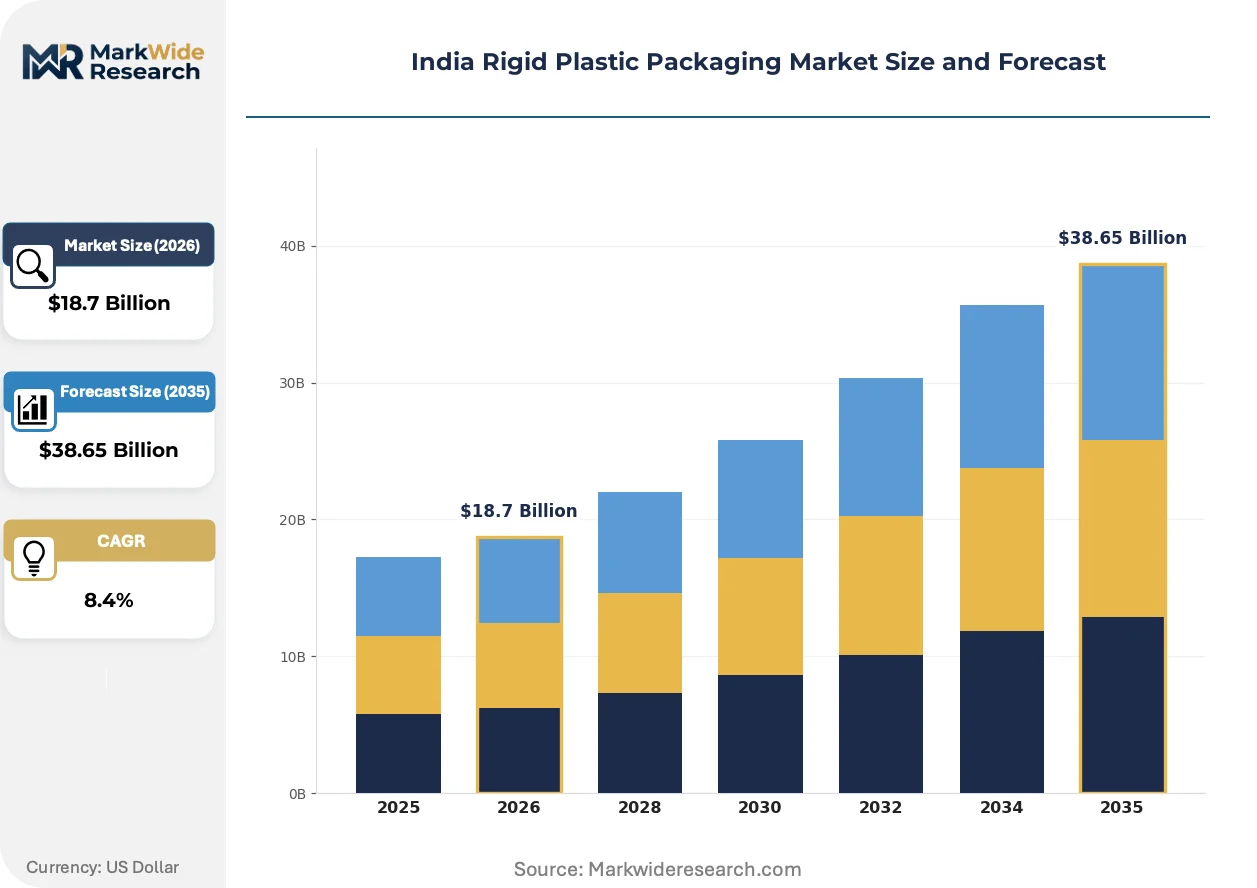
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Cups End Use Industry: Food & Beverage, Personal Care, Household, Pharmaceuticals Material: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Distribution Channel: Online Retail, Direct Sales, Wholesale, Convenience Stores |
| Companies Covered | Pyramid Technoplast Pvt Ltd, Hitech Corporation Limited, Mold-Tek Packaging Limited, Parekhplast India Limited, Pearl Polymers Limited, Manjushree Technopack Limited, Chemco Group, Amcor Rigid Plastics India Private Limited, Essel Propack (EPL Limited), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Rigid Plastic Packaging Market Shifts & Advancements
Material science advances and regulatory compliance automation are converging to reshape converter capabilities, with digital traceability and mono-material formats emerging as competitive differentiators in contract negotiations.
Barrier coating technologies for PET bottles are migrating from multi-layer co-injection structures to plasma-enhanced chemical vapor deposition and silicon oxide coatings. Edible oil and carbonated soft drink manufacturers are piloting these formats to meet EPR mono-material mandates without sacrificing shelf-life performance. The shift is compressing demand for EVOH and nylon oxygen barrier layers while expanding coating equipment supplier relationships.
India's Plastic Waste Management Rules enforcement is tightening EPR compliance verification through centralized plastic waste tracking portals. Converters must now document recycled content percentages and end-of-life collection partnerships to maintain brand owner contracts. The pharmaceutical and personal care segments are responding fastest, mandating design-for-recycling audits in supplier scorecards ahead of FMCG categories.
Brand owner consolidation of blow-molded bottle procurement is compressing supplier bases and extending contract durations. Large dairy and edible oil processors are reducing vendor counts from regional fragmentation to two-three national converters with multi-location BIS-certified capacity. Karnataka and Tamil Nadu filling operations are most visible in this shift, leveraging scale negotiations against Maharashtra and Gujarat incumbent suppliers.
India Rigid Plastic Packaging Market Segmentation
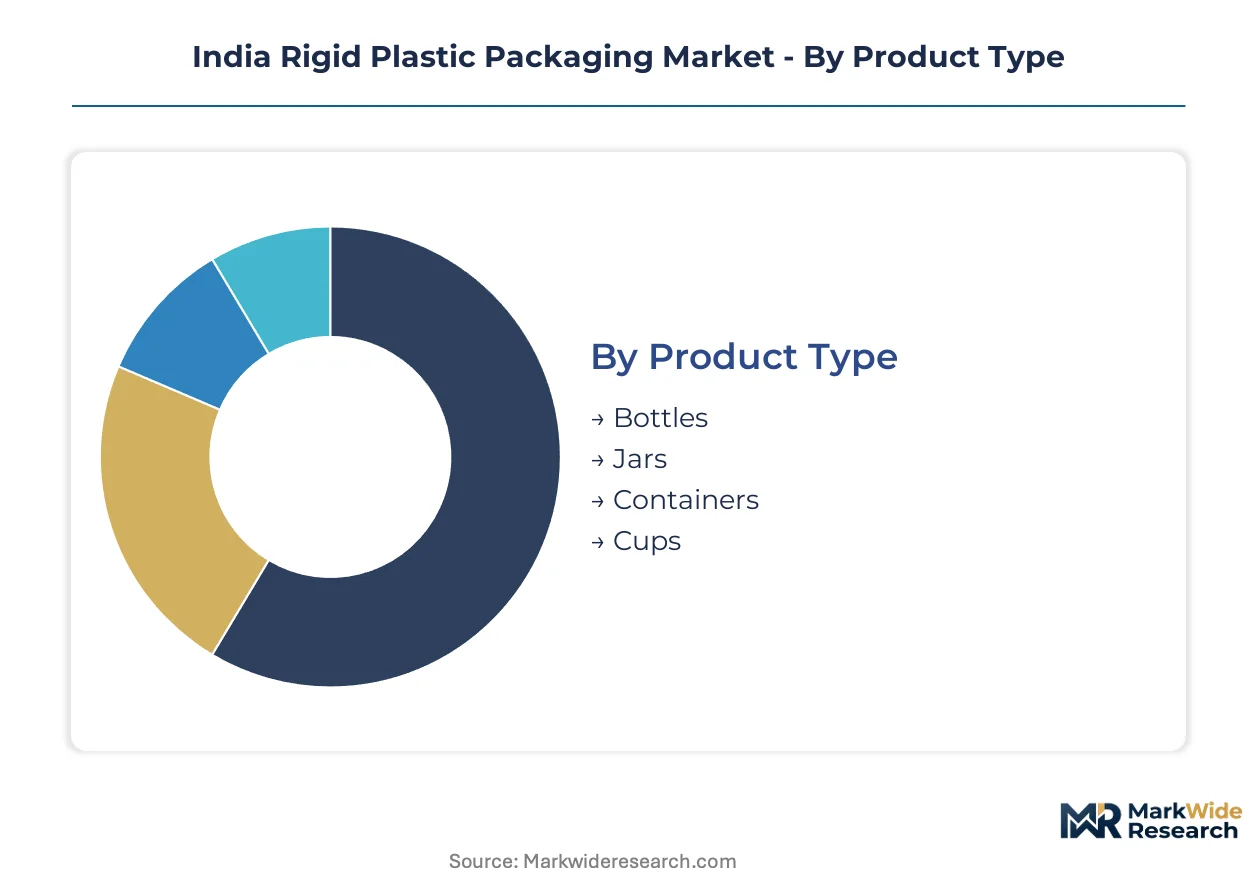
Segmentation in India's rigid plastic packaging market reveals how converter capabilities align with diverging technical requirements across food-contact safety tiers, barrier performance specifications, and channel-specific volume patterns. Understanding these divisions exposes where capital equipment investments and BIS certification priorities concentrate.
Product Type:
Application-driven format requirements split converter specialization between high-volume blow-molding operations and precision injection-molding lines serving distinct shelf-preservation and handling specifications.
- Bottles:Extrusion and injection-stretch blow-molded structures in PET and HDPE dominate edible oil and carbonated soft drink distribution where lightweighting targets and clarity standards dictate resin selection. Maharashtra and Gujarat converters anchor national supply for dairy and beverage brand owners seeking BIS-certified food-contact compliance.
- Containers:Rectangular and cylindrical molded formats with integrated handles or stacking features capture pharmaceuticals and household chemicals where child-resistant closure compatibility and chemical resistance specifications create qualification barriers. Karnataka filling operations are expanding procurement of HDPE containers for agrochemical and cleaning product distribution.
- Jars:Wide-mouth injection-molded formats serve confectionery and spice packaging with tamper-evident closure systems.
- Cups:Thermoformed polystyrene and polypropylene formats address dairy and ready-to-eat meal segments where microwaveability requirements are accelerating material substitution.
Bottles hold installed capacity. Containers is rotating up the share rankings.
End Use Industry:
Customer segment purchasing power and regulatory exposure determine converter margin structures and certification investment thresholds.
- Food & Beverage:Dairy processors and edible oil refiners drive the largest volume throughput with FSSAI migration testing mandates and extended shelf-life barrier requirements. Maharashtra-based converters with multi-location BIS certification are consolidating procurement relationships with national dairy cooperatives.
- Pharmaceuticals:Oral solid dosage and liquid formulation packaging demands CDSCO-compliant child-resistant closures, oxygen barrier performance, and serialization-ready surface specifications. Injection-molding converters with cleanroom capabilities and assembly integration are capturing specification-driven contracts.
- Personal Care:Decorated bottles and jars for shampoo and skincare applications prioritize in-mold labeling and premium surface aesthetics.
- Household:Detergent and disinfectant containers emphasize chemical compatibility and cost-optimized HDPE grades.
Food & Beverage commands volume concentration. Pharmaceuticals is climbing the fastest on value per kilogram metrics.
Material:
Polymer selection tradeoffs between barrier performance, recyclability credentials, and feedstock cost volatility define converter procurement strategies and customer specification negotiations.
- Polyethylene:HDPE grades dominate chemical and dairy applications with excellent moisture barrier properties and established mechanical recycling streams. Reliance Industries and Indian Oil Corporation virgin resin supply concentration creates procurement leverage asymmetries for mid-scale converters.
- Polypropylene:Homopolymer and random copolymer grades are displacing polystyrene in microwaveable dairy cups and expanding in pharmaceutical closures where heat resistance and recycling code advantages align with EPR compliance pressures.
- Polystyrene:General-purpose and high-impact grades retain position in cost-sensitive disposable cup applications.
- Polyvinyl Chloride:Rigid PVC maintains niche presence in pharmaceutical blister packs and specific chemical compatibility requirements.
Polyethylene holds installed capacity. Polypropylene is gaining share fastest as material substitution accelerates.
Distribution Channel:
Channel-specific volume patterns and working capital requirements shape converter customer segmentation and logistics network investments.
- Direct Sales:Large dairy, edible oil, and pharmaceutical manufacturers procure through annual contracts with converters maintaining dedicated production lines and vendor-managed inventory programs. The Mumbai-Pune belt concentration shortens logistics loops for western India FMCG distribution.
- Wholesale:Regional distributors aggregate demand from mid-tier food processors and household chemical formulators, requiring converters to maintain flexible minimum order quantities and standard specification catalogs.
- Online Retail:E-commerce platform sales of specialty and premium packaging formats remain nascent but expanding for small-batch cosmetic and nutraceutical brands.
- Convenience Stores:Single-serve beverage and dairy cup demand flows through modern retail chains with consolidated procurement and private label specifications.
Direct Sales holds installed capacity. Wholesale is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust and dedicated freight corridors linking western India to northern consumption centers underpin Maharashtra's dominance in rigid plastic packaging logistics.
Maharashtra
Mumbai-Pune belt converters operate the densest blow-molding capacity cluster for dairy and edible oil bottles. FSSAI food-contact safety standards drive migration testing investments across Thane and Nashik facilities. Reliance Industries' nearby petrochemical complexes supply virgin PET resin to processors within 150-kilometer radii.
Gujarat
Dahej and Hazira polymer processing zones feed pharmaceutical container demand from Ahmedabad formulation hubs. CDSCO packaging integrity requirements for oral solid dosages push Surat-based injection-molders toward cleanroom certifications. Mundra Port exports rigid packaging to Middle East and African markets.
Karnataka
Bengaluru-Tumkur dairy corridor expansion outpaces local rigid packaging supply, opening procurement gaps for BIS-certified converters. State-level plastic waste management enforcement tightens EPR documentation for recycled content claims. Mysuru thermoformers pivot from polystyrene to polypropylene dairy cups for modern retail chains.
Tamil Nadu
Chennai-Coimbatore pharmaceutical filling operations demand child-resistant closure systems from HDPE container specialists. PLI scheme incentives for specialty chemicals support domestic masterbatch capacity for UV-stabilized bottles. Sriperumbudur automotive belt spillover creates skilled technician pools for precision molding.
Telangana
Hyderabad's bulk drug and vaccine manufacturing expansion requires serialization-ready PET bottles with oxygen barrier specifications. State industrial policy fast-tracks environmental clearances for recycling-integrated greenfield plants. Medchal packaging parks attract Maharashtra converters seeking southern India market access.
India Rigid Plastic Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and equipment supply. The India rigid plastic packaging market structures around three operational tiers: multinational converters with pan-India BIS-certified networks, regional specialists dominating single-state procurement relationships, and commodity processors serving wholesale distributors. Strategic archetypes include decorated in-mold labeling specialists, pharmaceutical compliance-focused cleanroom operators, and dairy sector volume leaders. Competitive moves concentrate on capacity expansion in underpenetrated southern corridors and backward integration into recycled flake washing operations.
Among India-based fabricators, Mold-Tek Packaging Limited and Manjushree Technopack Limited exemplify scale-driven national coverage, while Amcor Rigid Plastics India Private Limited occupies a position within multinational technical standards tier. Pyramid Technoplast and Hitech Corporation represent regional specialists with western India density. These archetypes illustrate how BIS certification breadth and EPR compliance systems separate contract winners from commodity suppliers in consolidated dairy and pharmaceutical procurement.
| Leading Market Players |
|---|
| Pyramid Technoplast Pvt Ltd |
| Hitech Corporation Limited |
| Mold-Tek Packaging Limited |
| Parekhplast India Limited |
| Pearl Polymers Limited |
| Manjushree Technopack Limited |
| Chemco Group |
| Amcor Rigid Plastics India Private Limited |
| Essel Propack (EPL Limited) |
| Others |
Supply & Pricing Matrix
Overcapacity in Gujarat's blow-molding corridor is compressing converter margins and forcing Maharashtra processors to absorb resin volatility through longer contract terms rather than spot-price adjustments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified converters with FSSAI migration testing from commodity processors lacking food-contact approvals. Price differentiation rests on certification grade and volume scale, with national dairy cooperatives extracting double-digit discounts against regional edible oil bottlers. Cost compression in standard tiers is intensifying because Reliance Industries and Indian Oil Corporation control virgin PET and polypropylene supply. Regional wholesale distributors show highest price sensitivity, while pharmaceutical formulators prioritize compliance premiums over unit economics.
Supply Chain Analysis
Upstream feedstock concentration in India draws from Reliance Industries' Jamnagar petrochemical complex and Indian Oil Corporation's Panipat refinery for virgin resin supply. Raw material dependencies center on naphtha-derived PET, propylene-based polypropylene, and imported masterbatch additives. Single-source vulnerability runs through domestic virgin polymer production, where two suppliers control majority output. Distribution runs through direct sales relationships with large dairy and pharmaceutical manufacturers, supplemented by regional wholesale aggregators serving mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping procurement consolidation as national dairy cooperatives and edible oil refiners reduce vendor counts, forcing interoperability across BIS-certified multi-location networks.
For Market Incumbents: Entrench position through backward integration into recycled flake washing operations and capacity expansion in Karnataka-Tamil Nadu corridor where local supply lags filling demand. EPR compliance deadlines and FSSAI migration testing protocols create certification barriers that favor incumbents with pre-approved polymer grades. Multi-location BIS certification anchors long-term contracts against regional commodity processors. For New Entrants and Emerging Players: Pursue pharmaceutical child-resistant closure contracts where CDSCO packaging integrity requirements and cleanroom capabilities create specification barriers. Karnataka dairy corridor underpenetration offers the most accessible white space for converters with certified operations. Go-to-market positioning should emphasize design-for-recycling audits ahead of FMCG procurement consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with vendor-managed inventory programs and multi-year direct sales contracts with national brand owners. Long-term viability favors specialists with pharmaceutical compliance capabilities and southern India geographic diversification. Monitor EPR enforcement intensity through state-level plastic waste tracking portal adoption as inflection indicator for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Captive rPET flake supply secures EPR compliance and shields margin from virgin resin volatility. |
| Multi-Location BIS Certification | Pan-India approval network qualifies converters for consolidated national dairy procurement contracts. |
| Pharmaceutical Cleanroom Investment | CDSCO-compliant assembly capabilities open specification-driven oral solid dosage packaging contracts. |
| Karnataka-Tamil Nadu Capacity Expansion | Proximity to southern dairy and pharmaceutical filling operations shortens logistics loops and working capital cycles. |
| Barrier Coating Technology Adoption | Silicon oxide deposition equipment enables mono-material PET formats that satisfy EPR mandates without shelf-life sacrifice. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer plant managers, procurement leads at dairy and edible oil processors, FSSAI regulatory affairs officers, and pharmaceutical packaging engineers; and secondary validation through BIS certification registries, Plastic Waste Management Rule enforcement notifications, customs trade data on resin imports, and CDSCO packaging integrity guidelines. Bottom-up capacity estimates from converter equipment installations were triangulated against top-down demand projections from end-use sector consumption patterns.
Forecast inputs considered product type segmentation across bottles, containers, jars, and cups; material substitution dynamics between polyethylene, polypropylene, and polystyrene; and end-use industry concentration in food and beverage, pharmaceuticals, personal care, and household chemicals. CAGRs were derived from regression analysis of historical capacity utilization, resin price elasticity, and regulatory compliance cost trajectories across the analysis window. State-level EPR implementation timelines and PLI scheme disbursement patterns provided industry-specific forecast anchors.
Sensitivities concentrate around crude-linked resin volatility, state-level plastic ban enforcement heterogeneity, and mechanical recycling quality degradation limiting food-grade rPET applications. Cross-checking against FSSAI migration testing approval databases and state pollution control board EPR registration records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Containers Market