
 Thermoformed Tubs Market | 2026-2036
Thermoformed Tubs Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Tubs Market Analytics
Modular food-packaging configurations is restructuring buyer procurement patterns across the Thermoformed Tubs Market. Amcor plc leverages its integrated film-to-tub manufacturing footprint to serve protein processors with matched lid-and-base systems. Sonoco Products Company anchors its position through specialized anti-fog and barrier-coated solutions for refrigerated display cases. Dart Container Corp. competes aggressively in institutional foodservice channels with nested, space-efficient tub designs.
Thermoformed tubs are rigid plastic containers produced by heating thermoplastic sheets—typically 0.010 to 0.080 inches thick—and vacuum- or pressure-forming them over molds, yielding lightweight vessels with integral rims for heat-sealed or snap-on closure. These tubs serve primary functions in food preservation, medical sterilization containment, and industrial parts organization where dimensional repeatability and stackability matter. Polypropylene formulations lead material selection for hot-fill and microwaveable applications due to thermal stability above 120°C, while polyethylene grades dominate cold-chain dairy packaging where flexibility and cost efficiency outweigh heat resistance. Food Containers command the largest volume share as fresh-cut produce and ready-meal segments standardize on tamper-evident tub formats, though Medical Tubs generate superior margins through cleanroom manufacturing requirements and lot-traceability protocols.
FDA Title 21 CFR regulations govern food-contact substances and migration limits, compelling resin suppliers and thermoformers to maintain comprehensive extraction testing documentation. EU REACH restrictions on phthalate plasticizers and emerging PPWR packaging-waste rules are accelerating shifts toward mono-material polypropylene designs that simplify mechanical recycling streams. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to invest in chemical recycling partnerships or redesign tub geometries for improved sortation compatibility.
Market Dynamics
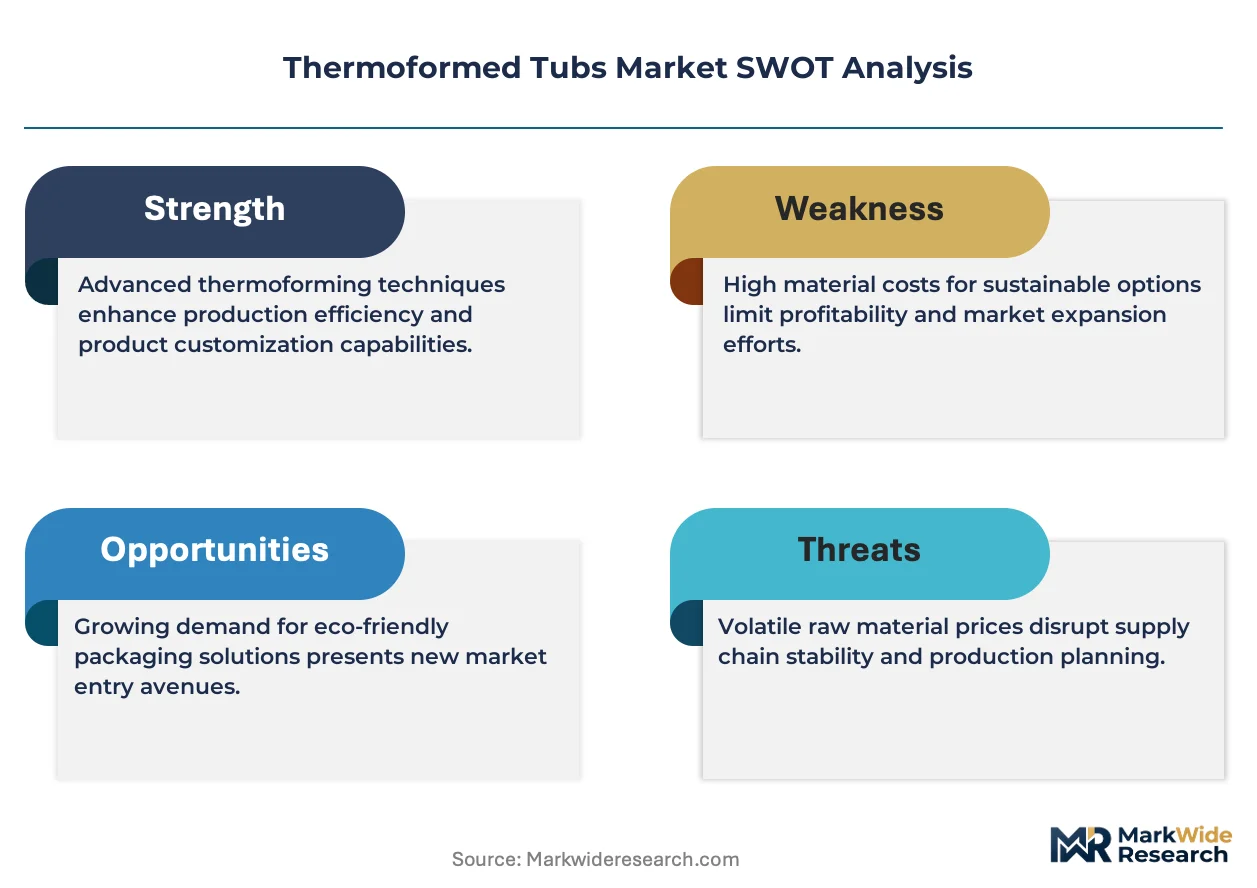
EU single-use plastics directives and FDA migration limits are forcing resin reformulation across the Thermoformed Tubs Market, compressing lead times for compliant material qualification while elevating technical barriers for smaller thermoformers.
Growth Catalysts
- Fresh-cut produce standardization:Retailers in Germany and the Netherlands are consolidating SKUs around tamper-evident tub formats with integral rims, driving volume commitments from protein processors seeking shelf-ready packaging.
- REACH phthalate restrictions:ECHA enforcement against plasticizer migration is accelerating shifts toward mono-material polypropylene designs that bypass mechanical recycling sortation complexity.
- Barrier coating advances:Anti-fog and oxygen-scavenging film technologies are extending refrigerated display case dwell times for dairy and ready-meal applications.
Market Restraints
- Propylene feedstock volatility:North American resin supply concentrates among Gulf Coast petrochemical complexes, exposing thermoformers to hurricane-season disruption and basis price swings.
- Cleanroom capital intensity:Medical tub manufacturing requires ISO 14644 Class 7 environments and lot-traceability systems that demand seven-figure facility investments.
- Flexible pouch substitution:Stand-up pouches with spouted closures are capturing ambient soup and sauce volumes previously held by rigid tubs.
Strategic Opportunities
- Indian cold-chain buildout:FSSAI enforcement of packaged food safety standards is creating first-mover advantage for dairy processors adopting standardized tub formats.
- Chemical recycling partnerships:Pyrolysis infrastructure investments by resin majors are opening circular feedstock pathways for contaminated post-industrial scrap.
- Direct-to-retailer consolidation:Club store buyers are bypassing distributors to specify custom tub geometries with nested stacking ratios above 4:1.
Industry Challenges
- Thermoforming die design specialization:Shortage of mold engineers capable of optimizing plug-assist geometries for thin-gauge polypropylene is extending new product development cycles.
- Extended producer responsibility compliance:Fragmented state-level packaging fee structures in the US are forcing multi-facility operators to maintain parallel reporting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Tubs Market |
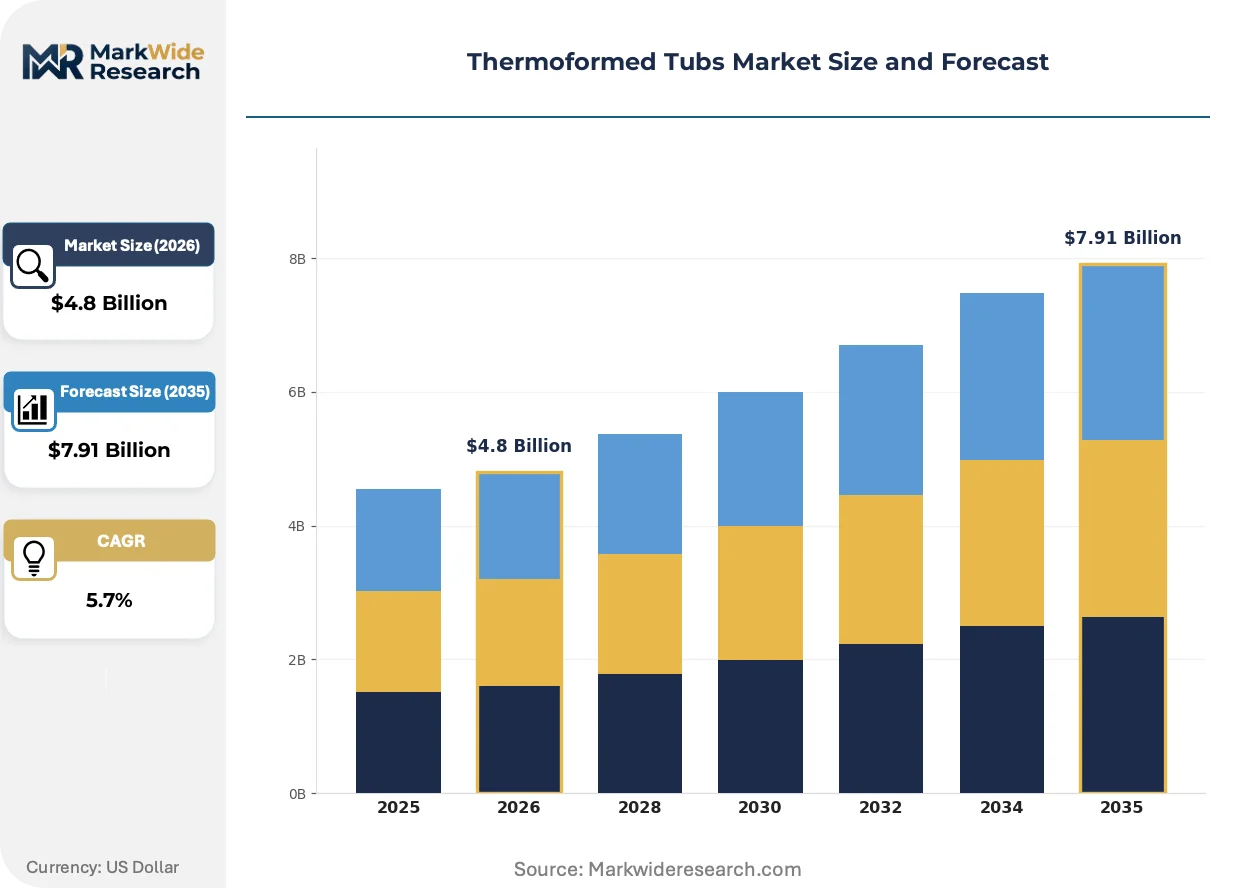
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Containers, Medical Tubs, Storage Tubs, Industrial Bins Material: Polyethylene, Polypropylene, PVC, Polystyrene End User: Food & Beverage, Healthcare, Retail, Manufacturing Application: Packaging, Storage, Transportation, Display |
| Companies Covered | Amcor plc, Pactiv Evergreen Inc., Sonoco Products Company, Sealed Air, Huhtamaki Oyj, Dart Container Corp., Berry Global Inc., Placon Corp., D&W Fine Pack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Tubs Market Evolving Landscape
Material science advances and regulatory compliance automation are compressing the gap between prototype validation and scaled production, while buyer consolidation is shifting specification authority upstream.
Digital twin simulation for thermoforming process optimization is integrating real-time sensor feedback from sheet heating stations and vacuum pressure transducers. Tier-one dairy packers in Wisconsin and Bavaria are deploying these systems to reduce start-up scrap rates. The technology is integrating predictive maintenance modules that flag heater element degradation before dimensional drift occurs.
EU PPWR packaging-waste rules are mandating design-for-recycling assessments across all plastic packaging placed on member-state markets. Thermoformers must now submit technical documentation proving mono-material construction or demonstrating compatible multi-layer separability. Small-format medical tubs with embedded RFID tags face particular scrutiny under WEEE directive overlap.
Centralized procurement by protein processing conglomerates is collapsing supplier rosters from twelve vendors to three preferred partners. Category managers now demand matched lid-and-base systems with synchronized lead times rather than commodity tub sourcing. This concentration is most visible in German meat packaging, where two retail cooperatives control over half of standardized fresh-case volume.
Thermoformed Tubs Market Segmentation
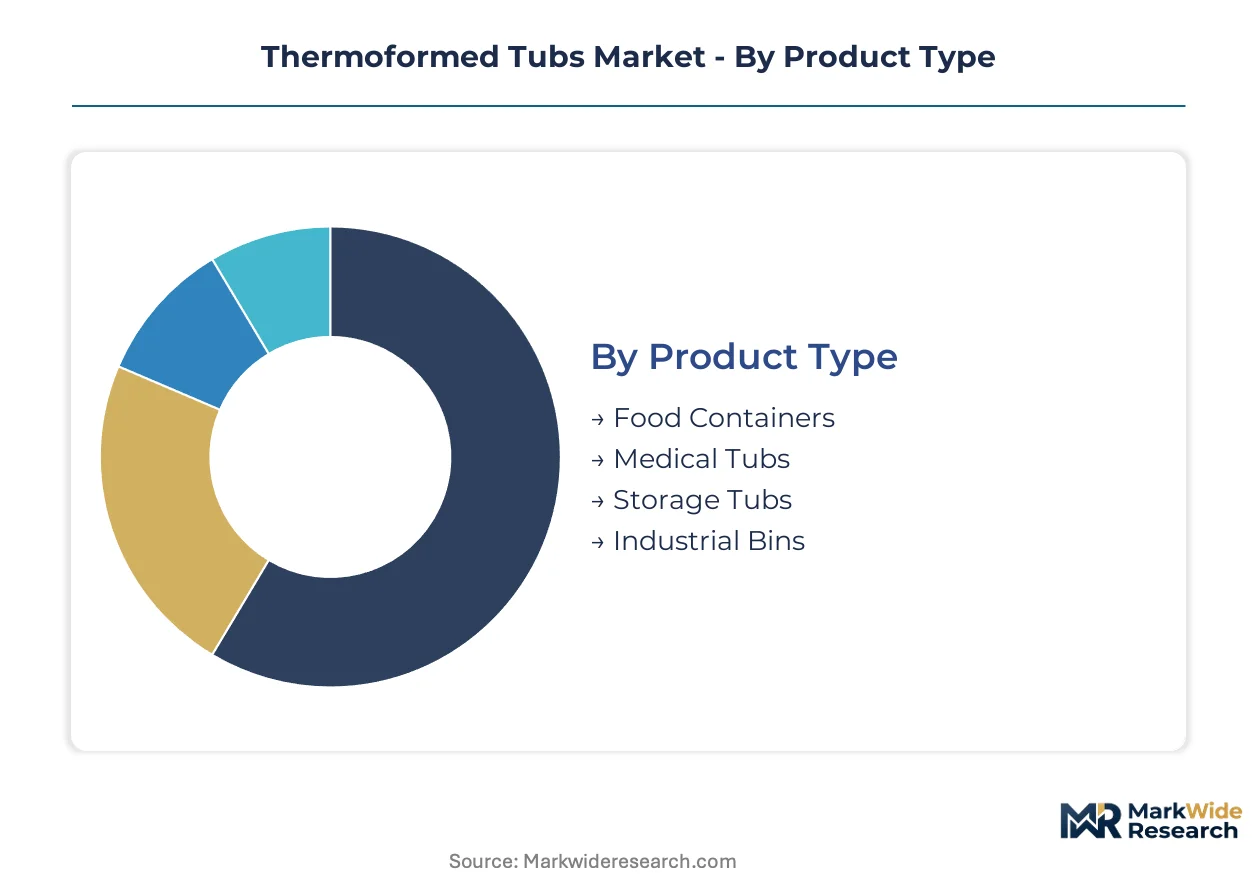
Thermoformed tub buyers prioritize divergent performance attributes—barrier properties, sterilization compatibility, or nested density—creating distinct procurement segments that reshape supplier R&D allocation and margin structures across the value chain.
Product Type:
Volume concentration and margin profiles split sharply across product categories, with food safety certification requirements and cleanroom capital intensity driving fundamentally different competitive economics.
- Food Containers:Tamper-evident designs with integral rims dominate fresh-cut produce and ready-meal applications. German and Dutch retailers are consolidating procurement around standardized formats, forcing protein processors to commit to matched lid-and-base systems rather than commodity sourcing.
- Medical Tubs:ISO 14644 Class 7 cleanroom manufacturing and lot-traceability protocols command premium pricing. Demand concentrates in sterilization containment for surgical kits and pharmaceutical distribution where dimensional repeatability prevents contamination.
- Storage Tubs:Modular nesting ratios above 4:1 serve institutional foodservice and warehouse organization. Space-efficient geometries reduce logistics costs for club store distribution networks.
- Industrial Bins:Heavy-gauge polyethylene formulations withstand automated handling in automotive parts sequencing. ESD-dissipative grades protect electronic components during assembly line replenishment.
Food Containers lead volumes today; Medical Tubs is gaining share fastest.
Material:
Resin selection hinges on thermal performance thresholds and regulatory migration limits, with EU REACH restrictions accelerating shifts away from legacy plasticizer formulations.
- Polypropylene:Thermal stability above 120°C enables hot-fill and microwaveable applications. Mono-material designs simplify mechanical recycling streams under emerging EU PPWR packaging-waste rules.
- Polyethylene:Cold-chain dairy packaging favors flexibility and cost efficiency over heat resistance. North American supply concentrates among Gulf Coast petrochemical complexes, exposing converters to hurricane-season disruption.
- PVC:Phthalate plasticizer restrictions under ECHA enforcement are compressing medical and food-contact applications. Remaining demand clusters in industrial chemical resistance where alternatives fail.
- Polystyrene:Lightweight clarity serves refrigerated display cases with anti-fog coating compatibility. Expanded grades provide cushioning for fragile electronics distribution.
Polyethylene dominates tonnage shipped; Polypropylene is climbing the fastest on sustainability-driven redesign.
End User:
Customer procurement authority is consolidating upstream, with centralized category management collapsing supplier rosters and demanding synchronized lead times across matched component systems.
- Food & Beverage:Fresh-cut produce standardization and ready-meal shelf-life extension drive specification authority. Retailer consolidation in Germany and the Netherlands is compressing vendor counts from twelve to three preferred partners.
- Healthcare:Sterilization validation protocols and FDA Title 21 CFR compliance documentation create technical barriers. Cleanroom capital requirements favor established converters with seven-figure facility investments.
- Retail:Club store buyers bypass distributors to specify custom geometries with nested stacking ratios. Direct-to-retailer consolidation is reshaping volume allocation across thermoformer capacity.
- Manufacturing:Automotive and electronics sectors demand ESD-dissipative and conductive grades for automated handling. Just-in-sequence delivery requirements favor regional suppliers with rapid changeover capabilities.
Food & Beverage anchors current demand; Healthcare is expanding most quickly on medical device outsourcing trends.
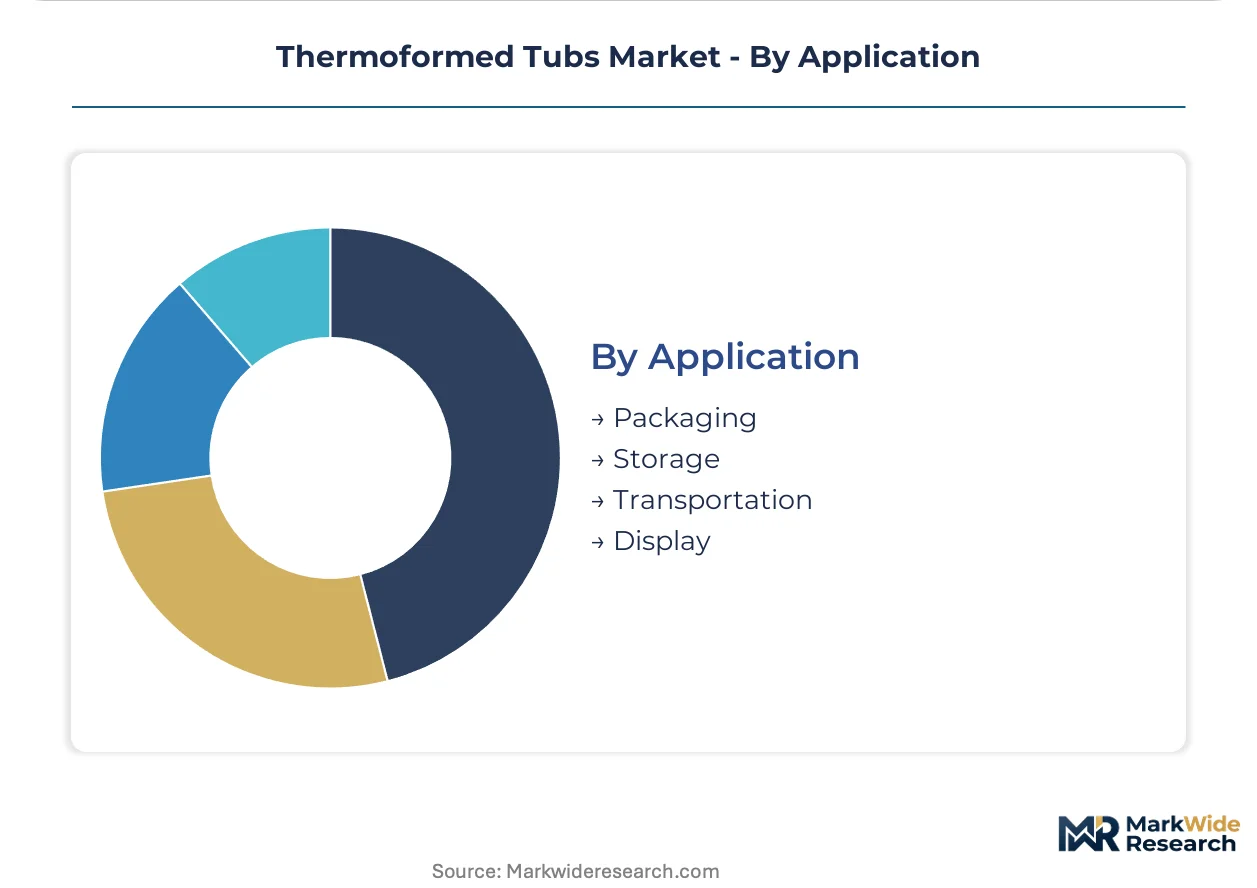
Application:
Functional requirements diverge across the use cycle, with shelf-preservation technologies competing against space-efficiency metrics in procurement evaluations.
- Packaging:Oxygen-scavenging and anti-fog barrier coatings extend refrigerated display case dwell times. Dairy and ready-meal segments standardize on tamper-evident formats with heat-sealed closure integrity.
- Storage:Nested designs reduce warehouse cube requirements for institutional foodservice operators. Modular configurations enable mixed-SKU pallet building for distribution efficiency.
- Transportation:Stack strength and dimensional stability protect contents through automated handling systems. Returnable tote programs in automotive assembly favor durable polypropylene grades.
- Display:Clarity and printability support retail-ready merchandising for fresh produce. Anti-fog properties maintain visual appeal in refrigerated cases with high door-opening frequency.
Packaging commands the largest installed base; Display is seeing steepest expansion trajectory on retailer shelf-ready requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermoforming technology for rigid packaging originated in post-war United States manufacturing, then migrated to German and Japanese industrial clusters as automated food processing scaled. Contemporary demand concentrates where centralized protein processing, dairy cooperatives, and retail consolidation create volume anchors for standardized tub formats.
United States
Wisconsin dairy packers and Georgia poultry processors drive tamper-evident tub standardization for club store distribution. FDA Title 21 CFR migration limits compel resin qualification documentation from Gulf Coast petrochemical suppliers. Chicago-area thermoforming clusters serve refrigerated ready-meal segments with barrier-coated formats.
Germany
Centralized meat processing in Lower Saxony and dairy cooperatives in Bavaria favor matched lid-and-base procurement systems. EU PPWR packaging-waste rules mandate mono-material polypropylene designs for mechanical recycling compatibility. The Emsland region hosts specialized anti-fog coating operations for refrigerated display cases.
China
Fresh-cut produce standardization in Yangtze River Delta retail chains accelerates tamper-evident tub adoption. SAMR food-contact substance regulations align with GB standards for migration testing documentation. Shenzhen-area converters supply nested designs for e-commerce grocery fulfillment centers.
India
FSSAI enforcement of packaged dairy safety standards drives first-mover adoption in Maharashtra and Gujarat processing cooperatives. BIS certification requirements for food-contact plastics elevate technical barriers for regional thermoformers. Bangalore-based cold-chain logistics operators specify standardized formats for pharmaceutical distribution.
Japan
Convenience store ready-meal segments in Kanto prefectures standardize on microwaveable polypropylene tubs. METI circular economy guidelines promote design-for-recycling assessments across packaging value chains. Osaka-area medical device clusters demand ISO 14644 cleanroom manufacturing for sterilization containment.
Thermoformed Tubs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and cleanroom capital intensity. The vendor base stratifies into three tiers: integrated film-to-tub manufacturers with captive resin supply, specialized barrier-coating operators serving refrigerated display cases, and regional converters competing on nested density for institutional foodservice. Dominant competitive moves include backward integration into sheet extrusion capacity and geographic expansion through distributor bypass strategies targeting club store buyers.
Within the integrated manufacturing tier, Amcor plc and Sonoco Products Company exemplify scale-driven positions with matched component system capabilities. Dart Container Corp. anchors the institutional foodservice vector with space-efficient nested designs. Among diversified packaging conglomerates, Berry Global Inc. and Sealed Air occupy positions spanning multiple material grades and end-use certifications.
| Leading Market Players |
|---|
| Amcor plc |
| Pactiv Evergreen Inc. |
| Sonoco Products Company |
| Sealed Air |
| Huhtamaki Oyj |
| Dart Container Corp. |
| Berry Global Inc. |
| Placon Corp. |
| D&W Fine Pack |
| Others |
Value Network & Pricing Analysis
Propylene monomer pricing indices cascading from Gulf Coast petrochemical benchmarks transmit volatility through three distinct pricing tiers across the Thermoformed Tubs Market, compressing margins for non-integrated converters while rewarding resin-captive manufacturers with cost pass-through advantages.
Pricing Analysis
Contract-based long-term offtake agreements with volume-scale adjustments dominate procurement between major dairy processors and integrated film-to-tub manufacturers. Price differentiation separates ISO 14644 cleanroom-certified medical grades from standard food-contact formulations and commodity institutional foodservice tubs. Cost compression in the economy tier is intensifying because flexible pouch substitutes are capturing ambient sauce volumes previously held by rigid containers. Club store buyers exhibit the lowest price sensitivity due to specification authority over custom nested geometries, while regional foodservice distributors face acute margin pressure from space-efficiency demands.
Supply Chain Analysis
Returnable tote programs and post-industrial scrap reclamation flows are expanding as EU PPWR packaging-waste rules mandate design-for-recycling assessments across member-state markets. Raw material supply concentrates in the United States, Germany, and China, with polypropylene resin production anchored in Gulf Coast petrochemical complexes, Emsland coating operations, and Yangtze River Delta extrusion facilities. Feedstock dependencies rest on propylene monomer, barrier coating chemicals, and anti-fog additive masterbatches. Hurricane-season disruption risk at Gulf Coast complexes creates single-source vulnerability for North American converters. Distribution runs through protein processing conglomerates that bypass traditional distributors to specify matched lid-and-base systems directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH phthalate restrictions against US FDA migration-limit enforcement creates a regulatory-arbitrage opportunity for mono-material polypropylene designs that satisfy both jurisdictions with single SKUs, compressing qualification costs for cross-border suppliers.
For Market Incumbents: Acquire captive sheet extrusion capacity to defend margin position against resin price volatility and Gulf Coast supply disruption. Consolidate mold engineering talent pools to shorten new product development cycles threatened by plug-assist geometry optimization shortages. Expand ISO 14644 Class 7 cleanroom footprints in Bavaria and Wisconsin to capture sterilization containment demand from medical device outsourcing trends. For New Entrants and Emerging Players: Small-format pharmaceutical distributors in India represent an underserved buyer archetype with FSSAI enforcement creating first-mover advantage for standardized tub formats. Target Maharashtra and Gujarat dairy cooperatives with BIS-certified food-contact designs that bypass established European supplier lead times. Pursue direct-to-retailer club store bypass strategies with nested stacking ratios above 4:1 as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized anti-fog coating operators serving refrigerated display cases, given barrier technology advances extending dwell times for dairy and ready-meal applications. Long-term viability over the next decade favors converters with chemical recycling partnerships that secure circular feedstock pathways for contaminated post-industrial scrap. Watch pyrolysis infrastructure investment announcements by resin majors as the critical inflection signal for circular economy positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sheet Extrusion | Captive polypropylene supply insulates margins from Gulf Coast hurricane disruption and basis price swings. |
| Chemical Recycling Partnership Formation | Pyrolysis feedstock agreements with resin majors unlock circular pathways for contaminated post-industrial scrap. |
| Cleanroom Capacity Expansion | ISO 14644 Class 7 environments in Wisconsin and Bavaria capture sterilization containment outsourcing from medical device clusters. |
| Direct-to-Retailer Distribution Bypass | Club store specification authority over nested geometries collapses distributor margins and concentrates volume with preferred partners. |
| Anti-Fog Coating Technology Investment | Emsland-region barrier advances extend refrigerated display case dwell times for dairy and ready-meal segments. |
Research Methodology
Bottom-up food processor and dairy cooperative modeling reconciled against top-down resin production and thermoforming capacity tracking forms the analytical core of this study. Primary interviews with plant managers at protein processing facilities, procurement leads at retail cooperatives, technical R&D directors at barrier coating operations, and distribution channel partners were validated against secondary sources including FDA Title 21 CFR filings, ECHA REACH substance restriction updates, EU PPWR technical documentation requirements, and customs trade data for polypropylene sheet imports.
Historical trendline analysis across material grade evolution, end-use certification tier proliferation, and geographic production cluster shifts informed the projection framework. Segmentation dimensions modeled include product type, resin formulation, cleanroom certification level, and nested density specification across the projection horizon. CAGRs were derived from elasticity-adjusted volume forecasts incorporating propylene feedstock price sensitivity and regulatory compliance cost trajectories. Industry-specific inputs encompassed FSSAI enforcement timelines in India and SAMR food-contact alignment with GB standards in China.
Inputs from thermoformer facility audits and resin supplier qualification documentation were available through the study window; gaps in real-time propylene spot pricing granularity and small-format medical tub RFID-tag compliance testing introduce uncertainty bands around medical segment forecasts. Practitioners should monitor ECHA enforcement actions against phthalate plasticizers, FSSAI packaged dairy safety standard rollout pace, and pyrolysis infrastructure commissioning announcements for early signals of regulatory and circular economy inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
MDO Films Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Cavitated Films Market
Packaging Materials
Finish Foils Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Fanfold Market
Packaging Materials
Expanded Polystyrene for Packaging Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Cast Polypropylene (CPP) Films Market
Packaging Materials
Release Film for OCA Market