
 Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market | 2026-2036
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market Insights
ISCC PLUS certification-grade resin supply is unwinding across European flexible packaging lines as converters face binding recycled-content mandates. Borealis leverages its mechanical and chemical recycling hub in Austria to dominate certified-circular polypropylene output for food-contact films. Dow anchors North American demand through its partnership-based pyrolysis sourcing model, while SABIC competes via its TRUCIRCLE portfolio spanning both polyethylene and polypropylene grades.
Certified-circular polyolefin resins denote polymers produced from post-consumer or post-industrial waste streams through mechanical recycling, chemical depolymerization, or pyrolysis, then validated under mass-balance chain-of-custody protocols with minimum recycled content thresholds typically ranging from 30% to 100% depending on certification tier. These resins serve primarily to displace virgin fossil-based polyolefins in packaging applications where brand-owners face Scope 3 emissions reduction targets and regulatory recycled-content floors. Certified-circular polyethylene leads volume due to its dominance in flexible film applications, though certified-circular polypropylene commands margin premiums in rigid containers and pharmaceutical blister packs where thermal performance and clarity requirements are stringent. Flexible films represent the fastest-growing packaging type as mono-material PE structures simplify recycling loops and reduce contamination rates versus multi-layer alternatives.
The EU Green Deal and its Packaging and Packaging Waste Regulation set legally binding recycled-content thresholds enforced by national environmental agencies across member states, while the FDA maintains stringent food-contact notification requirements for chemical recycling outputs in the United States. REACH compliance through ECHA governs substance restrictions in circular feedstocks entering European consumer goods supply chains, creating dual certification burdens for exporters. Stakeholders must monitor whether emerging state-level extended producer responsibility laws in California and New York will recognize mass-balance accounting equivalently with physical recycled content, as this determination will reshape procurement criteria and supplier qualification timelines.
Market Dynamics
Mass-balance chain-of-custody protocols are compressing certification timelines and forcing converters to requalify entire supplier bases as the EU Packaging and Packaging Waste Regulation hardens recycled-content floors.
Growth Catalysts
- EU Green Deal mandates:Binding recycled-content thresholds for plastic packaging are compelling brand-owners to source ISCC PLUS-certified resins ahead of enforcement deadlines.
- Pyrolysis scale-up:Chemical recycling infrastructure investments in Germany, the Netherlands, and Spain are expanding feedstock availability for food-contact-grade polyethylene.
- Mono-material film designs:Brand-owners are redesigning flexible packaging around single-polymer structures that simplify mechanical recycling loops and reduce contamination penalties.
Market Restraints
- Pyrolysis oil cost volatility:Crude-linked pricing for chemical recycling feedstocks exposes resin converters to fossil commodity swings they sought to escape.
- ISCC PLUS auditor concentration:Limited certification body capacity in Central Europe is creating six-month qualification backlogs for new entrants.
- Mechanical recycling yield limits:Multi-layer film contamination and degradation through reprocessing cycles cap post-consumer content at 30-50% for many flexible applications.
Strategic Opportunities
- Pharmaceutical blister packaging:Regulatory pressure on PVC is creating openings for certified-circular polypropylene with equivalent barrier performance.
- California EPR recognition:Pending state-level mass-balance accounting rules could unlock premium pricing for imported European-certified resins.
- Digital product passport integration:Blockchain-tracked chain-of-custody data is enabling real-time Scope 3 emissions reporting for brand-owner ESG disclosures.
Industry Challenges
- Mass-balance accounting expertise:Shortages of auditors fluent in ISCC PLUS fuel tracing and chemical recycling allocation methods are throttling certification throughput.
- Food-contact notification timelines:FDA review cycles for pyrolysis-derived polyethylene are extending 18-24 months, delaying North American commercialization.
- Legacy extrusion line compatibility:Certified-circular polypropylene with broader molecular weight distributions requires screw and die modifications that converters resist.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market |
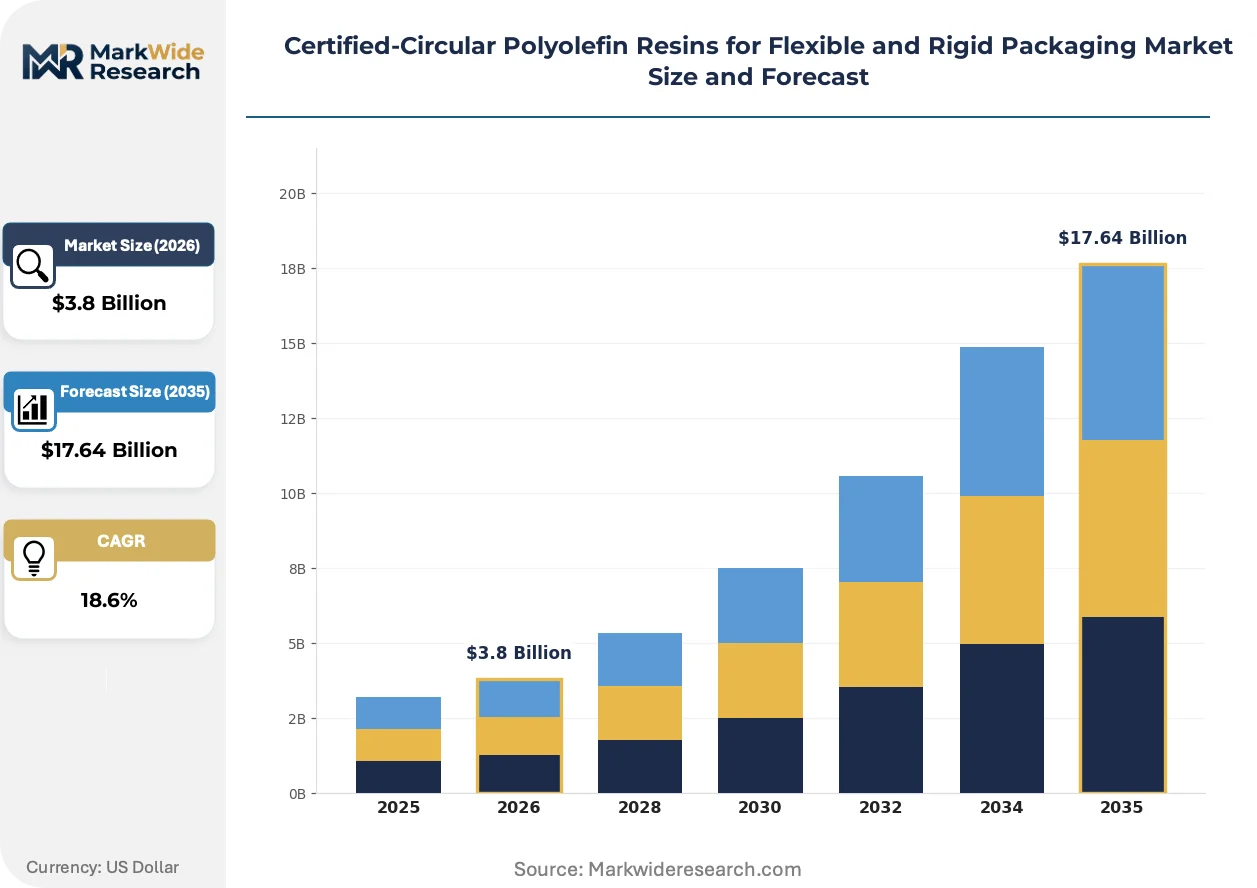
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Certified-Circular Polyethylene, Certified-Circular Polypropylene, Certified-Circular Ethylene-Propylene, Certified-Circular Linear Low-Density Polyethylene Packaging Type: Flexible Films, Rigid Containers, Blister Packs, Clamshells, Tubes Application: Food Packaging, Personal Care Products, Pharmaceutical Packaging, Industrial Packaging, Agricultural Films End User Industry: Consumer Goods Manufacturers, Pharmaceutical Firms, Cosmetics Companies, Agriculture Suppliers, Chemical Producers |
| Companies Covered | Borealis, SABIC, LyondellBasell, TotalEnergies, Dow, ExxonMobil Chemical, INEOS Group, Repsol, Braskem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market Trends and Innovations
Advanced sorting and purification technologies are collapsing the cost gap between mechanical and chemical recycling routes while digital traceability infrastructure is hardening chain-of-custody integrity.
Pyrolysis-based polyethylene production is supplanting mechanical recycling for food-contact flexible films as output consistency and odor control improve. Major dairy and meat packagers in France and Germany are switching procurement specifications to pyrolysis-derived grades. This shift is compressing mechanical recyclers into lower-margin non-food applications where certification requirements remain lighter.
REACH compliance through ECHA is tightening substance restrictions on circular feedstocks entering European consumer goods supply chains. Recycled-content thresholds in the EU Packaging and Packaging Waste Regulation are forcing exporters to maintain dual certification burdens. Flexible film converters are responding by consolidating supplier relationships around vertically integrated resin producers with in-house chemical recycling capabilities.
Direct contracting between brand-owners and resin producers is displacing distributor-mediated spot purchasing for certified-circular volumes. Consumer goods multinationals in the Netherlands and Belgium are negotiating three-year offtake agreements with fixed mass-balance premiums. This pattern is most visible in rigid dairy container applications where supply security outweighs price flexibility.
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market Segmentation
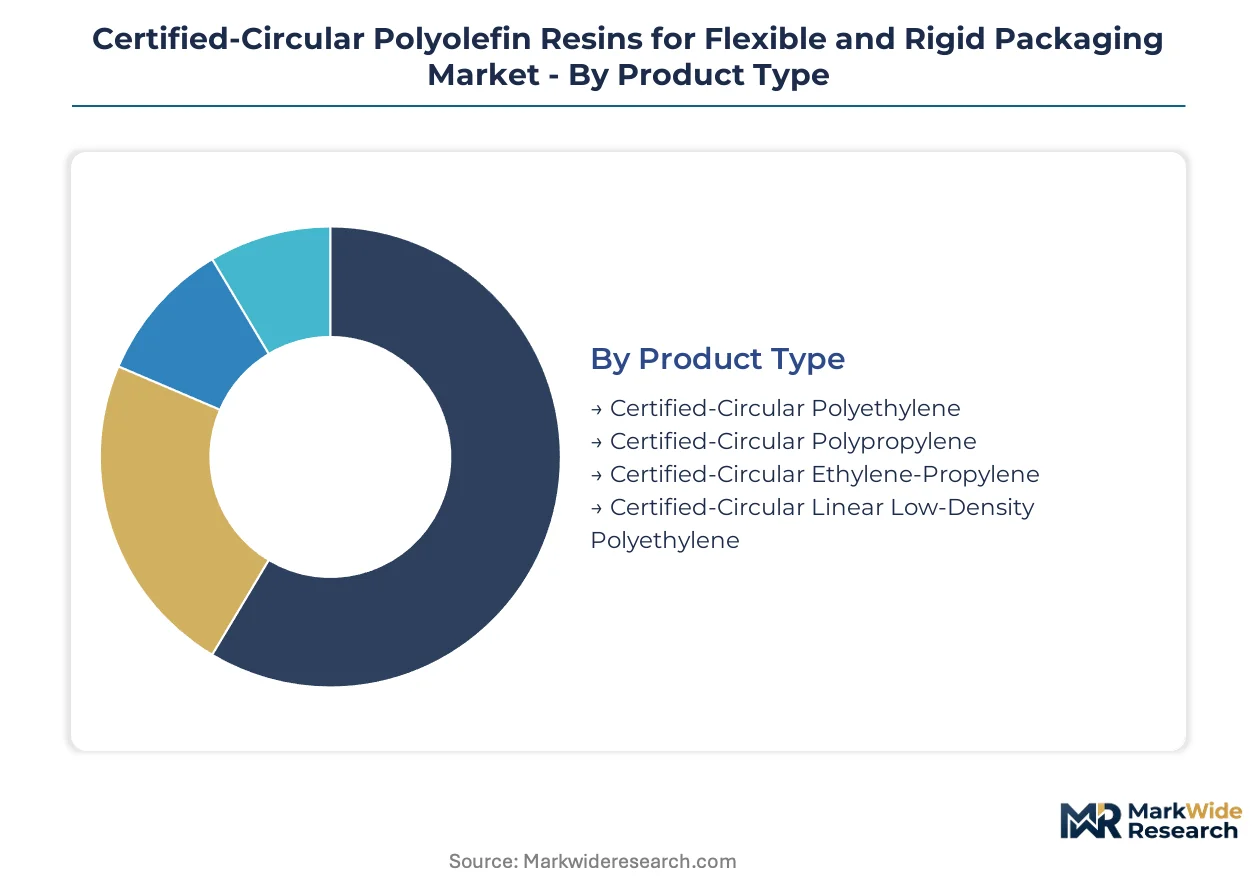
Segmentation in certified-circular polyolefin resins reveals where margin pools concentrate and where procurement complexity escalates. Certified-circular polyethylene commands volume leadership in flexible films, while certified-circular polypropylene extracts premiums in rigid pharmaceutical applications where thermal performance requirements are stringent.
Product Type:
Margin pools concentrate in polypropylene grades where food-contact certification complexity limits supplier entry and sustains pricing power.
- Certified-Circular Polyethylene:Dominates flexible film formulations with melt flow indices optimized for blown and cast extrusion. Dairy and meat packagers in France and Germany are switching procurement specifications to pyrolysis-derived grades as output consistency improves.
- Certified-Circular Polypropylene:Commands structural premiums in rigid containers and pharmaceutical blister packs. Thermal performance and clarity specifications limit viable suppliers to vertically integrated resin producers with in-house chemical recycling capabilities.
- Certified-Circular Ethylene-Propylene:Copolymer grades balance impact resistance with processability for durable goods packaging.
- Certified-Circular Linear Low-Density Polyethylene:Stretch film and heavy-duty sack applications drive demand for puncture-resistant formulations.
Certified-circular polyethylene holds installed capacity. Certified-circular polypropylene is rotating up the share rankings.
Packaging Type:
Application complexity and contamination sensitivity create divergent margin structures across packaging formats.
- Flexible Films:Mono-material PE structures simplify recycling loops and reduce contamination penalties versus multi-layer alternatives. Brand-owners are redesigning specifications around single-polymer architectures to meet EU Packaging and Packaging Waste Regulation thresholds.
- Rigid Containers:Dairy and food service applications demand consistent lot-to-lot performance that pyrolysis-derived resins increasingly deliver.
- Blister Packs:Regulatory pressure on PVC creates substitution opportunities for certified-circular polypropylene with equivalent barrier performance.
- Clamshells:Thermoformed formats require broad molecular weight distribution control that challenges legacy extrusion lines.
- Tubes:Laminated and extruded formats split between mechanical and chemical recycling feedstocks based on layer complexity.
Flexible films capture procurement volume. Rigid containers are climbing the fastest in supplier prioritization.
Application:
Regulatory stringency and brand-owner ESG disclosure requirements segment applications by certification burden and price tolerance.
- Food Packaging:Binding recycled-content mandates under the EU Green Deal compel brand-owners to source ISCC PLUS-certified resins. Pyrolysis-derived polyethylene is supplanting mechanical recycling as FDA notification timelines extend for North American commercialization.
- Pharmaceutical Packaging:Blister pack converters face REACH compliance constraints through ECHA on circular feedstocks entering European supply chains.
- Personal Care Products:Premium positioning supports mass-balance premium absorption for certified-circular polyolefins in rigid bottles.
- Industrial Packaging:Stretch film and pallet wrap applications tolerate lower certification tiers where mechanical recycling yields suffice.
- Agricultural Films:Soil contamination and UV degradation limit post-consumer content to 30-50% for many mulch and greenhouse applications.
Food packaging holds committed offtake volume. Pharmaceutical packaging is gaining share fastest in margin contribution.
End User Industry:
Procurement sophistication and supply security requirements differentiate customer segments by contract structure and qualification timelines.
- Consumer Goods Manufacturers:Multinationals in the Netherlands and Belgium are negotiating three-year offtake agreements with fixed mass-balance premiums. Direct contracting with resin producers is displacing distributor-mediated spot purchasing.
- Pharmaceutical Firms:Batch traceability and regulatory filing requirements favor vertically integrated suppliers with in-house certification expertise.
- Cosmetics Companies:Premium brand positioning supports certified-circular resin absorption in rigid and flexible formats.
- Agriculture Suppliers:Price sensitivity and performance durability requirements segment demand toward mechanical recycling grades.
- Chemical Producers:Intermediate applications in industrial films and compounds tolerate broader specification ranges.
Consumer goods manufacturers anchor contract volume. Pharmaceutical firms are rotating up the priority rankings for supplier qualification resources.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence for certified-circular polyolefin resins is reversing across Western Europe as domestic pyrolysis capacity scales. Germany and the Netherlands are emerging as net exporters to neighboring markets still building chemical recycling infrastructure.
Germany
ISCC PLUS-certified resin output is concentrating along the Rhine-Ruhr industrial corridor as brand-owners accelerate compliance with EU Packaging and Packaging Waste Regulation thresholds. The Federal Environment Agency enforces binding recycled-content mandates through national transposition of EU Green Deal directives. Ludwigshafen and Cologne host integrated chemical recycling hubs supplying food-contact-grade polyethylene to dairy packagers switching from mechanical recycling grades.
Netherlands
Rotterdam's port infrastructure anchors pyrolysis oil import and upgrading operations serving flexible film converters across the Benelux region. The Dutch National Institute for Public Health and the Environment coordinates REACH compliance verification for circular feedstocks entering consumer goods supply chains. Direct contracting between Amsterdam-headquartered consumer goods multinationals and resin producers is displacing traditional distributor relationships.
France
Mechanical recycling yield limits are pushing Paris-based dairy and meat packagers toward pyrolysis-derived polyethylene specifications. The French Agency for Food, Environmental and Occupational Health & Safety maintains stringent food-contact notification requirements for chemical recycling outputs. The Grand Est region hosts emerging purification technology clusters collapsing cost gaps between mechanical and chemical recycling routes.
Spain
Extended producer responsibility schemes administered by the Ministry for Ecological Transition are tightening virgin plastic quotas for flexible packaging producers. Barcelona and Tarragona concentrate chemical recycling investments targeting ISCC PLUS certification for export to Central European converters. Agricultural film applications in Valencia and Murcia remain price-sensitive segments tolerating lower certification tiers.
United States
FDA notification timelines extending 18-24 months for pyrolysis-derived polyethylene are delaying commercialization of food-contact applications. State-level extended producer responsibility laws in California and New York are pending mass-balance accounting recognition decisions that will reshape procurement criteria. Houston and the Gulf Coast petrochemical corridor dominate mechanical recycling capacity serving industrial packaging applications with lighter certification burdens.
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market Competitive Landscape
Concentration sits with vertically integrated petrochemical majors possessing in-house chemical recycling capabilities and ISCC PLUS certification expertise. The supplier base stratifies between European producers with pyrolysis infrastructure and North American players navigating extended regulatory timelines. Three archetypes dominate: integrated resin producers with captive recycling assets, mechanical recycling specialists pivoting toward certification-grade output, and technology licensors supplying pyrolysis equipment to third-party operators. Capacity expansion and strategic offtake partnerships constitute the dominant competitive moves as converters seek supply security ahead of mandate enforcement.
Within the integrated petrochemical tier, Borealis, SABIC, and Dow exemplify archetype positioning through their respective European and North American footprints. Borealis occupies a position anchored by its Austrian mechanical and chemical recycling hub serving food-contact film specifications. SABIC represents Middle Eastern-headquartered diversification across both polyethylene and polypropylene certified-circular portfolios. Dow sits within the North American competitive set through partnership-based pyrolysis sourcing models pending FDA commercialization timelines.
| Leading Market Players |
|---|
| Borealis |
| SABIC |
| LyondellBasell |
| TotalEnergies |
| Dow |
| ExxonMobil Chemical |
| INEOS Group |
| Repsol |
| Braskem |
| Others |
Pricing and Supply Chain Analysis
Three-year offtake agreements with fixed mass-balance premiums lock in supply access and price visibility for consumer goods multinationals in the Netherlands and Belgium ahead of EU Packaging and Packaging Waste Regulation enforcement deadlines. These contracts displace spot purchasing and insulate converters from pyrolysis oil cost volatility tied to crude commodity swings.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with tiered pricing across ISCC PLUS certification grades, volume scale, and food-contact notification status. Cost compression in mechanical recycling tiers is intensifying because pyrolysis-derived polyethylene commands premium positioning for dairy and meat packaging specifications. Agricultural film applications in Spain and Italy exhibit highest price sensitivity, while pharmaceutical blister pack converters absorb mass-balance premiums due to limited certified-circular polypropylene supplier pools.
Supply Chain Analysis
ISCC PLUS auditor concentration in Central Europe creates qualification chokepoints extending six-month backlogs for new resin entrants seeking certification. Supply draws from Germany, the Netherlands, and Spain as pyrolysis infrastructure scales, with feedstock dependencies on post-consumer plastic waste collection networks and pyrolysis oil upgrading capacity. Single-source vulnerability concentrates around Rotterdam's port infrastructure for oil import and upgrading operations. Distribution runs through direct converter relationships with vertically integrated resin producers, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISCC PLUS certification expertise functions as the critical bottleneck constraining supplier entry and sustaining margin pools for qualified incumbents. The gap between auditor capacity and converter qualification demand is reshaping competitive positioning across European flexible packaging lines.
For Market Incumbents: Shield margin position by accelerating in-house chemical recycling capacity additions in the Rhine-Ruhr corridor before pending FDA notification timelines unlock North American commercialization for pyrolysis-derived polyethylene. Consolidate supplier relationships around captive mechanical and chemical recycling hubs to defend against mechanical recycling specialists pivoting toward certification-grade output. For New Entrants and Emerging Players: Mass-balance accounting advisory services represent an underserved layer where incumbents under-serve small and mid-sized converters facing six-month ISCC PLUS qualification backlogs. Target agricultural film applications in Valencia and Murcia with lower certification tier tolerance, deploying technical field support bundled with certification navigation as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated resin producers with in-house pyrolysis infrastructure and established ISCC PLUS certification pipelines across the analysis window. The inflection signal to watch is California's pending mass-balance accounting recognition decision under state-level extended producer responsibility laws, which would unlock premium pricing arbitrage for European-certified resin imports.| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Capacity Expansion | Rotterdam and Ludwigshafen hubs anchor food-contact-grade polyethylene supply security for dairy packagers. |
| Backward Integration into Waste Collection | Captive post-consumer plastic feedstock sourcing insulates against contamination penalties and yield volatility. |
| ISCC PLUS Certification Investment | In-house auditor training and mass-balance expertise compresses six-month qualification timelines for converter customers. |
| Long-term Offtake Agreements | Three-year fixed premium contracts with Unilever and Danone displace spot purchasing and lock volume commitments. |
| Joint Venture for North American Market Entry | FDA notification navigation partnerships accelerate 18-24 month commercialization timelines for pyrolysis-derived resins. |
Research Methodology
The analysis maps certified-circular polyethylene, polypropylene, and copolymer grades, each validated through resin procurement managers at consumer goods multinationals, flexible film converters, pharmaceutical packaging specialists, and ISCC PLUS certification auditors. Primary interviews with plant managers at chemical recycling facilities and downstream OEM procurement leads combined with secondary validation from ECHA REACH substance restriction filings, EU Green Deal directive transposition documents, and customs trade data for circular feedstock imports. Bottom-up capacity and demand modeling triangulated against top-down regulatory mandate enforcement timelines.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled resin type, packaging format, application regulatory stringency, and regional chemical recycling infrastructure maturity. CAGRs were derived from segment-level demand build-ups incorporating EU Packaging and Packaging Waste Regulation recycled-content floor trajectories and pyrolysis capacity commissioning schedules. Forecast inputs included FDA food-contact notification approval timelines and state-level extended producer responsibility law implementation patterns.
Material uncertainties — pyrolysis oil price volatility, ISCC PLUS auditor capacity constraints, and mass-balance accounting recognition decisions in California and New York — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and chemical recycling yield improvements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market