
 Cold Chain Integrity and Shock Monitoring Test Devices Market | 2026-2036
Cold Chain Integrity and Shock Monitoring Test Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Chain Integrity and Shock Monitoring Test Devices Market Insights
The EU F-Gas Regulation is shifting cold chain equipment standards toward lower-global-warming-potential refrigerants, which in turn demands more sophisticated integrity monitoring across retrofit fleets. Carrier leverages its HVAC heritage to anchor refrigeration-monitoring integration, while Thermo Fisher Scientific sustains R&D intensity in ultra-low-temperature validation protocols. ELPRO-BUCHS specializes in pharmaceutical-grade data loggers that dominate European GDP-compliant distribution networks.
Cold chain integrity and shock monitoring test devices encompass calibrated instruments that record temperature excursions, mechanical shock events, and environmental anomalies during transit and storage, typically operating across ranges from -80°C to +60°C with accuracy thresholds of ±0.5°C. These devices serve primarily to document chain-of-custody compliance and trigger intervention protocols before product degradation occurs. Data loggers occupy the largest installed base due to their regulatory acceptance across pharmaceutical applications, while IoT-enabled devices represent the fastest-expanding technology segment as cloud-connected telemetry replaces manual download workflows. RFID Tags capture concentrated margin pools in high-value aerospace components where non-reusable indicators justify premium unit economics.
FDA 21 CFR Part 11 shapes electronic record-keeping requirements that directly determine device software architecture and audit trail capabilities for US pharmaceutical distribution. The EU GDP guidelines, enforced by national regulators such as Germany's BfArM and France's ANSM, mandate continuous monitoring with alarm functionality for temperature-sensitive medicinal products. Stakeholders must weigh capital deployment between retrofitting existing fleets with Bluetooth-enabled loggers versus full IoT infrastructure, as connectivity standardization remains unresolved across logistics provider networks.

Market Dynamics
The transition from manual data retrieval to real-time cloud telemetry is restructuring capital allocation across pharmaceutical logistics networks, forcing hardware vendors to embed cellular and satellite connectivity as standard rather than premium features.
Growth Catalysts
- EU GDP guidelines:Continuous monitoring mandates for temperature-sensitive medicinal products are expanding the installed base of alarm-enabled data loggers across European distribution corridors.
- mRNA biologics:Ultra-low-temperature storage requirements for next-generation vaccines and gene therapies are accelerating validation protocol upgrades in pharmaceutical-grade cold chains.
- Germany's pharmaceutical logistics corridor:Precision monitoring has become standard operational practice, creating concentrated demand for GDP-compliant hardware specifications.
Market Restraints
- Lithium battery supply concentration:Dependence on East Asian cell manufacturers creates input volatility for portable logger production and extended lead times for North American device assemblers.
- Sensor calibration drift:Temperature accuracy degradation over multi-year deployments forces premature replacement cycles, compressing effective hardware lifespans below depreciation schedules.
- FDA 21 CFR Part 11 compliance costs:Electronic record-keeping validation requirements impose software architecture constraints that extend development timelines and certification expenses.
Strategic Opportunities
- India's cold chain infrastructure:Underpenetrated pharmaceutical distribution networks present expansion potential for GDP-aligned monitoring hardware as domestic biologics manufacturing scales.
- RFID-NFC convergence:Hybrid tagging systems combining passive inventory tracking with active environmental sensing are opening aerospace and high-value electronics applications.
- EU F-Gas Regulation retrofit cycles:Refrigerant transition mandates are triggering fleet-wide equipment upgrades that bundle integrity monitoring into new infrastructure procurement.
Industry Challenges
- Multi-protocol integration:Logistics providers operate heterogeneous connectivity stacks that fragment IoT deployment, forcing device vendors to support redundant radio modules.
- Validation engineering scarcity:Shortage of professionals qualified in pharmaceutical thermal mapping and IQ/OQ/PQ documentation is extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Chain Integrity and Shock Monitoring Test Devices Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Loggers, Impact Indicators, RFID Tags, Temperature Sensors, Accelerometers Technology: Wireless Monitoring, IoT-enabled Devices, Bluetooth, NFC, GPS Tracking Application: Pharmaceuticals, Food & Beverage, Chemicals, Blood Products, Aerospace Components End User: Distributors, Logistics Providers, Warehousing Facilities, Regulatory Agencies |
| Companies Covered | Carrier, ELPRO-BUCHS, ORBCOMM, Controlant, Thermo Fisher Scientific, Testo, Zebra Technologies, Monnit, Berlinger & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Chain Integrity and Shock Monitoring Test Devices Market Trends and Innovations
Edge computing architectures are displacing centralized data aggregation in cold chain monitoring, enabling localized decision-making at the shipment level before cloud synchronization occurs.
Bluetooth Low Energy mesh networking is decentralizing temperature monitoring across refrigerated trailers and warehouse zones, allowing pharmaceutical distributors to retrofit existing fleets without pulling cable. Third-party logistics providers in Benelux and the Rhine-Ruhr corridor are deploying these self-healing networks to eliminate manual logger retrieval. The architecture compresses infrastructure costs while maintaining GDP-compliant audit trails through redundant node coverage.
REACH chemical restrictions and RoHS substance limits are forcing sensor manufacturers to reformulate encapsulants and solder alloys, eliminating legacy lead-based and restricted phthalate components. European device assemblers are requalifying supply chains to maintain CE marking eligibility for pharmaceutical-grade hardware. The regulatory pressure is accelerating material substitution timelines that were previously deferred due to validation burden.
Consolidated buying by multinational pharmaceutical distributors is compressing vendor negotiation cycles and unbundling hardware from service contracts. Large logistics integrators in Germany and Switzerland now procure loggers through centralized procurement functions that benchmark total cost of ownership across five-year operational lifespans. This behavioral shift is marginalizing smaller regional device vendors unable to demonstrate scale economies in calibration and firmware maintenance.
Cold Chain Integrity and Shock Monitoring Test Devices Market Segmentation
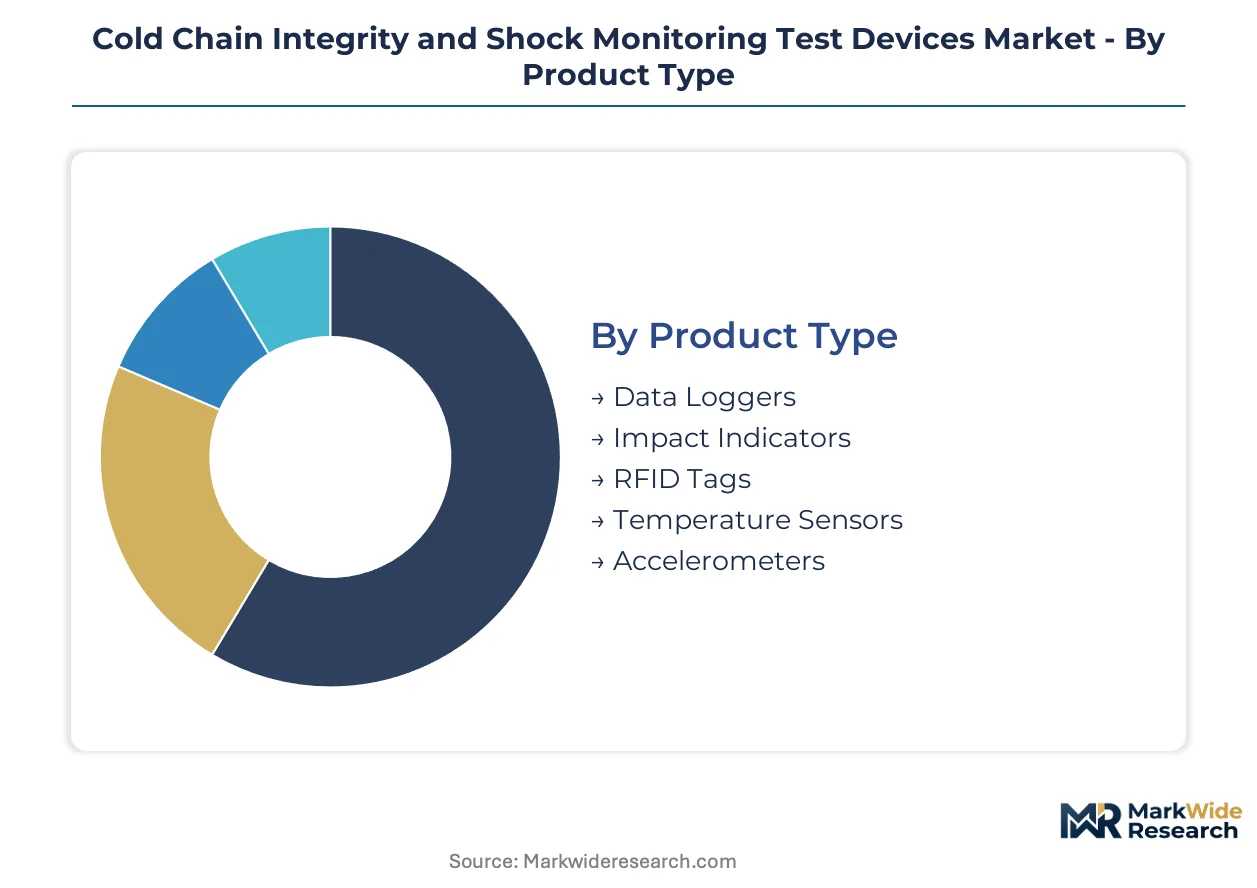
Cold chain integrity and shock monitoring test devices fragment across four distinct classification axes, each carrying different regulatory certification burdens and procurement decision frameworks. Understanding these segment boundaries clarifies why pharmaceutical distributors prioritize GDP-validated data loggers while aerospace manufacturers gravitate toward disposable impact indicators.
Product Type:
FDA 21 CFR Part 11 and EU GDP guidelines impose divergent validation requirements across hardware categories, with pharmaceutical applications demanding audit-trail capabilities that disposable indicators cannot satisfy.
- Data Loggers:Calibrated electronic recorders with internal memory and downloadable temperature histories, typically achieving ±0.5°C accuracy across -80°C to +60°C ranges. Pharmaceutical distributors in Germany's Rhine-Ruhr corridor deploy these as standard GDP-compliant infrastructure, with BfArM inspections validating their alarm functionality and electronic signature capabilities.
- Impact Indicators:Single-use mechanical or chemical devices that register shock events exceeding calibrated g-force thresholds through irreversible color change or fracture patterns. Aerospace component manufacturers in France's Toulouse cluster specify these for satellite and avionics shipments where non-reusable documentation satisfies EASA traceability mandates without retrieval logistics.
- RFID Tags:Passive or semi-passive transponders embedding temperature or shock sensing with wireless inventory tracking.
- Temperature Sensors:Discrete probe or thermocouple elements requiring external data acquisition systems.
- Accelerometers:MEMS-based shock measurement devices outputting digital g-force data for high-frequency vibration analysis.
Leading the category by volume: Data Loggers. Growing fastest: Impact Indicators.
Technology:
Connectivity architecture determines total cost of ownership across deployment scales, with cellular telemetry commanding premium positioning against Bluetooth retrofit solutions.
- Wireless Monitoring:Radio-frequency data transmission encompassing proprietary protocols and mesh network architectures. Third-party logistics providers in the Netherlands deploy self-healing Zigbee and LoRaWAN infrastructures across refrigerated trailer fleets, eliminating manual logger retrieval while maintaining redundant node coverage for GDP audit trails.
- IoT-enabled Devices:Cloud-connected hardware with embedded cellular or satellite modems enabling real-time telemetry and geofenced alerts. Swiss pharmaceutical distributors in Basel's logistics hub specify these for high-value biologics shipments where intervention timeframes compress to hours rather than days.
- Bluetooth:Short-range low-energy protocols for localized data harvest via smartphone or gateway.
- NFC:Near-field communication for tap-to-read temperature histories without battery-powered transmission.
- GPS Tracking:Satellite positioning integrated with environmental sensing for location-correlated anomaly detection.
Bluetooth dominates installed base through retrofit economics. IoT-enabled Devices claim steepest expansion trajectory as cellular module costs decline.
Application:
End-use temperature requirements and value-at-risk profiles create divergent hardware specifications, with ultra-low-temperature biologics demanding validation protocols that ambient food chains cannot justify.
- Pharmaceuticals:Temperature-sensitive medicinal products spanning mRNA vaccines, insulin, and monoclonal antibodies requiring continuous monitoring with alarm thresholds. Germany's BfArM and France's ANSM enforce GDP guidelines that mandate calibrated data loggers with electronic records for all distribution stages.
- Food & Beverage:Perishable cargo including dairy, seafood, and frozen proteins where HACCP compliance drives monitoring adoption. Benelux cold storage operators deploy Bluetooth mesh networks across warehouse zones, balancing regulatory documentation against thin margins that resist premium IoT subscriptions.
- Chemicals:Temperature-critical industrial reagents and specialty materials.
- Blood Products:Plasma, platelets, and whole blood with narrow thermal windows.
- Aerospace Components:High-value avionics, satellite payloads, and precision electronics where shock documentation supports insurance claims and failure analysis.
Pharmaceuticals anchor revenue concentration. Aerospace Components expand most quickly as satellite manufacturing scales.
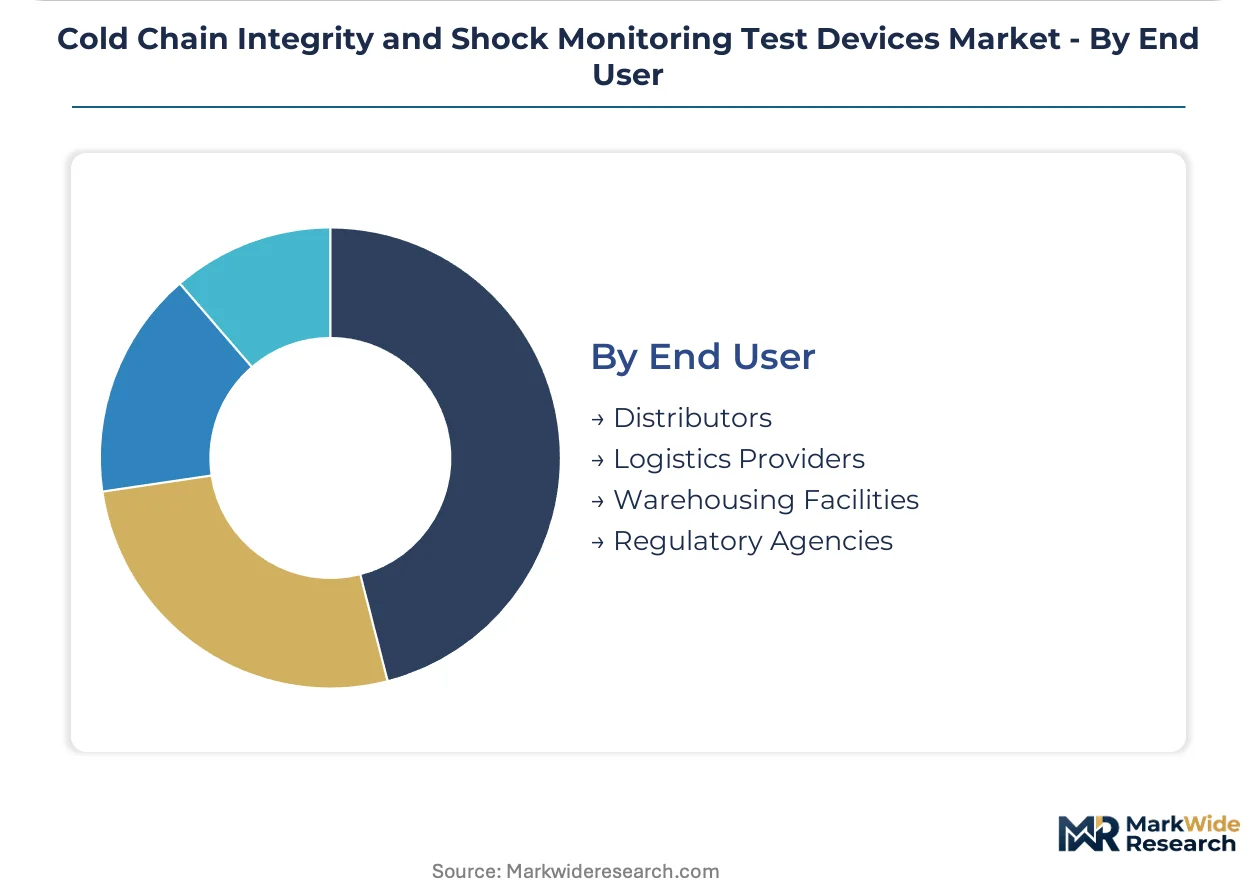
End User:
Procurement authority and technical sophistication vary sharply across buyer categories, with regulatory agencies imposing standards that downstream vendors must hardware-enable.
- Distributors:Pharmaceutical and food wholesalers managing multi-temperature storage and cross-dock operations. Germany's Phoenix Pharmahandel and similar regional distributors specify GDP-validated loggers with centralized fleet management platforms, amortizing calibration costs across thousands of deployment points.
- Logistics Providers:Third-party cold chain operators including Kuehne+Nagel and DHL Supply Chain segments. These buyers benchmark total cost of ownership across five-year operational lifespans, unbundling hardware from service contracts and marginalizing vendors lacking scale economies in firmware maintenance.
- Warehousing Facilities:Static cold storage operators with fixed infrastructure monitoring requirements.
- Regulatory Agencies:Government bodies including FDA, EMA, and national competent authorities that establish validation protocols and conduct inspections.
Distributors command largest procurement volumes. Logistics Providers are gaining share fastest through consolidated buying and centralized vendor rationalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr pharmaceutical logistics corridor anchors cold chain monitoring device deployment, where precision temperature validation has become standard operational infrastructure for biologics distribution.
United States
FDA 21 CFR Part 11 compliance mandates reshape electronic record-keeping specifications for pharmaceutical distributors across the Midwest and Northeast corridors. The EPA and FAA maintain overlapping jurisdiction for hazardous material transport monitoring in aerospace applications. Greater Boston's biotech cluster demands ultra-low-temperature validation protocols for mRNA manufacturing supply chains.
Germany
BfArM enforcement of EU GDP guidelines drives continuous monitoring adoption for temperature-sensitive medicinal products throughout the national distribution network. The F-Gas Regulation accelerates retrofit cycles that bundle integrity monitoring into refrigerant transition projects. The Rhine-Ruhr corridor concentrates procurement authority among pharmaceutical wholesalers requiring GDP-validated data loggers.
Switzerland
Swissmedic validation protocols for biologics shipments create premium-tier demand for IoT-enabled devices with cellular telemetry and geofenced alerts. Basel's logistics hub serves as the coordination point for high-value gene therapy distribution across European markets. The country's pharmaceutical manufacturing density sustains specialized calibration service ecosystems.
France
ANSM inspections mandate alarm-enabled data loggers for all stages of pharmaceutical distribution, expanding the installed base across domestic cold storage networks. EASA traceability requirements for aerospace components sustain demand for disposable impact indicators in Toulouse's satellite manufacturing cluster. REACH chemical restrictions force sensor manufacturers to reformulate encapsulants for CE marking eligibility.
India
CDSCO alignment with international GDP standards accelerates monitoring hardware adoption as domestic biologics manufacturing scales. The PLI scheme for pharmaceutical production incentivizes cold chain infrastructure investment across Maharashtra and Gujarat. Mumbai-Pune pharmaceutical corridor distributors benchmark total cost of ownership for validation-compliant device procurement.
Cold Chain Integrity and Shock Monitoring Test Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across calibration certification tiers, with GDP-validated devices commanding sustained pricing power against uncertified alternatives. The vendor base organizes into three strategic archetypes: diversified instrumentation conglomerates leveraging cross-divisional R&D, specialized pharmaceutical-grade data logger manufacturers, and connectivity-focused telemetry providers. Consolidated buying by multinational distributors compresses negotiation cycles and unbundles hardware from service contracts. Two dominant competitive moves are reshaping positioning: M&A activity targeting calibration service capabilities and strategic partnerships with third-party logistics providers for fleet-wide deployment.
Within the diversified instrumentation tier, Carrier and Thermo Fisher Scientific represent contrasting heritage advantages—HVAC-rooted refrigeration integration against laboratory-validated ultra-low-temperature protocols. ELPRO-BUCHS exemplifies the specialized pharmaceutical-grade archetype, occupying a position within European GDP-compliant distribution networks where audit-trail capabilities determine procurement decisions.
| Leading Market Players |
|---|
| Carrier |
| ELPRO-BUCHS |
| ORBCOMM |
| Controlant |
| Thermo Fisher Scientific |
| Testo |
| Zebra Technologies |
| Monnit |
| Berlinger & Co. |
| Others |
Pricing and Supply Chain Analysis
Bluetooth Low Energy mesh adoption is compressing infrastructure costs for pharmaceutical distributors while concentrating procurement leverage among German and Swiss logistics hubs capable of amortizing calibration across fleet-scale deployments. This technology transition simultaneously erodes premium pricing for standalone loggers and rewards vendors with embedded connectivity architectures.
Pricing Analysis
Outcome-based pricing anchors device procurement decisions, with pharmaceutical distributors in Germany's Rhine-Ruhr corridor benchmarking total cost of ownership across five-year operational lifespans rather than unit acquisition costs. Three-tier pricing structure across GDP-validated premium, CE-marked standard, and uncertified economy levels reflects calibration certification burdens and firmware maintenance capabilities. Cost compression in the economy tier is intensifying because consolidated buying by multinational logistics providers unbundles hardware from service contracts. Regional distributors exhibit highest price sensitivity due to thin margins and fragmented deployment scales, while Swiss biologics shippers accept premium IoT subscriptions for intervention-critical shipments.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the Netherlands anchor European device procurement, with hub-and-spoke patterns concentrating inventory leverage among pharmaceutical wholesalers managing multi-temperature corridors. Lithium battery cell production draws from South Korea, Japan, and China, while MEMS sensor fabrication rests on Taiwan and US semiconductor foundries. Single-source vulnerability in East Asian battery supply creates input volatility for portable logger assemblers facing extended lead times. Distribution runs through centralized procurement functions at Kuehne+Nagel and DHL Supply Chain segments, marginalizing vendors lacking scale economies in calibration and firmware maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated buying by multinational pharmaceutical distributors is forcing weaker regional device vendors out of European GDP-compliant networks, rewarding only those with validated calibration ecosystems and cellular-embedded product architectures.
For Market Incumbents: Lock in calibration service capabilities through captive laboratory investments in Basel and Frankfurt, insulating against margin pressure from unbundled hardware procurement. Defensive consolidation of firmware maintenance teams across German-speaking markets preserves pricing power against emerging IoT-native entrants lacking pharmaceutical validation heritage. For New Entrants and Emerging Players: Direct-to-distributor digital channels bypass incumbent field sales organizations entrenched in BfArM inspection relationships. India's CDSCO-aligned pharmaceutical corridor offers the most penetrable geography, where domestic biologics manufacturing scales faster than GDP-validated device supply. Target calibration-as-a-service bundling to overcome capital barriers against established European vendors. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified instrumentation conglomerates seeking pharmaceutical-grade data logger capabilities. Long-term viability favors vendors with embedded cellular architectures and recurring telemetry revenue streams over transactional hardware models. Watch for FDA 21 CFR Part 11 enforcement intensity as inflection indicator for premium-tier pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | Captures recurring service revenue from BfArM-inspected pharmaceutical distributors in Germany. |
| Cellular Module Integration | Enables real-time telemetry subscriptions that Swiss biologics shippers specify for gene therapy shipments. |
| India Distribution Partnership | Positions GDP-aligned hardware for CDSCO-compliant domestic biologics manufacturing scale-up. |
| Bluetooth Mesh Certification | Validates retrofit economics for Benelux third-party logistics providers eliminating manual logger retrieval. |
| F-Gas Regulation Bundle | Links integrity monitoring to refrigerant transition procurement cycles across EU retrofit fleets. |
Research Methodology
Document review covered EU GDP guideline enforcement records, FDA 21 CFR Part 11 validation documentation, and REACH chemical restriction filings, complemented by interviews with pharmaceutical logistics directors, cold chain validation engineers, and calibration laboratory managers. Secondary sources included BfArM inspection reports, ANSM distribution audits, and customs data on lithium battery imports. Bottom-up device shipment estimates triangulated against top-down pharmaceutical cold chain infrastructure investment figures.
Historical capacity deployment patterns cross-referenced against panel input from IoT hardware procurement officers and fleet management platform vendors shaped the analytical framework. Segmentation dimensions modeled encompass product type, connectivity technology, application temperature requirements, and end-user procurement authority. CAGRs derived from shipment volume trajectories weighted by average selling price evolution across certification tiers. Industry-specific inputs included mRNA biologics storage protocol adoption curves and F-Gas Regulation retrofit cycle timing.
The model holds under sustained EU GDP guideline enforcement and stable lithium battery supply; deviation in East Asian trade restrictions or FDA validation requirement relaxation would shift hardware demand trajectories. Forecasts reflect documented assumptions regarding cellular module cost decline and pharmaceutical distributor consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Pharmaceutical Cold Chain Packaging Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Cold Chain Packaging Pooling and Reverse Logistics Services Market
Cold Chain Packaging
Food Cold Chain Market
Cold Chain Packaging
Global Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Foam Cooler Box Market
Cold Chain Packaging
Refrigeration Packaging Market
Cold Chain Packaging
Middle East and Africa Frozen Food Packaging Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Reusable Cold Chain Packaging Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Fish Boxes Market
Cold Chain Packaging
Insulated Food Delivery Bags Market