
 Rigid Food Containers Market | 2026-2036
Rigid Food Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Food Containers Market Outlook
Skilled thermoforming technician availability is collapsing across North American manufacturing hubs, tightening production capacity for thin-wall polypropylene containers. Amcor plc leverages captive resin sourcing and integrated sheet extrusion to sustain margin stability despite labor scarcity. Berry Global Inc. anchors its position through multi-site blow molding networks that compete aggressively on dairy and deli container contracts. Silgan Holdings Inc. dominates metal food can supply to shelf-stable protein brands, extending its reach via two-piece aluminum drawing expertise.
Rigid food containers are structurally self-supporting receptacles manufactured from plastics, glass, metal, or fiberboard, typically featuring defined sidewalls, bases, and closure interfaces designed to protect contents from mechanical damage, moisture ingress, and gas permeation during distribution and retail display. Polypropylene and polyethylene thermoformed and injection-molded vessels constitute the dominant product type by unit volume, driven by cost efficiency, microwave compatibility, and lightweight logistics economics. Glass containers retain premium positioning in organic and baby food segments where chemical inertness and reuse cycles justify higher unit pricing. Metal formats, particularly tinplate and aluminum two-piece cans, occupy the mature shelf-stable category with stable but slow-growth demand tied to center-store grocery procurement patterns.
The FDA regulates food contact substances under 21 CFR, while EPA emissions frameworks shape resin production siting decisions in the United States. EU REACH and the Packaging and Packaging Waste Regulation impose recycled content minimums and extended producer responsibility obligations that redirect investment toward rPET and chemically recycled polyolefin streams. Stakeholders must monitor evolving state-level extended producer responsibility enactments and chemical recycling capacity buildouts to secure compliant material pipelines.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is forcing material substitution decisions across European converting capacity, redirecting capital toward chemically recycled polyolefin streams and away from virgin resin dependency.
Growth Catalysts
- EU Recycled Content Mandates:The Packaging and Packaging Waste Regulation establishes minimum recycled content thresholds that pull rPET and chemically recycled polypropylene into food-grade specifications.
- Ready-to-Eat Meal Proliferation:Food service channels are expanding chilled and ambient prepared food offerings, driving throughput for thin-wall thermoformed containers with modified atmosphere compatibility.
- Germany Manufacturing Expansion:Branded food manufacturers are scaling production lines in German facilities, concentrating demand for high-barrier rigid containers across dairy, deli, and ambient shelf-stable categories.
Market Restraints
- Skilled Labor Collapse:Thermoforming technician availability is tightening across North American manufacturing hubs, constraining thin-wall polypropylene production capacity expansion.
- Resin Price Volatility:Polypropylene and polyethylene feedstock costs fluctuate with crude oil and natural gas liquids pricing, compressing converter margins on fixed-price dairy and deli contracts.
- Glass Substitution Ceiling:Metal and plastic formats face technical barriers displacing glass in organic baby food segments where chemical inertness and reuse cycles command premium positioning.
Strategic Opportunities
- India Food Processing Scale-Up:The FSSAI is expanding food safety certification frameworks that enable branded ready-to-eat adoption, creating virgin territory for microwave-compatible polypropylene containers.
- Chemical Recycling Infrastructure:Pyrolysis and depolymerization capacity buildouts in the Netherlands and Belgium are opening compliant material pipelines for EU brands facing 2030 recycled content deadlines.
- Smart Packaging Convergence:Integration of time-temperature indicators with injection-molded bases is creating differentiated shelf-life extension propositions for cold-chain protein distributors.
Industry Challenges
- Thermoforming Skill Gap:North American technical colleges have shuttered plastics processing programs, leaving converters dependent on aging workforces for thin-wall tool setup and cycle optimization.
- Extended Producer Responsibility Timelines:State-level EPR enactments in California, Oregon, and Maine impose divergent reporting and fee structures that complicate national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Food Containers Market |
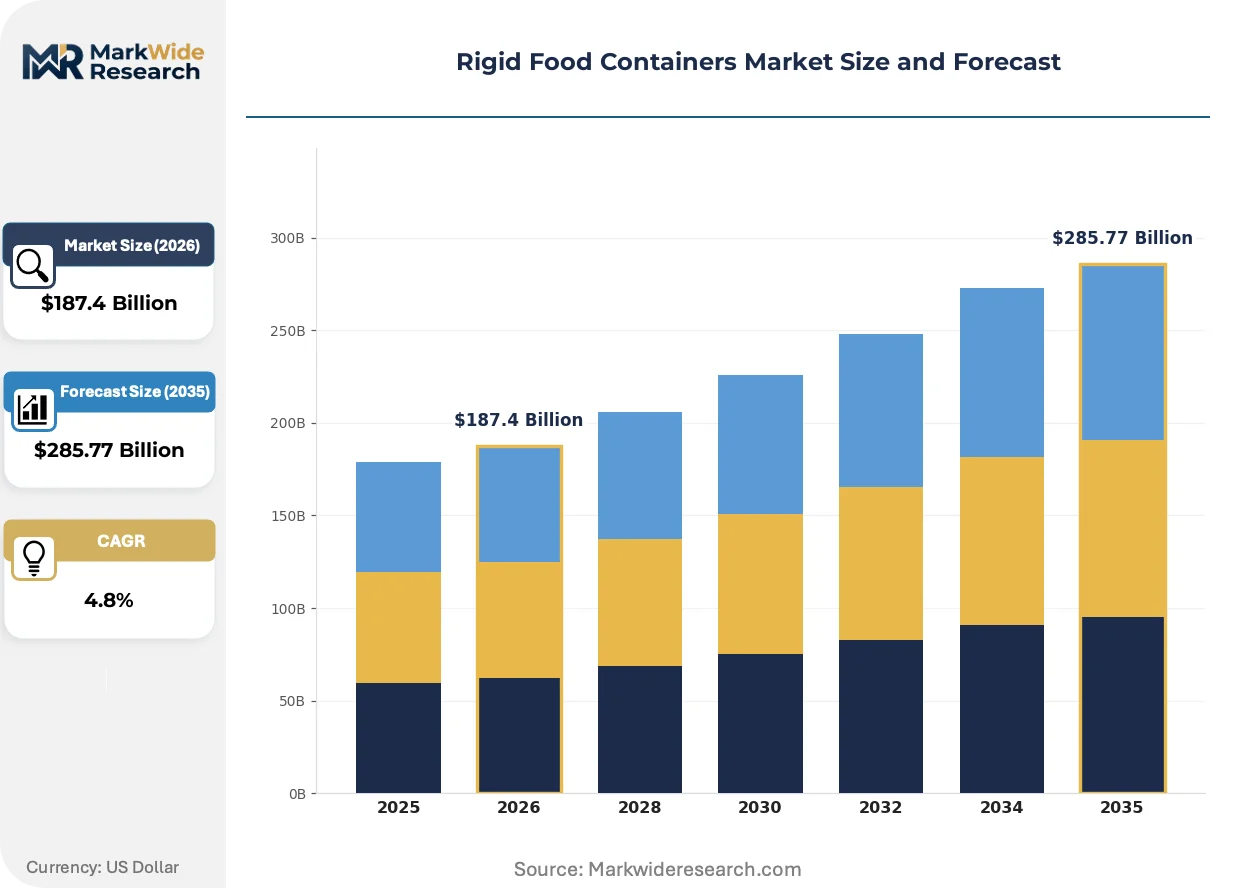
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Metal, Fiberboard End User: Food Service, Retail, E-commerce, Catering Material: Polypropylene, Polyethylene, Stainless Steel, Aluminum Closure Type: Screw Cap, Snap Fit, Tab Lock, Hinged |
| Companies Covered | Amcor plc, Berry Global Inc., Sealed Air Corporation, Sonoco Products Company, Huhtamaki Oyj, Silgan Holdings Inc., Ardagh Group S.A., Pactiv Evergreen Inc., Dart Container Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Food Containers Market Strategic Shifts
Active packaging integration and material circularity investments are compressing traditional container specifications while expanding functional performance requirements across temperature-sensitive categories.
Mono-material barrier films laminated to polypropylene bases are miniaturizing multi-layer structures previously required for oxygen and moisture protection. Dairy processors in Germany and the Netherlands are adopting these specifications at pace to meet retailer sustainability scorecards. This consolidation is miniaturizing the specialty film supplier base while concentrating converting expertise among integrated sheet extruders.
REACH authorization procedures for food contact additives are tightening migration limit testing protocols across European converter operations. Manufacturers must now document substance-by-substance compliance for recycled content streams, extending qualification timelines for rPET trays and deli containers. The chilled ready-to-eat segment is responding by consolidating supplier relationships toward vertically integrated resin-to-container producers with captive chemical recycling assets.
Direct-to-retailer procurement contracts are displacing traditional distributor intermediaries in North American grocery private-label programs. Container converters now negotiate directly with Kroger, Albertsons, and Ahold Delhaize category managers on specification, volume, and sustainability credential bundling. This disintermediation is most visible in the deli and prepared meals vertical, where annual contract values now exceed legacy multi-distributor arrangements.
Rigid Food Containers Market Segmentation
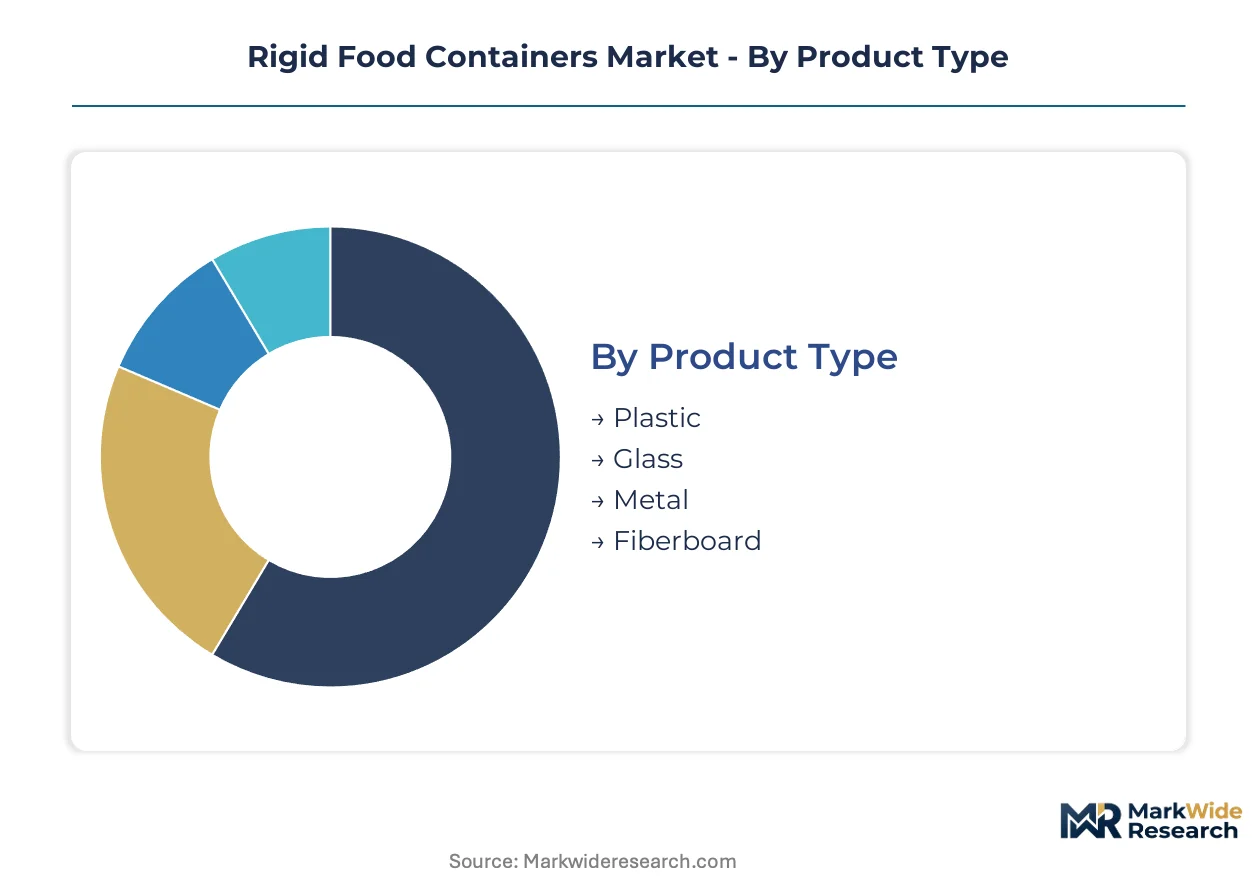
Segmentation in rigid food containers reveals how material specifications and channel requirements drive procurement patterns. Manufacturers configure production assets around end-use temperature demands and closure integrity standards rather than pursuing universal formats.
Product Type:
Channel throughput varies sharply by product type, with food service operators favoring lightweight disposables while retail grocers prioritize shelf presence and reusability signals.
- Plastic:Thermoformed polypropylene and polyethylene vessels dominate unit economics through microwave compatibility and lightweight logistics. Demand concentrates in North American deli and prepared meal channels where modified atmosphere packaging extends shelf life for retailers.
- Glass:Chemically inert borosilicate and soda-lime compositions command premium positioning in organic baby food and specialty preserves. German and Dutch organic brands are expanding glass lines to meet retailer sustainability scorecards and reuse deposit systems.
- Metal:Tinplate and aluminum two-piece cans anchor shelf-stable protein and vegetable categories with proven oxygen barrier performance.
- Fiberboard:Molded pulp and paperboard formats serve short-shelf-life produce and dry goods where moisture exposure is limited.
By volume, plastic leads across all measured channels. By growth pace, glass is gaining share fastest in premium organic segments.
End User:
Cost tier stratification separates specification intensity, with food service prioritizing unit cost and retail demanding printed branding surfaces and stackability engineering.
- Food Service:High-throughput operators in institutional catering and quick-service chains specify thin-wall thermoformed containers with snap-fit closures for speed of service. Chilled ready-to-meal proliferation in European contract catering is pulling rPET specifications to meet EU Packaging and Packaging Waste Regulation thresholds.
- Retail:Branded food manufacturers specify high-clarity bases with in-mold labeling for shelf differentiation. German supermarket chains are consolidating procurement toward integrated resin-to-container suppliers with verified recycled content documentation.
- E-commerce:Direct-to-consumer meal kit services specify nested, crush-resistant formats with tamper-evident features for last-mile durability.
- Catering:Event and corporate hospitality channels favor reusable or compostable formats with hinged lids for transport security.
Retail captures the highest revenue per unit through premium specifications. E-commerce is expanding most quickly as meal kit subscriptions scale.
Material:
Application temperature requirements dictate material selection, with hot-fill and retort processes eliminating lower-melting-point options regardless of cost.
- Polypropylene:High crystallinity grades deliver microwave stability and chemical resistance for dairy and deli applications. Indian food processors are adopting microwave-compatible polypropylene as FSSAI certification frameworks expand ready-to-eat manufacturing.
- Polyethylene:LDPE and HDPE variants serve cold-chain dairy and frozen formats where flexibility and impact resistance outweigh temperature tolerance. North American converter margins compress on fixed-price dairy contracts when ethylene feedstock costs fluctuate.
- Stainless Steel:304 and 316 grades occupy premium reusable segments and industrial food processing equipment where corrosion resistance and cleanability are paramount.
- Aluminum:Two-piece drawn and ironed cans dominate shelf-stable beverages and proteins with lightweight logistics and infinite recyclability credentials.
Polypropylene leads in unit volume across temperature-tolerant applications. Aluminum is climbing the fastest as beverage brands convert from plastic bottles.
Closure Type:
Customer type separates resealability demands, with household consumers prioritizing repeated access and food service operators valuing single-use speed.
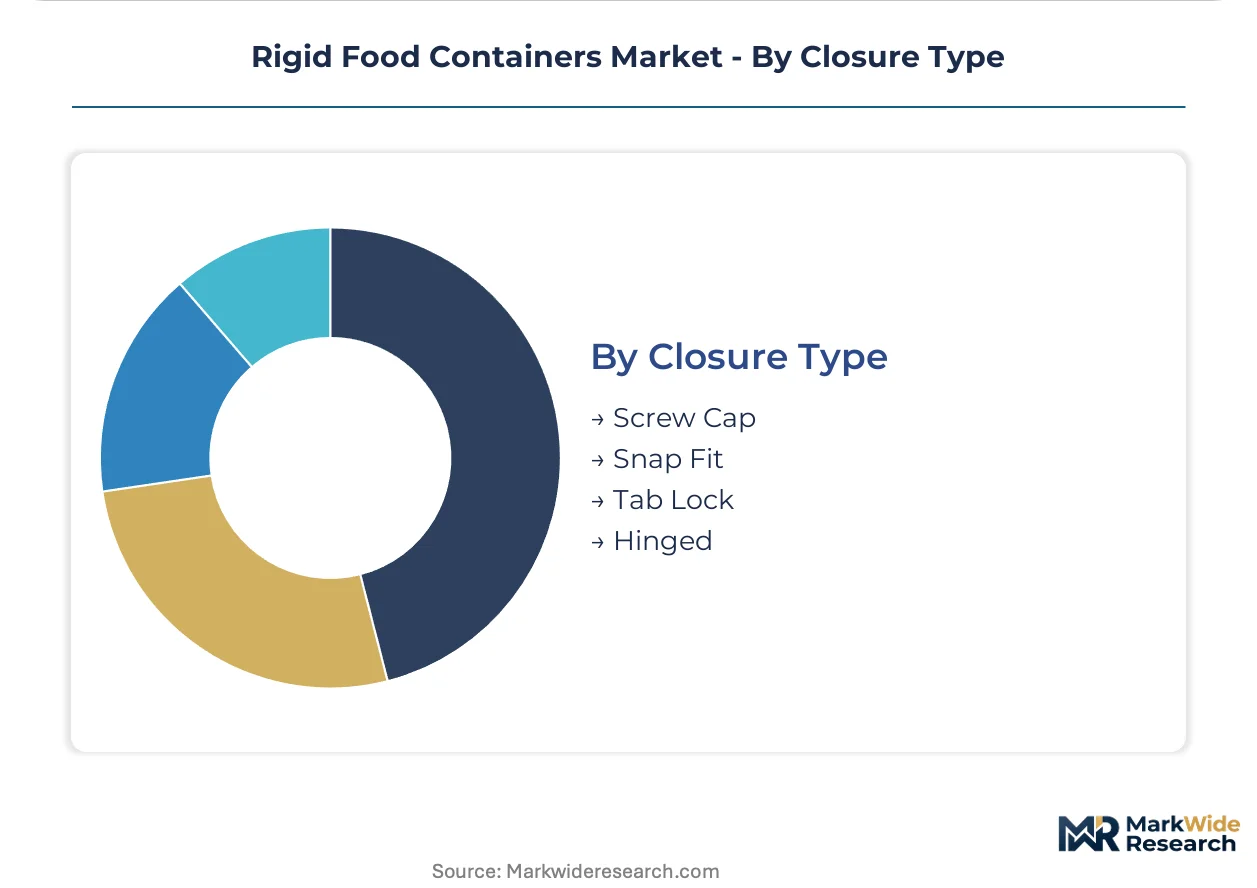
- Screw Cap:Precision-molded threaded closures with induction seals secure liquid and semi-liquid contents across glass and plastic jars. Organic baby food brands specify child-resistant screw caps to differentiate premium positioning.
- Snap Fit:Peripheral bead-and-groove designs enable one-handed operation for food service throughput. Quick-service chains in North America specify audible-click snap fits to confirm seal integrity during high-speed assembly.
- Tab Lock:Peelable aluminum tabs on metal cans provide tamper evidence and easy access for shelf-stable categories.
- Hinged:Integral living hinges connect lid to base for reusable deli and produce containers where lid retention prevents loss.
Snap fit closures dominate food service volume. Screw caps are gaining share fastest as retail brands emphasize resealability and portion control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Packaging and Packaging Waste Regulation anchors European demand redirection, while FDA and EPA frameworks shape resin production economics in the United States. Material substitution investments concentrate in jurisdictions with enforceable recycled content thresholds.
Germany
Branded food manufacturers are scaling chilled and ambient product lines, concentrating demand for high-barrier rigid containers. The EU Packaging and Packaging Waste Regulation imposes minimum recycled content thresholds that pull rPET and chemically recycled polypropylene into food-grade specifications. The Rhine-Ruhr industrial corridor hosts expanding thermoforming capacity serving dairy and deli supply chains.
United States
Quick-service chains and institutional catering operators specify thin-wall thermoformed containers with snap-fit closures for speed of service. FDA regulation of food contact substances under 21 CFR shapes material qualification protocols, while EPA emissions frameworks influence resin production siting decisions. The Midwest manufacturing belt faces skilled thermoforming technician shortages that constrain polypropylene container output expansion.
Netherlands
Chemical recycling infrastructure buildouts in pyrolysis and depolymerization are opening compliant material pipelines for brands facing 2030 recycled content deadlines. REACH authorization procedures tighten migration limit testing protocols for food contact additives. The Rotterdam-Antwerp port cluster anchors rPET tray and deli container qualification programs with vertically integrated resin-to-container producers.
India
FSSAI expansion of food safety certification frameworks enables branded ready-to-eat adoption, creating demand for microwave-compatible polypropylene containers. Food processors are adopting high-crystallinity grades as certification coverage broadens. The Maharashtra-Gujarat industrial corridor hosts emerging thermoforming investments targeting domestic chilled meal penetration.
Belgium
EU Packaging and Packaging Waste Regulation compliance timelines are accelerating converter investment in chemically recycled polyolefin streams. ECHA oversight of REACH authorization shapes substance-by-substance documentation requirements for recycled content streams. The Flanders chemical processing cluster concentrates chemical recycling capacity buildouts serving pan-European food brands.
Rigid Food Containers Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the rigid food containers market. The vendor base spans integrated resin-to-container producers, multi-site blow molding networks, and specialty metal can fabricators. Three archetypes dominate: captive resin converters with backward integration into sheet extrusion, scale-driven multi-plant operators competing on dairy and deli contracts, and metal drawing specialists commanding shelf-stable protein supply. Competitive moves concentrate on strategic partnerships for recycled content pipelines and geographic expansion into emerging food processing jurisdictions.
Within the integrated converter tier, Amcor plc and Berry Global Inc. occupy positions exemplifying resin sourcing control and multi-site manufacturing scale respectively. Silgan Holdings Inc. anchors metal food can supply archetypes through two-piece aluminum drawing expertise. These three entities represent distinct strategic postures: captive supply chain integration, distributed production network coverage, and specialized metal forming capabilities.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Sealed Air Corporation |
| Sonoco Products Company |
| Huhtamaki Oyj |
| Silgan Holdings Inc. |
| Ardagh Group S.A. |
| Pactiv Evergreen Inc. |
| Dart Container Corporation |
| Others |
Value Chain & Pricing Dynamics
Thin-wall thermoforming capacity utilization above 85% in the US Midwest and Rhine-Ruhr corridor concentrates supply-side leverage among integrated resin-to-container producers, elevating price floors for dairy and deli contract renewals while squeezing independent converters on fixed-price commitments.
Pricing Analysis
North American polypropylene container prices run 12-18% above EU equivalents due to ethane feedstock advantages and labor scarcity premiums. Three-tier pricing structure across premium, standard, and economy levels separates integrated converters with captive resin sourcing from distributors reselling commodity grades. Pricing pressure stems from resin price volatility tied to natural gas liquids fluctuations, compressing margins on multi-year dairy contracts. Quick-service chains exhibit highest price sensitivity through annual rebidding cycles, while organic baby food brands absorb premiums for glass and certified recycled content specifications.
Supply Chain Analysis
Germany and the Netherlands anchor European thermoforming output for high-barrier dairy and deli applications, while the US Midwest concentrates thin-wall polypropylene production for food service channels. Raw material flows draw from Saudi Arabian and US Gulf Coast propylene monomer sources, with rPET feedstock increasingly sourced from Belgian and Dutch chemical recycling facilities. Single-source vulnerability concentrates in specialized thermoforming tool fabrication, where German and Austrian mold makers command 18-month lead times. Distribution runs through direct-to-retailer procurement contracts that displace traditional distributor intermediaries in North American grocery private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ready-to-eat meal penetration in European contract catering and Indian food processing marks this market as an early-cycle expansion story, with microwave-compatible polypropylene container adoption accelerating as FSSAI certification frameworks broaden.
For Market Incumbents: Compound barrier technology leadership through mono-material film lamination investments that consolidate multi-layer structures into single-substrate specifications. Defend position against chemical recycling entrants by locking long-term rPET and pyrolysis-derived polyolefin offtake agreements with Rotterdam-Antwerp cluster producers. Prioritize capacity addition in Maharashtra-Gujarat corridor to capture Indian ready-to-eat scale-up before local converters achieve FSSAI compliance scale. For New Entrants and Emerging Players: Differentiate on smart packaging convergence by integrating time-temperature indicators with injection-molded bases for cold-chain protein distributors seeking shelf-life extension propositions. Target India's emerging thermoforming investments as the most penetrable geography, where FSSAI certification gaps create virgin territory for microwave-compatible polypropylene specifications. Pursue direct procurement relationships with German supermarket chains consolidating toward integrated resin-to-container suppliers with verified recycled content documentation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with captive chemical recycling assets and backward integration into sheet extrusion. Five-to-ten year viability hinges on EU Packaging and Packaging Waste Regulation compliance infrastructure rather than virgin resin scale. Acquisition target archetype: mid-cap thermoformers with qualified rPET tray programs and established retailer sustainability scorecard relationships. Signal to watch: state-level extended producer responsibility enactments in California, Oregon, and Maine that trigger national distribution strategy consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Infrastructure Investment | Pyrolysis capacity buildouts in Netherlands and Belgium open compliant material pipelines for EU brands facing recycled content deadlines. |
| Direct-to-Retailer Procurement Contracts | Kroger and Albertsons category managers now negotiate specification and sustainability credential bundling directly with container converters. |
| Smart Packaging Integration | Time-temperature indicators laminated to injection-molded bases create differentiated shelf-life extension for cold-chain protein distributors. |
| India Manufacturing Footprint Expansion | Maharashtra-Gujarat thermoforming investments target domestic chilled meal penetration as FSSAI certification coverage broadens. |
| Mono-Material Barrier Film Development | Miniaturized multi-layer structures consolidate converting expertise among integrated sheet extruders serving German dairy processors. |
Study Parameters
The analysis maps plastic thermoforming, glass container, metal can, and fiberboard pulp molding sub-sectors, each validated through converter operations directors, retailer category buyers, food processor packaging engineers, and resin procurement leads. Primary interviews with these stakeholders triangulate against secondary sources including FDA 21 CFR filings, EU REACH authorization databases, FSSAI certification registries, and trade data from customs authorities. Bottom-up unit volume estimates reconcile with top-down value assessments across material and end-use segmentations.
Consistency checks validate volume and value outputs against external benchmarks including resin producer capacity disclosures, retailer sustainability scorecard requirements, and food service operator procurement patterns. The analytical framework models polypropylene, polyethylene, glass, metal, and fiberboard material segments across food service, retail, e-commerce, and catering end-use channels throughout the forecast period. CAGRs derive from segment-level adoption curves weighted by regulatory compliance timelines and capacity expansion announcements. Key inputs include thermoforming technician labor availability indices and chemical recycling facility commissioning schedules.
Material uncertainties — abrupt resin price spikes, accelerated EU recycled content deadline adjustments, and thermoforming skill gap intensification — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and feedstock cost correlation patterns that could shift with crude oil volatility or trade policy adjustments. Recalibration cycles align with material shifts in EU Packaging and Packaging Waste Regulation implementation timelines and state-level extended producer responsibility enactments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market