
 United States Rigid PET Packaging Market | 2026-2036
United States Rigid PET Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Rigid PET Packaging Market Outlook
Modular bottle-and-cap configurations is restructuring procurement patterns among mid-sized beverage bottlers seeking line flexibility. Amcor Limited leverages integrated preform-to-bottle manufacturing to sustain cost advantages across high-volume contracts. Berry Global anchors its position through specialized pharmaceutical-grade barrier technologies. Sonoco Products Company differentiates via rigid tray formats serving prepared food channels.
United States Rigid PET Packaging comprises thermoformed or injection-stretch-blown polyethylene terephthalate structures engineered with intrinsic viscosity between 0.70 and 0.84 dL/g, delivering oxygen-barrier performance critical for carbonated beverage shelf stability and pharmaceutical protection. The bottles category dominates value contribution due to carbonated soft drink and bottled water volume concentration, while trays represent the fastest-expanding format as retail-ready meal packaging displaces flexible alternatives in deli and produce applications. Jars occupy specialized margin pools in nut butter and condiment segments where clarity and resealability command premium positioning.
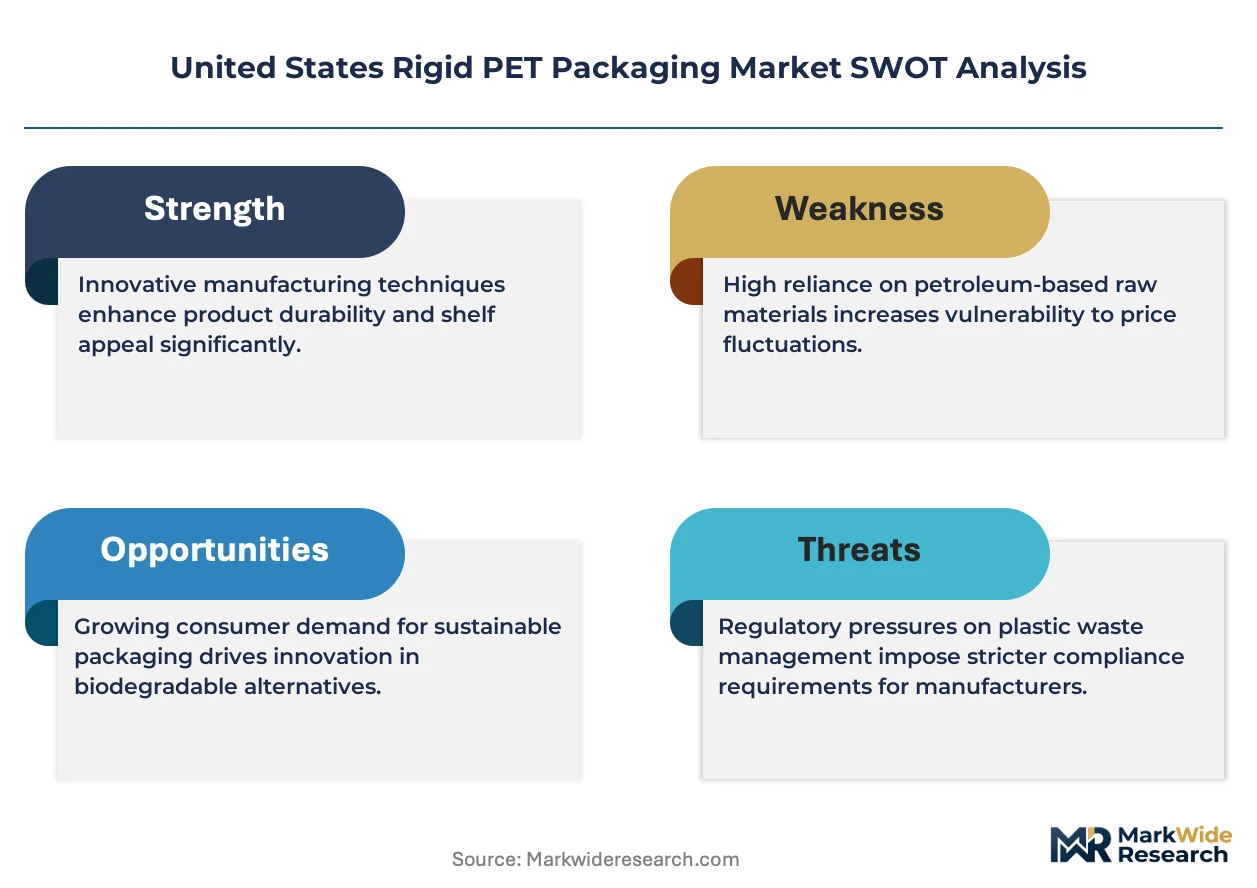
FDA food-contact notification requirements and EPA recycled-material procurement guidelines shape resin qualification pathways and limit rapid supplier switching for food-grade applications. State-level extended producer responsibility frameworks emerging in California and New York are tightening post-consumer content thresholds, forcing converters to validate rPET flake sourcing or risk distributor disqualification. Stakeholders must monitor how FDA modernization of food-contact recycling processes intersects with state implementation timelines to avoid stranded capacity investments.
Market Dynamics
State-level recycled-content mandates are compressing converter qualification timelines while FDA food-contact notification requirements lock in resin supplier relationships, creating a dual-layer sourcing constraint that favors integrated preform-to-bottle manufacturers with validated rPET flake pipelines.
Growth Catalysts
- California and New York EPR frameworks:These state-level extended producer responsibility laws are mandating post-consumer recycled thresholds, forcing bottlers to secure qualified rPET sources ahead of compliance deadlines.
- Lightweighting technology:Advanced injection-stretch-blow molding processes are reducing gram weight per bottle without compromising carbonation barrier performance, cutting resin input costs for high-volume beverage lines.
- Southeast manufacturing corridor concentration:Proximity between resin conversion facilities and major bottling operations in Georgia, Tennessee, and the Carolinas is minimizing freight costs and inventory carrying requirements.
Market Restraints
- rPET flake supply concentration:Limited domestic bottle-to-bottle recycling infrastructure concentrates qualified recycled feedstock among a handful of specialized reclaimers, creating input bottlenecks.
- Intrinsic viscosity degradation:Mechanical recycling processes reduce PET molecular weight below pharmaceutical-grade thresholds, restricting rPET penetration in barrier-critical drug packaging.
- Propylene glycol terephthalate substitution:Bio-based PGT resins are gaining traction in premium condiment and personal care segments where brand owners prioritize renewable content claims over cost optimization.
Strategic Opportunities
- Midwestern prepared food expansion:Retail-ready meal packaging demand in Illinois, Ohio, and Michigan is outpacing flexible format displacement, opening tray capacity for converters with thermoforming expertise.
- FDA modernization of food-contact recycling:Streamlined notification pathways for novel recycling technologies could accelerate chemical recycling validation and unlock non-bottle feedstock streams.
- Pharmaceutical serialization convergence:Integration of rigid PET barrier bottles with track-and-trace authentication technologies is creating premium positioning for converters with blow-fill-seal capabilities.
Industry Challenges
- Blow molding technician scarcity:Specialized expertise in injection-stretch-blow process optimization and mold temperature control is concentrated among aging workforce cohorts, constraining line expansion.
- Multi-layer co-injection capex requirements:Oxygen-scavenging barrier technologies demand capital-intensive equipment upgrades that mid-tier converters struggle to justify against contract duration uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Rigid PET Packaging Market |
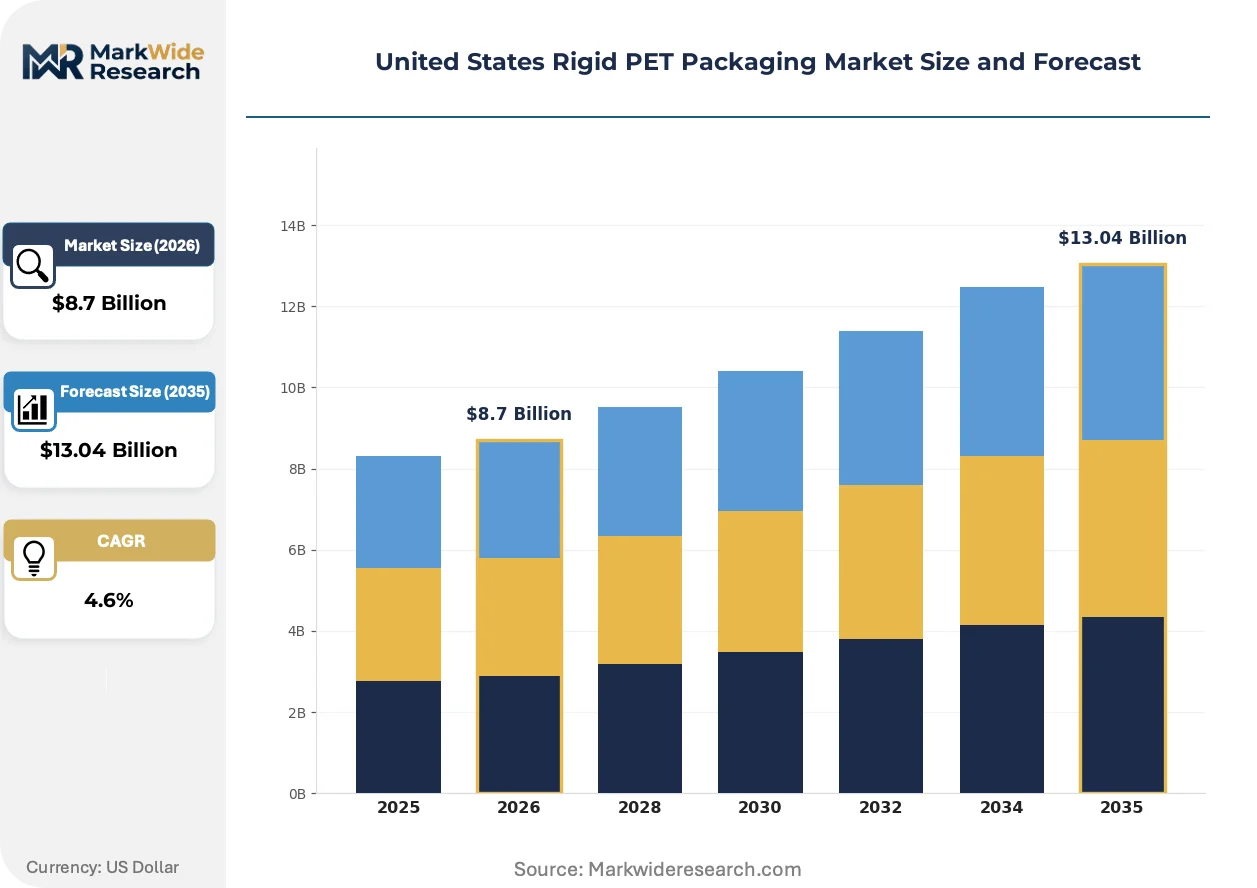
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Trays End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Household Capacity: Less than 500ml, 500ml to 1L, 1L to 5L, Above 5L Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Mondi Group, Pactiv Evergreen, Amcor Limited, Anchor Packaging, Sonoco Products Company, Berry Global, Smurfit Kappa Group, Genpak, CCL Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Rigid PET Packaging Market Strategic Shifts
Digital manufacturing controls and advanced barrier formulations are restructuring how converters compete on speed-to-market and specification flexibility, compressing traditional advantages of scale.
Active barrier scavenger technologies are converging with monolayer blow molding platforms to deliver extended shelf life without multi-layer co-injection complexity. Mid-sized dairy and functional beverage bottlers are adopting these systems to avoid premium licensing fees for oxygen-barrier patents. The convergence is enabling regional converters to challenge national suppliers on carbonated soft drink contracts previously secured through proprietary barrier film supply agreements.
FDA's draft guidance on post-consumer recycled plastic in food-contact articles is tightening documentation requirements for contamination screening and challenge testing protocols. Converters must now maintain chain-of-custody records from flake sourcing through final article production, elevating compliance costs for smaller operations. The beverage bottling segment is responding by consolidating supplier panels to partners with established food-contact notification portfolios.
Direct-to-retail procurement contracts are displacing traditional distributor-mediated resin purchasing among large-format retail chains with private-label beverage programs. These buyers are negotiating resin-price pass-through clauses and volume commitments directly with converters, compressing margins on intermediary distribution. The shift is most visible in the club store and dollar store channels where SKU proliferation demands rapid format changeover capabilities.
United States Rigid PET Packaging Market Segmentation
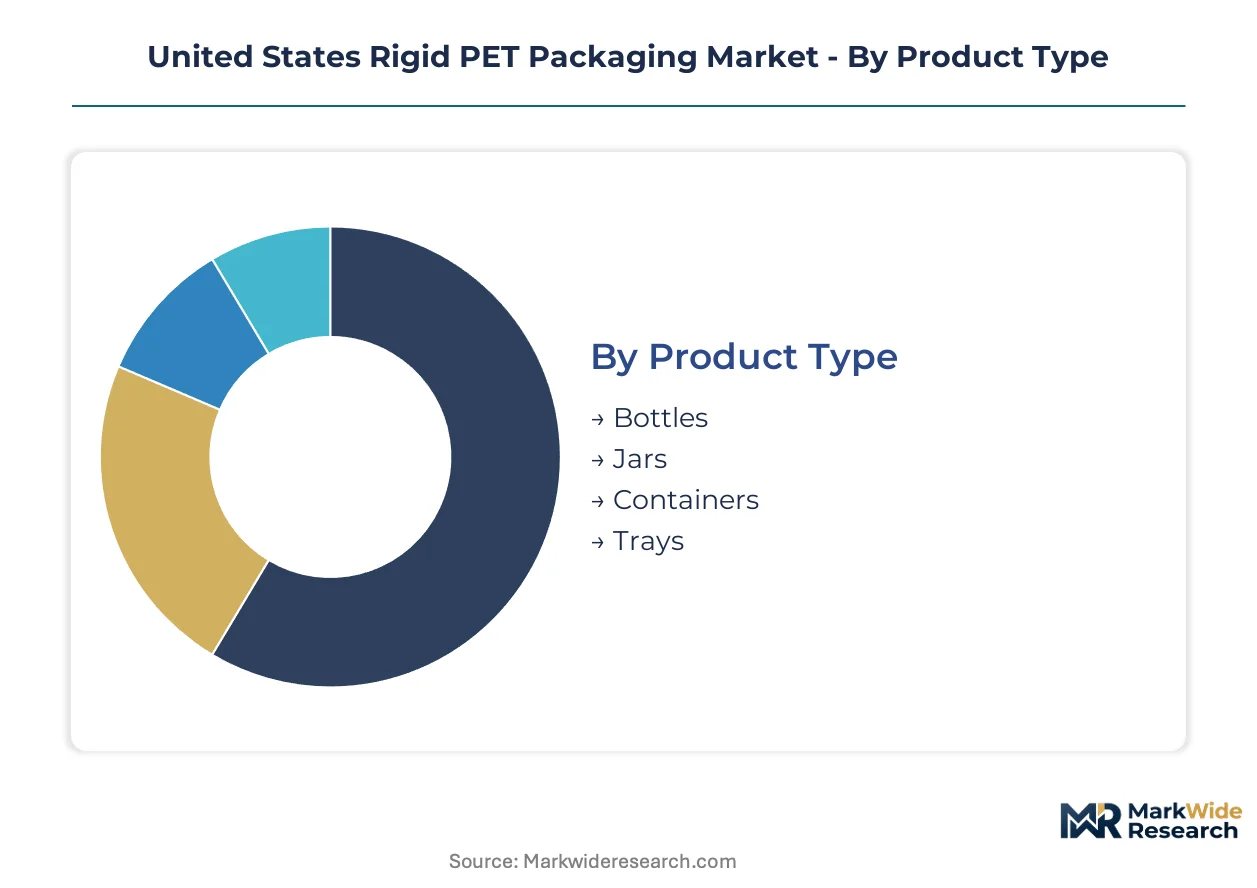
Segmentation in rigid PET packaging reveals how specification requirements fragment across end-use applications, with food-contact compliance, barrier performance, and format flexibility driving divergent procurement patterns among converters and brand owners.
Product Type:
Standalone bottle formats dominate high-volume beverage contracts, while embedded tray systems integrate into retail-ready meal packaging workflows requiring thermoforming precision.
- Bottles:Injection-stretch-blown structures with intrinsic viscosity between 0.70 and 0.84 dL/g deliver oxygen-barrier performance for carbonated soft drink and bottled water shelf stability. Demand concentrates in the Southeast manufacturing corridor where Georgia and Tennessee bottling operations cluster near resin conversion facilities, driven by lightweighting adoption across carbonated and still drink lines.
- Trays:Thermoformed formats with controlled crystallinity enable retail-ready meal packaging for deli and produce applications where clarity and dimensional stability displace flexible alternatives. Illinois, Ohio, and Michigan prepared food channels are outpacing national growth, opening capacity for converters with rapid format changeover capabilities.
- Jars:Wide-mouth configurations serve nut butter and condiment segments where resealability commands premium positioning.
- Containers:Specialized formats accommodate household and industrial chemical applications requiring modified PET copolymers for enhanced chemical resistance.
Bottles lead volumes today; trays are gaining share fastest.
End Use Industry:
Cost-tier differentiation separates commodity beverage applications from pharmaceutical-grade barrier specifications requiring validated resin qualification pathways.
- Food & Beverage:Carbonated soft drinks, bottled water, and ready-to-drink beverages represent the volume foundation, with FDA food-contact notification requirements locking in resin supplier relationships and limiting rapid switching.
- Pharmaceuticals:Barrier-critical drug packaging demands intrinsic viscosity maintenance above pharmaceutical-grade thresholds, restricting rPET penetration due to mechanical recycling degradation. Blow-fill-seal capabilities with track-and-trace authentication integration create premium positioning opportunities.
- Personal Care:Bio-based PGT resin substitution is gaining traction where renewable content claims outweigh cost optimization priorities.
- Household:Industrial chemical compatibility requirements favor modified PET copolymers with enhanced resistance profiles.
Food & Beverage dominates volume contribution; Pharmaceuticals commands the steepest margin expansion trajectory.
Capacity:
Volume-scale economics favor mid-range formats where production line standardization minimizes changeover downtime.
- 500ml to 1L:Single-serve beverage and functional drink applications concentrate procurement in this range, with lightweighting technology reducing gram weight per bottle without compromising carbonation barrier performance.
- 1L to 5L:Family-size and club-store formats benefit from direct-to-retail procurement contracts with resin-price pass-through clauses.
- Less than 500ml:Sample-size and travel-format applications serve premium positioning strategies.
- Above 5L:Industrial and institutional bulk formats require specialized handling equipment and distribution infrastructure.
500ml to 1L leads volumes today; 1L to 5L is climbing the fastest.
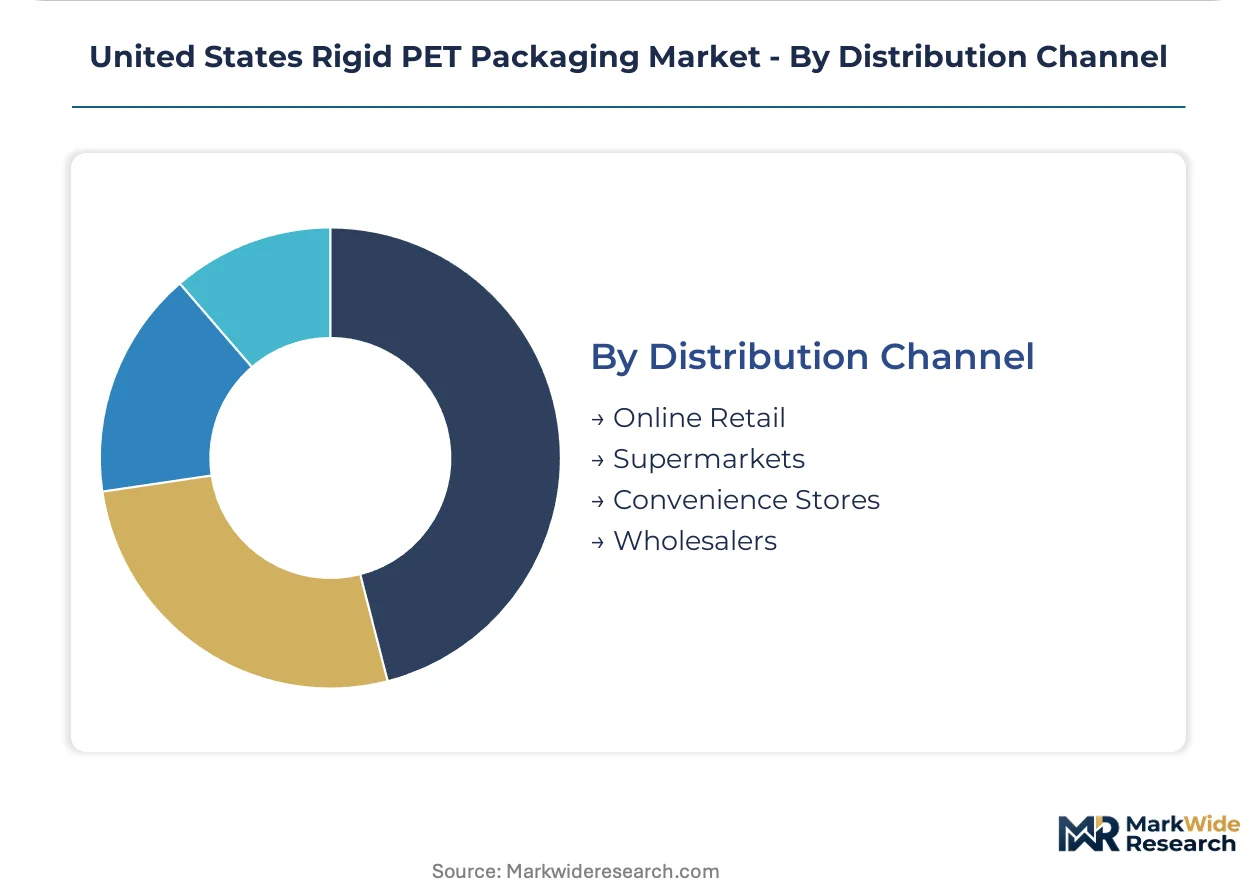
Distribution Channel:
Customer-type fragmentation separates traditional distributor-mediated purchasing from direct converter relationships among large-format retail chains.
- Supermarkets:Private-label beverage programs and retail-ready meal packaging drive format standardization requirements, with direct procurement contracts displacing traditional distributor relationships.
- Online Retail:E-commerce fulfillment demands optimized cube utilization and damage-resistant packaging specifications.
- Convenience Stores:Grab-and-go beverage formats prioritize shelf-ready presentation and rapid replenishment logistics.
- Wholesalers:Traditional distribution intermediaries face margin compression as club store and dollar store channels consolidate supplier panels.
Supermarkets lead volumes today; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States rigid PET packaging industry traces its modern scale to 1970s carbonated beverage bottling expansion in the Southeast, where resin conversion infrastructure first clustered near Atlanta and Charlotte to serve Coca-Cola and Pepsi bottling networks.
Southeast Manufacturing Corridor
Georgia and Tennessee anchor the highest concentration of injection-stretch-blow molding capacity, driven by carbonated soft drink and bottled water bottlers demanding lightweight formats. FDA food-contact notification requirements lock in resin supplier relationships, limiting rapid switching among converters. The Atlanta-Charlotte corridor hosts integrated preform-to-bottle manufacturers with validated rPET flake pipelines serving Coca-Cola and Pepsi bottling operations.
Midwest Prepared Food Belt
Illinois, Ohio, and Michigan generate outsized demand for thermoformed tray formats as retail-ready meal packaging displaces flexible alternatives in deli and produce channels. State-level extended producer responsibility frameworks emerging in neighboring jurisdictions are tightening post-consumer content thresholds. Chicago and Detroit metropolitan areas concentrate thermoforming expertise among converters serving Kroger, Meijer, and regional grocery private-label programs.
California Regulatory Frontier
The state mandates aggressive post-consumer recycled content thresholds through its extended producer responsibility framework, forcing bottlers to secure qualified rPET sources ahead of compliance deadlines. CalRecycle enforcement mechanisms are disqualifying converters without validated chain-of-custody documentation. Los Angeles and Central Valley bottling operations are consolidating supplier panels to partners with established food-contact notification portfolios.
New York Metro Distribution Hub
The metropolitan area functions as the primary distribution gateway for imported PET resin and finished packaging serving Northeast beverage and food manufacturers. New York State's emerging EPR legislation mirrors California's recycled-content mandates, creating dual-coast compliance pressure. Port Newark-Elizabeth processing facilities and New Jersey warehousing clusters enable rapid format changeover capabilities demanded by club store and dollar store channels.
Pacific Northwest Sustainability Cluster
Oregon and Washington beverage bottlers prioritize renewable content claims and lightweighting adoption to differentiate in premium functional drink segments. EPA recycled-material procurement guidelines shape resin qualification pathways for converters serving organic and natural product brands. Seattle and Portland metropolitan areas host specialized operations integrating digital manufacturing controls with monolayer barrier technologies.
United States Rigid PET Packaging Market Competitive Environment
The competitive structure tilts toward integrated preform-to-bottle manufacturers with captive resin conversion capabilities. National-scale converters dominate high-volume beverage contracts through economies of scale in lightweighting technology, while mid-tier specialists occupy pharmaceutical-grade and retail-ready meal packaging niches requiring thermoforming precision. Three archetypes define positioning: integrated resin-to-article manufacturers, barrier-technology specialists, and format-flexible regional converters. Capacity expansion and validated rPET flake pipeline development constitute the dominant competitive moves as state mandates compress qualification timelines.
Among the integrated manufacturing tier, Amcor Limited and Berry Global exemplify scale-driven positioning through captive preform production and food-contact notification portfolios. Sonoco Products Company occupies a specialized position representing the format-differentiation archetype through rigid tray expertise. These three entities anchor the supplier consolidation trend as beverage bottlers narrow procurement panels to partners capable of documenting chain-of-custody compliance from flake sourcing through final article production.
| Leading Market Players |
|---|
| Mondi Group |
| Pactiv Evergreen |
| Amcor Limited |
| Anchor Packaging |
| Sonoco Products Company |
| Berry Global |
| Smurfit Kappa Group |
| Genpak |
| CCL Industries |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade intrinsic viscosity certification creates a bifurcated cost structure that separates barrier-critical drug packaging from commodity beverage applications, with FDA food-contact notification requirements locking in premium resin supplier relationships while lightweighting technology compresses margins across high-volume carbonated soft drink contracts. This tier divergence manifests in supply chain configurations where integrated preform-to-bottle manufacturers capture pricing power through validated rPET flake pipelines, while mid-tier converters face input cost volatility from limited domestic bottle-to-bottle recycling infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement dynamics, with pharmaceutical-grade barrier specifications and FDA food-contact certification tiers driving differentiation. Price differentiation stems from intrinsic viscosity maintenance requirements and volume scale commitments in direct-to-retail contracts. Cost compression in the beverage segment is intensifying because lightweighting adoption reduces gram weight per bottle without compromising carbonation barrier performance. Club store and dollar store channels exhibit the highest price sensitivity, while pharmaceutical bottlers prioritize barrier performance over unit cost optimization.
Supply Chain Analysis
Bottle-to-bottle recycling returns and rPET flake refurbishment flows concentrate qualified feedstock among specialized reclaimers in Georgia, Tennessee, and the Carolinas, creating reverse-logistics dependencies for converters serving California and New York compliance deadlines. Raw material inputs draw from virgin PET resin producers, mechanical recycling operations, and emerging chemical recycling technologies. Single-source vulnerability runs through the limited domestic rPET flake pipeline validated for food-contact applications. Distribution runs through direct converter relationships with large-format retail chains and traditional wholesaler intermediaries serving regional grocery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United States rigid PET Packaging operates as a regulatory compounder where state-level extended producer responsibility mandates in California and New York are forcing accelerated rPET qualification timelines and supplier panel consolidation ahead of compliance deadlines.
For Market Incumbents: Extend food-contact notification portfolios to capture pharmaceutical-grade barrier contracts before chemical recycling technologies mature and erode mechanical recycling's quality advantage. Deepen backward integration into validated rPET flake sourcing to defend against supply concentration among specialized reclaimers, while expanding thermoforming capacity in the Midwest prepared food belt to offset margin compression in lightweighted beverage formats. For New Entrants and Emerging Players: Regional dairy and functional beverage bottlers represent an underserved buyer archetype seeking monolayer active barrier scavenger technologies without multi-layer co-injection licensing fees. Penetrate the Illinois-Ohio-Michigan retail-ready meal packaging corridor where rapid format changeover capabilities outrank scale economics, and pursue a co-development go-to-market angle with mid-sized converters lacking in-house barrier R&D. For Investors and Strategic Acquirers: Consolidation pressure builds where blow molding technician scarcity constrains line expansion and aging workforce cohorts concentrate specialized expertise among legacy operators. Long-term viability favors integrated preform-to-bottle manufacturers with captive resin conversion and established FDA food-contact portfolios over format-flexible regional converters vulnerable to distributor disqualification. Watch for FDA modernization of food-contact recycling processes as the inflection signal that unlocks chemical recycling validation and reshapes rPET supply economics.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Flake Pipeline Validation | California CalRecycle enforcement mechanisms disqualify converters without chain-of-custody documentation. |
| Monolayer Barrier Technology Adoption | Active scavenger systems enable regional converters to challenge national suppliers on carbonated soft drink contracts. |
| Midwest Thermoforming Capacity Expansion | Illinois and Ohio retail-ready meal packaging demand outpaces national growth in deli and produce channels. |
| Direct-to-Retail Procurement Contracts | Club store and dollar store channels negotiate resin-price pass-through clauses compressing intermediary margins. |
| Blow-Fill-Seal Capability Integration | Pharmaceutical serialization convergence creates premium positioning for track-and-trace authentication technologies. |
Study Parameters
Multiple input streams — converter production data, resin qualification records, and state regulatory filings — were reconciled through bottom-up and top-down triangulation. Primary interviews with blow molding technicians, FDA regulatory affairs specialists, beverage procurement directors, and thermoforming operations managers were validated against secondary sources including FDA food-contact notification databases, EPA recycled-material procurement guidelines, CalRecycle enforcement records, and SEC filings from publicly traded packaging converters.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, modeling segmentation dimensions spanning product type, end-use industry, capacity tier, and distribution channel alongside regional compliance cluster dynamics. CAGRs were derived from trend extrapolation of lightweighting adoption rates and rPET penetration curves, with forecast inputs incorporating state EPR implementation timelines and FDA modernization pathways for novel recycling technologies.
Underlying measurement precision varies by segment; pharmaceutical-grade barrier specifications and validated rPET flake sourcing carry tighter precision than emerging chemical recycling adoption curves. Forecasts reflect assumptions regarding state mandate enforcement consistency and mechanical recycling quality maintenance that could revise projections if chemical recycling achieves food-contact validation earlier than modeled. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market