
 Mexico Rigid Plastic Packaging Market | 2026-2036
Mexico Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Rigid Plastic Packaging Market Foresight
Skilled blow-molding technicians is reorganizing plant expansion timelines across central Mexico. ALPLA México SA de CV leverages captive resin conversion to sustain margin stability in PET preforms. Grupo Phoenix anchors its position through diversified container formats serving household and personal care accounts. Berry Global Inc. competes on thermoformed tray specialization for protein packaging in refrigerated supply chains.
Mexico Rigid Plastic Packaging comprises injection-molded, blow-molded, or thermoformed polymer structures with wall thickness exceeding 0.25 millimeters, engineered to protect contents from moisture, oxygen ingress, and mechanical damage during distribution. These structures serve primary containment for food, beverages, pharmaceuticals, and consumer chemicals across retail and institutional channels. Bottles command the largest volume share within Product Type, though trays are gaining share from meat and fresh produce processors seeking modified-atmosphere configurations. Polyethylene leads the Material hierarchy by tonnage, while PET posts faster growth from bottled water and carbonated drink bottlers converting from glass. Food & Beverage dominates End User demand, with Pharmaceutical representing a higher-margin pocket where barrier specifications and child-resistant closures justify premium positioning.
SEMARNAT enforces federal waste management norms that obligate packaging producers to fund collection and recycling infrastructure, directly elevating demand for rPET and post-industrial regrind content. NOM-252-SSA1-2011 governs food-contact polymer safety, while PROFECO monitors labeling accuracy and net content compliance in consumer-facing rigid containers. Stakeholders must track state-level plastic restriction proposals in Mexico City, Jalisco, and Quintana Roo that could abruptly reshape allowable formats for single-use applications.
Market Dynamics
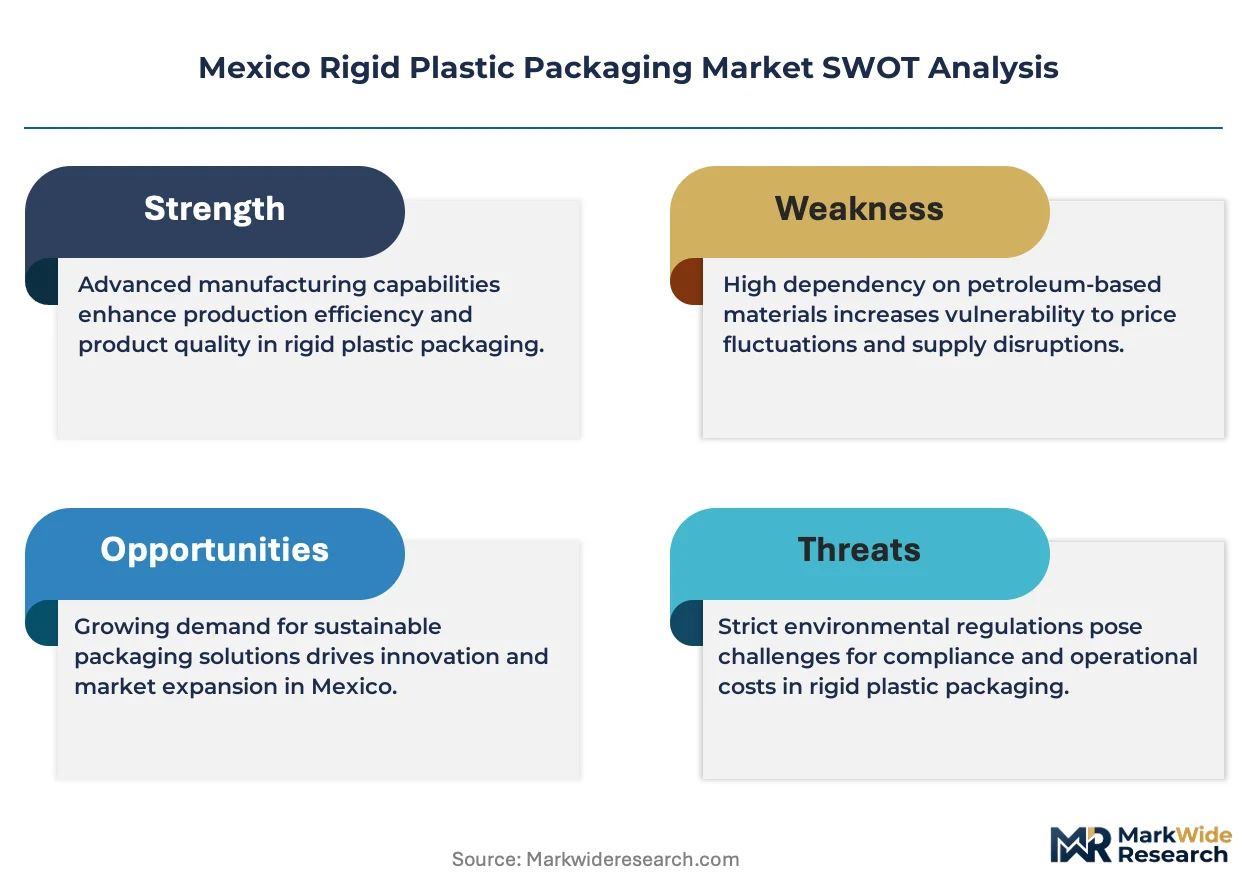
SEMARNAT's tightened extended producer responsibility rules are forcing converters to restructure resin sourcing and fund post-consumer collection infrastructure, compressing margins for non-integrated processors while advantaging those with captive recycling capabilities.
Growth Catalysts
- Bottled water conversion from glass:Carbonated soft drink and still water bottlers in the Bajío corridor are accelerating PET bottle procurement to reduce breakage and logistics costs in refrigerated distribution.
- Modified-atmosphere tray adoption:Meat and fresh produce processors are specifying thermoformed barrier configurations to extend shelf life in modern retail cold chains.
- NOM-252-SSA1-2011 compliance:Food-contact safety mandates are consolidating demand toward certified converters with documented polymer traceability and migration testing protocols.
Market Restraints
- rPET feedstock scarcity:Post-consumer flake supply in central Mexico lags converter demand, forcing reliance on imported regrind and virgin resin price linkage.
- Skilled blow-molding technician shortage:Technical training pipelines in Querétaro and Guanajuato cannot match plant expansion timelines, delaying commissioning.
- State-level restriction uncertainty:Proposed single-use plastic bans in Mexico City, Jalisco, and Quintana Roo create format-specific demand risk without federal preemption clarity.
Strategic Opportunities
- Pharmaceutical barrier packaging:Child-resistant closures and oxygen-scavenging structures command premium positioning in prescription and over-the-counter drug distribution.
- Aguascalientes logistics hub:The state's central rail and highway connectivity offers untapped thermoformed tray supply to northern meatpacking clusters.
- Post-industrial regrind integration:Processors with in-house grinding of sprue and trim waste can meet SEMARNAT recovery targets while insulating margin from virgin resin volatility.
Industry Challenges
- PROFECO labeling compliance:Net content verification and accuracy monitoring require dedicated quality personnel and sampling protocols that extend order-to-delivery cycles.
- Multi-cavity mold commissioning:High-output preform production lines demand six-month lead times for tool validation and process window establishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Rigid Plastic Packaging Market |
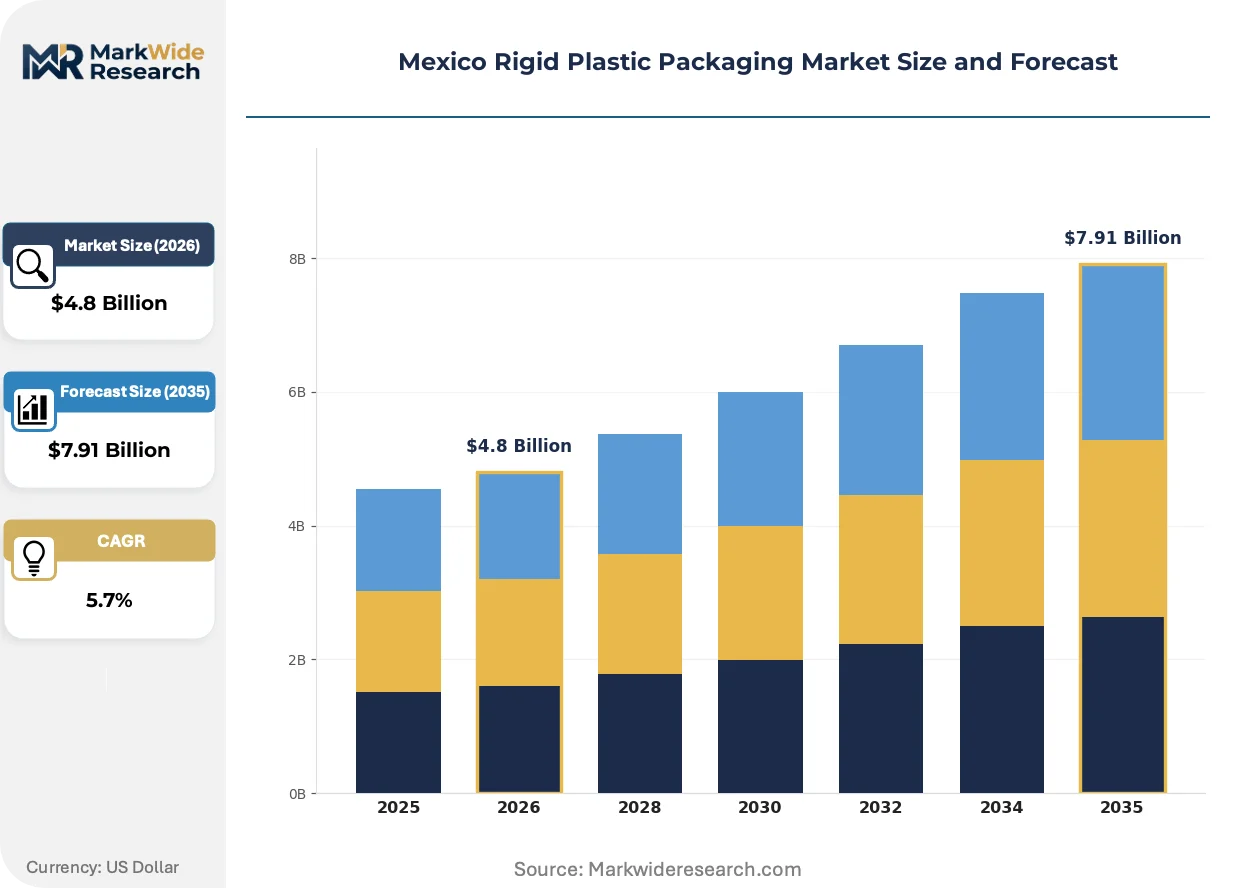
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays Material: Polyethylene, Polypropylene, PVC, PET End User: Food & Beverage, Personal Care, Pharmaceutical, Household Form: Rigid, Semi-Rigid, Custom, Standard |
| Companies Covered | Sonoco México, Coexpan México SA de CV, Amcor plc, Amcor Rigid Packaging Mexico, Grupo Phoenix, ALPLA México SA de CV, Greif Inc., Berry Global Inc., AptarGroup Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Rigid Plastic Packaging Market Shifts & Advancements
Converter technology roadmaps are splitting between high-speed commodity output and specialized barrier structures, with regulatory pressure and end-use certification requirements determining which path individual processors pursue.
Lightweighting technology is bifurcating the PET bottle segment. Neck finish reduction and wall-thickness optimization preserve mechanical performance while cutting resin content per unit. Carbonated beverage bottlers in Guanajuato are adopting these designs fastest, displacing heavier legacy preforms from smaller regional converters unable to fund mold retrofits.
SEMARNAT's federal waste management norms are mandating producer-funded collection infrastructure. Packaging converters must now finance post-consumer recovery systems through eco-modulated fees tied to recyclability scores. Food and beverage brands with national distribution are responding fastest, pressuring suppliers for rPET certificates and mass-balance documentation.
Consolidated procurement by retail chains is compressing supplier bases. Walmart México and Soriana are reducing rigid packaging vendor counts from twelve to four per category, replacing fragmented regional supply with national frame contracts. This concentration is most visible in refrigerated protein trays, where thermoformed specifications now flow through centralized technical teams rather than individual store formats.
Mexico Rigid Plastic Packaging Market Segmentation
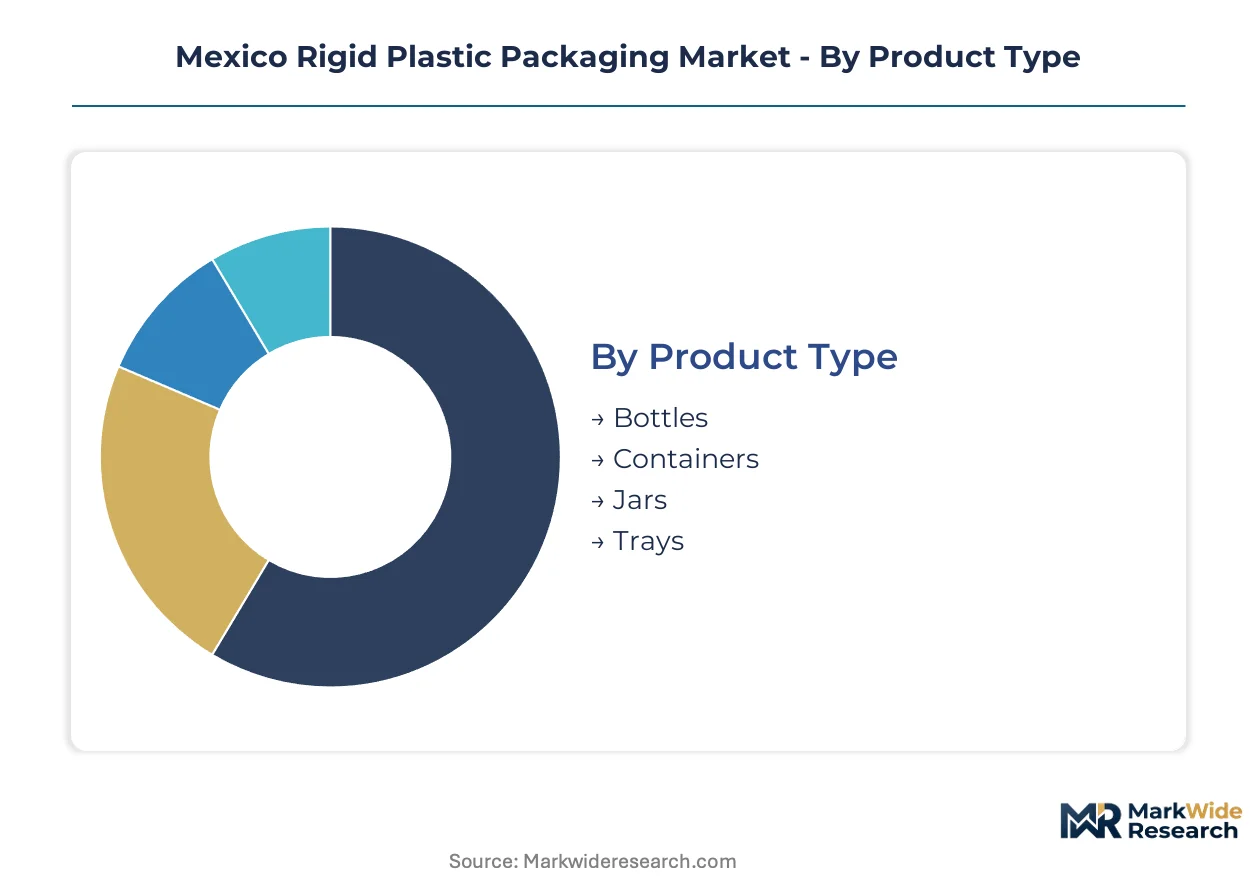
Mexico's rigid plastic packaging market fragments across four structural dimensions that determine resin procurement patterns, conversion technology investments, and regulatory compliance burdens. Each segmentation axis reveals distinct channel concentrations and margin profiles that shape supplier positioning in the Bajío corridor and beyond.
Product Type:
Bottles flow predominantly through beverage bottler direct procurement channels, while trays concentrate in meatpacker and retail private-label supply chains. Jars and containers split between institutional foodservice distributors and consumer goods brand owners with distinct specification requirements.
- Bottles:Blow-molded PET structures with neck finish precision engineered for carbonated soft drink and bottled water capping systems. Demand concentrates in Guanajuato and Querétaro bottling plants where lightweighting retrofits are displacing heavier legacy preforms from regional converters lacking mold investment capacity.
- Trays:Thermoformed barrier configurations with modified-atmosphere specifications for protein and fresh produce shelf-life extension. Expansion concentrates in refrigerated supply chains serving northern Mexico meatpacking clusters where Walmart México and Soriana are consolidating vendor bases from twelve suppliers to four per category.
- Containers:Injection-molded tubs and pails serving household chemical and institutional foodservice accounts with UN certification requirements for hazardous contents.
- Jars:Wide-mouth configurations for personal care creams and pharmaceutical ointments where child-resistant closure compatibility drives specification.
Bottles dominate installed base by unit volume. Trays represent where expansion concentrates most steeply.
Material:
Resin selection determines compliance pathway under SEMARNAT extended producer responsibility rules and NOM-252-SSA1-2011 food-contact safety mandates. Cost tiers separate virgin resin converters from those with captive recycling capabilities.
- Polyethylene:HDPE and LDPE grades command largest tonnage position across injection-molded containers and extruded sheets. Demand concentrates in household chemical and institutional pail applications where cost minimization outweighs optical clarity requirements.
- PET:Virgin and rPET grades for bottle and tray applications with oxygen barrier specifications. Bottled water and carbonated drink bottlers in the Bajío corridor are accelerating procurement to reduce breakage and logistics costs versus glass alternatives.
- Polypropylene:Clarified and impact-copolymer grades for hot-fill containers and medical trays requiring autoclave sterilization compatibility.
- PVC:Rigid formulations for blister packs and pharmaceutical primary packaging with established migration testing documentation.
Polyethylene anchors volume share. PET climbs the fastest as beverage conversion accelerates.
End User:
Customer type determines margin structure and certification burden. Food and beverage accounts drive scale economics while pharmaceutical and personal care segments justify premium positioning through barrier specifications.
- Food & Beverage:Largest demand segment spanning carbonated drinks, bottled water, dairy, and processed meat packaging. Procurement consolidates under national frame contracts with centralized technical teams replacing fragmented regional supply arrangements.
- Pharmaceutical:Child-resistant closures and oxygen-scavenging structures for prescription and over-the-counter distribution. PROFECO labeling accuracy requirements and NOM-252-SSA1-2011 migration testing extend order-to-delivery cycles.
- Personal Care:Cosmetic jars and dispensing containers with aesthetic surface finish requirements and fragrance barrier specifications.
- Household:Chemical-resistant containers for cleaners and pesticides with UN certification for hazardous material transport.
Food & Beverage dominates unit demand. Pharmaceutical represents the highest-margin pocket.
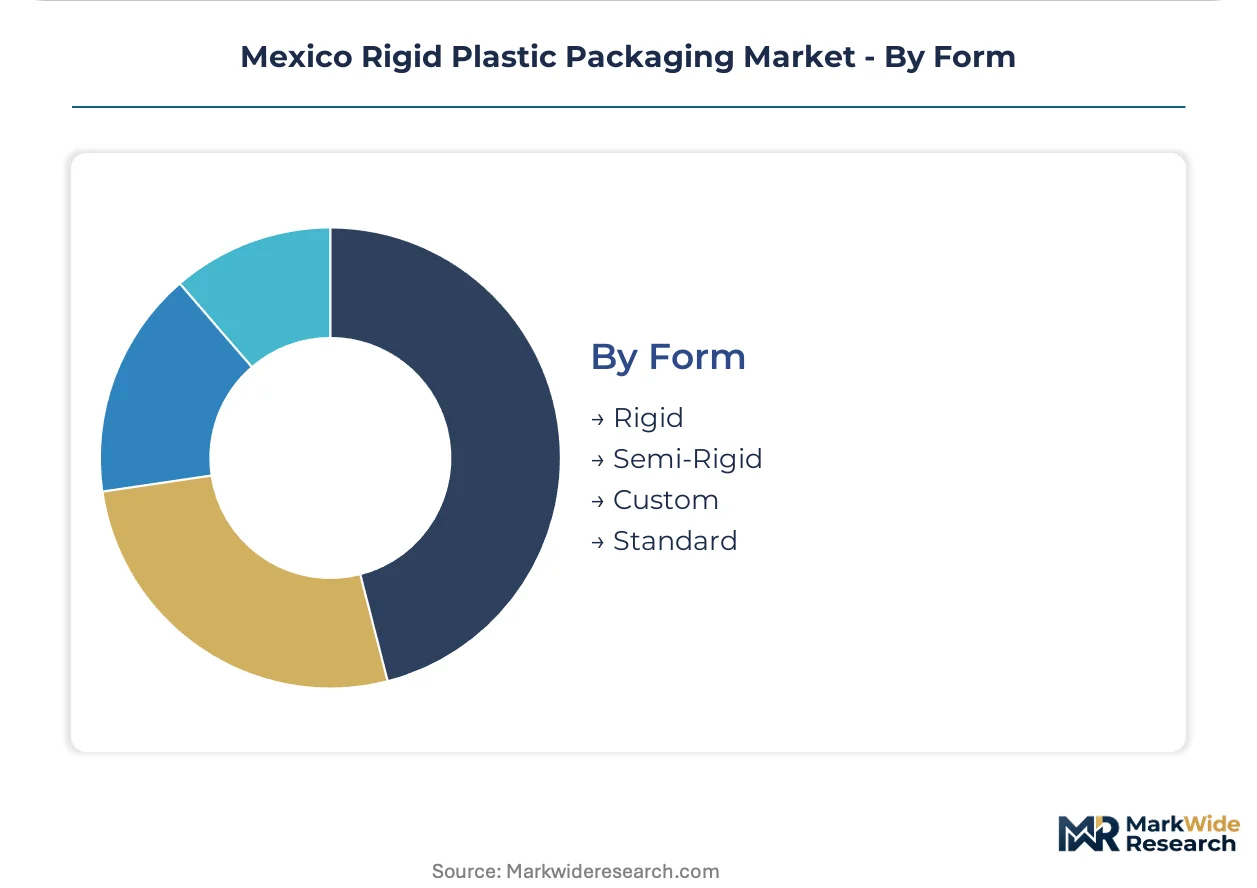
Form:
Manufacturing configuration determines capital intensity and mold amortization economics. Standard formats achieve scale through multi-cavity tooling while custom configurations command specification premiums.
- Rigid:Wall thickness exceeding 0.25 millimeters with structural integrity for stacking and distribution handling. Standard across bottles, containers, and jars with established blow-molding and injection-molding process windows.
- Semi-Rigid:Reduced wall sections with thermoformed tray configurations for modified-atmosphere protein packaging. Aguascalientes logistics connectivity offers untapped supply positioning for northern meatpacking clusters.
- Standard:Catalog formats with amortized tooling and shortest lead times for high-volume beverage and food accounts.
- Custom:Proprietary designs with dedicated mold investment and extended validation protocols for pharmaceutical and premium personal care brand owners.
Rigid structures dominate installed capacity. Semi-Rigid formats gain share fastest from meat and produce processor adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bajío corridor commands premium pricing power over northern border states, where logistics proximity to US markets inflates input costs without matching value capture in rigid plastic packaging conversion.
Bajío Region
Carbonated beverage bottlers and fresh produce processors drive PET bottle and modified-atmosphere tray procurement. SEMARNAT's extended producer responsibility rules obligate converters here to fund post-consumer collection infrastructure. Querétaro and Guanajuato host the densest blow-molding plant clusters, where lightweighting retrofits are displacing heavier legacy preforms.
Nuevo León
Monterrey-based meatpackers and household chemical formulators sustain demand for thermoformed barrier trays and injection-molded containers. State environmental agencies coordinate with federal norms on industrial waste tracking. The Apodaca industrial park concentrates thermoforming capacity serving Walmart México's northern distribution network.
Jalisco
Tequila exporters and pharmaceutical compounders generate specialized packaging requirements for spirit bottles and child-resistant closures. Proposed state-level single-use plastic restrictions create format-specific demand uncertainty without federal preemption clarity. Guadalajara's logistics hub anchors supply to Pacific coast retail chains.
Mexico City Metro
Centralized procurement by retail headquarters and pharmaceutical distributors concentrates high-specification container demand. PROFECO labeling accuracy enforcement extends order-to-delivery cycles for consumer-facing rigid containers. The Toluca corridor supplies converted packaging to institutional foodservice accounts.
Northern Border States
Maquiladora operations and cross-border logistics providers sustain demand for durable shipping containers and UN-certified hazardous material packaging. US EPA and Mexican SEMARNAT dual compliance requirements elevate certification burdens. Tijuana and Ciudad Juárez house specialized converters serving California and Texas distribution channels.
Mexico Rigid Plastic Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Mexico's rigid plastic packaging market. Vertically integrated resin converters with captive recycling capabilities capture margin stability under SEMARNAT's tightened recovery mandates, while non-integrated processors face compressed profitability from imported rPET feedstock reliance. Three archetypes dominate: multinational specialists with barrier technology portfolios, regional scale players with Bajío corridor density, and diversified converters spanning multiple polymer formats. Consolidation proceeds through national frame contract capture with retail chains and backward integration into post-industrial regrind processing.
Among multinational specialists, Amcor plc and Berry Global Inc. occupy positions defined by thermoformed tray specialization and pharmaceutical barrier specifications. ALPLA México SA de CV anchors the regional scale tier through captive resin conversion and PET preform concentration in central Mexico. Grupo Phoenix exemplifies diversified format coverage across household and personal care accounts with multi-material flexibility.
| Leading Market Players |
|---|
| Sonoco México |
| Coexpan México SA de CV |
| Amcor plc |
| Amcor Rigid Packaging Mexico |
| Grupo Phoenix |
| ALPLA México SA de CV |
| Greif Inc. |
| Berry Global Inc. |
| AptarGroup Inc. |
| Others |
Supply & Pricing Matrix
rPET substitution for virgin PET resin is redrawing procurement geography across central Mexico, simultaneously compressing margins for converters dependent on imported regrind while rewarding Bajío corridor processors with captive recycling infrastructure and localized feedstock security.
Pricing Analysis
The customization-premium spread separates commodity PET preforms from modified-atmosphere barrier trays and pharmaceutical-grade containers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under NOM-252-SSA1-2011 and volume scale of national frame contracts. Cost compression in standard beverage bottles is intensifying because Walmart México and Soriana are consolidating vendor bases from twelve suppliers to four per category. Food and beverage processors show highest price sensitivity, while pharmaceutical brand owners absorb premium positioning for child-resistant closure compatibility and oxygen-scavenging specifications.
Supply Chain Analysis
Mexico and the United States anchor resin supply, with HDPE and PET feedstock flowing from Gulf Coast petrochemical complexes and domestic polymerization plants in Altamira and Tampico. Converter operations draw from virgin resin contracts, imported rPET flake, and post-industrial regrind streams. Single-source vulnerability concentrates in post-consumer flake supply where central Mexican collection infrastructure lags processor demand. Distribution runs through direct procurement channels for beverage bottlers and retail private-label supply chains for thermoformed protein trays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as retail procurement consolidation and regulatory complexity create specialist niches for certified converters with barrier technology portfolios and documented polymer traceability.
For Market Incumbents: Shield market position by deepening backward integration into post-industrial regrind processing to meet SEMARNAT recovery targets without virgin resin price exposure. ALPLA México SA de CV's captive resin conversion model offers a template for margin stability. Prioritize certification investment for NOM-252-SSA1-2011 compliance to capture pharmaceutical and premium food accounts where documentation requirements consolidate demand toward proven converters. For New Entrants and Emerging Players: Anchor in Aguascalientes logistics connectivity to supply untapped thermoformed tray demand from northern Mexico meatpacking clusters. The state's central rail and highway positioning offers distribution cost advantages absent from saturated Querétaro and Guanajuato plant clusters. Pursue modified-atmosphere barrier configurations as the entry wedge, targeting mid-tier protein processors outside Walmart México's consolidated vendor base with shorter lead times and flexible minimum order quantities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors converters with captive recycling capabilities and pharmaceutical certification portfolios. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale alone. Acquisition targets should demonstrate documented SEMARNAT eco-modulated fee management and established rPET certificate supply chains. The signal to watch is federal preemption clarity on state-level single-use plastic restrictions in Mexico City, Jalisco, and Quintana Roo, which would abruptly reshape format-specific demand risk.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Recycling Infrastructure Buildout | SEMARNAT extended producer responsibility rules obligate producer-funded collection systems, advantaging integrated processors. |
| Pharmaceutical Barrier Certification | NOM-252-SSA1-2011 migration testing and child-resistant closure compatibility justify premium positioning in prescription distribution. |
| Aguascalientes Logistics Hub Expansion | Central rail and highway connectivity offers untapped thermoformed tray supply positioning for northern meatpacking clusters. |
| Lightweighting Mold Retrofit Investment | Neck finish reduction and wall-thickness optimization displace heavier legacy preforms from regional converters lacking capital access. |
| Post-Industrial Regrind Integration | In-house grinding of sprue and trim waste insulates margin from virgin resin volatility while meeting recovery targets. |
Research Methodology
A standing panel of blow-molding plant managers, retail category buyers at Walmart México and Soriana, resin procurement leads at beverage bottlers, and SEMARNAT compliance officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC 10-K filings of multinational packaging parents, and Mexican federal regulatory gazettes. Bottom-up demand modeling from end-use procurement patterns triangulated against top-down resin consumption estimates from petrochemical industry associations.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented demand by product type, material grade, end-use industry, and regional production hub, with additional modeling of certification tier as a pricing dimension. CAGRs were derived from curve-fitting historical procurement trends against capacity expansion pipelines and regulatory implementation timelines. Forecast inputs incorporated rPET feedstock availability trajectories and retail vendor consolidation schedules.
Material uncertainties — abrupt state-level plastic restriction enactment, post-consumer flake supply shortfalls, and skilled technician training pipeline gaps — sit outside the modeled envelope. Forecasts reflect assumptions about SEMARNAT enforcement intensity and federal preemption clarity that could shift with administrative transitions. Recalibration cycles align with material shifts in extended producer responsibility fee structures and retail procurement centralization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Nigeria Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
US Rigid Thermoform Plastic Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market