
 Asia-Pacific Rigid Bulk Packaging Market | 2026-2036
Asia-Pacific Rigid Bulk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Rigid Bulk Packaging Market Insights
Reusable container pooling services is consolidating purchasing decisions around total-cost-of-ownership metrics rather than unit price. Greif Inc leverages its captive fleet management network to anchor long-term contracts with multinational chemical distributors. Mauser Packaging Solutions sustains competitive density through closed-loop wash-and-return infrastructure across coastal China. SCHUTZ Container Systems (Shanghai) Co Ltd dominates regional IBC refurbishment capacity, controlling aftermarket service revenue streams that rival new equipment margins.
Asia-Pacific rigid bulk packaging denotes freight-rated containers engineered to ISO 10490 and UN certification standards for solids and liquids exceeding 450 liters, typically fabricated from high-density polyethylene, cold-rolled steel, or laminated plywood. These units protect intermediate and finished goods through multi-modal transit across extended supply chains. Plastic drums command the largest installed base due to chemical resistance and lightweight handling economics, while metal totes capture premium margin pools in solvent and flammable liquid applications where UN-rated containment is mandatory. Wood crates retain structural importance in construction materials distribution despite slower growth, constrained by ISPM-15 phytosanitary treatment costs at cross-border nodes.
China's MEE enforces extended producer responsibility frameworks for industrial packaging waste, compelling manufacturers to certify recyclability pathways. Japan's METI circular economy guidelines and India's BIS material safety standards create layered compliance obligations for exporters serving multiple national markets. Stakeholders must monitor regulatory divergence between national EPR schemes and harmonized ASEAN product safety protocols to avoid stranded inventory or duplicate certification spend.
Market Dynamics
Extended producer responsibility mandates from China's MEE are forcing chemical manufacturers to redesign packaging lifecycles around reuse and certified recyclability, compressing traditional single-use procurement models and elevating fleet-based pooling economics.
Growth Catalysts
- MEE Extended Producer Responsibility:China's Ministry of Ecology and Environment mandates industrial packaging waste accountability, compelling manufacturers to adopt reusable IBC programs and certified recycling pathways.
- Petrochemical Export Concentration:Jiangsu province's chemical processing clusters generate concentrated demand for HDPE intermediate bulk containers serving multi-modal export logistics.
- UN Certification Requirements:Solvent and flammable liquid handlers across Southeast Asia must deploy metal totes meeting UN-rated containment standards, locking in premium-grade packaging demand.
Market Restraints
- HDPE Resin Price Volatility:Feedstock cost swings tied to naphtha and ethylene cracker economics compress margin predictability for plastic drum fabricators.
- ISPM-15 Treatment Costs:Heat-treatment and fumigation requirements at ASEAN cross-border nodes erode wood crate competitiveness in construction materials distribution.
- Steel Tote Fabrication Concentration:Cold-rolled steel IBC production clusters in coastal China create supply vulnerability during port congestion or regional energy rationing.
Strategic Opportunities
- India BIS Standardization Gap:India's Bureau of Indian Standards material safety protocols remain partially unenforced in secondary chemical markets, creating first-mover positioning for certified packaging suppliers.
- Closed-Loop Wash Infrastructure:Coastal China's underdeveloped IBC refurbishment density outside Shanghai and Ningbo presents expansion territory for captive fleet operators.
- Japan METI Circular Guidelines:METI's carbon footprint disclosure requirements for industrial packaging create service revenue streams around lifecycle tracking and ESG reporting integration.
Industry Challenges
- Multi-Jurisdiction Certification Lag:Exporters serving China, Japan, and India simultaneously face divergent national EPR schemes and BIS, JIS, and GB standard compliance timelines.
- Wash-and-Return Network Integration:Pooling operators struggle to synchronize container tracking systems with legacy ERP platforms at mid-sized chemical distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Rigid Bulk Packaging Market |
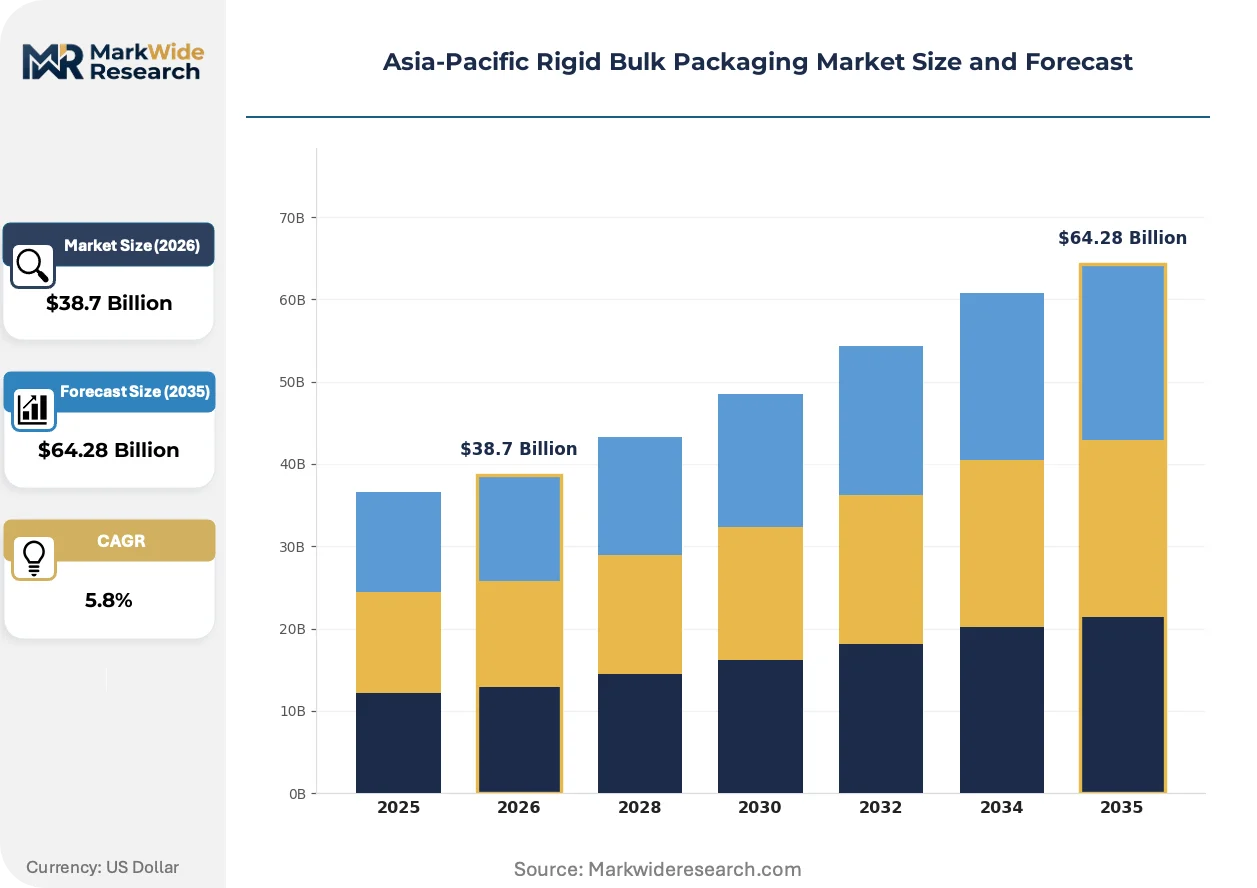
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Boxes, Crates, Totes Material: Plastic, Metal, Wood, Glass End User: Food & Beverage, Pharmaceuticals, Chemicals, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | SCHUTZ Container Systems (Shanghai) Co Ltd, Pyramid Technoplast Ltd, Kodama Plastics Co Ltd, Greif Inc, Mauser Packaging Solutions, Time Technoplast Ltd, Berry Global Inc, Amcor Group GmbH, Yangzhou United Packaging Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Rigid Bulk Packaging Market Trends and Innovations
Digital tracking and automated refurbishment systems are compressing container turnaround cycles and enabling outcome-based pricing models that displace traditional equipment ownership structures across Asia-Pacific chemical logistics.
RFID-embedded IBC fleets with real-time location and residue monitoring are rewriting asset utilization economics for multinational chemical distributors. Petrochemical exporters in Jiangsu and Shandong provinces are deploying these systems at scale to satisfy MEE traceability requirements. The technology is compressing pooling contract structures toward per-use pricing rather than capital lease arrangements.
Japan's METI circular economy disclosure rules now require packaging carbon intensity reporting for industrial chemical shipments. Manufacturers serving Japanese buyers must document cradle-to-grave emissions or forfeit contract eligibility. Metal tote suppliers with ISO 14001-certified fabrication facilities capture preferential positioning in this procurement filter.
Buyer consolidation among ASEAN chemical distributors is concentrating purchasing authority around total-cost-of-ownership metrics rather than unit equipment pricing. Procurement teams at integrated petrochemical majors now mandate wash-and-return service inclusion in packaging contracts. This behavioral shift is most pronounced in Singapore and Thailand, where distributor margins have compressed below equipment ownership viability thresholds.
Asia-Pacific Rigid Bulk Packaging Market Segmentation
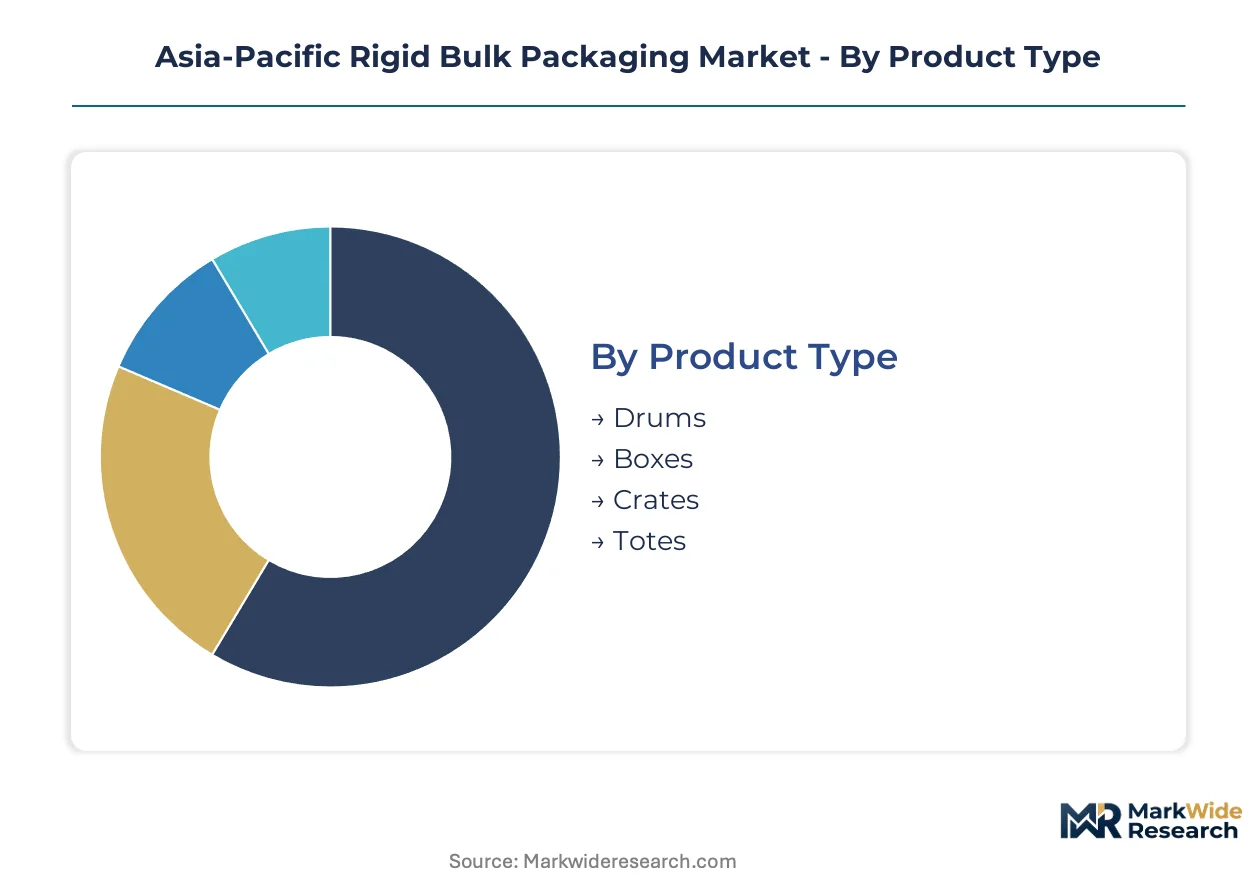
Segmentation reveals how packaging specifications diverge across chemical handling, food safety, and construction logistics in Asia-Pacific. Material choices and certification requirements create distinct procurement clusters that resist commoditization.
Product Type:
Standalone container formats dominate chemical and food logistics, while embedded crate systems integrate with automated warehouse infrastructure.
- Drums:Cylindrical HDPE or steel vessels rated for 200-250 liter capacities serve chemical and pharmaceutical liquid handling. Jiangsu province's petrochemical exporters specify UN-certified drums for solvent shipments to meet MEE traceability mandates.
- Totes:Intermediate bulk containers ranging 500-3000 liters consolidate multi-drum equivalent volumes into single units. Coastal China's closed-loop pooling operators favor totes for wash-and-return economics in high-frequency chemical distribution.
- Boxes:Corrugated triple-wall or rigid polymer containers protect intermediate goods in electronics and automotive parts logistics. BIS packaging standards in India drive certified box adoption for pharmaceutical exports.
- Crates:Returnable plastic or wooden lattice structures enable stacked produce and component handling. ISPM-15 treatment requirements at ASEAN border crossings constrain wooden crate reuse cycles.
Drums lead volumes today; totes are gaining share fastest.
Material:
Cost tiers separate premium-certified metals from commodity plastics and regulated wood treatments.
- Plastic:HDPE and polypropylene formulations dominate chemical resistance applications with lightweight handling economics. Naphtha feedstock volatility compresses margin predictability for regional fabricators.
- Metal:Cold-rolled steel and stainless steel constructions capture UN-rated containment premiums for flammable solvents. METI carbon disclosure rules in Japan favor ISO 14001-certified metal suppliers.
- Wood:Laminated plywood and timber crates retain construction materials distribution despite phytosanitary compliance burdens. Heat-treatment costs at Singapore and Thailand border nodes erode competitiveness.
- Glass:Borosilicate and soda-lime containers serve pharmaceutical purity requirements with inert surface properties. Fragility limits glass to short-haul specialty chemical segments.
Plastic commands the largest installed base; metal is expanding most quickly.
End User:
Application severity determines whether packaging must satisfy food-grade, pharmaceutical, or hazardous material standards.
- Chemicals:Petrochemical manufacturers and specialty chemical distributors drive demand for UN-certified containment across multi-modal export chains. MEE extended producer responsibility mandates compel reusable IBC adoption.
- Food & Beverage:Processors and bulk ingredient handlers require FDA-compliant or equivalent food-grade polymer surfaces. ASEAN harmonized safety protocols create certification complexity for cross-border suppliers.
- Pharmaceuticals:Active pharmaceutical ingredient and excipient handlers specify contamination-resistant containers with batch traceability. India's CDSCO and BIS standards partially overlap, creating compliance gaps.
- Construction:Cement, adhesive, and coating distributors utilize returnable crates and drums with abrasion-resistant specifications. Slower growth reflects project-based demand volatility.
Chemicals anchor revenue concentration; pharmaceuticals show the steepest expansion trajectory.
Distribution Channel:
Customer scale and integration depth separate direct fleet contracts from fragmented wholesale procurement.
- Direct Sales:Captive fleet operators and multinational packaging vendors contract directly with integrated petrochemical majors. Total-cost-of-ownership metrics displace unit pricing in Singapore and Thailand procurement.
- Distributors:Regional packaging specialists aggregate mid-sized chemical and food processor demand with inventory positioning. Wash-and-return service bundling differentiates distributor value propositions.
- Wholesalers:Bulk volume resellers serve construction materials and general industrial accounts with standardized drum and crate specifications. Price sensitivity limits service attachment rates.
- Online Retail:Digital platforms facilitate small-lot procurement for specialty chemical and pharmaceutical R&D operations. Limited penetration reflects certification documentation requirements.
Direct sales capture premium contract value; distributors are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China generates the heaviest absolute demand for rigid bulk packaging in Asia-Pacific, while India's regulatory fragmentation creates steeper compliance costs for multinational suppliers serving both markets simultaneously.
China
Jiangsu province's petrochemical processing clusters drive concentrated demand for HDPE intermediate bulk containers serving multi-modal export corridors. MEE extended producer responsibility mandates compel chemical manufacturers to certify reusable packaging lifecycles and recyclability pathways. Shanghai and Ningbo anchor the region's closed-loop wash-and-return infrastructure, though refurbishment density thins beyond these coastal hubs.
India
Specialty chemical distributors in Maharashtra and Gujarat are expanding UN-certified drum procurement to serve pharmaceutical export growth. BIS material safety standards partially overlap with CDSCO pharmaceutical packaging rules, creating certification complexity for container suppliers. The Delhi-NCR corridor shows rising demand for food-grade polymer totes as processed food exports accelerate.
Japan
METI circular economy guidelines now mandate carbon footprint disclosure for industrial packaging used in chemical shipments. Kanto region buyers filter procurement toward ISO 14001-certified metal tote suppliers with documented cradle-to-grave emissions data. Osaka-based chemical distributors are consolidating purchasing authority around total-cost-of-ownership metrics rather than unit equipment pricing.
Singapore
Integrated petrochemical majors headquartered here mandate wash-and-return service bundling in packaging contracts, compressing distributor margins below equipment ownership viability. The city-state's port infrastructure supports transshipment of refurbished IBCs across Southeast Asian chemical distribution networks. Procurement teams increasingly specify RFID-embedded fleets with real-time residue monitoring.
Thailand
ASEAN harmonized safety protocols create certification complexity for cross-border packaging suppliers serving food and beverage processors in the Eastern Economic Corridor. ISPM-15 phytosanitary treatment requirements at Thai border nodes erode wooden crate competitiveness in construction materials distribution. Bangkok-based chemical distributors are adopting per-use pricing models for pooled container fleets.
Asia-Pacific Rigid Bulk Packaging Market Competitive Landscape
Top-tier vendors anchor captive fleet management and closed-loop refurbishment networks, while mid-scale fabricators compete on regional certification speed and distributor relationships. Market structure tilts toward consolidation around pooling economics rather than equipment manufacturing scale. Three archetypes dominate: multinational pooling operators with integrated wash infrastructure, regional refurbishment specialists capturing aftermarket service revenue, and resin-integrated drum fabricators managing feedstock cost volatility. Competitive moves center on wash-and-return network expansion and digital tracking system deployment.
Among Asia-Pacific-based operators, SCHUTZ Container Systems (Shanghai) Co Ltd exemplifies the regional refurbishment specialist archetype with concentrated IBC aftermarket capacity. Greif Inc and Mauser Packaging Solutions represent multinational pooling operators leveraging captive fleet networks to anchor long-term chemical distributor contracts. These three occupy positions across the premium service tier where total-cost-of-ownership procurement filters increasingly determine contract eligibility.
| Leading Market Players |
|---|
| SCHUTZ Container Systems (Shanghai) Co Ltd |
| Pyramid Technoplast Ltd |
| Kodama Plastics Co Ltd |
| Greif Inc |
| Mauser Packaging Solutions |
| Time Technoplast Ltd |
| Berry Global Inc |
| Amcor Group GmbH |
| Yangzhou United Packaging Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Integrated petrochemical majors headquartered in Singapore and Thailand anchor procurement authority around total-cost-of-ownership frameworks, compressing distributor margins below equipment ownership viability and accelerating per-use pricing adoption across ASEAN chemical logistics.
Pricing Analysis
Capacity additions in China's Jiangsu and Shandong provinces are reshaping price floors for HDPE intermediate bulk containers as captive fleet operators compete on wash-and-return service bundling rather than unit equipment cost. Three-tier pricing structure across premium UN-certified metal totes, standard reusable plastic IBCs, and economy single-use drums reflects certification grade and service integration depth. Cost compression in commodity plastic drum tiers is intensifying because naphtha feedstock volatility erodes fabricator margin predictability. Mid-sized chemical distributors in coastal China exhibit highest price sensitivity, while Japanese buyers under METI carbon disclosure mandates show lowest sensitivity due to compliance-driven procurement filters.
Supply Chain Analysis
Dual-sourcing requirements from multinational chemical distributors mandate qualified supplier rosters spanning China, South Korea, and Japan to mitigate port congestion and regional energy rationing risks. HDPE resin supply draws from naphtha crackers concentrated in East Asian petrochemical hubs, with cold-rolled steel for metal totes sourced from integrated mills in China and Japan. Single-source vulnerability in coastal China IBC fabrication clusters creates supply disruption exposure during MEE environmental compliance inspections. Distribution runs through captive fleet operators with integrated refurbishment infrastructure, displacing arm's-length equipment sales with pooled container service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as MEE extended producer responsibility mandates and METI carbon disclosure rules displace commodity procurement with certified reusable packaging specifications.
For Market Incumbents: Anticipate margin compression from resin-integrated drum fabricators in China by deepening captive wash-and-return network density in underpenetrated coastal zones beyond Shanghai and Ningbo. Lock in long-term pooling contracts with ASEAN chemical distributors before per-use pricing standardization erodes equipment ownership economics. Certification investment in ISO 14001 fabrication facilities captures preferential positioning in Japanese procurement filters. For New Entrants and Emerging Players: Regional packaging specialists in India's Maharashtra and Gujarat corridors offer the most penetrable entry point, as BIS standardization gaps and CDSCO overlap create compliance complexity that rewards certified-first positioning. Target pharmaceutical export handlers in the Delhi-NCR corridor with food-grade polymer tote offerings as processed food logistics accelerate. Go-to-market through distributor partnerships bundling wash-and-return services rather than competing on equipment price. For Investors and Strategic Acquirers: Chemical logistics pooling operators are the most active acquirer in this space, consolidating regional refurbishment specialists to capture aftermarket service revenue streams. Long-term viability centers on asset-light fleet management platforms with digital tracking integration, not resin-integrated manufacturing scale. Watch RFID-embedded IBC deployment rates in Jiangsu province as the inflection signal for outcome-based pricing adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Wash Infrastructure Expansion | Captive fleet operators in coastal China capture aftermarket revenue rivaling new equipment margins. |
| Backward Integration into HDPE Resin Supply | Drum fabricators in Jiangsu province hedge naphtha volatility through captive cracker relationships. |
| ISO 14001 Certification Investment | Metal tote suppliers secure preferential positioning in METI-filtered Japanese procurement channels. |
| RFID Fleet Tracking Deployment | Real-time residue monitoring satisfies MEE traceability mandates and enables per-use pricing models. |
| Regional Refurbishment Specialist Acquisition | Pooling operators consolidate SCHUTZ-style aftermarket capacity to anchor long-term distributor contracts. |
Research Methodology
Coverage spans China, India, Japan, Singapore, and Thailand, with primary inputs from each market combining interviews with plant managers at petrochemical processing facilities, procurement leads at downstream chemical distributors, technical R&D directors at packaging fabricators, and channel partners in wash-and-return logistics. Secondary validation draws from customs and trade data, MEE regulatory filings, METI circular economy disclosures, BIS standardization records, and SEC 10-K filings from listed packaging vendors. Bottom-up demand modeling and top-down supply capacity assessment triangulate market sizing.
Granularity-level modeling spans product type dimensions including drums, totes, boxes, and crates; material tiers across plastic, metal, wood, and glass; end-use verticals in chemicals, food and beverage, pharmaceuticals, and construction; and distribution channel structures from direct sales through wholesalers. CAGRs were derived from segment-level volume trajectories and value-per-unit trends across the projection horizon. Industry-specific forecast inputs incorporate MEE compliance timeline acceleration scenarios and ASEAN harmonized safety protocol adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to naphtha-ethylene cracker economics, regional energy rationing severity, and divergence between national EPR schemes. Forecasts reflect documented assumptions regarding MEE enforcement consistency and METI disclosure rule permanence. Deviation in HDPE resin price volatility or port congestion duration in coastal China would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market