
 Non-Hyaluronic Acid Dermal Filler Market | 2026-2036
Non-Hyaluronic Acid Dermal Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Hyaluronic Acid Dermal Filler Market Analytics
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for non-hyaluronic acid dermal fillers, forcing manufacturers to generate expanded clinical data for CE marking renewal. Merz Pharma leverages its Rumenis portfolio to sustain European market presence amid these tightened compliance timelines. Sinclair Pharma anchors its competitive position through geographic dominance across Western European aesthetic clinics. Bioxis Pharmaceuticals differentiates via specialized biostimulator expertise in poly-L-lactic acid technology.
Non-hyaluronic acid dermal fillers comprise injectable implants formulated from calcium hydroxylapatite microspheres, poly-L-lactic acid particles, or polymethyl methacrylate microspheres suspended in biocompatible carriers, designed to restore facial volume through collagen neogenesis or permanent structural support. Calcium hydroxylapatite leads product type revenue due to established safety profiles and immediate volumizing effects, while poly-L-lactic acid captures expanding share among patients seeking gradual, natural-appearing outcomes through biostimulation. Medical distributors dominate channel flow for facial contouring applications, though direct sales to cosmetic surgery centers are gaining traction for premium composite filler lines.
FDA premarket notification requirements and the EU MDR clinical evaluation framework shape product development timelines and market access pathways for non-resorbable implant categories. Health Canada's alignment with ISO 10993 biocompatibility standards adds another compliance layer for North American manufacturers. Stakeholders must monitor evolving regulator positions on long-term safety surveillance for permanent fillers as post-market clinical follow-up mandates intensify across jurisdictions.
Market Dynamics
The EU Medical Device Regulation is compressing commercialization timelines for permanent and semi-permanent injectables, forcing manufacturers to front-load clinical evidence generation before CE marking renewal cycles. This regulatory density is reshaping competitive entry barriers and portfolio prioritization across calcium hydroxylapatite and poly-L-lactic acid formulations.
Growth Catalysts
- Patient demand for extended duration outcomes:Aesthetic clinics report rising preference for biostimulators that deliver collagen neogenesis over 18-24 month intervals rather than hyaluronic acid's 6-12 month retreatment cycles.
- Calcium hydroxylapatite safety data accumulation:Long-term post-market surveillance databases in the United States and Germany reinforce physician confidence for facial contouring applications.
- Medical spa channel expansion:Cosmetic surgery centers in Florida, California, and Texas are adding dedicated injection suites staffed by nurse practitioners trained in composite filler protocols.
Market Restraints
- EU MDR clinical evaluation costs:The expanded technical documentation requirements for Class III implantable devices are elevating regulatory compliance expenditures to levels that disadvantage mid-tier manufacturers.
- Polymethyl methacrylate permanent filler liability exposure:Late-onset granuloma formation and migration risks continue to constrain physician adoption despite permanent volumizing benefits.
- Hyaluronic acid reversibility advantage:The availability of hyaluronidase dissolution creates a safety backstop that non-resorbable fillers cannot match, particularly for novice injectors.
Strategic Opportunities
- Male aesthetic patient penetration:Underpenetrated demand among men for jawline definition and temporal hollowing correction represents a whitespace segment with distinct anatomical injection protocols.
- Combination therapy protocols:Sequencing calcium hydroxylapatite for structural support with poly-L-lactic acid for diffuse biostimulation is creating premium service tiers in dermatology practices.
- Direct-to-clinic distribution models:Bypassing medical distributors for high-volume cosmetic surgery centers reduces margin leakage and enables real-time inventory replenishment systems.
Industry Challenges
- Advanced injector training scarcity:Mastery of deep-plane injection techniques for calcium hydroxylapatite requires cadaver lab certification that fewer than 15% of aesthetic nurses currently hold.
- Post-market clinical follow-up infrastructure:EU MDR mandates for 10-year patient registries demand data collection systems that most aesthetic practices lack the administrative capacity to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Hyaluronic Acid Dermal Filler Market |
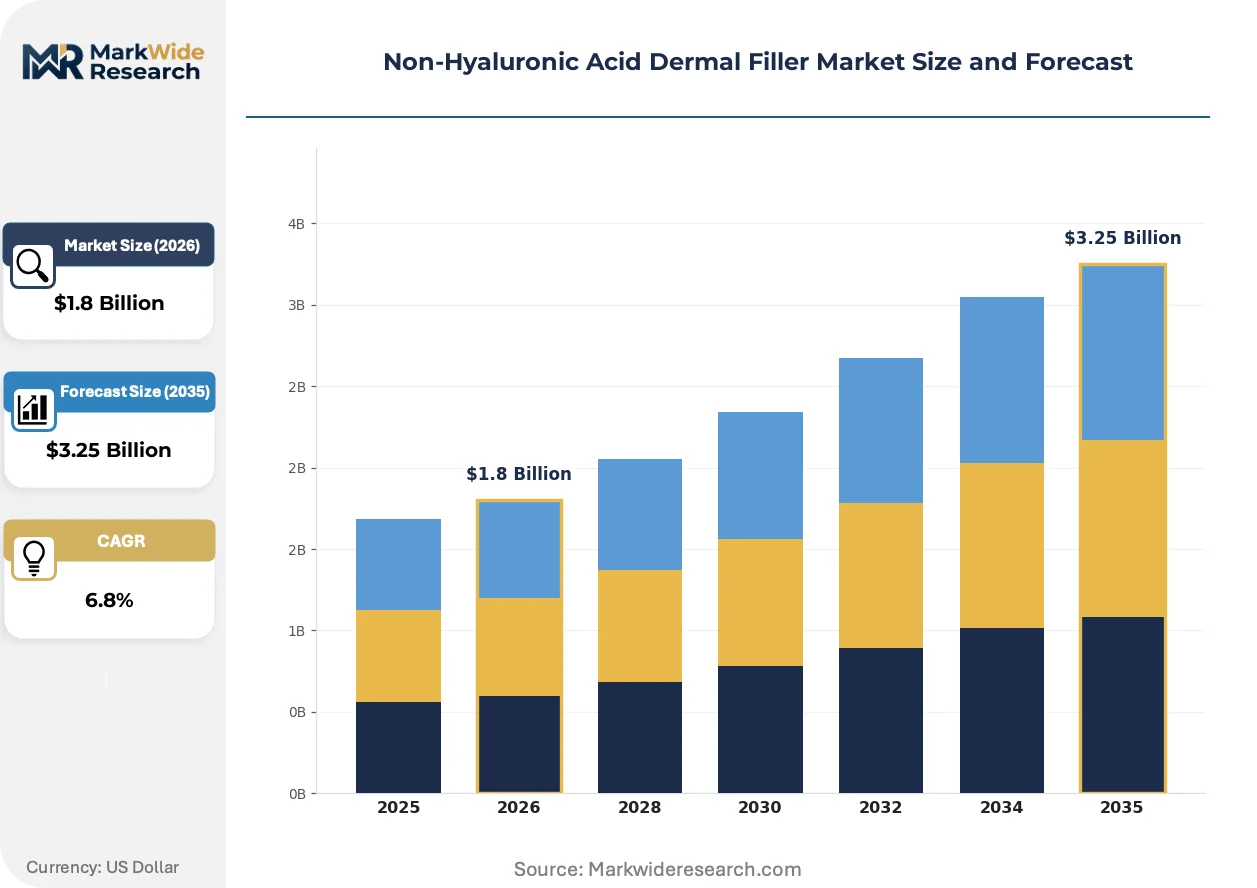
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Hydroxylapatite, Poly-L-Lactic Acid, Polymethyl Methacrylate, Composite Fillers End User: Dermatology Clinics, Cosmetic Surgery Centers, Medical Spas, Aesthetic Practices Application: Facial Contouring, Lip Enhancement, Wrinkle Reduction, Scar Treatment Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Beauty Supply Stores |
| Companies Covered | Merz Pharma, Suneva Medical, Bioxis Pharmaceuticals, Bioplus Co., Ltd., Sinclair Pharma, Revance Therapeutics, Inc., Prollenium Medical Technologies, SCULP Luxury Dermal Fillers Ltd., Medytox Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Hyaluronic Acid Dermal Filler Market Evolving Landscape
Formulation science is advancing beyond particle size optimization toward engineered degradation profiles that synchronize with native collagen remodeling kinetics. These material innovations are enabling procedure-specific customization that was previously unattainable with first-generation biostimulators.
Poly-L-lactic acid microsphere surface modification is rewriting the competitive calculus for gradual volumizing therapies. Aesthetic dermatology practices in Seoul and São Paulo are adopting these next-generation particles for facial lipoatrophy and décolletage rejuvenation at rates exceeding traditional hyaluronic acid sequences. The technology is compressing the treatment-to-result interval from three months to four weeks, collapsing the historical patience barrier that limited poly-L-lactic acid adoption.
REACH compliance deadlines for residual monomer content in polymethyl methacrylate suspensions are tightening purity specifications for European market access. Manufacturers with captive polymerization capabilities are absorbing capital equipment costs to maintain formulation continuity, while contract manufacturers without vertical control over monomer supply face portfolio rationalization. The regulatory pressure is concentrating supply among integrated producers with in-house analytical chemistry laboratories.
Subscription-based maintenance programs are displacing episodic filler purchasing in high-volume aesthetic clinics. Patients in Manhattan, Beverly Hills, and Miami are committing to annual treatment packages that bundle calcium hydroxylapatite touch-ups with skincare protocols, locking in practice revenue and reducing competitive switching. The model is most visible in concierge dermatology settings where relationship continuity commands premium pricing power.
Non-Hyaluronic Acid Dermal Filler Market Segmentation
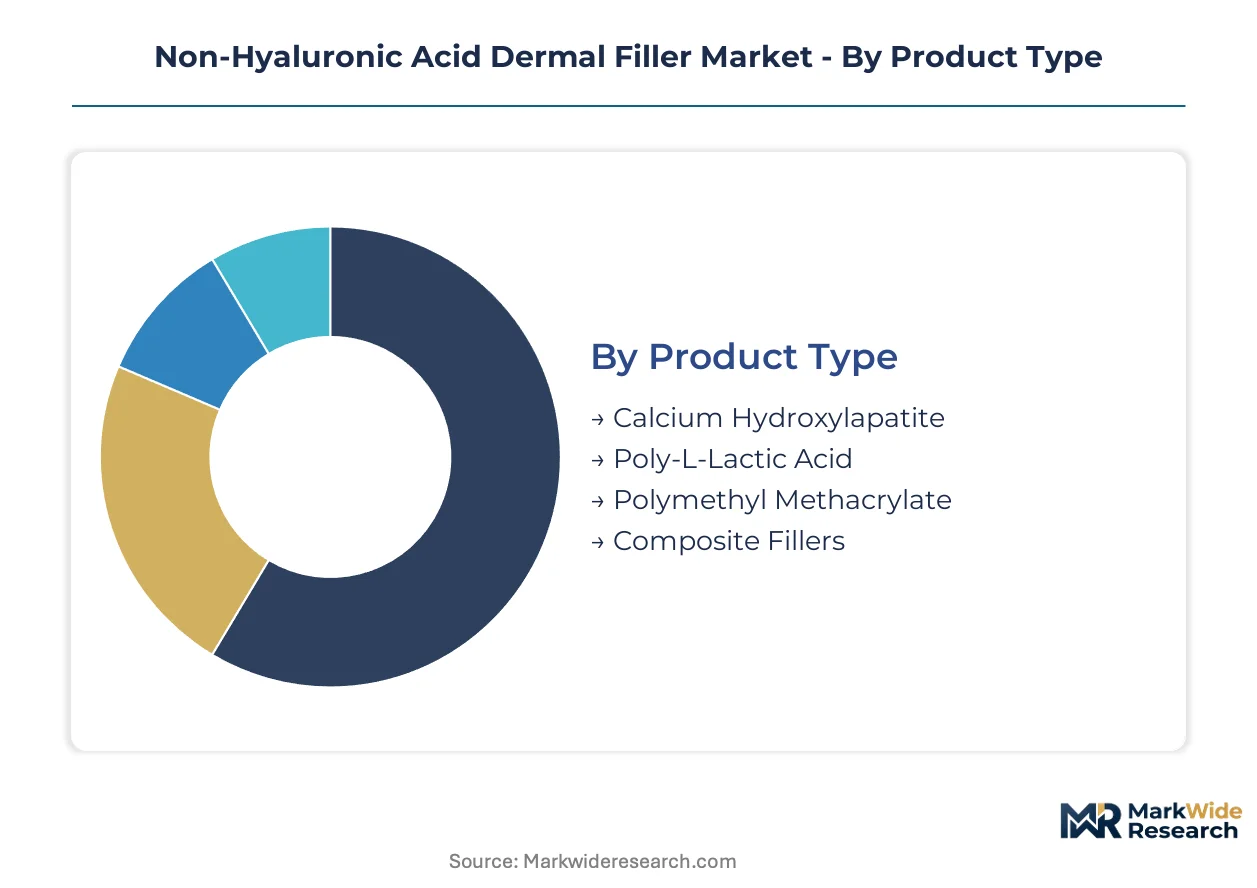
Segmentation in non-hyaluronic acid dermal fillers reveals how regulatory pathways and clinical use cases fragment commercial opportunity. Each dimension carries distinct certification burdens, channel economics, and patient safety profiles that reshape competitive positioning.
Product Type:
FDA premarket notification and EU MDR Class III implantable device requirements concentrate differentially across these four material categories, with calcium hydroxylapatite and poly-L-lactic acid navigating established 510(k) pathways while polymethyl methacrylate faces heightened scrutiny.
- Calcium Hydroxylapatite:Microsphere suspensions in aqueous gel carriers deliver immediate volumizing through mechanical filling plus sustained collagen induction. Demand clusters in US cosmetic surgery centers where physicians value the established RADIESSE safety database for nasolabial folds and hand rejuvenation.
- Poly-L-Lactic Acid:Biodegradable polymer microparticles trigger gradual fibroblast activation and neocollagenesis over 4-6 weeks. Seoul and São Paulo aesthetic practices are adopting surface-modified variants for facial lipoatrophy, compressing the historical treatment-to-result interval that previously limited patient acceptance.
- Polymethyl Methacrylate:Permanent microsphere implants require the most extensive clinical evidence packages under EU MDR post-market surveillance mandates. Late-onset granuloma risks constrain adoption despite permanent structural benefits.
- Composite Fillers:Hybrid formulations combining biostimulator particles with resorbable carriers occupy niche positioning for patients seeking intermediate durability.
Calcium hydroxylapatite sits at the top of the volume ranking, with poly-L-lactic acid climbing the fastest.
End User:
Procurement authority and injection complexity split across these four settings, with medical spas capturing volume through nurse practitioner protocols while cosmetic surgery centers command premium pricing for advanced techniques.
- Dermatology Clinics:Board-certified dermatologists with cadaver lab certification perform deep-plane injections using calcium hydroxylapatite for structural support. These practices in Manhattan and Beverly Hills bundle biostimulator sequences with skincare protocols.
- Cosmetic Surgery Centers:Plastic surgeons with hospital privileges manage complication risks for permanent fillers. Florida, California, and Texas facilities are adding dedicated injection suites staffed by advanced practice providers.
- Medical Spas:Nurse practitioners trained in composite filler protocols drive volume for maintenance touch-ups. Subscription-based annual packages are displacing episodic purchasing in high-volume settings.
- Aesthetic Practices:Mixed-specialty clinics without surgical backup concentrate on reversible hyaluronic acid alternatives, limiting non-resorbable filler penetration.
Cosmetic surgery centers generate the highest revenue per procedure, with medical spas expanding most quickly through standardized training protocols.
Application:
Anatomical site selection dictates product choice, with facial contouring requiring structural fillers while lip enhancement demands precision placement in vascular-sensitive zones.
- Facial Contouring:Jawline definition and cheek volumizing utilize calcium hydroxylapatite for immediate structural support. Male patients represent underpenetrated whitespace with distinct anatomical injection protocols for temporal hollowing correction.
- Lip Enhancement:Vascular compromise risks limit non-resorbable filler adoption in this application. Hyaluronic acid reversibility through hyaluronidase creates a safety backstop that permanent alternatives cannot match.
- Wrinkle Reduction:Poly-L-lactic acid sequences address diffuse facial lipoatrophy through biostimulation rather than direct filling.
- Scar Treatment:Subcision combined with biostimulator injection addresses acne and traumatic scars through collagen remodeling.
Facial contouring commands the largest procedure volume, with scar treatment gaining share fastest through expanded subcision protocols.
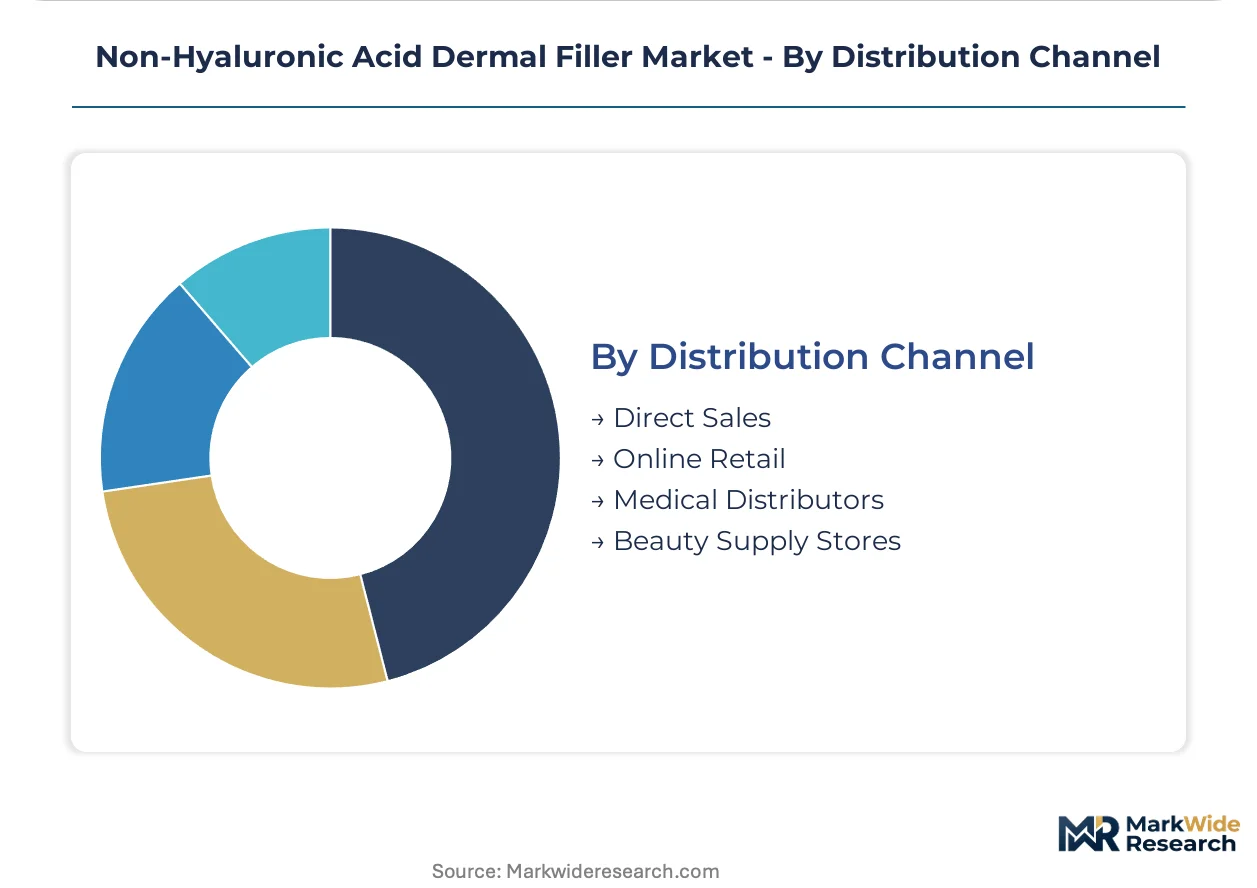
Distribution Channel:
Margin capture and inventory velocity diverge sharply between direct manufacturer relationships and third-party medical distribution, with regulatory traceability requirements favoring consolidated channel partners.
- Direct Sales:High-volume cosmetic surgery centers in Miami and Los Angeles bypass distributors for premium composite filler lines. Real-time inventory replenishment systems reduce stockout risk for multi-location practices.
- Online Retail:Regulatory restrictions on prescription device e-commerce limit this channel to ancillary skincare products rather than injectable fillers.
- Medical Distributors:Dominant channel flow for facial contouring applications requires cold chain logistics and lot tracking for EU MDR vigilance compliance.
- Beauty Supply Stores:Non-prescriptive retail channel excluded from professional-grade filler distribution due to FDA and Health Canada device regulations.
Medical distributors handle the greatest transaction volume, with direct sales expanding most quickly among multi-site aesthetic groups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified aesthetic physicians cluster in metropolitan medical corridors where disposable income and cosmetic procedure acceptance converge. These talent concentrations anchor demand geography across four distinct national markets.
United States
Cosmetic surgery centers in Florida, California, and Texas drive calcium hydroxylapatite volume through dedicated injection suites staffed by nurse practitioners. FDA premarket notification requirements shape product development timelines for permanent filler categories. Manhattan and Beverly Hills dermatology practices bundle biostimulator sequences with premium skincare protocols.
Germany
Long-term post-market surveillance databases reinforce physician confidence for facial contouring applications across Bavaria and North Rhine-Westphalia. EU MDR clinical evaluation requirements elevate compliance expenditures for Class III implantable devices. Frankfurt and Munich aesthetic clinics concentrate demand for poly-L-lactic acid biostimulation therapies.
Brazil
Aesthetic practices in São Paulo adopt surface-modified poly-L-lactic acid particles for décolletage rejuvenation at rates exceeding traditional sequences. ANVISA alignment with ISO 10993 biocompatibility standards adds certification layers for imported filler formulations. Rio de Janeiro medical spas expand subscription-based maintenance programs for male jawline definition procedures.
South Korea
Seoul dermatology practices lead adoption of next-generation poly-L-lactic acid microspheres compressing treatment-to-result intervals. MFDS regulates residual monomer content specifications for polymethyl methacrylate suspensions entering the market. Gangnam district aesthetic clusters pioneer combination therapy protocols sequencing structural and biostimulator fillers.
United Kingdom
London cosmetic surgery centers navigate CE marking renewal cycles under tightened EU MDR vigilance mandates for permanent implants. MHRA post-market surveillance requirements demand 10-year patient registry infrastructure most practices lack. Harley Street medical corridors sustain premium pricing for calcium hydroxylapatite contouring procedures.
Non-Hyaluronic Acid Dermal Filler Market Competitive Landscape
The competitive structure tilts toward specialized biostimulator developers with captive polymerization capabilities. Mid-tier manufacturers face portfolio rationalization as REACH compliance deadlines concentrate supply among integrated producers. Three archetypes dominate: European pharmaceutical incumbents with established CE marking pathways, Asian contract manufacturers with surface-modification expertise, and North American device specialists with direct-to-clinic distribution models. Competitive moves center on M&A for polymerization assets and strategic partnerships for EU MDR clinical evidence generation.
Within the European incumbent tier, Merz Pharma and Sinclair Pharma exemplify established market presence through differentiated material portfolios. Among biostimulator specialists, Bioxis Pharmaceuticals occupies a position representing poly-L-lactic acid technology concentration. Suneva Medical and Revance Therapeutics, Inc. sit within the North American device specialist archetype, anchoring direct sales channel expansion in high-volume cosmetic surgery centers. These three groupings represent the structural fault lines reshaping competitive positioning as regulatory density elevates barriers for non-integrated entrants.
| Leading Market Players |
|---|
| Merz Pharma |
| Suneva Medical |
| Bioxis Pharmaceuticals |
| Bioplus Co., Ltd. |
| Sinclair Pharma |
| Revance Therapeutics, Inc. |
| Prollenium Medical Technologies |
| SCULP Luxury Dermal Fillers Ltd. |
| Medytox Inc. |
| Others |
Value Network & Pricing Analysis
Poly-L-lactic acid resin spot indices in Asian chemical markets cascade through filler manufacturing tiers, compressing margins for contract polymerization houses while integrated producers with captive supply chains capture pricing power across premium, standard, and economy product tiers in aesthetic clinics.
Pricing Analysis
Bundled subscription protocols versus unbundled per-procedure purchasing splits the pricing architecture across aesthetic practices. Three-tier pricing structure across premium, standard, and economy levels differentiates by injector certification grade and after-sales complication management coverage. Cost compression in mid-tier calcium hydroxylapatite lines is intensifying because REACH compliance investments concentrate supply among integrated manufacturers. Nurse practitioner-staffed medical spas exhibit highest price sensitivity, while board-certified dermatology practices in Manhattan and Beverly Hills accept premium positioning for cadaver-lab-certified injection protocols.
Supply Chain Analysis
Direct-to-clinic channels handle hyperscale cosmetic surgery center demand in Florida, California, and Texas, while medical distributors retain cold-chain custody for smaller aesthetic practices. Manufacturing concentrates in Germany, the United States, and South Korea, with poly-L-lactic acid polymerization drawing from pharmaceutical-grade lactide monomer supply. Single-source vulnerability in PMMA microsphere production creates bottleneck risk for permanent filler portfolios. Distribution runs through consolidated medical device distributors with EU MDR vigilance traceability infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-hyaluronic acid dermal filler market functions as a stable compounder, with patient demand for extended-duration outcomes generating predictable revenue recurrence across 18-24 month retreatment cycles.
For Market Incumbents: Hedge against EU MDR compliance cost inflation by securing captive polymerization assets and pre-loading clinical evidence packages for CE marking renewal cycles. Backward integration into poly-L-lactic acid resin production defends margin position against raw material volatility. Channel control through direct-to-clinic inventory replenishment systems locks in high-volume cosmetic surgery center relationships. For New Entrants and Emerging Players: FDA premarket notification requirements in the United States open a window for surface-modified poly-L-lactic acid formulations with accelerated collagen induction timelines. Target male aesthetic patients for jawline definition protocols, where anatomical injection standards remain underdeveloped and competition is sparse. ANVISA alignment pathways in Brazil offer a streamlined entry point for biostimulator portfolios seeking Latin American beachheads. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier biostimulator developers possessing vertical polymerization control and EU MDR clinical evidence packages already assembled. Long-term viability over a multi-year horizon hinges on regulatory dossier durability rather than near-term revenue scale. Watch for MFDS residual monomer rulings as an inflection indicator for polymethyl methacrylate supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Generation | Front-loaded documentation investment secures CE marking renewal for Class III implantable devices. |
| Surface-Modified Poly-L-Lactic Acid Launch | Compressed treatment-to-result intervals capture patient preference in Seoul and São Paulo clinics. |
| Direct-to-Clinic Distribution Expansion | Bypassing medical distributors reduces margin leakage for high-volume cosmetic surgery centers. |
| Male Aesthetic Protocol Development | Distinct anatomical injection standards for jawline definition unlock underpenetrated demand segments. |
| Subscription-Based Maintenance Programs | Annual treatment packages lock in practice revenue and reduce competitive switching in concierge settings. |
Research Methodology
Coverage spans North America, Western Europe, Latin America, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with aesthetic clinic medical directors, biomedical engineers at filler manufacturers, GPO contracts managers, and regulatory affairs specialists at CE marking consultancies anchor the primary foundation. FDA 510(k) filings, EU MDR technical documentation databases, ANVISA registration records, and MFDS approval summaries constitute secondary sources. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue assessments.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include product material category, end-user facility type, anatomical application site, and distribution channel structure. CAGRs derive from procedure frequency assumptions tied to patient demographic penetration and retreatment interval compression. Industry-specific inputs encompass EU MDR compliance cost trajectories and injector certification expansion rates.
Revisions become necessary when regulatory timelines for CE marking renewal accelerate or when post-market surveillance mandates expand beyond current 10-year registry requirements. Forecasts reflect assumptions about patient preference stability for extended-duration outcomes and physician training pipeline capacity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Facial Bone Contouring Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Hair Transplant Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
South Korea Hair Transplant Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
Medical Aesthetics Market