
 Rhytidectomy Market | 2026-2036
Rhytidectomy Market Size, Share, and Industry Trends Forecast 2026-2036
Rhytidectomy Market Intelligence
South Korea is reconfiguring its medical tourism infrastructure to capture international rhytidectomy demand through specialized cosmetic surgery districts in Seoul. Allergan Inc leverages its dermal filler portfolio to anchor adjacent facelift service revenues in premium clinics. Merz GmbH & Co KGaA competes through R&D intensity in minimally invasive thread lift technologies. Galderma S.A. sustains brand strength across physician training networks that drive technique adoption.
Rhytidectomy denotes the surgical excision and redraping of facial skin and superficial musculoaponeurotic tissue to correct age-related ptosis and rhytid formation, typically involving preauricular incisions extending into the temporal scalp with subcutaneous or deep-plane dissection. The procedure restores cervicofacial contour through tissue repositioning rather than volume augmentation alone. Full facelift procedures command the deepest margin pools due to operative complexity and facility fee structures, while non-surgical facelift segments attract the fastest volume expansion through energy-based device platforms. Laser-assisted techniques occupy a narrowing but defended niche where physician certification requirements limit competitive entry.
FDA premarket notification pathways shape device commercialization timelines for laser-assisted and radiofrequency systems used in adjunctive rhytidectomy procedures. The EU Medical Device Regulation imposes clinical evidence thresholds on thread lift and energy-based platforms that filter market access for smaller manufacturers. Reimbursement exclusion for purely cosmetic indications across Medicare and most private US payers concentrates demand in self-pay channels where financing programs and bundled pricing determine patient conversion rates. Stakeholders must monitor evolving state-level scope-of-practice debates that could expand non-physician provider participation in postoperative care protocols.
Market Dynamics
FDA tightening of 510(k) premarket validation for laser-assisted rhytidectomy devices is extending commercialization timelines and compressing margins for device manufacturers while favoring established players with regulatory infrastructure.
Growth Catalysts
- Ambulatory Surgical Center Expansion:CMS facility fee structures incentivize outpatient migration for facelift procedures across United States metropolitan markets.
- Thread Lift Technology Maturation:Absorbable polydioxanone suture systems enable minimally invasive tissue repositioning with reduced recovery intervals.
- Medical Tourism Infrastructure:South Korea's Gangnam district clustering concentrates international patient acquisition through integrated cosmetic surgery ecosystems.
Market Restraints
- Reimbursement Exclusion:Medicare and commercial payer policies classify rhytidectomy as cosmetic, forcing 100% self-pay burden on patients.
- Physician Certification Bottlenecks:Laser-assisted technique credentialing requirements limit qualified provider supply in secondary United States markets.
- Substitute Technology Pressure:Energy-based skin tightening platforms capture patients seeking non-surgical alternatives with lower price points.
Strategic Opportunities
- Bundled Pricing Models:Dermal filler-anchored facelift packages create patient retention and lifetime value capture in premium United States clinics.
- Deep-Plane Technique Standardization:Advanced SMAS dissection protocols differentiate high-margin surgical offerings from commoditized mini-lift alternatives.
- Postoperative Care Protocol Expansion:Scope-of-practice liberalization in select United States states enables non-physician provider participation in follow-up services.
Industry Challenges
- Facility Fee Compression:Ambulatory center reimbursement rate negotiations demand operational cost discipline without quality degradation.
- Device Validation Timelines:FDA clinical evidence requirements for radiofrequency adjunct systems extend development cycles beyond 24 months.
- Technique Training Standardization:Deep-plane rhytidectomy skill transfer remains dependent on preceptor-led fellowship models with limited throughput capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhytidectomy Market |
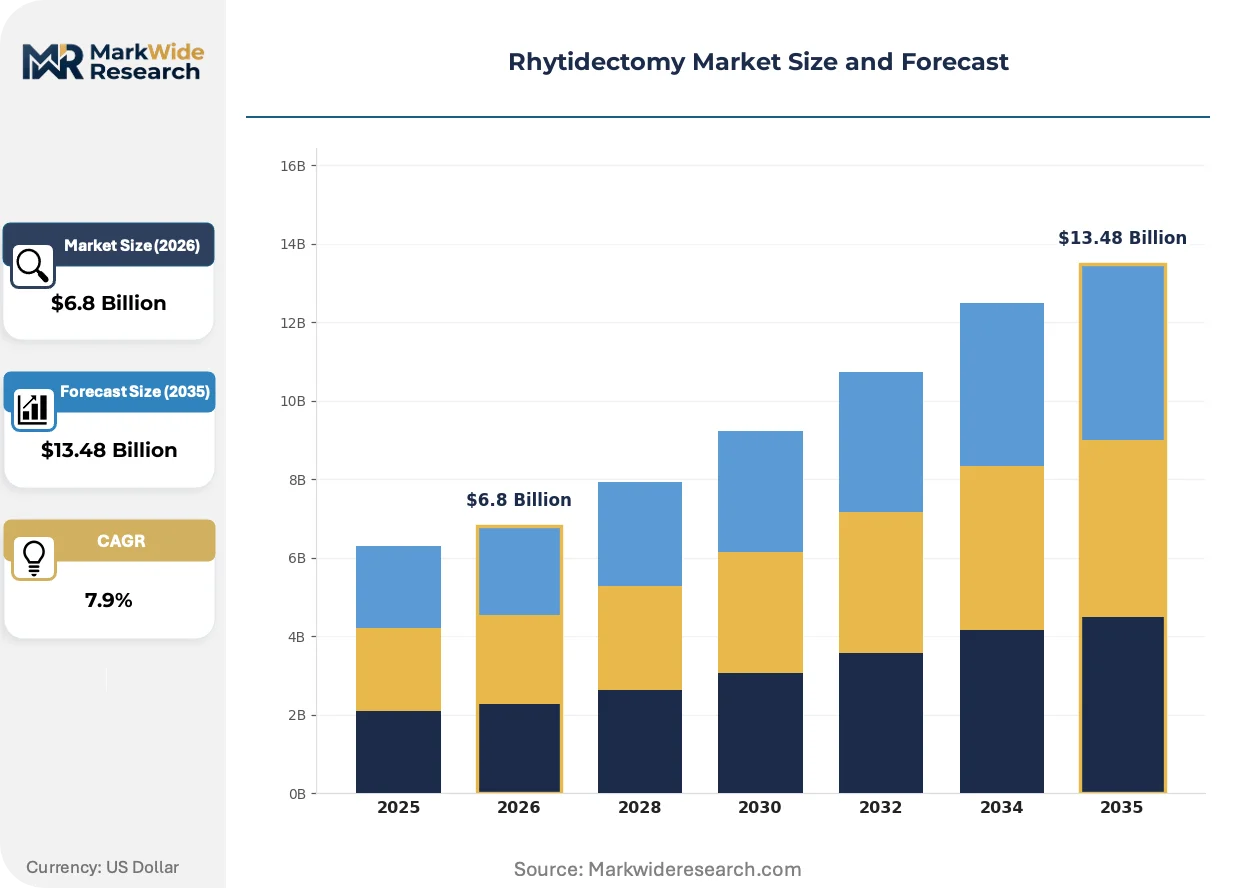
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Mid-Facelift, Lower Facelift, Full Facelift, Non-Surgical Facelift Technique: Traditional, Minimal Invasive, Endoscopic, Laser-Assisted Patient Type: Cosmetic Seekers, Reconstructive Candidates, Age-Related Patients, Others End User: Clinics, Hospitals, Ambulatory Surgical Centers, Private Practices |
| Companies Covered | Allergan Inc, Merz GmbH & Co KGaA, Galderma S.A., Cynosure Inc, Alma Lasers Ltd, Cutera Inc, Lumenis Ltd, Solta Medical Inc, Sciton Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhytidectomy Market Strategic Shifts & Innovations
Energy-based platforms are converging with surgical techniques to create hybrid procedure categories that blur traditional boundaries between invasive and non-invasive facial rejuvenation.
Radiofrequency-assisted lipolysis with simultaneous subdermal heating is hybridizing facelift procedures by enabling tissue tightening without extensive undermining. High-volume United States aesthetic practices adopt these systems to capture patients declining traditional surgery. The technology is hybridizing competitive positioning between surgical and device-based segments.
EU Medical Device Regulation clinical evidence thresholds filter market access for thread lift and energy-based platforms, imposing biocompatibility and performance documentation burdens that smaller manufacturers cannot satisfy. European notified body capacity constraints extend certification timelines. Thread lift product categories face the steepest compliance cost escalation.
Patient financing integration now precedes consultation scheduling in United States self-pay channels, with third-party lenders embedding pre-approval workflows into clinic intake systems. Traditional fee-for-service models lose volume to subscription-based aesthetic membership programs. California and Florida metropolitan markets exhibit the highest financing penetration rates.
Rhytidectomy Market Segmentation
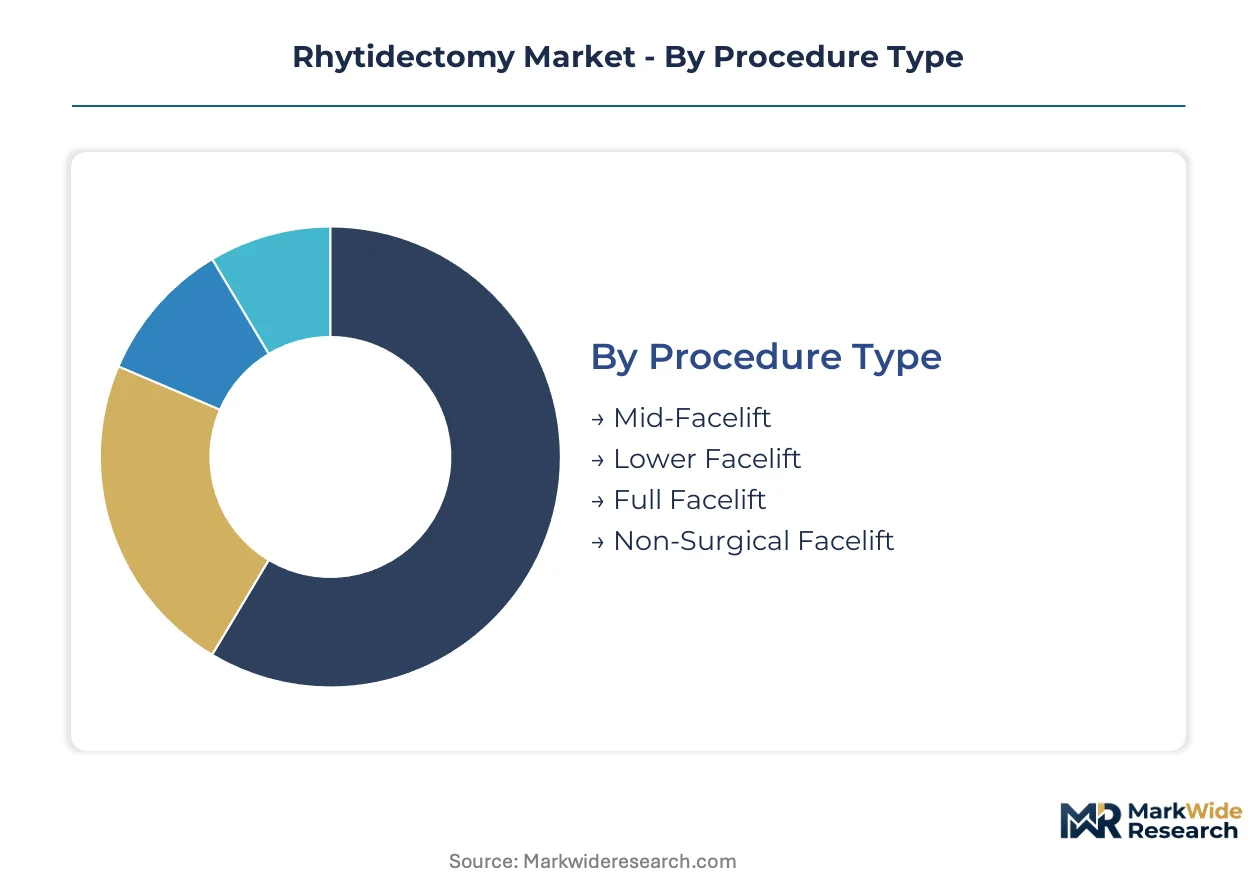
Rhytidectomy segmentation reveals distinct service intensity profiles across procedure tiers. Postoperative monitoring requirements and revision rates vary significantly by technique and patient cohort, shaping provider capacity planning and revenue per case.
Procedure Type:
After-sales service intensity escalates with tissue manipulation depth and incision complexity, driving follow-up visit frequency and complication management protocols.
- Full Facelift:Comprehensive SMAS elevation with preauricular and temporal incisions demands the highest postoperative surveillance cadence. United States metropolitan practices concentrate demand here, where disposable income thresholds support premium pricing and extended care packages.
- Non-Surgical Facelift:Energy-based and injectable protocols require iterative maintenance sessions rather than discrete surgical events. California and Florida clinics capture volume through membership models that embed recurring touchpoints into patient relationships.
- Mid-Facelift:Targeted malar fat pad repositioning addresses isolated midface ptosis with moderate recovery intervals.
- Lower Facelift:Cervicofacial contouring focuses on jowl and neck laxity with standardized postoperative pathways.
Full facelift holds the largest share; momentum sits with non-surgical facelift.
Technique:
Cost tier stratification separates capital-intensive platform investments from labor-dependent manual dissection methods.
- Traditional:Open SMAS dissection with direct tissue visualization remains the reference standard for durable outcomes. Deep-plane credentialing through ASAPS-accredited fellowships limits qualified United States provider supply, preserving margin structures.
- Laser-Assisted:Subcutaneous laser heating enables tissue contraction with reduced undermining scope. FDA 510(k) pathway tightening extends commercialization timelines for device manufacturers, concentrating market access among established regulatory infrastructure holders.
- Minimal Invasive:Short-scar and limited-dissection variants reduce operative time and facility overhead.
- Endoscopic:Camera-assisted dissection through minimal access ports targets brow and midface applications with reduced scarring profiles.
Traditional technique anchors revenue concentration; endoscopic methods are climbing the fastest.
Patient Type:
Application urgency and psychological readiness create distinct conversion funnel dynamics across patient cohorts.
- Age-Related Patients:Cumulative elastin degradation and gravitational ptosis drive procedural candidacy in the 55-70 demographic. Self-pay concentration in United States markets reflects Medicare cosmetic exclusion policies.
- Cosmetic Seekers:Preventive intervention motivation in the 40-55 cohort sustains mini-lift and early intervention volumes. South Korea's Gangnam district clustering captures this segment through integrated medical tourism infrastructure.
- Reconstructive Candidates:Post-traumatic or post-oncologic facial nerve and soft tissue restoration requires specialized microsurgical expertise.
- Others:Gender-affirming facial feminization and secondary revision cases occupy specialized practice niches.
Age-related patients hold the largest share; cosmetic seekers are gaining share fastest.
End User:
Volume concentration patterns reflect facility fee structures and scope-of-practice regulations that shape provider economics.
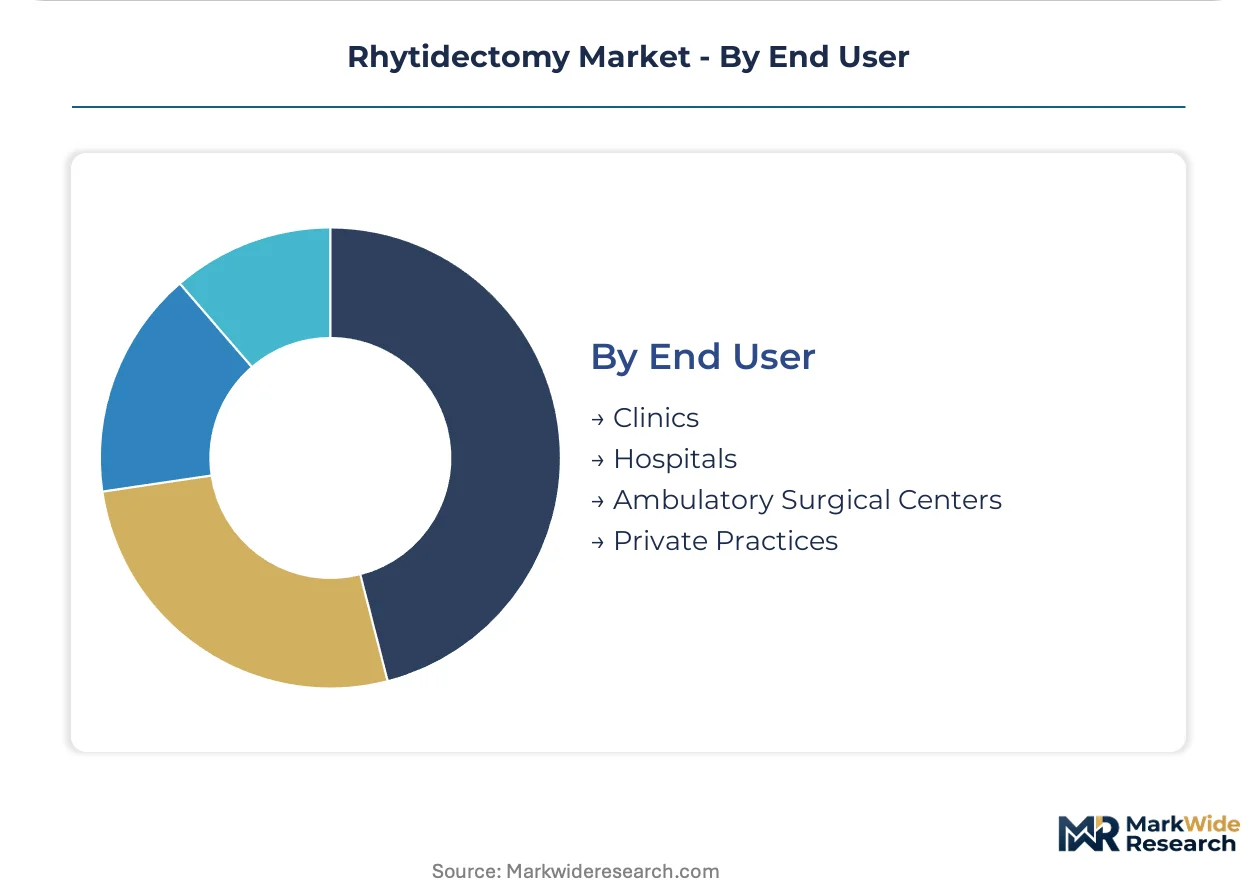
- Ambulatory Surgical Centers:CMS facility fee differentials incentivize outpatient migration for appropriately selected patients. United States metropolitan markets exhibit the steepest ASC penetration rates where certificate-of-need restrictions permit.
- Private Practices:Integrated surgical suites enable procedure capture without third-party facility dependency. Bundled pricing control and direct financing relationships maximize lifetime patient value in premium United States markets.
- Hospitals:Academic medical centers anchor complex reconstructive and revision case referrals with resident training integration.
- Clinics:Non-surgical and thread-lift service lines concentrate in high-volume aesthetic chains with standardized protocols.
Ambulatory surgical centers hold the largest share; private practices show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhytidectomy consumption patterns diverge sharply by geography. United States patients favor comprehensive surgical interventions with extended care packages, while South Korean demand clusters on preventive mini-lift procedures integrated with medical tourism itineraries.
United States
Aging demographics and disposable income concentration in coastal metropolitan markets sustain premium surgical volumes. FDA 510(k) pathway tightening for laser-assisted devices extends commercialization timelines for manufacturers. Los Angeles and Miami anchor the highest procedure densities, where private practice integrated suites capture patients through direct financing relationships.
South Korea
Medical tourism infrastructure and cultural normalization of cosmetic intervention drive international patient acquisition. MFDS regulates thread lift and energy-based platforms under strengthened biocompatibility documentation requirements. Seoul's Gangnam district concentrates over 500 specialized cosmetic surgery clinics in a coordinated ecosystem targeting Chinese and Southeast Asian visitors.
Germany
Technical precision expectations and statutory health insurance exclusion for cosmetic indications shape self-pay market development. EU Medical Device Regulation imposes clinical evidence thresholds on thread lift systems that filter smaller manufacturers. Munich and Düsseldorf aesthetic surgery centers specialize in deep-plane technique standardization through ASAPS-accredited fellowship programs.
Brazil
Cultural acceptance of body aesthetics and competitive pricing relative to North American markets attract regional medical tourism flows. ANVISA regulates laser-assisted and radiofrequency devices with premarket validation requirements modeled on FDA pathways. São Paulo's Jardins district clusters high-volume aesthetic practices with standardized postoperative care protocols.
Japan
Subtle rejuvenation preferences and aging population demographics sustain demand for minimally invasive techniques. PMDA oversees medical device approval with emphasis on long-term safety surveillance for absorbable suture systems. Tokyo's Ginza and Omotesando districts concentrate premium clinics specializing in natural-appearing outcomes through limited-dissection methods.
Rhytidectomy Market Key Industry Players
Capability concentration sits with specialized surgical device manufacturers; scale advantage sits with diversified aesthetic pharmaceutical portfolios. The vendor base organizes into three tiers: established regulatory infrastructure holders, minimally invasive technology specialists, and energy-based platform developers. Dominant competitive moves include strategic partnerships between device manufacturers and premium clinic networks, plus portfolio diversification through adjacent dermal filler and thread lift product integration.
Within the pharmaceutical-anchor tier, Allergan Inc and Galderma S.A. represent integrated aesthetic portfolio strategies that bundle surgical adjacencies with injectable revenues. Merz GmbH & Co KGaA occupies a position among German-based specialists emphasizing R&D intensity in absorbable suture technologies. These three entities exemplify divergent pathways to patient retention: pharmaceutical bundling, device innovation, and minimally invasive technique maturation.
| Leading Market Players |
|---|
| Allergan Inc |
| Merz GmbH & Co KGaA |
| Galderma S.A. |
| Cynosure Inc |
| Alma Lasers Ltd |
| Cutera Inc |
| Lumenis Ltd |
| Solta Medical Inc |
| Sciton Inc |
| Others |
Cost & Logistics Intelligence
Ambulatory surgical center undercapacity in secondary United States metropolitan markets is compressing facility fee negotiations while concentrating pricing power among integrated private practices with captive surgical suites. This utilization asymmetry drives supplier consolidation toward high-throughput aesthetic chains and forces device manufacturers into extended payment terms to secure ASC placement.
Pricing Analysis
Project-based surgical contracting dominates full facelift procedures, while membership subscriptions anchor non-surgical facelift revenues in California and Florida clinics. Price differentiation separates ASAPS-accredited deep-plane surgeons from mini-lift generalists, with certification tier commanding premium positioning. Pricing pressure stems from energy-based substitute platforms capturing price-sensitive cosmetic seekers in the 40-55 demographic. Thread-lift patients exhibit highest price sensitivity; deep-plane candidates show lowest.
Supply Chain Analysis
Export-control restrictions on laser-assisted device components limit flows from German and United States precision-optics manufacturers to South Korean and Brazilian assemblers. Absorbable polydioxanone sutures draw from South Korean and German polymer suppliers, with radiofrequency generator chips resting on Taiwan semiconductor foundries. Single-source vulnerability concentrates in FDA-cleared laser handpiece suppliers. Distribution runs through GPO-integrated hospital systems and direct-to-clinic aesthetic device specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as patient financing integration and hybrid surgical-device protocols splinter demand across specialized service tiers. Preventive intervention motivation in younger demographics fragments traditional age-based segmentation.
For Market Incumbents: Entrench regulatory infrastructure advantages by deepening FDA 510(k) pathway expertise and acquiring thread-lift technology specialists before EU MDR compliance costs filter smaller competitors. Anchor patient retention through dermal filler-anchored facelift bundles that capture lifetime value across surgical and non-surgical touchpoints. Energy-based substitute platforms threaten margin compression in mini-lift segments; vertical integration into absorbable suture manufacturing preserves cost control. For New Entrants and Emerging Players: Establish a beachhead in postoperative care protocol expansion where scope-of-practice liberalization in select United States states enables non-physician provider participation. Target medical tourism infrastructure gaps in Southeast Asian markets outside Seoul's saturated Gangnam cluster. Penetrate through hybrid procedure training programs that credential physicians on radiofrequency-assisted lipolysis adjuncts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aesthetic clinic chains with embedded membership models and direct financing relationships; these archetypes offer superior cash-flow quality versus device manufacturers facing FDA validation timeline extension. Five-to-ten year viability favors platforms with regulatory infrastructure depth across multiple geographies. Watch for inflection in state-level scope-of-practice legislation enabling non-physician provider expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Investment | Extended validation timelines concentrate market access among established regulatory infrastructure holders. |
| EU MDR Compliance Certification | Clinical evidence thresholds filter thread-lift and energy-based platform competitors from European markets. |
| Medical Tourism Infrastructure Partnership | Seoul's Gangnam district clustering demonstrates patient acquisition leverage through integrated cosmetic surgery ecosystems. |
| Patient Financing Integration | Pre-approval workflow embedding in California and Florida clinic intake systems converts price-sensitive consultations. |
| Deep-Plane Technique Standardization | ASAPS-accredited fellowship protocols differentiate high-margin surgical offerings from commoditized mini-lift alternatives. |
Research Approach
The analysis maps full facelift, non-surgical facelift, mid-facelift, and lower facelift segments, each validated through plastic surgeons, ambulatory surgical center administrators, biomedical engineers, and aesthetic clinic operations directors. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS facility fee schedules, hospital procurement databases, and GPO contract records. Bottom-up procedure volume estimates triangulated against top-down market value reconstruction.
Assumptions held fixed include FDA regulatory pathway timelines, Medicare cosmetic exclusion policies, and EU MDR compliance cost structures; variables stress-tested across patient financing penetration rates, scope-of-practice liberalization velocity, and energy-based device substitution curves. Segmentation dimensions modeled span procedure type, technique category, patient demographic cohort, and end-user facility class across the projection horizon. CAGRs derived from fitted growth curves applied to base-year procedure volume estimates, with inputs including aging demographic projections and disposable income concentration indices.
Stress conditions across reimbursement policy shifts, regulatory timeline extensions, and substitute technology adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to FDA premarket notification pathway changes and state-level scope-of-practice legislation. Material shifts in Medicare cosmetic indication coverage determination would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market