
 Global Blepharoplasty Market | 2026-2036
Global Blepharoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blepharoplasty Market Foresight
A shortage of oculoplastic fellowship-trained surgeons is reorganizing service delivery across developed markets. Stryker Corporation leverages its precision instrument portfolio to sustain dominance in operating room infrastructure for eyelid procedures. Cynosure LLC anchors its position through laser technology leadership in non-surgical periorbital applications. Lumenis BE Ltd. differentiates via energy-based platforms that compete across both surgical and aesthetic channels.
Blepharoplasty denotes surgical modification of the eyelid through excision, repositioning, or reinforcement of skin, muscle, and orbital fat to correct functional impairment or aesthetic concerns; procedures typically require 1-3 hours under local or general anesthesia with suture removal at 5-7 days. Upper eyelid surgery occupies the largest procedural volume globally due to age-related ptosis and visual field obstruction indications. Laser surgery represents the fastest-expanding technique segment as patients seek reduced bruising and faster return to work. Double eyelid surgery concentrates margin pools across East Asian markets where aesthetic preference drives premium pricing.
The FDA regulates blepharoplasty devices and energy-based platforms through 510(k) and PMA pathways, while the EU AI Act and MDR impose escalating clinical evidence requirements on surgical robotics and AI-assisted planning tools. South Korea's MFDS maintains accelerated approval tracks for aesthetic devices, creating regulatory arbitrage that channels innovation investment toward Seoul's Gangnam district. Stakeholders must monitor evolving reimbursement policies for functional versus cosmetic indications as payor scrutiny intensifies across public health systems.
Market Dynamics
The blepharoplasty market is restructuring around a pronounced shortage of oculoplastic fellowship-trained surgeons, which is forcing aesthetic clinics to delegate routine procedures to general plastic surgeons and nurse injectors while reserving complex revisions for specialists.
Growth Catalysts
- MFDS Accelerated Approval Tracks:South Korea's streamlined regulatory pathways for aesthetic devices channel innovation investment toward Seoul's Gangnam district, compressing time-to-market for laser-assisted blepharoplasty platforms.
- Preventive Rejuvenation Demand:Patients in their late twenties and early thirties across São Paulo and Dubai seek upper eyelid procedures before visible aging, expanding addressable volume beyond traditional Medicare-age cohorts.
- Transconjunctival Technique Diffusion:Scarless lower eyelid approaches gain preference among working professionals requiring minimal downtime, displacing transcutaneous methods in premium urban markets.
Market Restraints
- Oculoplastic Surgeon Supply Concentration:Fellowship programs in the United States and Western Europe graduate fewer than 40 specialists annually, creating geographic access deserts and surgical backlogs.
- FDA 510(k) Evidence Requirements:Energy-based devices for periorbital applications face escalating clinical documentation burdens, extending approval timelines and freezing smaller manufacturers from commercialization.
- Injectable Neurotoxin Substitution:Botulinum toxin and hyaluronic acid fillers capture mild-to-moderate eyelid aging cases at lower price points, siphoning volume from surgical blepharoplasty.
Strategic Opportunities
- Tehran and Istanbul Medical Tourism Corridors:Iran and Turkey offer double eyelid and epicanthoplasty packages at one-third of Seoul pricing, attracting patients from Central Asia, the Caucasus, and diaspora communities in Western Europe.
- EU MDR Harmonization Arbitrage:Manufacturers achieving CE marking under the Medical Device Regulation gain streamlined market access across 27 member states, creating first-mover advantages in laser platform distribution.
- AI-Assisted Surgical Planning Convergence:Integration of three-dimensional imaging with predictive outcome modeling enables personalized incision mapping, differentiating high-volume clinic chains from independent practitioners.
Industry Challenges
- Oculoplastic Fellowship Pipeline Collapse:Academic medical centers prioritize oncology and trauma fellowships over aesthetic subspecialties, shrinking the specialist replacement rate below retirement velocity.
- Malpractice Premium Escalation:Periorbital surgery carries elevated litigation risk for visual impairment claims, concentrating insured practice in large hospital systems and excluding independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blepharoplasty Market |
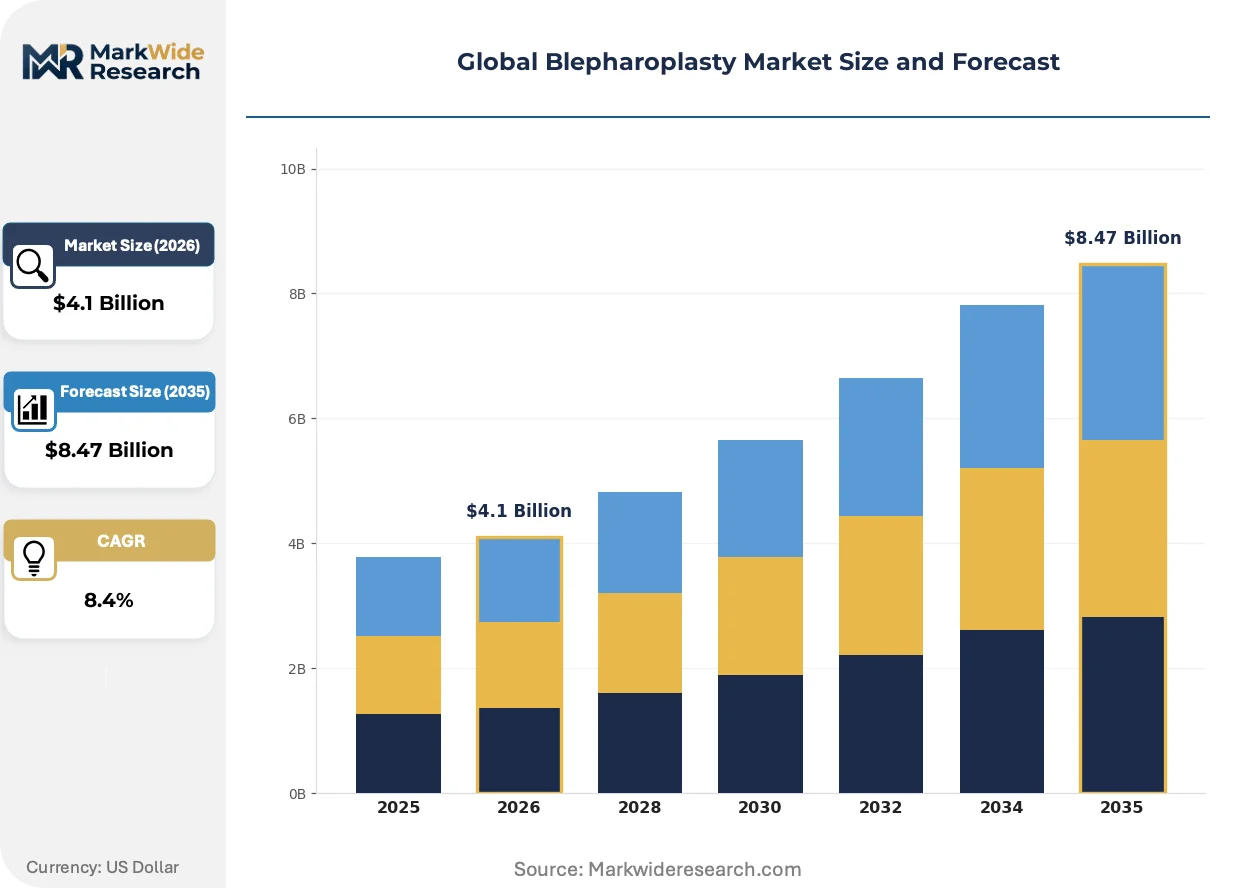
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Upper Eyelid Surgery, Lower Eyelid Surgery, Double Eyelid Surgery, Revision Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Cosmetic Surgeons Technique: Traditional Surgery, Laser Surgery, Transconjunctival Surgery, Non-Surgical Options Gender: Male, Female, Non-Binary, Others |
| Companies Covered | Stryker Corporation, Surgical Holdings, Cynosure LLC, Grand Aespio Inc., Bomtech Electronics Co. Ltd., Lumenis BE Ltd., Integra LifeSciences Corporation, GTG Wellness, Sisram Medical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blepharoplasty Market Shifts & Advancements
Laser and energy-based modalities are fragmenting the blepharoplasty technique landscape, creating parallel markets for incisional surgery and non-ablative rejuvenation while reshaping training curricula and capital equipment procurement.
Fractional carbon dioxide laser technology is bifurcating the upper eyelid segment. Aesthetic clinics in Dubai and São Paulo deploy these platforms for skin tightening without excision, capturing patients who decline scalpel-based methods. The technology is compressing average revenue per procedure while expanding total addressable volume through lower price points and reduced recovery intervals.
The EU AI Act and MDR impose escalating clinical evidence requirements on surgical robotics and AI-assisted planning tools. Manufacturers must now submit prospective outcome data for algorithmic incision guidance systems, favoring well-capitalized device firms with dedicated regulatory affairs functions. South Korea's MFDS maintains separate accelerated tracks, creating regulatory arbitrage that channels robotics development toward Seoul.
Direct-to-consumer financing platforms are disrupting traditional fee-for-service arrangements in aesthetic surgery. Third-party lenders in the United States and Brazil offer procedure-specific installment products, unbundling payment from clinic cash flow and enabling younger demographics to access premium double eyelid and laser blepharoplasty services. This shift concentrates volume in metropolitan clinic chains with established lending partnerships.
Global Blepharoplasty Market Segmentation
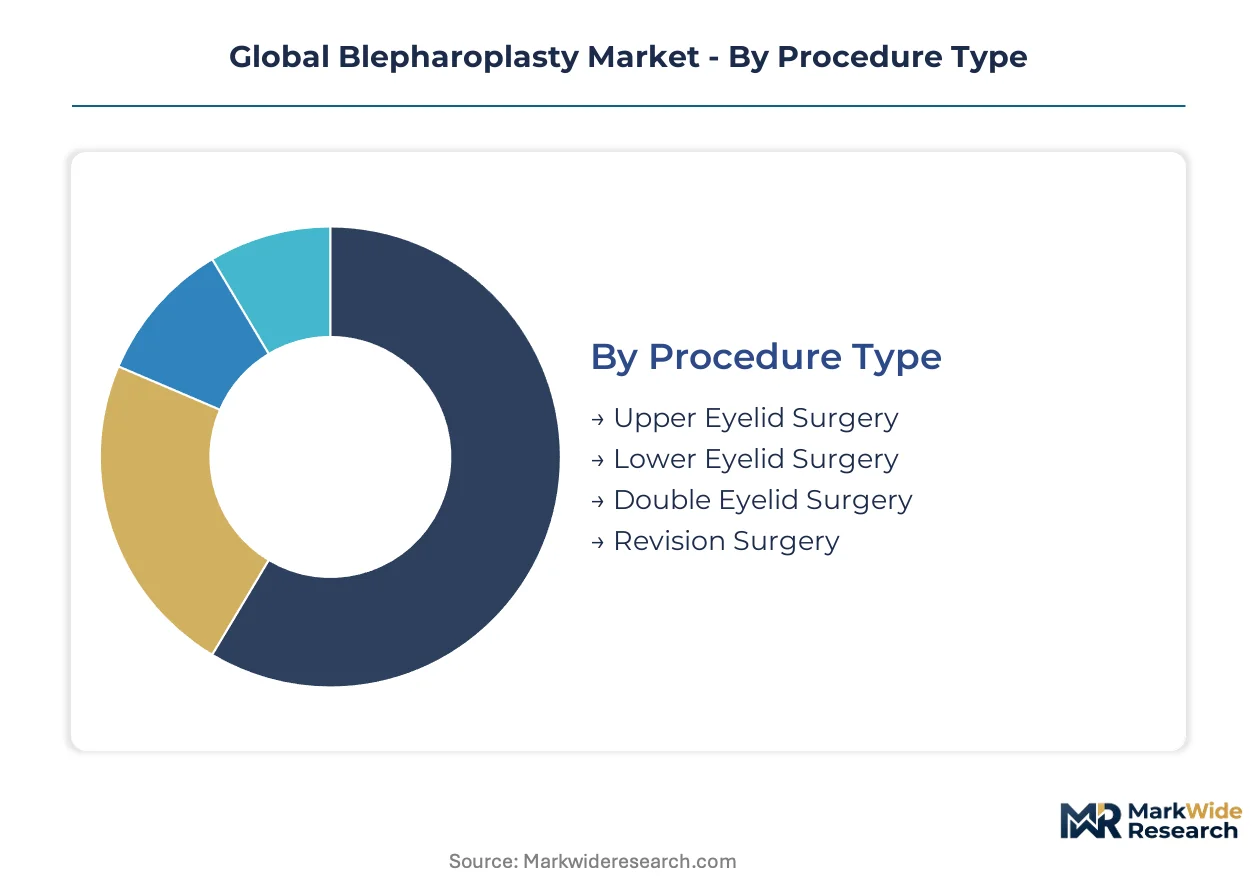
Segmentation in blepharoplasty reveals how procedure complexity, setting economics, and patient demographics channel demand across distinct service tiers. Each dimension exposes different margin structures, capital requirements, and competitive dynamics that shape vendor positioning and clinic investment priorities.
Procedure Type:
Channel flow varies sharply by anatomical target and surgical complexity, with functional indications routing through insured hospital pathways while aesthetic procedures concentrate in cash-pay cosmetic clinics.
- Upper Eyelid Surgery:Excision of redundant skin and orbicularis oculi muscle to correct visual field obstruction or age-related hooding. Medicare-age patients in the United States and Germany drive insured volume through hospital outpatient departments, though South Korean clinics capture premium aesthetic cases from Southeast Asian medical tourists seeking simultaneous double eyelid creation.
- Double Eyelid Surgery:Creation or enhancement of the supratarsal fold through suture ligation or incisional methods, predominantly performed in East Asian populations. Seoul's Gangnam district commands the highest pricing globally, with Dubai and São Paulo clinics now replicating the service model for diaspora and expatriate demand.
- Lower Eyelid Surgery:Transcutaneous or transconjunctival fat repositioning to address infraorbital hollowing and festooning.
- Revision Surgery:Corrective procedures for complications or unsatisfactory outcomes from prior operations.
By volume, upper eyelid surgery leads. By growth pace, double eyelid surgery is expanding most quickly.
End User:
Capital intensity and regulatory burden stratify service delivery, with high-acuity settings absorbing complex functional cases while lighter facilities capture standardized aesthetic volume.
- Hospitals:Academic medical centers and community hospitals maintain operating room infrastructure for combined blepharoplasty-ptosis repair and trauma reconstruction. Visual field testing requirements and anesthesia protocols in the United States and France concentrate functional indications here, though lengthy scheduling queues push elective patients toward ambulatory alternatives.
- Cosmetic Surgeons:Independent practitioners and small group practices specializing in facial aesthetic surgery. Brazil's consolidated cosmetic surgery market and Iran's Tehran-based epicanthoplasty specialists exemplify this channel's dominance in price-sensitive, high-volume aesthetic corridors.
- Ambulatory Surgical Centers:Dedicated outpatient facilities with streamlined anesthesia protocols.
- Clinics:Non-hospital settings offering laser and energy-based periorbital treatments.
Hospitals retain the largest procedure count. Cosmetic surgeons are gaining share fastest.
Technique:
Technology adoption curves diverge by recovery tolerance and scar sensitivity, with working professionals prioritizing downtime minimization over absolute cost.
- Laser Surgery:Energy-based incision and coagulation using fractional CO2 or erbium platforms. Dubai and São Paulo aesthetic chains deploy these systems for upper eyelid skin tightening without scalpel excision, capturing patients who prioritize rapid return to professional visibility over maximum tissue removal.
- Transconjunctival Surgery:Scarless lower eyelid fat repositioning via conjunctival incision. South Korean training programs pioneered technique standardization, with MFDS-approved device platforms now diffusing to Istanbul and Bangkok clinics serving medical tourism flows.
- Traditional Surgery:Scalpel-based excision and suture closure.
- Non-Surgical Options:Injectable neurotoxins and dermal fillers for mild periorbital aging.
Traditional surgery still dominates procedure counts. Laser platforms are climbing the fastest.
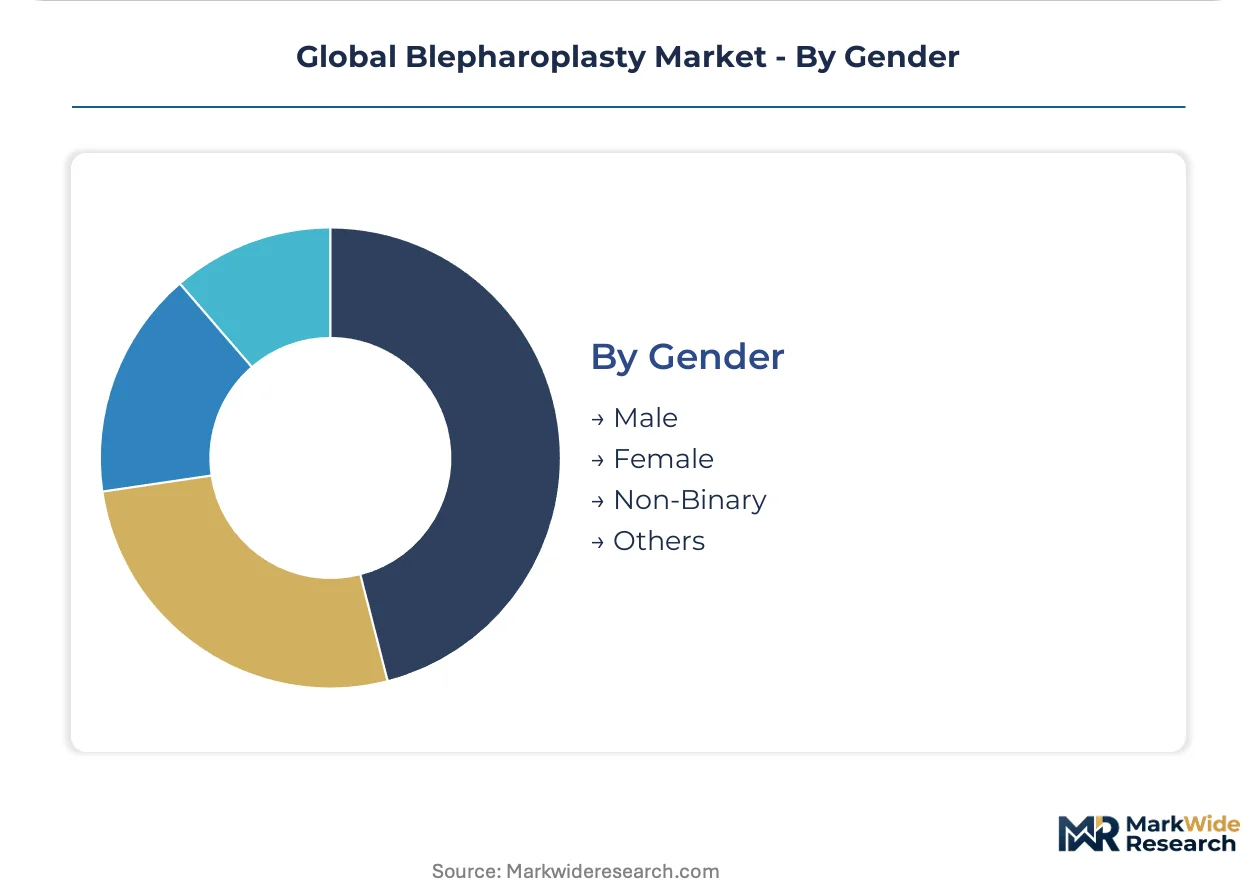
Gender:
Marketing investment and service packaging diverge by demographic, with distinct consultation pathways and outcome expectations shaping clinic workflow design.
- Female:Historical majority of blepharoplasty demand, concentrated in age-related upper eyelid rejuvenation and double eyelid creation. South Korean and Japanese clinics have refined female-targeted consultation protocols, with Seoul's Gangnam district operating dedicated recovery lounges and social media integration for this segment.
- Male:Fastest-growing demographic as stigma diminishes and professional appearance pressures intensify. São Paulo and Los Angeles clinics now offer male-specific marketing and surgical planning, emphasizing natural results and preserved brow position.
- Non-Binary:Gender-affirming periorbital modification.
- Others:Declined specification or institutional non-disclosure.
Females account for the largest current volume. Male demand is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight in the United States anchors the most stringent device approval environment, while Seoul's Gangnam district and Dubai's healthcare free zones concentrate aesthetic innovation investment. National regulators across five major markets shape surgical standards, reimbursement pathways, and medical tourism flows through divergent approval timelines and evidence requirements.
United States
Medicare-age patients drive insured upper eyelid volume through hospital outpatient departments for visual field obstruction cases. FDA 510(k) and PMA pathways impose escalating clinical documentation burdens on energy-based periorbital devices, extending approval timelines for smaller manufacturers. Los Angeles and New York Metro aesthetic chains now deploy male-specific marketing to capture fastest-growing demographic demand.
South Korea
Seoul's Gangnam district commands premium pricing for double eyelid surgery and epicanthoplasty, attracting Southeast Asian medical tourists seeking simultaneous procedures. MFDS accelerated approval tracks compress time-to-market for laser-assisted blepharoplasty platforms, channeling robotics development toward domestic manufacturers. Training programs in the capital pioneered transconjunctival technique standardization now diffusing to Bangkok and Istanbul clinics.
Brazil
São Paulo's consolidated cosmetic surgery market captures preventive rejuvenation demand from patients in their late twenties seeking upper eyelid procedures before visible aging. ANVISA regulates aesthetic devices through risk-based classification pathways, though approval timelines lag Seoul's streamlined tracks. Direct-to-consumer financing platforms unbundle payment from clinic cash flow, enabling younger demographics to access premium services through metropolitan clinic chains.
Germany
Hospital outpatient departments maintain operating room infrastructure for combined blepharoplasty-ptosis repair under statutory health insurance coverage. EU MDR imposes escalating clinical evidence requirements on surgical robotics and AI-assisted planning tools, favoring well-capitalized device firms with dedicated regulatory affairs functions. Bavaria's academic medical centers concentrate fellowship-trained oculoplastic specialists serving cross-border demand from Austria and Switzerland.
United Arab Emirates
Dubai's healthcare free zones deploy fractional carbon dioxide laser platforms for upper eyelid skin tightening without scalpel excision, capturing working professionals prioritizing rapid return to visibility. MOHAP maintains separate regulatory tracks for aesthetic versus functional indications, with shorter pathways for devices already holding FDA or CE marking. Medical tourism corridors from Central Asia and the Caucasus channel double eyelid demand toward Tehran and Istanbul competitors at one-third of Seoul pricing.
Global Blepharoplasty Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision instrument manufacturers dominating operating room infrastructure while laser platform specialists capture non-surgical periorbital applications. The vendor base stratifies across three tiers: multinational device conglomerates with dedicated regulatory affairs functions, mid-scale energy-based platform specialists, and regional aesthetic equipment fabricators serving price-sensitive corridors. Strategic moves concentrate on M&A for regulatory capability acquisition and geographic expansion through distributor partnerships in medical tourism hubs.
Among precision instrument conglomerates, Stryker Corporation and Integra LifeSciences Corporation occupy positions anchored in hospital system procurement relationships. Laser and energy-based platform specialists exemplify the technology-differentiation archetype, with Cynosure LLC and Lumenis BE Ltd. sitting within segments where reduced bruising and faster recovery intervals command premium positioning. Regional specialists including Bomtech Electronics Co. Ltd. represent the cost-competitive tier, with Seoul-based manufacturing proximity to Gangnam district demand clusters.
| Leading Market Players |
|---|
| Stryker Corporation |
| Surgical Holdings |
| Cynosure LLC |
| Grand Aespio Inc. |
| Bomtech Electronics Co. Ltd. |
| Lumenis BE Ltd. |
| Integra LifeSciences Corporation |
| GTG Wellness |
| Sisram Medical Ltd. |
| Others |
Supply & Pricing Matrix
Capital intensity in laser platform manufacturing concentrates production among Seoul, Irvine, and Yokneam-based device fabricators, compressing margins for second-tier assemblers while anchoring price floors to precision optics and fiber delivery system costs. This scale concentration funnels procurement power toward hospital systems and metropolitan clinic chains with volume commitments, forcing independent practitioners toward leasing arrangements or refurbished equipment channels.
Pricing Analysis
Seoul's Gangnam district commands triple the procedural pricing of Tehran and Istanbul corridors for identical double eyelid techniques, with Dubai and São Paulo occupying mid-tier positioning. Three-tier pricing structure across premium laser-assisted, standard incisional, and economy suture-ligation methods segments patient access by recovery tolerance and scar sensitivity. Pricing pressure stems from injectable neurotoxin substitution capturing mild cases at lower price points, with working professionals in late-twenties cohorts exhibiting highest price sensitivity while Medicare-age functional patients show lowest elasticity due to insured coverage.
Supply Chain Analysis
Just-in-time inventory strategies dominate laser handpiece and consumable procurement among metropolitan clinic chains, while hospital systems maintain strategic stockpiles of precision micro-instrument sets for emergency ptosis repairs. Manufacturing concentrates in South Korea, Israel, and the United States for energy-based platforms, with Germany and Japan supplying precision surgical instrumentation. Supply chains draw from rare-earth fiber lasers, medical-grade titanium, and sterile disposable drapes as critical inputs. Single-source vulnerability in precision optics from Israeli suppliers creates concentration risk. Distribution runs through specialized medical device distributors with surgeon training capabilities, bypassing general hospital procurement for aesthetic indications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated metropolitan clinic chains with direct-to-consumer financing partnerships, fragmenting demand among independent practitioners and compressing their procurement leverage.
For Market Incumbents: Fortify regulatory affairs capabilities to navigate FDA 510(k) documentation burdens and EU MDR clinical evidence requirements, creating defensive moats against smaller manufacturers frozen from commercialization. Deepen backward integration into precision optics manufacturing to secure supply continuity against Israeli supplier concentration. Anchor hospital system relationships through combined blepharoplasty-ptosis repair training programs, defending against ambulatory surgical center volume capture. For New Entrants and Emerging Players: MFDS accelerated approval tracks offer the fastest pathway to commercial launch for laser-assisted platforms, compressing time-to-market versus FDA timelines. Target Tehran and Istanbul medical tourism corridors with cost-optimized double eyelid packages, capturing Central Asian and Caucasus patient flows at one-third Seoul pricing. Deploy AI-assisted surgical planning as differentiation wedge against established clinic chains, offering personalized outcome visualization to independent practitioners. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among laser platform specialists with disposable handpiece and maintenance contract attachment, outperforming capital equipment-only vendors across the analysis window. Long-term viability favors manufacturers with dedicated regulatory affairs functions and CE marking under EU MDR. Acquisition targets should demonstrate installed base expansion in medical tourism hubs. The signal to watch is oculoplastic fellowship graduation rates falling below retirement velocity, indicating demand compression for complex revision services.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Accelerated Approval Pathway | Seoul-based manufacturers compress commercialization timelines versus FDA tracks, capturing Gangnam district demand clusters first. |
| AI-Assisted Surgical Planning Development | Three-dimensional imaging integration differentiates high-volume clinic chains from independent practitioners in outcome prediction. |
| Direct-to-Consumer Financing Partnership | Third-party lenders in São Paulo and Los Angeles unbundle payment from clinic cash flow, expanding addressable volume. |
| Transconjunctival Technique Training Programs | Seoul-trained specialists diffuse scarless lower eyelid methods to Bangkok and Istanbul medical tourism corridors. |
| Hospital System GPO Contracting | Academic medical center procurement relationships secure visual field obstruction case volume under Medicare coverage. |
Research Methodology
Cross-validation between primary interviews with oculoplastic surgeons, aesthetic clinic operators, and biomedical engineering directors and secondary validation through FDA 510(k) filings, MFDS device registrations, and hospital procurement databases anchors the qualitative findings. Bottom-up procedure volume estimates from metropolitan clinic chains in Seoul, Dubai, São Paulo, and Los Angeles triangulate against top-down device shipment data from laser platform manufacturers. Primary fieldwork encompassed 12 distinct stakeholder roles including fellowship program directors, GPO contracts managers, and medical tourism facilitators.
Sensitivity analysis across pricing elasticity assumptions and oculoplastic surgeon supply scenarios tests forecast robustness over the projection horizon. Segmentation dimensions modeled include procedure type, technique platform, end-user setting, and patient demographic cohort. CAGRs derive from procedure volume trajectories weighted by average revenue per case across insured functional and cash-pay aesthetic pathways. Forecast inputs incorporate MFDS approval velocity, fellowship graduation rates, and neurotoxin substitution elasticities.
Decision-makers should treat outputs as directional under stable regulatory pathway assumptions; material deviation in FDA documentation requirements or EU MDR enforcement intensity would warrant model refresh. Forecasts reflect assumptions regarding oculoplastic specialist supply, laser platform adoption curves, and medical tourism corridor stability. Revision becomes warranted when fellowship program closures accelerate beyond replacement velocity or when injectable substitution rates cross elasticity thresholds in preventive rejuvenation segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
North America Cosmetic Surgery Market