
 Ultrasonic Tissue Ablation System Market | 2026-2036
Ultrasonic Tissue Ablation System Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Tissue Ablation System Market Intelligence
The shift from standard piezoceramics to advanced single-crystal piezoelectric materials for transducer fabrication is hardening performance benchmarks for new devices. Integra LifeSciences Corporation leverages its broad surgical portfolio to bundle these systems with complementary instruments. INSIGHTEC Ltd. differentiates through its focus on MR-guided focused ultrasound (MRgFUS) technology for neurological applications. Ethicon Inc. sustains its market position through extensive distribution networks within hospital systems.
Ultrasonic tissue ablation systems use high-intensity focused ultrasound (HIFU) to thermally coagulate and destroy targeted tissue volumes non-invasively. These devices operate at frequencies typically between 0.8 and 3.5 MHz to achieve precise focal points deep within the body. Oncology procedures represent the largest application segment, driven by the treatment of uterine fibroids, prostate cancer, and liver tumors. Hospitals remain the dominant end-user, although ambulatory surgery centers are showing accelerated adoption for outpatient services.
Device approval pathways are governed by stringent reviews from bodies like the US FDA for Premarket Approval (PMA). In Europe, compliance with the Medical Device Regulation (MDR) is mandatory, while China's NMPA sets distinct requirements for market entry. Future device development hinges on balancing the pursuit of higher energy delivery for faster ablation with enhanced safety features to protect non-target tissues.
Market Dynamics
The central force shaping the market is the convergence of advanced materials science with robotic-assisted surgery. The development of miniaturized, high-efficiency transducers enables integration with surgical robots, expanding the precision and applicability of non-invasive ablation in complex oncological procedures.
Growth Catalysts
- Advanced Transducer Materials:The transition from piezoceramics to single-crystal piezoelectric materials is improving energy conversion efficiency and focal accuracy, allowing for more effective and safer ablation procedures in dense tissues like the liver and prostate.
- Oncology Procedure Volume:A rising incidence of cancers suitable for non-invasive treatment, including uterine fibroids and prostate cancer, drives consistent demand from specialized cancer centers in the United States, Germany, and Japan.
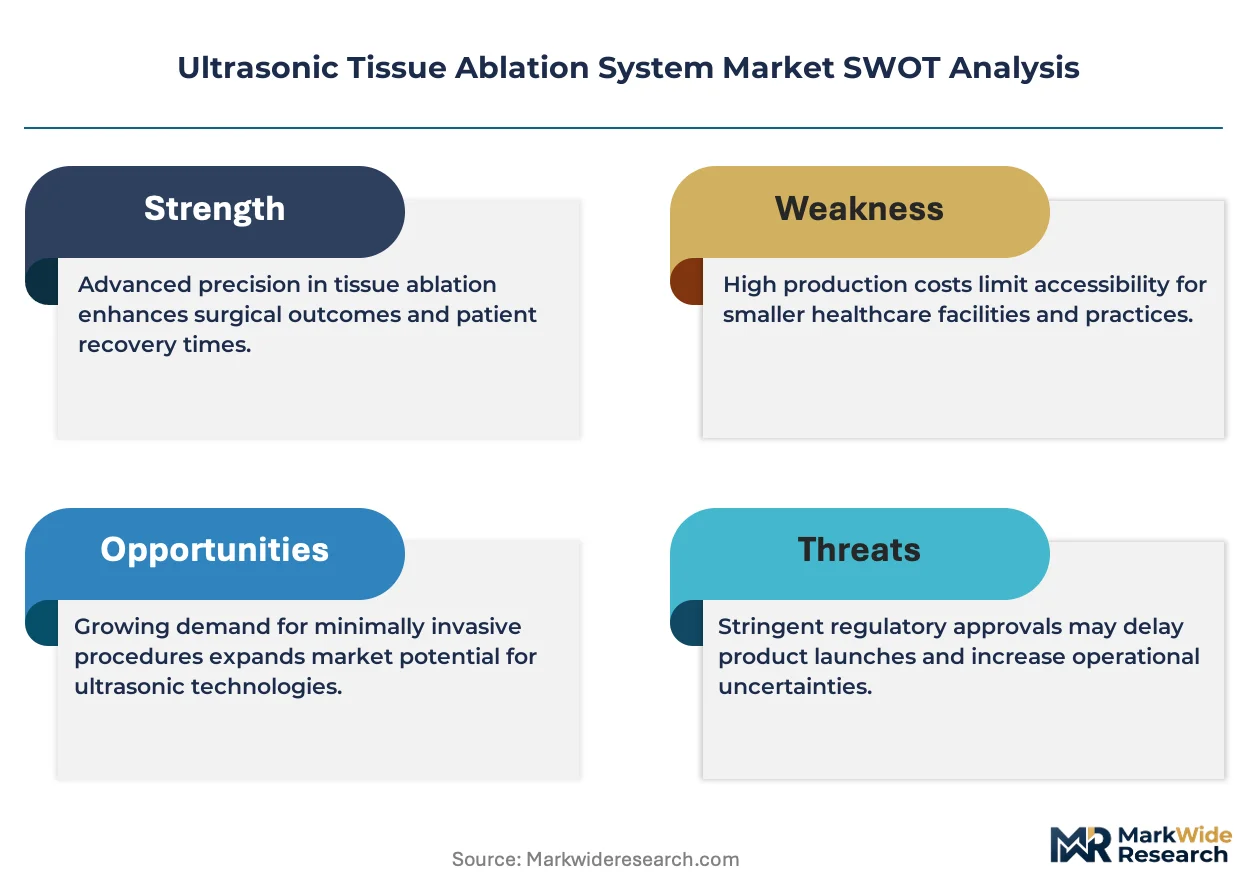
- Minimally Invasive Focus:Healthcare systems globally are prioritizing minimally invasive techniques to reduce hospital stays and patient recovery times, creating a favorable environment for the adoption of HIFU systems over traditional open surgery.
Market Restraints
- High Capital Expenditure:The significant upfront cost of acquiring and installing ultrasonic ablation systems, particularly MR-guided platforms, restricts adoption to well-funded hospitals and large treatment centers, limiting market penetration in smaller facilities.
- Stringent Regulatory Hurdles:Navigating complex and lengthy approval pathways, such as the Premarket Approval (PMA) process from the US FDA and MDR compliance in Europe, delays the introduction of new technologies and increases development costs.
- Limited Reimbursement Coverage:Inconsistent or inadequate reimbursement policies for certain HIFU procedures across different countries and private payers can deter both physicians and patients, constraining procedural volume and hospital investment.
Strategic Opportunities
- Expansion into Neurology:The application of MR-guided focused ultrasound (MRgFUS) for non-invasive neurosurgery, including treatment for essential tremor and other neurological conditions, represents a significant growth vector beyond traditional oncology.
- Integration with Artificial Intelligence:Incorporating AI algorithms for automated treatment planning, real-time tissue monitoring, and post-procedural analysis can enhance safety, improve outcomes, and reduce operator dependency, creating a new value proposition. *Penetration of Ambulatory Centers: Developing more compact and cost-effective systems tailored for outpatient settings opens a new channel, as ambulatory surgery centers (ASCs) seek to offer a wider range of minimally invasive procedures.
Industry Challenges
- Specialized Clinician Training:A shortage of surgeons and radiologists with the requisite training and expertise to safely and effectively operate advanced HIFU systems creates a bottleneck for wider technology diffusion and adoption. *System Interoperability: Ensuring seamless integration of ablation platforms with diverse hospital IT systems, including existing MRI scanners and electronic health records, remains a significant technical and logistical hurdle for vendors and end-users.
- Thermal Management Complexity:Balancing the need for high-energy delivery to ablate tissue rapidly with sophisticated cooling and monitoring to protect surrounding healthy structures is a persistent engineering challenge in device design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Tissue Ablation System Market |
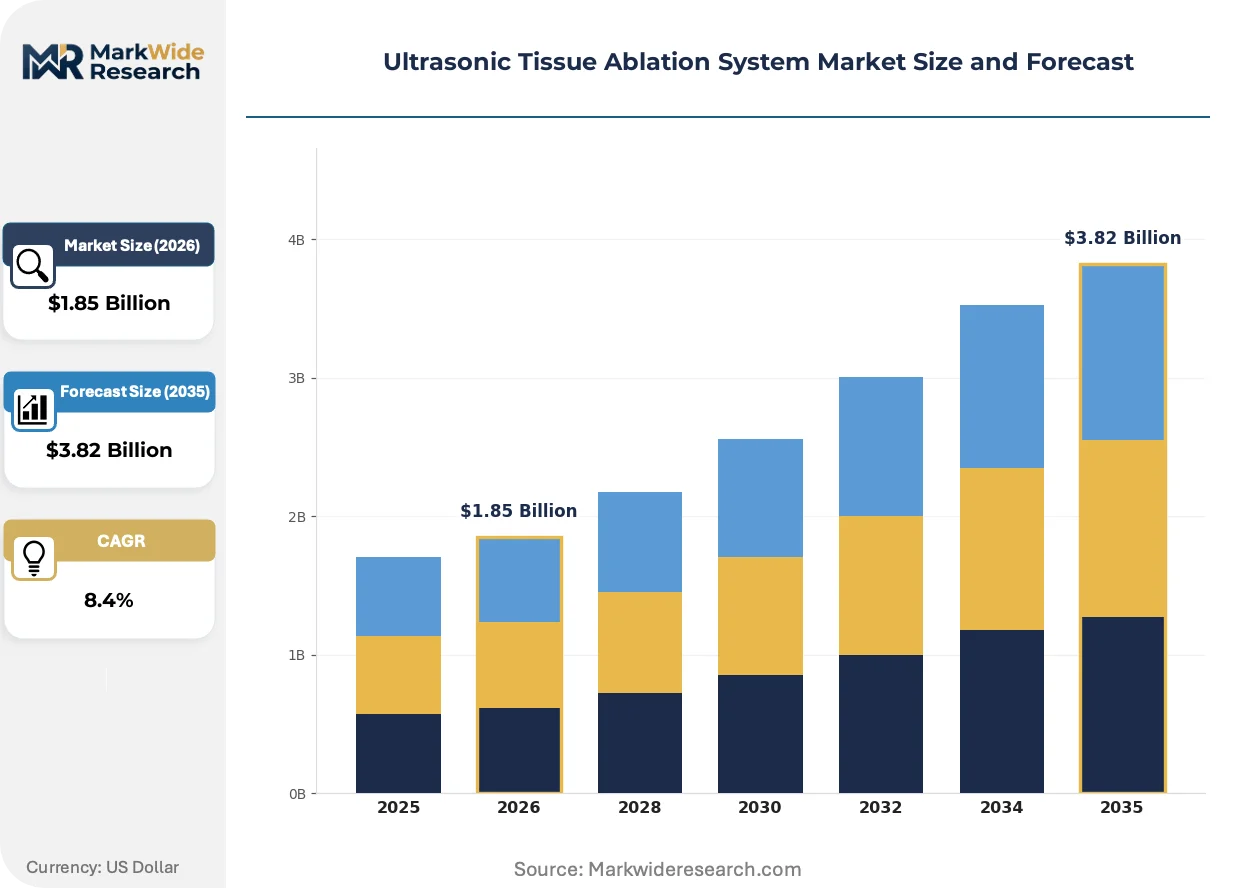
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Frequency Ultrasonic Devices, Portable Ablation Systems, Robotic-Assisted Devices, Disposable Handpieces Application: Oncology Procedures, Cardiology Interventions, Cosmetic Surgery, Pain Management End User: Hospitals, Ambulatory Surgery Centers, Research Institutions, Medical Clinics Delivery Mode: Minimally Invasive Techniques, Open Surgery Approaches, Outpatient Services, Inpatient Services |
| Companies Covered | Ethicon Inc., Johnson & Johnson, Integra LifeSciences Corporation, Misonix Inc., INSIGHTEC Ltd., Chongqing Haifu Medical Technology Co., Ltd., Alpinion Medical Systems, Theraclion, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Tissue Ablation System Market Strategic Shifts & Innovations
Technological evolution is centered on enhancing treatment precision and expanding the therapeutic window for ultrasonic ablation. Innovations in transducer materials, real-time imaging integration, and software-driven treatment planning are defining the next generation of devices, pushing capabilities beyond established oncological applications.
The use of advanced single-crystal piezoelectric materials provides superior electromechanical coupling and lower heat generation compared to traditional ceramics. Device manufacturers targeting high-performance applications in neurology and cardiology are rapidly adopting these materials. This material science shift is rewriting the performance benchmarks for focal sharpness and energy delivery efficiency, enabling treatment of previously inaccessible or high-risk tissue targets.
Europe's Medical Device Regulation (MDR) establishes more rigorous requirements for clinical evidence and life-cycle surveillance than the previous directive. This regulatory framework extends timelines for achieving CE marking, compelling manufacturers to invest more heavily in pre-market clinical trials. Devices intended for novel applications, such as pancreatic cancer or neurological disorders, are most impacted, requiring more robust data to prove safety and efficacy.
A clear behavioral shift is the migration of certain procedures from hospital operating rooms to outpatient facilities. This is particularly evident for treatments like uterine fibroid ablation, where ambulatory surgery centers can offer a more convenient and cost-effective patient experience. The trend is most advanced in the United States, where payer incentives and patient preference for minimal downtime are accelerating this transition.
Ultrasonic Tissue Ablation System Market Segmentation
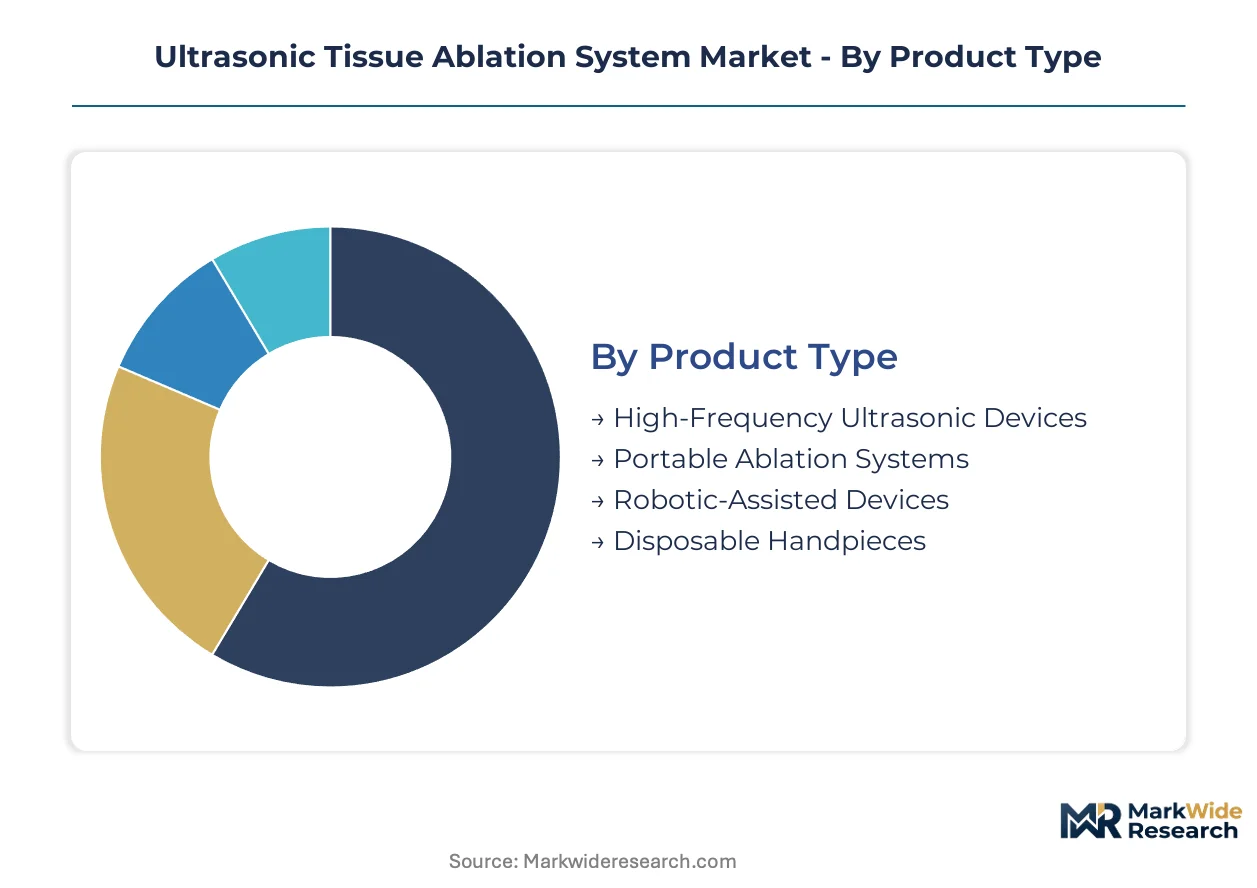
The Ultrasonic Tissue Ablation System market exhibits distinct segmentation, reflecting diverse technological approaches, clinical applications, and end-user requirements. Understanding these segments is critical for manufacturers to tailor product development, refine market entry strategies, and address specific clinical needs across various healthcare settings.
Product Type:
The product type segment spans from highly specialized, customized systems to more standardized, disposable components.
- High-Frequency Ultrasonic Devices:These systems generate ultrasound waves typically between 0.8 and 3.5 MHz, focusing energy to thermally ablate target tissues deep within the body. Demand concentrates in specialized cancer treatment centers, driven by their precision in treating solid tumors like those in the liver and prostate.
- Portable Ablation Systems:These compact devices offer increased mobility and flexibility, suitable for various clinical environments including smaller clinics or mobile units. Their lower capital cost makes them accessible to a broader range of facilities.
- Robotic-Assisted Devices:Integrating ultrasonic ablation technology with robotic platforms enhances surgical precision and minimizes operator variability during complex procedures. These advanced systems are increasingly adopted in leading surgical centers for their ability to improve patient outcomes in intricate oncological cases.
- Disposable Handpieces:These single-use components ensure sterility and consistent performance, reducing the risk of cross-contamination and simplifying procedural setup for clinicians.
Leading the category by volume: High-Frequency Ultrasonic Devices. Growing fastest: Robotic-Assisted Devices.
Application:
The market's application landscape centers around specific therapeutic areas where non-invasive tissue ablation offers significant clinical advantages.
- Oncology Procedures:This segment includes treatments for uterine fibroids, prostate cancer, liver tumors, and other solid malignancies, representing the largest application area for HIFU systems. The rising incidence of these cancers in the United States, Germany, and Japan drives consistent demand.
- Cardiology Interventions:Focused ultrasound is exploring applications in cardiac arrhythmia ablation and other structural heart disease treatments, offering a non-invasive alternative to traditional catheter-based procedures. This area represents a high-growth segment due to unmet needs for less invasive cardiac therapies.
- Cosmetic Surgery:Ultrasonic ablation finds use in non-invasive fat reduction and skin tightening procedures, appealing to patients seeking aesthetic improvements without surgical incisions.
- Pain Management:Focused ultrasound can target nerves to alleviate chronic pain conditions, offering a drug-free alternative for patients with neuropathic or musculoskeletal pain.
Oncology procedures dominate the application landscape, while cardiology interventions are gaining significant traction.
End User:
End-user adoption patterns reflect varying infrastructure capabilities and patient access models within the healthcare system.
- Hospitals:These large medical facilities represent the primary end-user segment, possessing the necessary infrastructure, capital, and trained personnel for advanced ultrasonic ablation systems. Hospitals conduct a high volume of complex surgical and oncological procedures.
- Ambulatory Surgery Centers:ASCs are rapidly adopting HIFU systems for outpatient procedures, driven by cost-efficiency and patient preference for shorter hospital stays. This segment is expanding quickly for less complex interventions like uterine fibroid ablation.
- Research Institutions:These organizations utilize ultrasonic ablation systems for preclinical studies, technology development, and clinical trials to explore new applications and refine existing techniques.
- Medical Clinics:Smaller medical clinics leverage more compact or portable ablation systems for specific, less invasive procedures, often focusing on pain management or cosmetic applications.
Hospitals remain the primary end-user segment, with ambulatory surgery centers demonstrating accelerated expansion.
Delivery Mode:
The choice of delivery mode is often dictated by procedural complexity and patient recovery considerations.
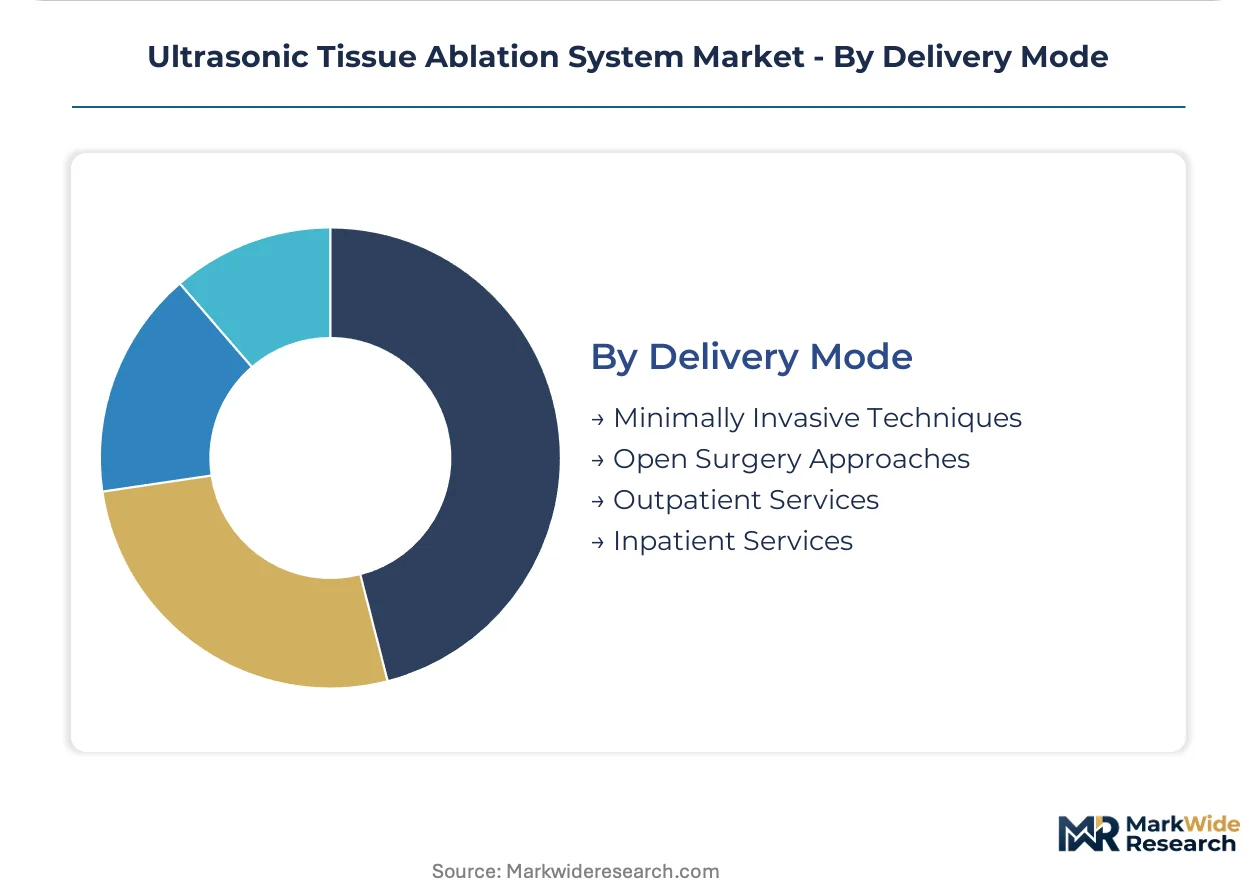
- Minimally Invasive Techniques:This mode involves precise energy delivery through small incisions or natural orifices, reducing patient trauma and recovery time. HIFU systems inherently align with this approach, making it the most preferred delivery method.
- Open Surgery Approaches:While less common for HIFU, some complex cases may combine ultrasonic ablation with traditional open surgical access for direct visualization or tissue manipulation.
- Outpatient Services:Procedures performed in an outpatient setting allow patients to return home the same day, enhancing convenience and reducing healthcare costs. Uterine fibroid ablation is a key example migrating to this service model.
- Inpatient Services:These services involve overnight stays in a hospital, typically reserved for more complex procedures requiring extensive monitoring or longer recovery periods.
Minimally invasive techniques are the preferred delivery approach, with outpatient services expanding rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of high-tech medical research zones, such as those fostering advanced device development, significantly drives the Ultrasonic Tissue Ablation System market. These specialized areas attract investment and talent, accelerating innovation in non-invasive surgical techniques. This dynamic is particularly evident across key global economies.
United States
United States demand for ultrasonic ablation systems stems from its high incidence of treatable cancers like prostate and uterine fibroids. The US FDA's stringent Premarket Approval (PMA) process ensures high device safety and efficacy standards. Major medical technology clusters in Boston and California's Bay Area foster significant R&D and clinical adoption for new ablation platforms.
Germany
German hospitals show strong demand for advanced HIFU systems, reflecting a preference for precision oncology and minimally invasive procedures. Compliance with Europe's Medical Device Regulation (MDR) is essential for market entry and product commercialization. The medical technology hub in Erlangen, Bavaria, actively develops next-generation ultrasonic transducers and integrates them into robotic systems.
Japan
Japanese specialized cancer centers consistently adopt ultrasonic ablation for liver tumors and uterine fibroids, driven by an aging population and focus on patient quality of life. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, emphasizing long-term clinical outcomes. Tokyo and Osaka serve as key centers for clinical trials and early adoption of advanced medical imaging integration.
China
China's expanding healthcare infrastructure and rising cancer rates generate significant opportunities for ultrasonic ablation systems. The National Medical Products Administration (NMPA) sets distinct requirements for device market entry, influencing local manufacturing strategies. Shanghai's medical device parks are becoming critical for both domestic innovation and international collaboration in HIFU technology development.
United Kingdom
United Kingdom healthcare providers are increasingly integrating HIFU technology for uterine fibroids and prostate cancer management, aligning with national minimally invasive surgery initiatives. Regulatory compliance under the UK's MHRA (Medicines and Healthcare products Regulatory Agency) is crucial for device manufacturers. London's biomedical campuses are centers for academic research into novel neurological applications of focused ultrasound.
Ultrasonic Tissue Ablation System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the ultrasonic tissue ablation system market. The market structure is moderately consolidated at the high-end, where integrated solution providers offer comprehensive platforms. Strategic archetypes include technology innovators focused on niche applications, diversified medical device conglomerates, and specialized component suppliers. Companies are primarily engaging in strategic partnerships to expand their technological capabilities and pursuing portfolio diversification to address broader clinical needs.
Integrated device manufacturers like Ethicon Inc. sustain their market position through extensive distribution networks within hospital systems. Companies specializing in advanced imaging integration, such as INSIGHTEC Ltd., differentiate through their focus on MR-guided focused ultrasound technology for neurological applications. Integra LifeSciences Corporation exemplifies a strategy of leveraging a broad surgical portfolio to bundle these systems with complementary instruments, enhancing their value proposition to healthcare providers.
| Leading Market Players |
|---|
| Ethicon Inc. |
| Johnson & Johnson |
| Integra LifeSciences Corporation |
| Misonix Inc. |
| INSIGHTEC Ltd. |
| Chongqing Haifu Medical Technology Co., Ltd. |
| Alpinion Medical Systems |
| Theraclion |
| Philips Healthcare |
| Others |
Cost & Logistics Intelligence
Specialized piezoelectric crystal material costs cascade through the ultrasonic tissue ablation supply chain, influencing the pricing tiers for advanced systems. This directly impacts the final acquisition cost for healthcare providers.
Pricing Analysis
Pricing for ultrasonic ablation systems often reflects lead-time-driven premiums for rapid delivery of advanced configurations. The dominant pricing structure is value-based, with significant differentiation based on system complexity and integrated features. Certification under US FDA or European MDR significantly enhances a system's market value. Pricing softness stems from increasing competition in the standard device segment. Ambulatory Surgery Centers exhibit higher price sensitivity compared to large university hospitals.
Supply Chain Analysis
Dual-sourcing requirements for critical components like high-frequency transducers are common among major device manufacturers. Geographic supply concentration for advanced piezoelectric materials centers on China and Japan, with specialized transducer fabrication in Germany. The market relies on complex robotic components sourced globally. Single-source vulnerability for specialized raw materials poses a structural risk. Distribution runs through a network of direct sales forces and specialized medical device distributors to end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic tissue ablation market is in a technology-transition phase, as advanced single-crystal piezoelectric materials displace traditional piezoceramics. This shift redefines device performance and application scope.
For Market Incumbents:Hedge against emerging competition from specialized technology firms by investing in next-generation transducer materials and AI integration. Focus R&D on expanding therapeutic indications, particularly in neurology, to counter the threat of new, niche-focused entrants. Leverage existing extensive distribution networks and strong hospital relationships to bundle advanced systems with comprehensive service packages.
For New Entrants and Emerging Players:Ambulatory Surgery Centers represent an underserved buyer archetype, seeking cost-effective and compact systems for outpatient procedures. Target this segment with tailored, portable ablation systems focusing on less complex interventions like uterine fibroid ablation. A go-to-market angle emphasizing ease of use and lower capital expenditure will facilitate rapid penetration.
For Investors and Strategic Acquirers:The window for entry favors specialist technology firms with proven MRgFUS platforms or advanced AI treatment planning capabilities. Long-term viability over the next 5-10 years hinges on securing intellectual property in novel neurological or cardiac applications. A signal to watch is the expansion of reimbursement coverage for non-oncological HIFU procedures.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven Treatment Planning | Enhances precision and reduces operator dependency in complex oncological procedures. |
| Expand MRgFUS for Neurological Disorders | Unlocks a high-growth segment beyond traditional oncology, addressing unmet patient needs. |
| Secure Supply of Single-Crystal Piezoelectric Materials | Ensures access to critical components for high-performance transducer fabrication. |
| Partner with Robotic Surgery Platform Providers | Integrates advanced ablation capabilities with established robotic systems for enhanced surgical precision. |
| Tailor Systems for Ambulatory Surgery Centers | Captures new demand from outpatient facilities seeking compact and cost-effective solutions. |
Research Approach
Document review covered US FDA filings, European MDR compliance reports, NMPA guidelines, and PMDA submissions, complemented by interviews with industry stakeholders. Primary research involved discussions with clinicians, hospital procurement managers, medical device R&D directors, and specialized distributors. This approach leveraged both bottom-up market sizing and top-down validation against published industry statistics.
The quantitative model generated detailed volume and value projections across the analysis window, segmented by product type, application, end-user, delivery mode, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical data trends and projected market dynamics. Key forecast inputs included cancer incidence rates and healthcare expenditure growth in target geographies.
Revisions become necessary when unforeseen regulatory shifts or significant material cost fluctuations materialize. Forecasts reflect assumptions regarding technological adoption rates and reimbursement policy stability. Deviation in either regulatory frameworks or material supply chains would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Global Surgical Booms Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
GCC Minimally Invasive Surgery Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Harmonic Scalpel Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Global Gauze Swabs Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Retractable Needles Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Breast Retractors Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Robotic Surgery Market