
 Cosmetic Surgery and Services Market | 2026-2036
Cosmetic Surgery and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Surgery and Services Market Outlook
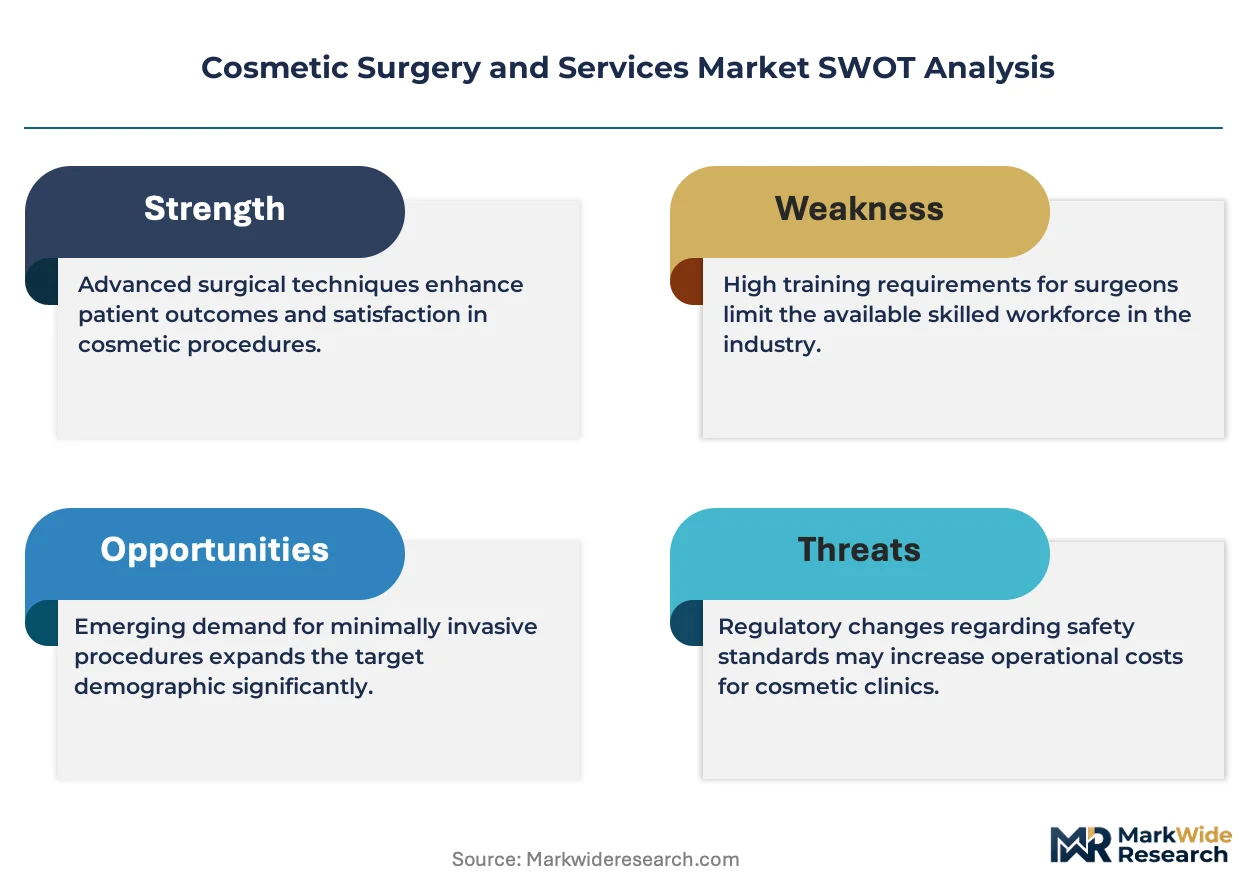
Board-certified plastic surgeon availability is rotating unevenly across metropolitan markets, creating access bottlenecks in secondary cities while oversupply emerges in established cosmetic surgery hubs. AbbVie Inc. leverages its Allergan Aesthetics portfolio to dominate the neuromodulator and filler segments with vertically integrated manufacturing. Johnson & Johnson sustains competitive positioning through its broad Ethicon surgical instrument and suture lines that anchor hospital-based cosmetic procedures. Galderma specializes in hyaluronic acid filler innovation and biostimulatory injectables, competing on clinical data depth rather than price.
Cosmetic surgery and services encompass surgical reconstruction and elective enhancement of physical appearance, employing techniques ranging from laser resurfacing at specific wavelengths to autologous fat grafting with defined viability thresholds, all aimed at altering aesthetic outcomes or restoring form after trauma. Non-surgical service types now capture the fastest margin expansion as clinics convert one-time surgical patients into recurring injectable clients with higher lifetime value. Laser technology leads procedural volume through fractional and ablative platforms, while thread-based minimally invasive lifts represent the emerging growth category as patients delay surgical intervention. Breast augmentation remains the mature surgical anchor, though rhinoplasty and liposuction sustain steadier demographic diversification across customer types.
The FDA governs device clearance and biologic approval for aesthetic technologies in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for implantable and active devices sold across European markets. South Korea's Ministry of Food and Drug Safety operates parallel pathways that accelerate domestic innovation in energy-based devices and novel filler formulations. Stakeholders must monitor how regulatory divergence between major markets fragments product launch timelines and forces dual-track clinical development strategies.
Market Dynamics
Young professionals in Seoul, New York, and São Paulo are compressing the age of first aesthetic intervention, converting cosmetic services from episodic reconstruction into preventive maintenance with recurring revenue profiles.
Growth Catalysts
- MFDS accelerated device pathways:South Korea's streamlined approval for energy-based technologies compresses time-to-market for novel laser platforms, attracting device manufacturers to Seoul's regulatory sandbox.
- Biostimulatory injectable chemistry:Poly-L-lactic acid and calcium hydroxylapatite formulations extend treatment intervals from months to years, lifting patient lifetime value and clinic utilization rates.
- Seoul metropolitan cluster density:Concentrated medical tourism infrastructure in Gangnam district normalizes cosmetic procedures through celebrity culture amplification and price-transparent package bundling.
Market Restraints
- Cross-linked hyaluronic acid supply concentration:Three fermentation-based manufacturers control pharmaceutical-grade raw material, exposing filler producers to input volatility and geographic supply disruption.
- FDA 510(k) clinical evidence escalation:The Center for Devices and Radiological Health demands larger safety datasets for novel dermal fillers, extending development timelines and capital requirements.
- Autologous fat grafting viability thresholds:Technical limitations in adipocyte survival rates during transfer constrain procedural consistency and patient satisfaction predictability.
Strategic Opportunities
- Brazil's middle-market expansion:São Paulo and Rio de Janeiro clinics report unmet demand for tiered service pricing between luxury surgical suites and unregulated beauty parlors.
- Telemedicine pre-consultation protocols:Remote assessment platforms reduce geographic friction for patients in secondary cities, expanding catchment areas for metropolitan surgical centers.
- EU MDR harmonization:Stricter clinical evidence requirements for implantable devices create competitive moats for manufacturers with pre-existing European trial infrastructure.
Industry Challenges
- Board-certified plastic surgeon maldistribution:Secondary cities face acute specialist shortages while established hubs experience oversupply, complicating national service network planning.
- Dual-track regulatory development:Divergent FDA and EU MDR evidence requirements force parallel clinical trials, fragmenting product launch timelines and R&D capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Surgery and Services Market |
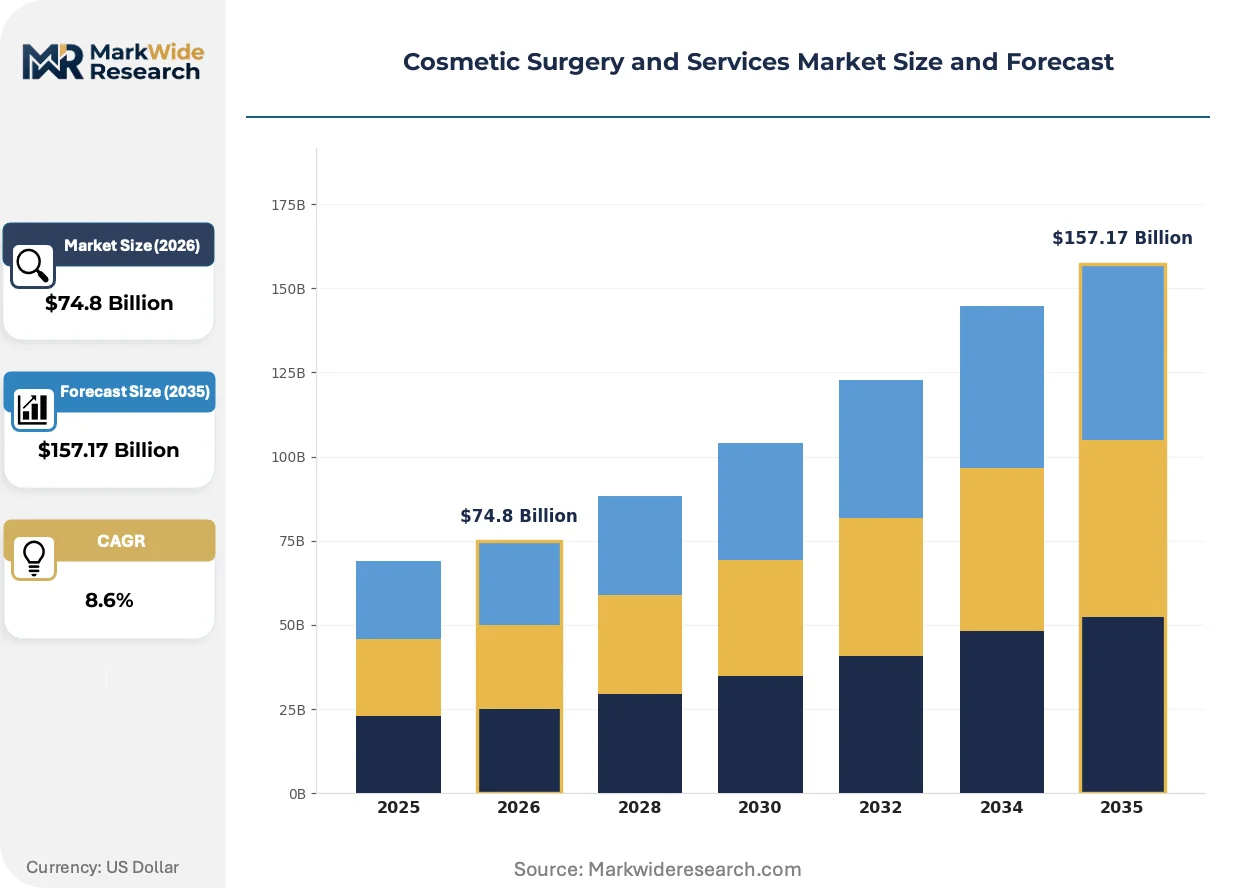
| Market Size in 2026 | $74.8 Billion |
| Market Size in 2035 | $157.17 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Rhinoplasty, Liposuction, Facelifts Service Type: Consultation, Surgical, Non-Surgical, Aftercare Customer Type: Males, Females, Professionals, Influencers Technology: Laser, Fillers, Injectables, Threads |
| Companies Covered | Bausch Health Companies Inc., Johnson & Johnson, AbbVie Inc., Galderma, Merz Pharma, Cutera, Cynosure, Sientra Inc., Candela Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Surgery and Services Market Strategic Shifts
Energy-based devices and injectable formulations are reshaping competitive boundaries between surgical and non-surgical service lines, with technology ownership determining margin capture.
Fractional laser technology is bifurcating the resurfacing market between ablative platforms for severe photodamage and non-ablative systems for maintenance protocols. Aesthetic chains in Los Angeles and Dubai are standardizing non-ablative treatments into membership programs. This split is compressing standalone surgical facelift volume while expanding recurring service revenue.
The EU Medical Device Regulation imposes stricter post-market surveillance and clinical follow-up requirements for active implantable devices. Manufacturers must maintain European Authorized Representatives and expanded technical documentation. Energy-based device categories face the steepest compliance cost escalation, favoring larger portfolios with amortized regulatory overhead.
Subscription-based aesthetic membership models are displacing per-procedure pricing in metropolitan markets. Young professionals in London and Toronto prefer fixed monthly fees covering injectable maintenance and preventive laser treatments. This shift is most visible in clinic chains with centralized CRM infrastructure and predictive scheduling algorithms.
Cosmetic Surgery and Services Market Segmentation
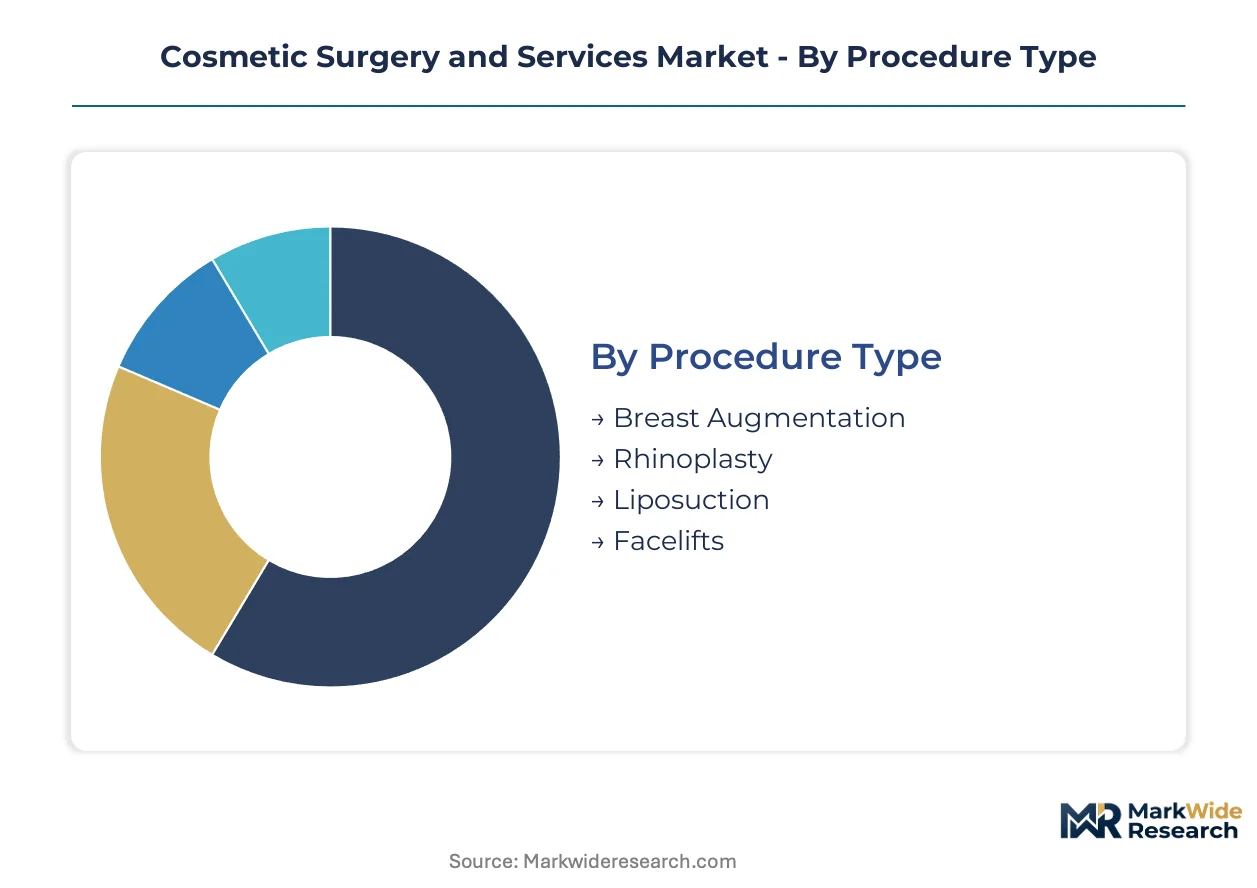
Segmentation in cosmetic surgery and services reveals how substitution pressures between surgical and non-surgical alternatives reshape revenue streams. Understanding these cross-category dynamics helps stakeholders allocate capital across technology platforms and service delivery models.
Procedure Type:
Substitution pressure runs strongest against invasive surgical options as energy-based devices and biostimulatory injectables extend treatment intervals and reduce recovery downtime.
- Breast Augmentation:Silicone and saline implant procedures employ cohesive gel formulations with defined shell integrity specifications. Demand concentrates in São Paulo and Dubai surgical suites where medical tourism packages bundle augmentation with recovery hospitality. Autologous fat transfer alternatives constrain pricing power in premium segments.
- Rhinoplasty:Open and closed surgical techniques modify nasal cartilage and bone structure with precise osteotomy protocols. Seoul's Gangnam district generates concentrated volume through celebrity-culture normalization and transparent package bundling. Non-surgical filler rhinoplasty captures younger first-time patients seeking reversible outcomes.
- Liposuction:Tumescent and ultrasound-assisted adipose removal techniques target localized fat deposits.
- Facelifts:SMAS plication and deep plane techniques address midface and neck laxity in aging demographics.
Breast augmentation retains volume leadership; thread-based minimally invasive alternatives hold the steepest expansion curve.
Service Type:
Cost tier stratification separates episodic high-value surgical events from recurring lower-ticket maintenance protocols that compound lifetime customer value.
- Surgical:Operating room-based procedures require anesthesia support, sterile field maintenance, and post-operative monitoring infrastructure. Metropolitan hubs in Los Angeles and London capture premium pricing through board-certified specialist concentration and facility accreditation tiering.
- Non-Surgical:Injectable and energy-based treatments deliver aesthetic outcomes without incision or sedation requirements. Young professionals in Toronto and New York compress first-intervention age through membership-based preventive maintenance programs.
- Consultation:Pre-procedure assessment and treatment planning services establish patient expectations and candidacy criteria.
- Aftercare:Follow-up monitoring, complication management, and revision protocols support outcome durability.
Non-surgical services are climbing the fastest as clinics convert one-time surgical patients into recurring injectable clients.
Customer Type:
Volume concentration varies sharply by demographic segment, with professional cohorts normalizing aesthetic intervention as career-maintenance expenditure rather than luxury consumption.
- Professionals:Lawyers, consultants, and finance sector employees in São Paulo and Seoul pursue preventive treatments during career acceleration phases. LinkedIn-era visual professionalization drives demand for subtle, undetectable outcomes that suggest natural maintenance rather than obvious intervention.
- Females:Historically dominant customer base spanning preventive and corrective treatment motivations across age cohorts.
- Males:Emerging segment concentrated in jawline definition, hair restoration, and body contouring procedures.
- Influencers:Content creators dependent on visual presentation for platform algorithm performance.
Females retain volume leadership; male customer acquisition represents the steepest expansion curve.
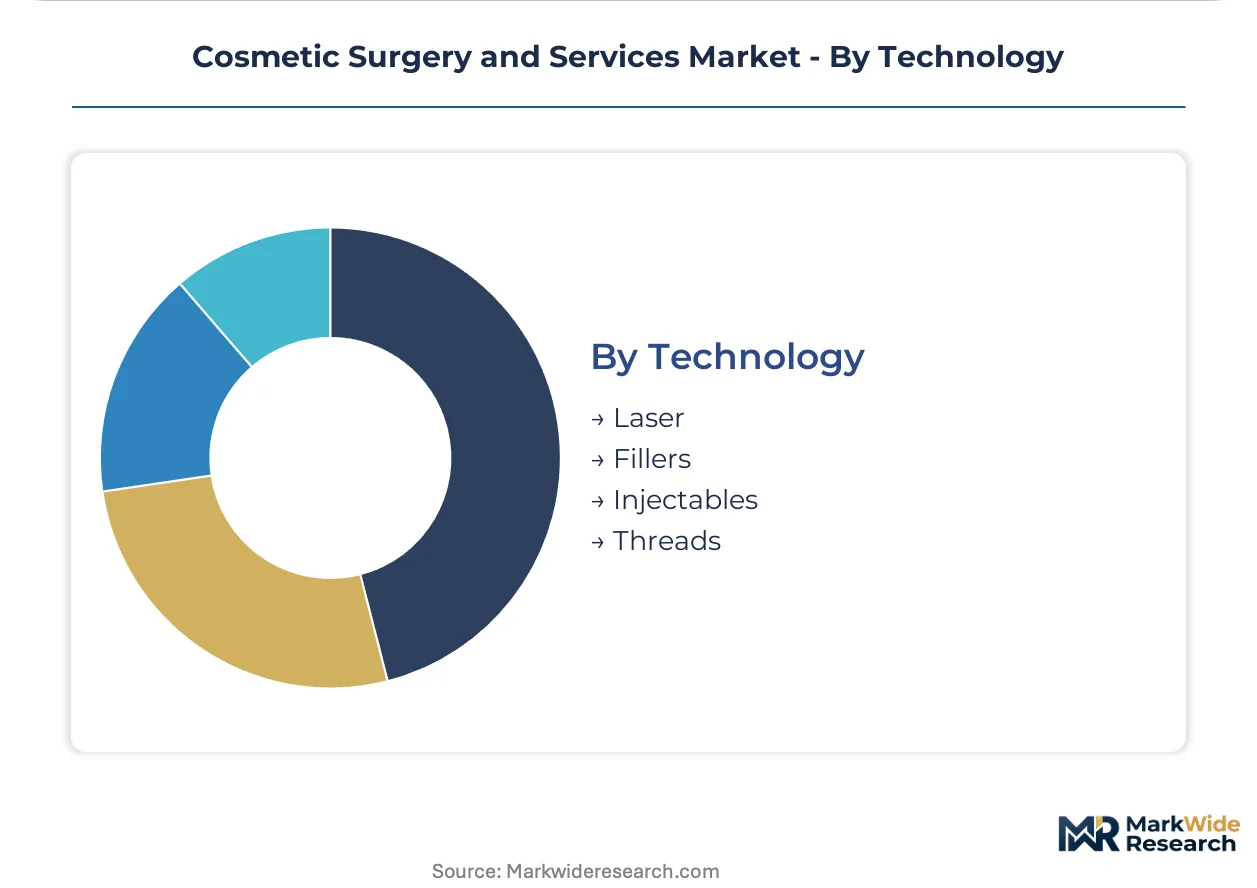
Technology:
Supply concentration in pharmaceutical-grade raw materials and device manufacturing creates asymmetric margin capture across technology categories.
- Injectables:Neuromodulator and filler formulations employ botulinum toxin serotypes and cross-linked hyaluronic acid with defined particle size distributions. FDA and EU MDR evidence requirements fragment development timelines, favoring established manufacturers with parallel trial infrastructure.
- Laser:Fractional and ablative platforms target photodamage, vascular lesions, and hair removal through selective photothermolysis. Seoul's MFDS accelerated pathways attract device manufacturers seeking compressed time-to-market for novel wavelength configurations.
- Fillers:Hyaluronic acid and biostimulatory formulations restore volume and stimulate neocollagenesis.
- Threads:Polydioxanone and polylactic acid sutures provide minimally invasive lifting through tissue anchoring and collagen induction.
Injectables retain volume leadership; thread-based technologies hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with South Korea normalizing preventive intervention at younger ages while the United States concentrates surgical volume in aging demographics and Brazil anchors medical tourism flows from across Latin America.
United States
Los Angeles and New York surgical suites capture premium pricing through board-certified specialist concentration and facility accreditation tiering. FDA 510(k) pathways for dermal fillers demand larger safety datasets, extending development timelines for novel formulations. Miami and Dallas aesthetic chains standardize membership-based injectable programs for young professionals seeking preventive maintenance.
South Korea
Seoul's Gangnam district generates concentrated procedural volume through celebrity-culture normalization and transparent package bundling for foreign patients. MFDS accelerated device pathways compress time-to-market for novel laser platforms, attracting manufacturers to Seoul's regulatory sandbox. Busan-Ulsan medical tourism corridors expand capacity for Chinese and Southeast Asian visitors seeking rhinoplasty and double-eyelid procedures.
Brazil
São Paulo and Rio de Janeiro clinics report unmet demand for tiered service pricing between luxury surgical suites and unregulated beauty parlors. ANVISA oversees device registration and biologic approval for aesthetic technologies, maintaining parallel pathways for imported and domestically manufactured products. Minas Gerais and Rio Grande do Sul secondary cities face acute board-certified plastic surgeon shortages while metropolitan hubs experience oversupply.
Germany
Berlin and Munich aesthetic practices serve cross-border patients from Switzerland and Austria seeking EU MDR-compliant implant procedures. EU Medical Device Regulation imposes stricter post-market surveillance requirements for active implantable devices, favoring larger portfolios with amortized regulatory overhead. Baden-Württemberg surgical instrument manufacturers supply precision tools for rhinoplasty and liposuction procedures across European markets.
United Arab Emirates
Dubai healthcare free zones attract South Korean and European clinic chains seeking tax-advantaged regional headquarters. MOHAP regulates medical advertising and facility licensing, requiring Arabic-language informed consent documentation for all procedures. Abu Dhabi and Dubai surgical centers bundle recovery hospitality services for medical tourists from Saudi Arabia, Kuwait, and Egypt.
Cosmetic Surgery and Services Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates controlling neuromodulator and filler supply through captive fermentation capacity while device manufacturers compete on wavelength innovation and treatment protocol differentiation. Three strategic archetypes dominate: diversified healthcare conglomerates with aesthetic divisions, pure-play dermatology specialists, and energy-based device manufacturers. Competitive moves center on M&A for technology access and geographic expansion into medical tourism corridors.
Within the integrated pharmaceutical tier, AbbVie Inc. and Johnson & Johnson occupy positions defined by vertically controlled manufacturing and hospital-based surgical instrument anchoring. Galderma exemplifies the pure-play dermatology specialist archetype, competing on clinical data depth rather than price. Among energy-based device manufacturers, Cutera and Cynosure represent technology-driven competitors seeking MFDS accelerated pathways in Seoul.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| Johnson & Johnson |
| AbbVie Inc. |
| Galderma |
| Merz Pharma |
| Cutera |
| Cynosure |
| Sientra Inc. |
| Candela Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day fermentation cycles for pharmaceutical-grade hyaluronic acid tie filler pricing power to bioreactor capacity in South Korea and Germany, concentrating margin capture among manufacturers with captive upstream production. Contract structures for cross-linked HA raw material split between multi-year offtake agreements with volume minimums and spot purchases exposed to commodity volatility, with Seoul-based device manufacturers leveraging MFDS accelerated pathways to compress time-to-market and offset input cost pressure.
Pricing Analysis
Project-based surgical contracts dominate high-ticket procedures while membership subscriptions capture recurring injectable revenue. Three-tier pricing structure across premium, standard, and economy levels separates board-certified surgeon suites from nurse-administered clinic chains and unregulated beauty parlors. Cost compression in the standard tier is intensifying because Brazilian and Southeast Asian clinics compete on package bundling. Price sensitivity concentrates in young professionals seeking preventive maintenance, while aging surgical patients demonstrate lower elasticity.
Supply Chain Analysis
Fermentation-based bioreactor capacity in South Korea, Germany, and the United States controls pharmaceutical-grade hyaluronic acid supply for dermal fillers. Device manufacturing draws from precision optics in Japan, laser resonators in Germany, and semiconductor components in Taiwan. Single-source vulnerability in cross-linked HA raw material exposes filler producers to geographic disruption. Distribution runs through hospital purchasing committees, aesthetic clinic chains, and direct-to-practitioner specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as subscription-based membership models convert episodic surgical patients into recurring service clients, with interoperability between CRM scheduling and predictive inventory systems determining clinic network scalability.
For Market Incumbents: Compound defensive positioning through backward integration into bioreactor capacity and certification investment in EU MDR compliance. Thread-based minimally invasive technologies threaten surgical facelift volume. Capacity addition in São Paulo and Dubai medical tourism corridors anchors geographic control. For New Entrants and Emerging Players: MFDS accelerated device pathways offer regulatory fast-track entry for novel laser platforms. Brazil's middle-market tier between luxury suites and unregulated parlors presents the most penetrable white space. Telemedicine pre-consultation protocols reduce geographic friction for secondary city patient acquisition. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue healthcare services play because injectable membership models compound lifetime customer value beyond one-time surgical events. Target acquisition archetypes include energy-based device manufacturers with Seoul regulatory sandbox access and clinic chains with centralized CRM infrastructure. Watch FDA 510(k) clinical evidence escalation as inflection indicator for R&D capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS Accelerated Device Pathway | Seoul's regulatory sandbox compresses time-to-market for novel laser wavelength configurations. |
| EU MDR Compliance Investment | Stricter clinical evidence requirements create competitive moats for implantable device portfolios. |
| Subscription Membership Model | Fixed monthly fees for injectable maintenance convert surgical patients into recurring revenue streams. |
| Backward Integration into Fermentation | Captive bioreactor capacity insulates filler producers from cross-linked HA supply volatility. |
| Telemedicine Pre-Consultation Platform | Remote assessment expands catchment areas for metropolitan surgical centers in secondary cities. |
Study Parameters
A standing panel of board-certified plastic surgeons, aesthetic clinic chain operators, biomedical device engineers, and GPO contracts managers provided ongoing calibration across primary interviews and secondary validation. FDA 510(k) filings, MFDS device registrations, ANVISA submissions, and hospital procurement databases anchored quantitative inputs. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include procedure type, service delivery model, customer demographic, and technology platform. CAGRs were derived from fitted growth curves incorporating regulatory approval timelines, medical tourism corridor expansion rates, and membership program adoption patterns.
Underlying assumptions cover MFDS pathway efficiency, EU MDR implementation timelines, and raw material supply stability, with deviation risk concentrated in FDA clinical evidence escalation and cross-linked HA fermentation capacity constraints. Practitioners should keep alternative scenarios live as regulatory divergence between major markets evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market