
 Harness-Level EMI and Shielding Component Systems Market | 2026-2036
Harness-Level EMI and Shielding Component Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Harness-Level EMI and Shielding Component Systems Market Insights
Platform licensing revenue is rewriting margin allocation across the value chain. TE Connectivity leverages its connector-shield integration expertise to capture premium positioning in high-frequency harness architectures. Aptiv anchors its competitive stance through R&D intensity focused on smart vehicle electrical distribution systems. Sumitomo Electric Industries dominates Asian supply corridors with manufacturing scale that spans conductive material production through finished cable assembly.
Harness-level EMI and shielding component systems encompass integrated electromagnetic interference suppression assemblies engineered into wire harnesses, typically incorporating conductive polymers rated for 150°C continuous operation and shielding effectiveness exceeding 60 dB across 30 MHz to 1 GHz spectra, serving to prevent signal degradation in densely packed electrical architectures. Metallic foil technology leads in automotive and aerospace implementations where weight-sensitive Faraday cage performance proves critical, while polymer composites represent the fastest-expanding technology category as OEMs pursue recyclable, halogen-free alternatives that maintain flexural durability through millions of deformation cycles. Cable shields command the largest product-type volume pool, though absorber sheets concentrate margin capture in military equipment and 5G infrastructure applications where broadband absorption above 18 GHz commands specification premiums.
FCC Part 15 emissions limits in the United States and ECE R10 regulations across Europe are elevating pre-compliance testing burdens, compelling harness suppliers to integrate shielding validation earlier in design cycles. Japan's METI administers JIS standards that govern conductive coating adhesion and salt-spray durability for underhood harness deployments. China's MIIT enforces GB/T electromagnetic compatibility mandates that increasingly reference shielding effectiveness metrics for new energy vehicle platforms. Stakeholders must monitor how regional certification divergence affects modular platform strategies and whether nanocoating technology maturation will consolidate technology tiers currently split between metallic and polymer-based shielding approaches.
Market Dynamics
High-voltage platform deployment across automotive OEMs is compressing shielding design cycles from 36 months to 18 months, forcing harness suppliers to front-load electromagnetic validation before chassis integration locks. This acceleration is restructuring supplier-OEM technical collaboration models.
Growth Catalysts
- ECE R10 tightening:Europe's electromagnetic compatibility thresholds now mandate pre-certification at the harness subsystem level, pulling shielding specification earlier into vehicle architecture design.
- 800V powertrain proliferation:Electric vehicle platforms above 600V nominal require braided shielding with 90 dB effectiveness to prevent inverter-induced interference in adjacent signal lines.
- Stuttgart-Munich corridor concentration:Germany's tier-1 harness engineering density creates knowledge spillover effects that accelerate shielding material qualification timelines.
Market Restraints
- Copper price volatility:Braided shielding architectures depend on high-purity copper wire, with spot price swings above 20% compressing quoted margin buffers on fixed-price OEM contracts.
- Single-source polymer dependency:Fluoropolymer jacketing rated for 150°C continuous operation concentrates among three Japanese chemical suppliers, creating input bottlenecks during automotive ramp cycles.
- Metallic-to-polymer performance gap:Conductive polymer composites still fall 15-20 dB short of tin-plated copper braid at frequencies above 500 MHz, limiting substitution in aerospace applications.
Strategic Opportunities
- India automotive electrification:PLI scheme incentives for domestic EV component manufacturing are drawing harness suppliers to Chennai and Pune industrial corridors for localized shielded cable assembly.
- 5G infrastructure absorber sheets:Millimeter-wave base station deployments above 28 GHz specify multilayer absorber laminates that command specification premiums unavailable in automotive volume contracts.
- Halogen-free mandate convergence:REACH restrictions on brominated flame retardants and Japan's METI green procurement guidelines are aligning to create unified polymer formulation targets across three continents.
Industry Challenges
- Electromagnetic simulation talent scarcity:Full-wave 3D modeling of harness-level crosstalk requires specialized CST or HFSS expertise that automotive wiring suppliers struggle to recruit against semiconductor and aerospace employers.
- Dual certification timeline compression:Simaneous FCC Part 15 and ECE R10 validation creates parallel testing queues that extend product release schedules by 4-6 months.
- Legacy 12V integration complexity:Mixed-voltage architectures force shielding designers to isolate high-voltage PWM noise from unshielded legacy body electronics without complete harness redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harness-Level EMI and Shielding Component Systems Market |
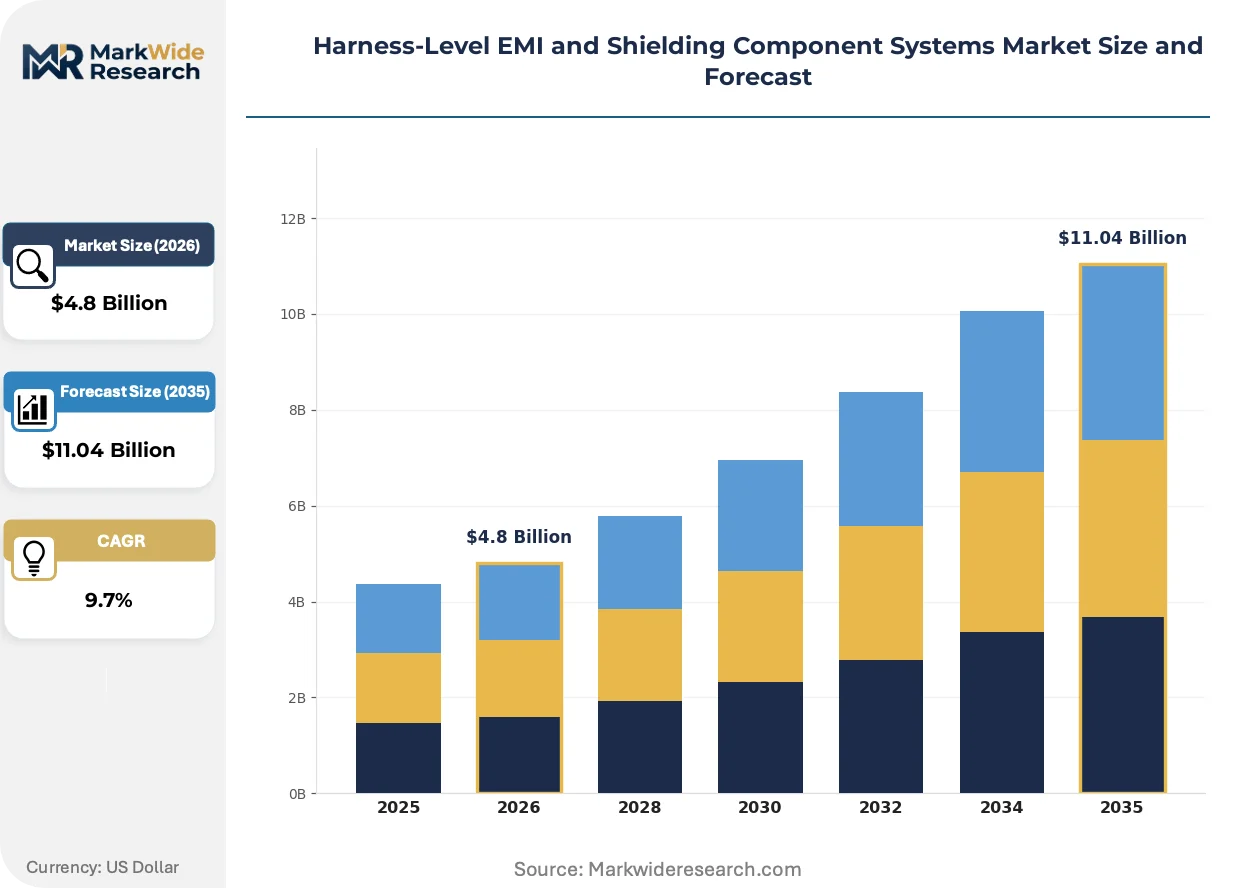
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Shields, Conductive Tapes, Ferrite Beads, Absorber Sheets, EMI Gaskets Technology: Metallic Foil, Conductive Coatings, Magnetic Materials, Polymer Composites, Nanocoatings Application: Consumer Electronics, Aerospace Systems, Industrial Controls, Data Centers, Military Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators, Contract Manufacturers |
| Companies Covered | TE Connectivity, Aptiv, Rosenberger Group, Amphenol, Yazaki Corporation, Sumitomo Electric Industries, LEONI, Coroplast Fritz Müller, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harness-Level EMI and Shielding Component Systems Market Trends and Innovations
Material science breakthroughs are collapsing the traditional tradeoff between shielding performance and manufacturing flexibility, while regulatory harmonization pressures are standardizing test protocols across previously fragmented national regimes.
Aluminum-polymer hybrid tapes are collapsing the cost-performance frontier for automotive high-voltage harnesses. Tier-1 suppliers in Germany and Japan are adopting these laminates at production scale for 400V platform variants. The technology is collapsing the historic 40% cost premium of metallic shielding solutions, enabling OEMs to specify full-harness coverage rather than selective segment shielding.
China's MIIT has issued draft amendments to GB/T electromagnetic compatibility standards that explicitly incorporate shielding effectiveness metrics for new energy vehicle wiring assemblies. The regulation compels domestic harness manufacturers to invest in anechoic chamber testing capacity. European suppliers with existing ECE R10 certification infrastructure are capturing technical advisory roles with Chinese OEMs navigating the transition.
Automotive electrical distribution engineers are consolidating supplier relationships from 12-15 shielding component vendors to 3-4 integrated system partners. This consolidation eliminates redundant qualification cycles and transfers design responsibility upstream to harness manufacturers with captive electromagnetic simulation capabilities. The pattern is most pronounced in Germany, where BMW and Mercedes-Benz powertrain divisions have issued single-source RFQ structures for 800V platform harnesses.
Harness-Level EMI and Shielding Component Systems Market Segmentation
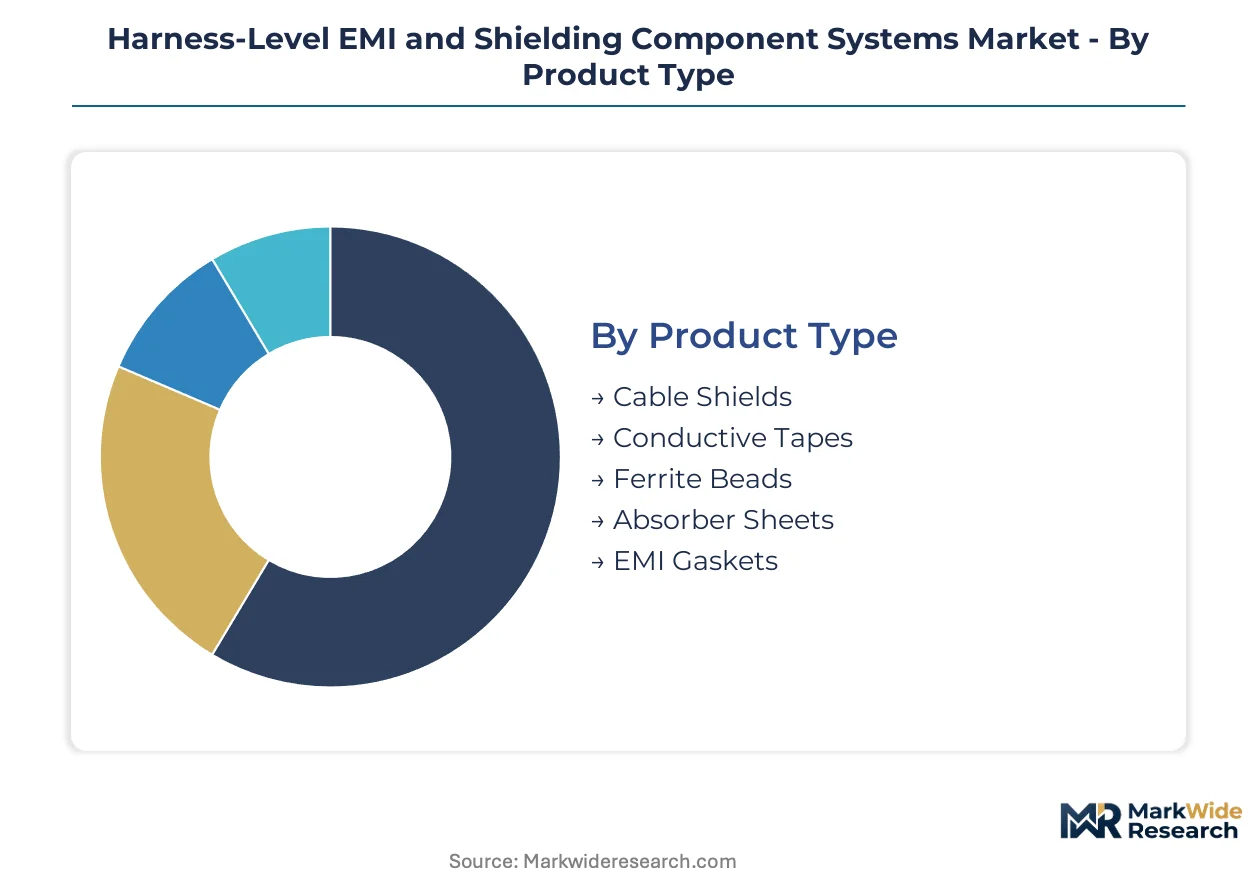
Segmentation in the harness-level EMI and shielding market reveals divergent engineering cycles across product categories. Cable shields and conductive tapes refresh on 18-24 month automotive platform cadences, while absorber sheets and nanocoatings follow 5-7 year aerospace qualification timelines. Understanding these temporal patterns guides supplier capacity planning and R&D allocation.
Product Type:
Cable shields turn inventory fastest due to automotive volume contracts, while absorber sheets sit in extended military qualification pipelines.
- Cable Shields:Braided tin-plated copper or aluminum-polymer laminates wrapping conductor bundles, specified for 60-90 dB effectiveness across 30 MHz to 1 GHz. Demand clusters in Germany's Stuttgart-Munich automotive corridor where BMW and Mercedes-Benz 800V platforms require full-harness coverage. Copper price volatility above 20% spot swings compresses quoted margins on fixed-price OEM contracts.
- Absorber Sheets:Multilayer ferrite or carbon-based laminates engineered for broadband absorption above 18 GHz. Military equipment and 5G infrastructure deployments in South Korea and Japan command specification premiums unavailable in automotive volume contracts. Millimeter-wave base station specifications above 28 GHz drive formulation complexity.
- Conductive Tapes:Aluminum-polymer hybrid laminates collapsing the 40% historic cost premium of metallic shielding for 400V automotive platforms.
- Ferrite Beads:Cylindrical ceramic components suppressing high-frequency noise on individual signal lines in consumer electronics and industrial controls.
- EMI Gaskets:Elastomeric seals with conductive fillers maintaining enclosure shielding integrity across mating surfaces in data center and aerospace applications.
Cable shields anchor the volume base while absorber sheets gain share at the steepest rate.
Technology:
Cost tiers separate mature metallic solutions from emerging polymer and nanocoating alternatives seeking aerospace certification.
- Metallic Foil:Copper or aluminum tapes providing weight-sensitive Faraday cage performance for aerospace wire harnesses. Boeing and Airbus specifications in the United States and France maintain tin-plating requirements that resist salt-spray degradation under FAA and EASA airworthiness mandates.
- Polymer Composites:Halogen-free conductive formulations rated for 150°C continuous operation and millions of flexural cycles. REACH restrictions on brominated flame retardants and Japan's METI green procurement guidelines align formulation targets across Europe and Asia.
- Conductive Coatings:Silver or nickel-based sprays applied to thermoplastic substrates, concentrated in consumer electronics and industrial control enclosures.
- Magnetic Materials:Ferrite and nanocrystalline alloys absorbing electromagnetic energy through hysteresis losses in military and telecommunications applications.
- Nanocoatings:Ultra-thin carbon nanotube or graphene layers promising to bridge the 15-20 dB performance gap versus copper braid above 500 MHz.
Metallic foil dominates aerospace value capture while polymer composites expand most quickly across automotive platforms.
Application:
Customer procurement patterns split between high-volume automotive contracts and low-volume, high-specification aerospace and military programs.
- Aerospace Systems:Shielded harnesses for avionics, flight control, and in-flight entertainment systems requiring FAA and EASA certification. Weight constraints favor aluminum-polymer hybrid tapes over traditional copper braid.
- Military Equipment:Tempest-rated and MIL-STD-461 compliant assemblies with broadband absorption specifications. Extended qualification timelines and sole-source dependencies characterize procurement.
- Consumer Electronics:Compact ferrite beads and conductive gaskets in smartphones, laptops, and wearable devices with 12-18 month design cycles.
- Data Centers:High-density cable shields and EMI gaskets managing crosstalk in hyperscale server and switch installations.
- Industrial Controls:Robust shielding for factory automation, robotics, and process control systems in electrically noisy manufacturing environments.
Aerospace systems concentrate margin per unit while data centers drive volume scaling fastest.
End User:
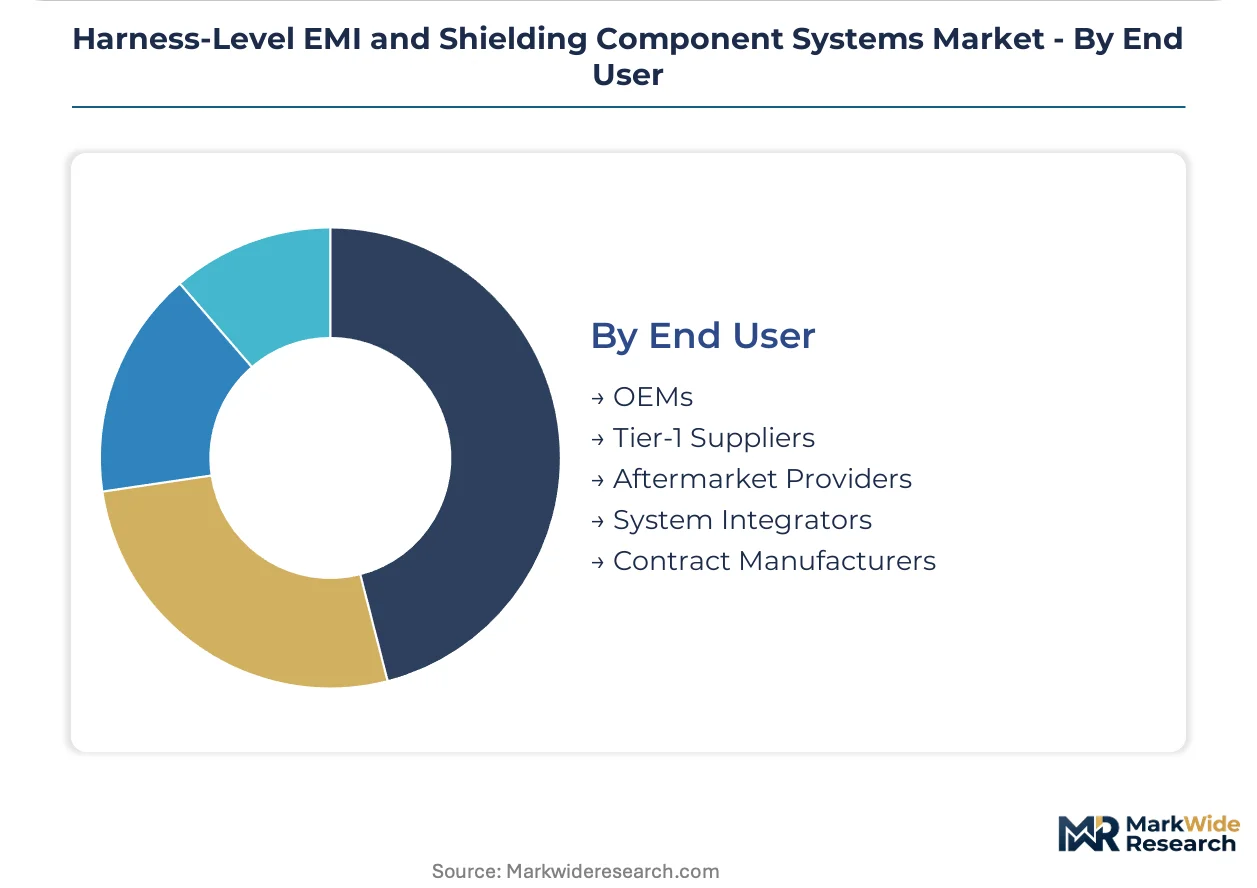
Supply chain position determines technical collaboration depth, with OEMs and tier-1 suppliers integrating shielding design earlier in vehicle architecture cycles.
- OEMs:Automotive and aerospace original equipment manufacturers specifying harness-level shielding requirements and validating ECE R10 or FAA compliance. BMW and Mercedes-Benz powertrain divisions in Germany have consolidated to 3-4 integrated system partners from 12-15 vendors.
- Tier-1 Suppliers:Harness manufacturers with captive electromagnetic simulation capabilities assuming design responsibility upstream. TE Connectivity and Aptiv leverage connector-shield integration expertise and R&D intensity in smart vehicle electrical distribution.
- System Integrators:Specialized firms assembling shielded harnesses for military, aerospace, and industrial applications with custom specifications.
- Contract Manufacturers:Volume producers executing OEM and tier-1 designs with limited specification authority.
- Aftermarket Providers:Distributors and service shops supplying replacement shielded cables and repair components for legacy vehicle and equipment fleets.
Tier-1 suppliers anchor the value chain's technical center while OEMs consolidate procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes shielded harness architectures as integrated system solutions for 800V automotive platforms, while China deploys comparable materials as discrete component inputs for domestic EV supply chains still consolidating design authority.
United States
FCC Part 15 emissions enforcement is tightening pre-certification testing for automotive wiring assemblies bound for Detroit's electric truck programs. The FAA maintains tin-plating requirements for Boeing and Airbus harness specifications that resist salt-spray degradation. Dallas-Fort Worth aerospace clusters concentrate system integrators serving defense and commercial aviation shielding contracts.
Germany
BMW and Mercedes-Benz powertrain divisions specify full-harness coverage for 800V platforms rather than selective segment shielding. ECE R10 mandates pre-certification at the harness subsystem level, pulling shielding specification earlier into vehicle architecture design. Stuttgart-Munich corridor tier-1 engineering density accelerates shielding material qualification timelines through knowledge spillover effects.
China
MIIT draft amendments to GB/T standards explicitly incorporate shielding effectiveness metrics for new energy vehicle wiring assemblies. Domestic harness manufacturers are investing in anechoic chamber testing capacity to meet compliance deadlines. Yangtze River Delta automotive supplier parks near Shanghai concentrate aluminum-polymer hybrid tape production for 400V platform variants.
Japan
METI green procurement guidelines align with REACH restrictions to create unified halogen-free polymer formulation targets. JIS standards govern conductive coating adhesion and salt-spray durability for underhood harness deployments. Nagoya industrial corridor manufacturers supply fluoropolymer jacketing rated for 150°C continuous operation to global automotive OEMs.
India
PLI scheme incentives for domestic EV component manufacturing are drawing harness suppliers to Chennai and Pune industrial corridors. BIS electromagnetic compatibility standards are converging toward ECE R10 test protocols for automotive wiring assemblies. Tamil Nadu supplier parks are localizing shielded cable assembly capacity for export to Southeast Asian EV programs.
Harness-Level EMI and Shielding Component Systems Market Competitive Landscape
Capability concentration sits with tier-1 harness manufacturers possessing captive electromagnetic simulation infrastructure; scale advantage sits with diversified component suppliers spanning conductive material production through finished cable assembly. The vendor base stratifies across three tiers: integrated system partners consolidated from 12-15 vendors down to 3-4 per OEM program; specialized shielding component suppliers with deep material science expertise; and contract manufacturers executing designs with limited specification authority. Dominant competitive moves include strategic consolidation of supplier relationships by automotive OEMs and upstream transfer of design responsibility to harness manufacturers with in-house validation capabilities.
Among Japan-based diversified electrical manufacturers, Sumitomo Electric Industries exemplifies the scale-driven archetype spanning conductive material production through finished assembly. TE Connectivity and Aptiv occupy positions within the integrated system partner tier, anchoring competitive positioning through connector-shield integration expertise and R&D intensity in smart vehicle electrical distribution architectures. These three companies represent the convergence of electromagnetic simulation capabilities with manufacturing scale that OEM consolidation strategies increasingly favor.
| Leading Market Players |
|---|
| TE Connectivity |
| Aptiv |
| Rosenberger Group |
| Amphenol |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| LEONI |
| Coroplast Fritz Müller |
| Molex |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into shielding component landed costs, compressing margin buffers for European harness manufacturers while amplifying price differentiation between integrated system partners and discrete component suppliers. Copper spot swings above 20% and fluoropolymer supply tightness from Nagoya chemical producers concentrate pricing power upstream, forcing tier-1 harness manufacturers to absorb input volatility through long-term OEM contracts.
Pricing Analysis
Long-term offtake agreements dominate automotive volume contracts, locking shielding specifications 18-24 months ahead of platform launch while spot purchasing persists for aerospace qualification batches and military Tempest-rated assemblies. Price differentiation separates ECE R10 pre-certified integrated harness systems from uncertified discrete components, with certification tier and electromagnetic simulation capability commanding premium positioning. Cost compression in 400V platform aluminum-polymer hybrid tapes intensifies as Chinese domestic suppliers scale Yangtze River Delta production. Contract manufacturers exhibit highest price sensitivity due to fixed-margin execution models, while OEM powertrain divisions prioritize technical compliance over unit cost in 800V architectures.
Supply Chain Analysis
Tariff exposure between Japan and Germany dominates supply chain risk planning for fluoropolymer jacketing rated to 150°C continuous operation, with METI green procurement guidelines and REACH restrictions creating formulation compliance complexity. Raw material sourcing concentrates in Japan for conductive polymer precursors, Germany for precision copper wire drawing, and China for aluminum-polymer laminate substrate production. Single-source dependency on three Nagoya chemical suppliers for high-temperature jacketing creates input bottlenecks during automotive ramp cycles. Distribution runs through Stuttgart-Munich tier-1 engineering clusters for European OEM programs, with Yangtze River Delta supplier parks serving Chinese domestic EV platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The harness-level EMI and shielding market is entering a cyclical recovery phase as automotive OEMs accelerate 800V platform deployment following ECE R10 regulatory tightening, with shielding specification pull-forward creating demand visibility through the projection horizon.
For Market Incumbents: Harden electromagnetic simulation capabilities against semiconductor and aerospace employer competition for CST and HFSS talent, while consolidating supplier relationships from 12-15 vendors to 3-4 integrated partners per OEM program. Backward integration into conductive polymer formulation insulates against Japanese chemical supplier bottlenecks during automotive ramp cycles. Certification investment in simultaneous FCC Part 15 and ECE R10 validation infrastructure compresses dual-timeline release schedules by 4-6 months.
For New Entrants and Emerging Players: Build out anechoic chamber testing capacity to capture technical advisory roles with Chinese OEMs navigating MIIT GB/T shielding effectiveness amendments, as European suppliers with existing certification infrastructure currently dominate this transition support. India's PLI scheme incentives for Chennai and Pune industrial corridors offer the most penetrable geography for localized shielded cable assembly. Go-to-market positioning as electromagnetic compliance consultants rather than discrete component vendors accelerates OEM relationship formation.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified Japanese electrical manufacturers with captive conductive material production but underutilized harness assembly capacity. The 5-10 year viability window favors acquisition of tier-1 harness manufacturers possessing in-house electromagnetic validation capabilities, as OEM consolidation strategies increasingly transfer design responsibility upstream. Monitor nanocoating technology maturation as inflection indicator for potential consolidation between metallic and polymer-based shielding technology tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Anechoic Chamber Testing Capacity Buildout | MIIT GB/T compliance deadlines compel domestic Chinese harness manufacturers to invest in validation infrastructure. |
| Long-term Fluoropolymer Supply Agreement | Japanese chemical suppliers lock in automotive OEM volume commitments ahead of EV platform ramp cycles. |
| Connector-Shield Integration Partnership | TE Connectivity and Aptiv leverage architectural expertise to capture 800V platform RFQ consolidation. |
| Aluminum-Polymer Hybrid Tape Scale-Up | Yangtze River Delta production expansion collapses historic metallic shielding cost premiums for 400V variants. |
| Electromagnetic Simulation Talent Acquisition | Automotive wiring suppliers compete against semiconductor employers for scarce CST and HFSS expertise. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tier-1 harness procurement directors, OEM platform electromagnetic compatibility engineers, conductive polymer R&D leads, and anechoic chamber testing facility managers. Secondary validation drew from ECE R10 regulatory filings, MIIT GB/T draft standard publications, customs trade data for copper wire and fluoropolymer imports, and SEC disclosures from diversified electrical manufacturers. Bottom-up segment sizing across cable shields, absorber sheets, and conductive tapes was triangulated against top-down automotive production forecasts and 800V platform deployment trajectories.
Calibration against historical automotive platform cadences and aerospace qualification timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, shielding technology tier, application vertical, and end-user supply chain position. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends reflecting material substitution dynamics. Industry-specific forecast inputs incorporated copper price volatility assumptions and ECE R10 pre-certification adoption curves.
Practitioners should monitor copper spot price movements, Japanese fluoropolymer supplier capacity announcements, and nanocoating technology performance validation for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Latin America RFID Tags Market
RF Components
Power Amplifier Market
RF Components
Phase Shifters Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
RF Semiconductor Market
RF Components
Americas Small Signal Transistor Market
RF Components
RF Acoustic Wave Filters Market
RF Components
China Small Signal Transistor Market
RF Components
5G Gain Block Amplifier Market
RF Components
Wi-Fi Module Market
RF Components
Digital Radio Frequency Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
Global RF Transceiver Market
RF Components
Coaxial Connectors (RF) Market
RF Components
Multilayer Coupled Inductor Market
RF Components
FBAR Devices Market