
 Coaxial Coupler Market | 2026-2036
Coaxial Coupler Market Size, Share, and Industry Trends Forecast 2026-2036
Coaxial Coupler Market Outlook
RF engineering talent scarcity is rotating toward Asia-Pacific manufacturing hubs as Western defense budgets expand. Amphenol Corporation leverages in-house ceramic substrate fabrication to sustain margins on high-frequency precision lines. TE Connectivity anchors North American aerospace procurement through AS9100-certified facilities in California and Texas. Hirose Electric competes on miniaturized board-level couplers for satellite payload integration.
A coaxial coupler is a passive RF component that samples a defined fraction of electromagnetic power flowing through a transmission line, typically operating from DC to 67 GHz with impedance matching at 50 or 75 ohms. Directional couplers serve as the workhorse for signal distribution networks, while precision couplers command premium positioning in calibration laboratories and satellite test ranges where amplitude accuracy drives system validation.
FCC Part 15 emissions rules and EU RoHS substance restrictions shape material selection and plating chemistry across export-oriented supply chains. Military procurement through MIL-STD-348 and the EU Defense Fund's RF component sourcing criteria tighten traceability requirements on coaxial assemblies. Stakeholders must monitor how ITAR reform discussions and REACH candidate list expansions recast supplier qualification timelines for cross-border programs.
Market Dynamics
Defense procurement automation and China's MIIT spectrum reallocation are compressing lead times while fragmenting supplier qualification pathways across Western and Asian supply chains. The market structure pivots on whether ceramic substrate fabrication stays captive or migrates to contract foundries.
Growth Catalysts
- Defense automation protocols:Automated RF testing systems in US and German satellite ground stations reduce dependency on scarce calibration engineers. Procurement velocity accelerates for precision couplers meeting MIL-STD-348.
- MIIT 5G spectrum mandates:China's Ministry of Industry and Information Technology reallocation drives domestic base station deployment, pulling demand for sub-6 GHz directional couplers through state-owned equipment vendors.
- Satellite ground station densification:Low-earth orbit constellation operators in Japan and Germany expand calibration laboratory networks, prioritizing amplitude-accurate precision couplers for signal validation chains.
Market Restraints
- Silver-palladium plating cost volatility:Precious metal price swings in electroplating chemistry compress margins on high-frequency precision lines, forcing pass-through clauses in aerospace contracts.
- Ceramic substrate supply concentration:Alumina and aluminum nitride substrate fabrication clusters in Japanese and Chinese facilities create single-source vulnerability for US and European coupler assemblers.
- ITAR qualification timeline extension:US State Department export control reform discussions stretch supplier onboarding for cross-border defense programs, freezing procurement decisions.
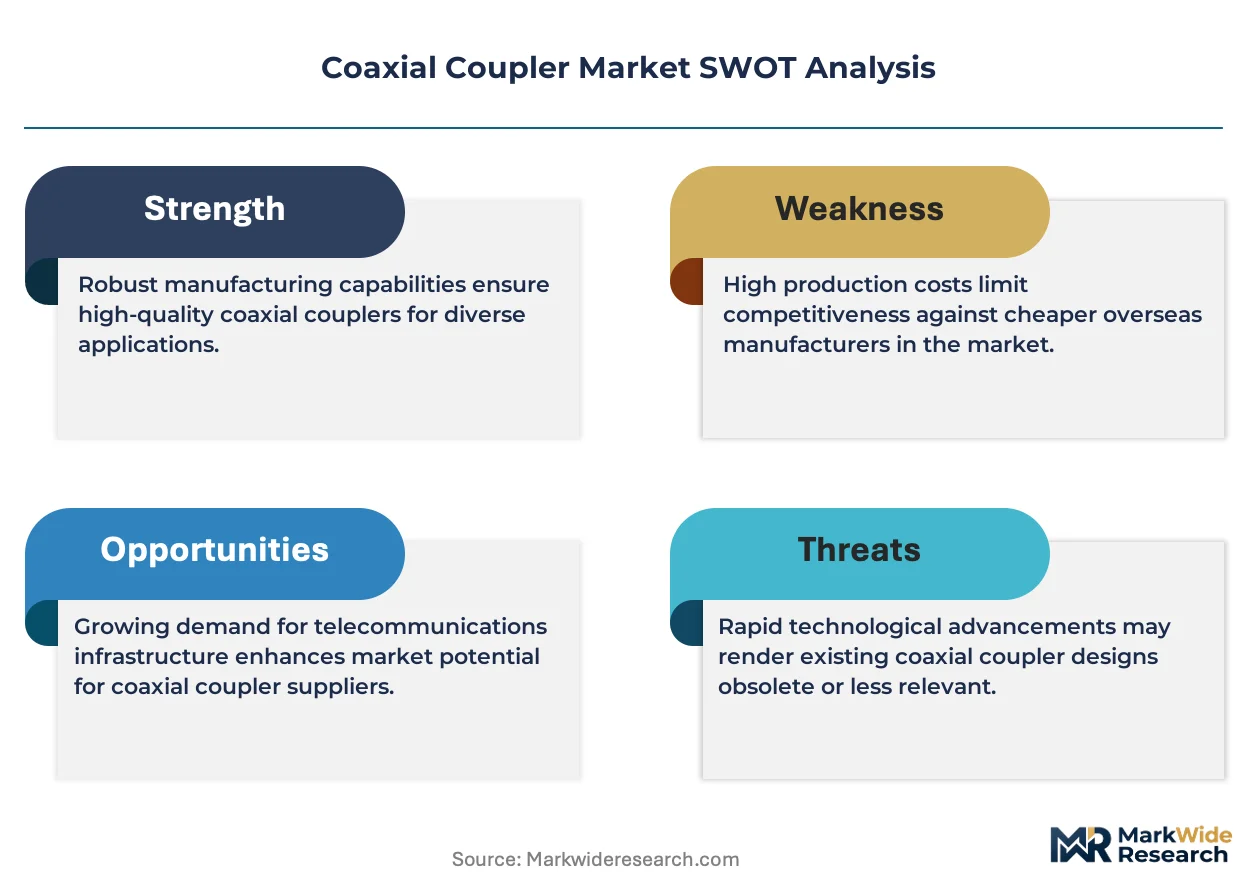
Strategic Opportunities
- India's defense indigenization:The country's PLI scheme for telecom and defense electronics creates opening for coupler manufacturers establishing local assembly to bypass import duties on finished RF components.
- GaN-SiC convergence:Gallium nitride power amplifiers paired with silicon carbide substrates in radar transmitters demand broadband directional couplers handling higher thermal and power density.
- EU Defense Fund RF sourcing criteria:The bloc's traceability and security-of-supply mandates favor European-certified suppliers for satellite and electronic warfare programs, creating premium positioning for AS9100-certified facilities.
Industry Challenges
- RF calibration engineer scarcity:North American and European defense contractors face 18-24 month hiring cycles for amplitude calibration specialists, forcing reliance on automated test equipment with degraded fault diagnosis capability.
- REACH candidate list expansion:ECHA additions to restricted substance lists trigger reformulation of plating baths and dielectric materials, requiring requalification of existing product lines.
- Legacy 75-ohm infrastructure integration:Broadcast and cable operators in Japan and Germany maintain substantial 75-ohm plant, complicating 50-ohm coupler standardization in converged network upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coaxial Coupler Market |
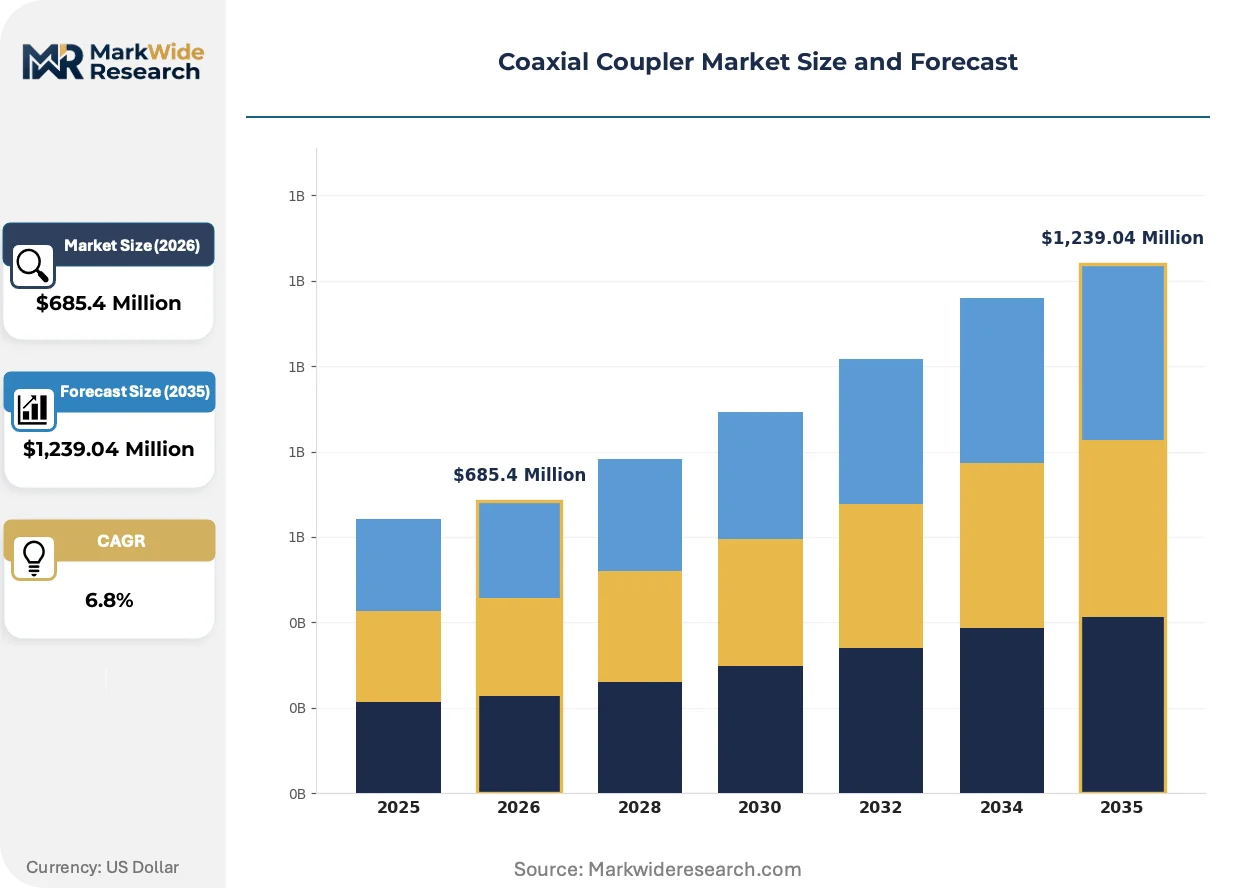
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Couplers, High-Power Couplers, Precision Couplers, Directional Couplers Technology: Passive Devices, Active Devices, Optical Devices, RF Devices End User: Telecommunications, Broadcasting, Military, Aerospace Application: Signal Distribution, Measurement, Modulation, Testing |
| Companies Covered | Amphenol Corporation, TE Connectivity, Molex, Radiall, Rosenberger, Hirose Electric, HUBER+SUHNER, Pasternack Enterprises, Japan Aviation Electronics Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coaxial Coupler Market Strategic Shifts
Ceramic substrate technology and automated calibration workflows are splitting the market between premium precision lines and commoditized broadband couplers. Regulatory substance restrictions and defense procurement reforms are rewriting material selection and supplier qualification protocols simultaneously.
Micromachined air-suspended stripline couplers is bifurcating the precision segment from traditional coaxial geometries. Satellite payload integrators in Japan and Germany adopt these structures for mass and volume reduction in LEO constellations. The technology is compressing board-level coupler footprints below 3 mm while forcing legacy coaxial suppliers into specialty high-power niches.
EU RoHS substance restrictions and REACH candidate list expansions are mandating elimination of hexavalent chromium and cadmium from plating chemistry. Electroless nickel-immersion gold finishes displace traditional silver-palladium in export-oriented supply chains. German and French aerospace suppliers absorb the highest compliance costs, accelerating qualification of alternative barrier layers.
Buyer consolidation among LEO satellite operators compresses vendor lists and extends contract durations for calibration-grade couplers. SpaceX and Amazon Kuiper procurement teams now mandate five-year price locks and dedicated capacity reservations. This concentration is visible most acutely in California and Texas test range facilities, where sole-source negotiations displace competitive bidding.
Coaxial Coupler Market Segmentation
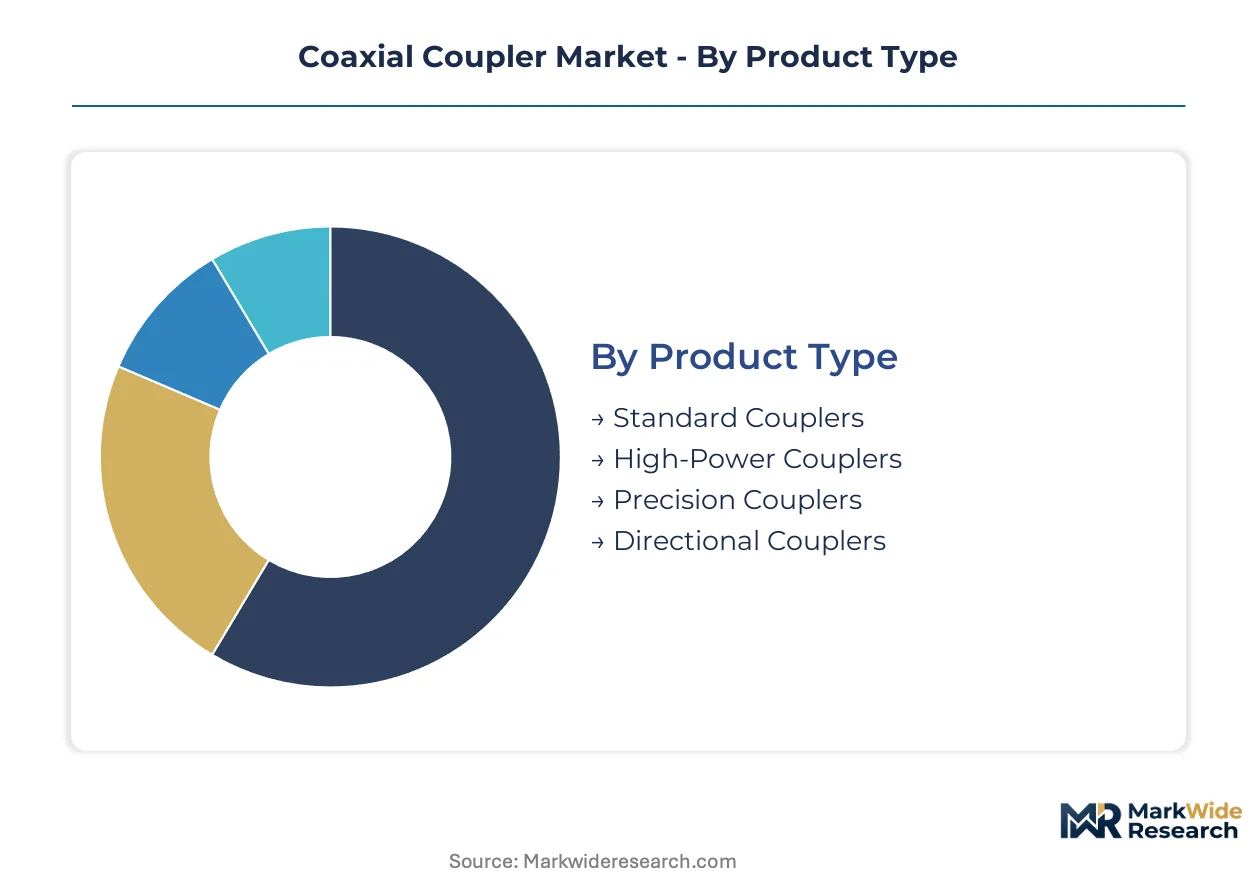
Coaxial coupler segmentation reflects divergent technical requirements across defense, telecom, and aerospace procurement channels. Substitution pressures from planar and stripline technologies reshape competitive boundaries within each category.
Product Type:
Micromachined stripline alternatives threaten standard coaxial geometries most acutely in satellite payload applications where mass reduction dominates.
- Precision Couplers:Amplitude-accurate devices with calibration-grade traceability serve satellite ground station validation chains in Germany, Japan, and the United States. RF engineer scarcity across North American and European defense contractors accelerates automated testing procurement for this segment.
- Directional Couplers:Broadband passive sampling devices operating DC to 67 GHz form the backbone of signal distribution networks. China's MIIT spectrum reallocation pulls sub-6 GHz demand through state-owned base station vendors.
- Standard Couplers:General-purpose 50-ohm and 75-ohm devices for commercial broadcast and cable infrastructure.
- High-Power Couplers:Thermal-dissipating designs for radar transmitters and electronic warfare systems handling elevated power density.
Directional couplers retain volume leadership; precision couplers hold the steepest expansion curve.
Technology:
Cost tier stratification separates captive ceramic substrate fabrication from outsourced assembly models.
- RF Devices:Electromagnetic power sampling components utilizing coaxial transmission line geometries. Defense procurement through MIL-STD-348 and EU Defense Fund sourcing criteria tightens traceability requirements on these assemblies.
- Passive Devices:Non-amplifying components including resistive, capacitive, and inductive coupling structures. REACH candidate list expansions trigger reformulation of plating baths and dielectric materials for European export compliance.
- Active Devices:Semiconductor-integrated couplers with signal conditioning and amplification capabilities.
- Optical Devices:Fiber-optic coupling technologies competing for bandwidth in certain signal distribution applications.
Passive devices dominate current procurement volumes; RF devices are climbing the fastest on defense and 5G capital expenditure.
End User:
Customer type concentration varies sharply between state-directed procurement and commercial infrastructure deployment.
- Military:Electronic warfare, radar, and secure communications systems requiring MIL-STD-348 compliance and ITAR-controlled supply chains. US State Department export control reform discussions stretch supplier onboarding timelines for cross-border programs.
- Telecommunications:5G base station and backhaul infrastructure driving sub-6 GHz directional coupler demand. India's PLI scheme for telecom electronics creates openings for local assembly to bypass import duties.
- Aerospace:Satellite payload and ground station applications demanding precision amplitude accuracy.
- Broadcasting:Legacy 75-ohm cable and terrestrial transmission infrastructure in Japan and Germany.
Military end use commands premium positioning; telecommunications is expanding most quickly on Asia-Pacific infrastructure buildout.
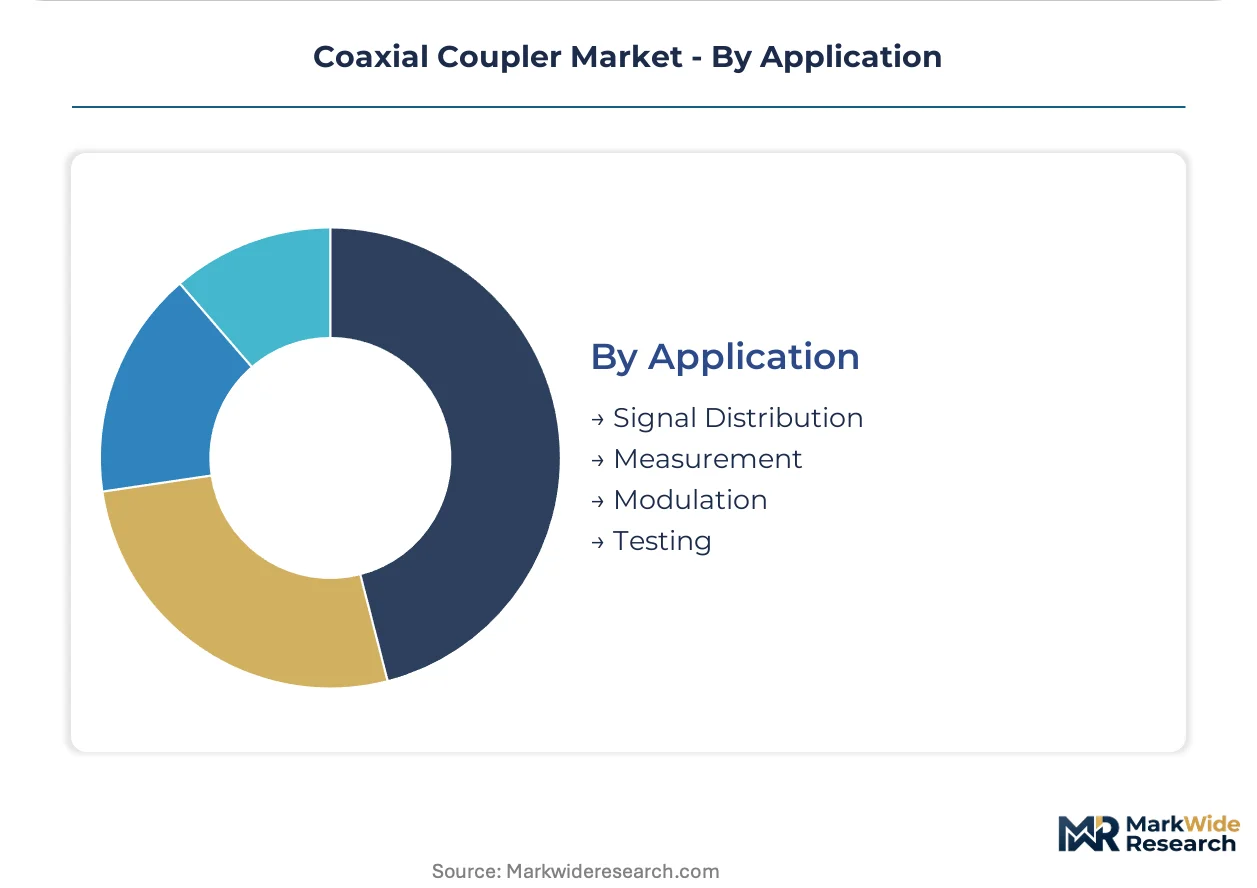
Application:
Supply concentration in calibration-grade testing equipment creates margin differentiation against commoditized signal distribution.
- Measurement:Laboratory and field calibration systems requiring traceable amplitude accuracy for system validation. LEO constellation operators in California and Texas now mandate five-year price locks and dedicated capacity reservations for these components.
- Signal Distribution:Power splitting and sampling networks for broadcast, cable, and wireless infrastructure. Silver-palladium plating cost volatility compresses margins, forcing pass-through clauses in aerospace contracts.
- Testing:Automated RF test systems reducing dependency on scarce calibration engineers in US and German facilities.
- Modulation:Signal conditioning applications in communications and radar transmitters.
Signal distribution retains installed base dominance; measurement applications gain share fastest on satellite ground station densification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 emissions rules anchor procurement protocols across the United States, while spectrum reallocations and defense procurement reforms reshape demand patterns in Germany, China, Japan, and India.
United States
Defense contractors in California and Texas expand automated RF testing facilities to offset scarce calibration engineer availability. MIL-STD-348 procurement protocols tighten traceability requirements on cross-border satellite programs. SpaceX and Amazon Kuiper procurement teams in these states now mandate five-year price locks and dedicated capacity reservations for precision couplers.
Germany
Satellite ground station densification for low-earth orbit constellations pulls amplitude-accurate precision coupler demand through calibration laboratory networks. EU RoHS substance restrictions and REACH candidate list expansions force reformulation of plating baths and dielectric materials. Bavarian aerospace suppliers absorb the highest compliance costs as they qualify alternative barrier layers for export-oriented supply chains.
China
MIIT spectrum reallocation accelerates domestic 5G base station deployment, pulling sub-6 GHz directional coupler demand through state-owned equipment vendors. The country's dual carbon goals influence material selection in ceramic substrate fabrication. Yangtze River Delta manufacturing clusters concentrate alumina and aluminum nitride substrate production for regional coupler assemblers.
Japan
METI industrial standards shape high-frequency component specifications for satellite payload integration. Legacy 75-ohm broadcast and cable infrastructure complicates 50-ohm coupler standardization in converged network upgrades. Tokyo and Osaka metropolitan areas host precision coupler fabrication facilities serving domestic LEO constellation operators.
India
The PLI scheme for telecom and defense electronics creates openings for coupler manufacturers establishing local assembly to bypass import duties on finished RF components. TRAI spectrum allocation timelines influence base station deployment schedules. Maharashtra and Karnataka industrial corridors attract RF component investments targeting military and telecommunications procurement channels.
Coaxial Coupler Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the coaxial coupler market. Captive ceramic substrate fabrication distinguishes premium-positioned players from outsourced assembly models. Three archetypes dominate: vertically integrated substrate-to-assembly operations, precision calibration-grade specialists, and high-volume broadband coupler suppliers. Competitive moves concentrate on strategic partnerships for substrate security and geographic expansion to capture India PLI scheme benefits.
Among North American diversified connectors manufacturers, Amphenol Corporation and TE Connectivity occupy positions reflecting integrated substrate capabilities. Hirose Electric exemplifies the miniaturization specialist archetype serving satellite payload integration requirements. These three entities represent distinct competitive vectors: captive material control, aerospace certification anchoring, and board-level form factor leadership.
| Leading Market Players |
|---|
| Amphenol Corporation |
| TE Connectivity |
| Molex |
| Radiall |
| Rosenberger |
| Hirose Electric |
| HUBER+SUHNER |
| Pasternack Enterprises |
| Japan Aviation Electronics Industry |
| Others |
Value Chain & Pricing Dynamics
Alumina substrate fabrication at scale in Japanese and Chinese facilities creates dual sourcing advantages that simultaneously compress price floors for precision couplers and elevate entry barriers for non-integrated assemblers. This capacity concentration allows captive producers to absorb silver-palladium plating volatility through internal cost allocation while contract-dependent competitors pass through precious metal swings to aerospace buyers.
Pricing Analysis
California and Texas test range facilities pay premiums reaching double-digit spreads over Bavarian aerospace suppliers for identical MIL-STD-348 certified precision couplers. Three-tier pricing structure across calibration-grade, military-aerospace, and commercial broadband levels separates amplitude-accurate devices from general-purpose 50-ohm units. Cost compression in high-frequency precision lines is intensifying because SpaceX and Amazon Kuiper procurement teams mandate five-year price locks with dedicated capacity reservations. Commercial broadcast buyers exhibit highest price sensitivity, while satellite ground station operators accept premium positioning for traceable calibration-grade devices.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Yangtze River Delta ports extend inbound logistics cycles for European and North American coupler assemblers. Alumina and aluminum nitride substrate fabrication concentrates in Japanese and Chinese facilities, while precision plating chemistry draws from German and French specialty chemical suppliers. Single-source vulnerability in ceramic substrate supply creates structural risk for US and European assemblers lacking backward integration into captive material production. Distribution runs through direct procurement contracts with LEO constellation operators and state-owned telecommunications equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across automated testing, satellite payload miniaturization, and India's defense indigenization creates multiple entry niches for specialized players. Defense procurement automation and REACH substance restrictions simultaneously expand addressable whitespace while compressing incumbent margin structures.
For Market Incumbents: Consolidate ceramic substrate fabrication capabilities through acquisition of Japanese or Chinese specialty ceramics producers to eliminate single-source vulnerability. Lock in five-year capacity reservations with LEO constellation operators before micromachined stripline alternatives displace coaxial geometries in satellite payload applications.
For New Entrants and Emerging Players: Automated calibration workflow integration services represent the most penetrable service-layer gap where incumbents under-serve defense contractors facing 18-24 month RF engineer hiring cycles. Target India's PLI scheme beneficiaries with local assembly partnerships that bypass import duties on finished RF components. Lead with GaN-SiC thermal management expertise as the go-to-market angle for radar transmitter applications.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision coupler specialists with AS9100-certified facilities serving satellite ground station densification programs. Long-term viability over the next decade rests on substrate-to-assembly integration depth and defense procurement automation exposure. Watch ITAR reform timeline acceleration as the critical inflection signal for cross-border program accessibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | Eliminates single-source vulnerability in Japanese and Chinese alumina supply clusters. |
| AS9100 Certification Investment | Unlocks EU Defense Fund procurement criteria for satellite and electronic warfare programs. |
| India Local Assembly Partnership | Captures PLI scheme benefits while bypassing import duties on finished RF components. |
| Automated Calibration Workflow Development | Addresses RF engineer scarcity compressing hiring cycles at US and German defense contractors. |
| GaN-SiC Thermal Management R&D | Positions for broadband directional coupler demand from radar transmitter power density increases. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with RF engineering directors, defense procurement officers, satellite payload integrators, and ceramic substrate fabrication specialists; and secondary validation through FCC Part 15 filings, MIL-STD-348 procurement databases, EU RoHS compliance registries, and MIIT spectrum allocation notices. Bottom-up and top-down triangulation cross-checked component-level production estimates against end-use deployment tracking.
Across the analysis window, the forecasting framework modeled volume and value trajectories through product type segmentation (precision, directional, standard, high-power), technology tier (RF, passive, active, optical), end-use vertical (military, telecommunications, aerospace, broadcasting), and application category (measurement, signal distribution, testing, modulation). CAGRs were derived from regression analysis of historical procurement velocity correlated with defense budget automation indices and 5G base station deployment schedules. Industry-specific inputs included precious metal plating cost indices and ITAR qualification timeline elasticity assumptions.
Material uncertainties — ITAR reform implementation pace, REACH candidate list expansion timing, and silver-palladium price volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding defense procurement automation adoption curves and MIIT spectrum reallocation execution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Timing Relay Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
Electronic Speed Controllers Market
Electronic Components
Electric Fuse Market
Electronic Components
Digital Class-D Amplifier Market
Electronic Components
Europe Water Cooled Capacitors Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
RAID Controller Card Market
Electronic Components
Industrial Relays Market
Electronic Components
Surface Mountable Laser Direct Structuring Antenna (LDS) Market
Electronic Components
Microcontroller Socket Market
Electronic Components
Electromechanical Timers Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Ceiling Microphone Market
Electronic Components
Breadboards Market
Electronic Components
Audio Capacitor Market