
 Middle East Connector Market | 2026-2036
Middle East Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Connector Market Insights
Aftermarket service revenue is fragmenting across the Middle East connector landscape as OEMs and distributors compete for lifecycle maintenance contracts. TE Connectivity leverages its regional logistics hubs to capture refurbishment and technical support margins. Amphenol anchors its position through specialized harsh-environment product lines suited for desert oilfield and aerospace applications. Molex competes aggressively on lead-time reduction for telecom infrastructure projects across the Gulf states.
A connector is an electromechanical device engineered to join electrical terminations, typically incorporating contact pins rated for specific current loads, insulation resistance measured in megaohms, and mating cycles ranging from hundreds to tens of thousands depending on application class. Its primary industrial purpose is to establish reliable, removable signal or power pathways between subsystems while maintaining electromagnetic integrity under vibration, thermal cycling, and moisture exposure. Optical connectors and RF connectors command premium positioning due to bandwidth density requirements in 5G and satellite communication networks, while Ethernet connectors sustain volume leadership across industrial automation and data center builds. Fiber optic technology segments attract disproportionate R&D allocation as Gulf operators deploy submarine cable landing stations and metro fiber rings.
Saudi Arabia's SFDA enforces medical device connector standards that restrict market access for uncertified suppliers, while the UAE's telecommunications regulator mandates EMC compliance for network infrastructure components. The EU's RoHS and REACH frameworks indirectly shape procurement specifications for European-owned projects and joint ventures operating across the region. Stakeholders must monitor evolving Gulf standardization harmonization efforts and decide whether to pursue multi-jurisdiction certification portfolios or concentrate on single-country regulatory dominance.
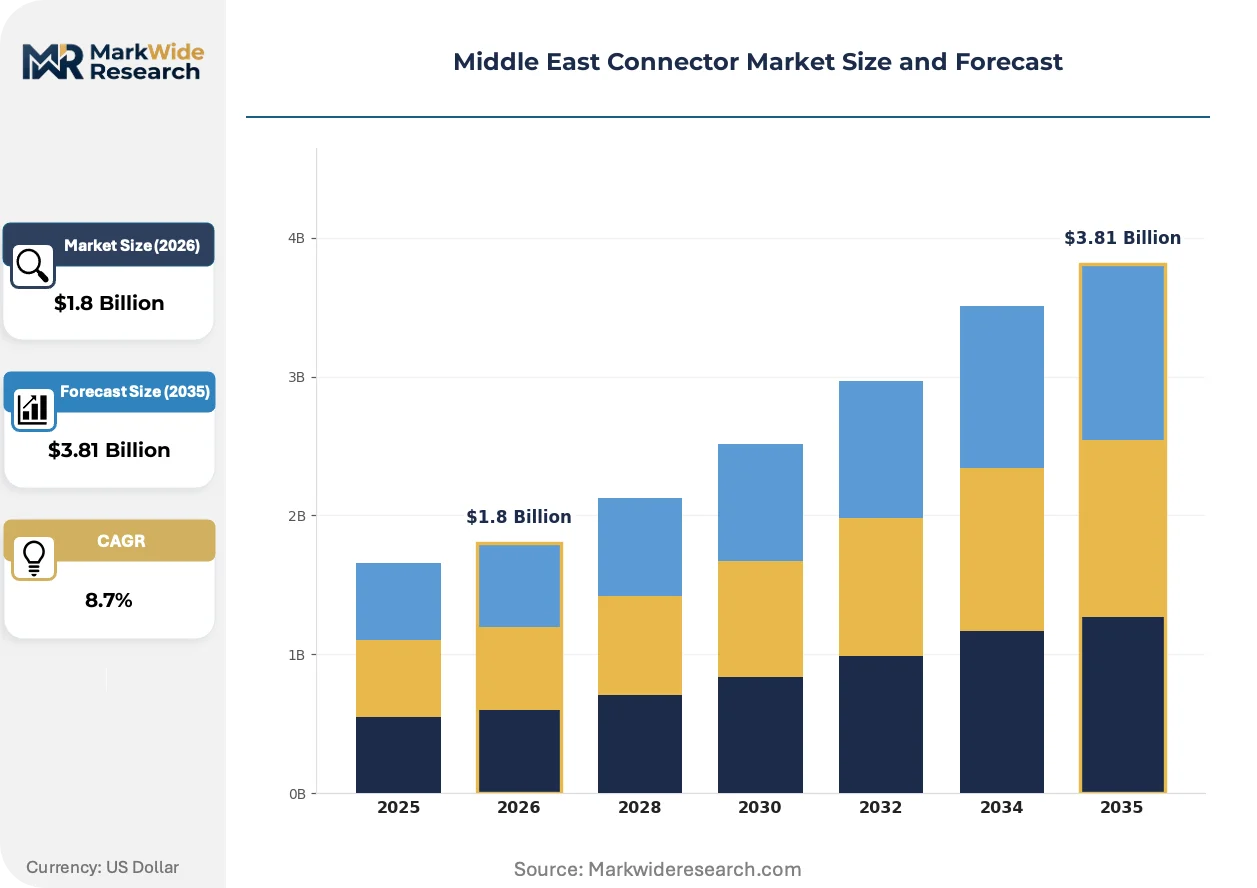
Market Dynamics
Telecom infrastructure buildouts across Saudi Arabia and the UAE are accelerating connector procurement for 5G base stations and fiber backhaul networks. Regional adoption of SFDA medical device standards and NMPA-influenced quality benchmarks is elevating product certification requirements for suppliers.
Growth Catalysts
- SFDA Medical Device Standards:Saudi Arabia's enforcement of connector specifications for healthcare equipment restricts market access for uncertified suppliers, creating protected revenue pools for compliant manufacturers.
- Smart City Deployments:Gulf Cooperation Council urban infrastructure projects consume high-reliability optical and RF connector volumes for data center and smart grid applications.
- Submarine Cable Landing Stations:Metro fiber ring expansions across Dubai and Abu Dhabi drive disproportionate R&D allocation toward fiber optic connector technology segments.
Market Restraints
- Copper and Rare Earth Volatility:Contact pin material costs fluctuate with commodity markets, compressing margins on high-volume industrial connector lines.
- East Asian Supply Concentration:Precision stamping and plating capacity clusters in China and Taiwan create vulnerability to logistics disruptions affecting Gulf procurement timelines.
- EMC Compliance Friction:UAE telecommunications regulator mandates for network infrastructure components add certification delays for non-European suppliers unfamiliar with CE marking alignment.
Strategic Opportunities
- Qatar's Lusail Smart City:Underpenetrated connector demand exists in integrated utility and transport networks beyond the Saudi-UAE corridor.
- Desert Harsh-Environment Specialization:Oilfield and aerospace applications require thermal cycling and moisture-resistant designs that command premium positioning.
- EU-Gulf Joint Ventures:RoHS and REACH framework alignment creates regulatory tailwinds for European-certified suppliers bidding on European-owned regional projects.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Harmonization gaps between SFDA, MOHAP, and emerging Gulf standardization efforts force suppliers to maintain parallel compliance tracks.
- Legacy System Integration Complexity:Smart grid deployments must interface with existing SCADA infrastructure, requiring backward-compatible connector architectures that extend development cycles.
- Optical Assembly Skill Scarcity:Fiber polishing and ferrule alignment expertise concentrates in East Asian technician pools, constraining regional manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Connector Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Connectors, RF Connectors, Ethernet Connectors, USB Connectors End User: Telecommunication, Aerospace, Automotive, Industrial Applications Technology: Fiber Optic, Coaxial, Twisted Pair, Wireless Application: Data Centers, Networking, Consumer Electronics, Smart Grid |
| Companies Covered | TE Connectivity, Amphenol, Molex, Fujitsu, American Connectors Inc., Thomas & Betts, ITT BIW Connector Systems, Emerson Industrial Automation, Samtec, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Connector Market Trends and Innovations
Active optical cable assemblies are rendering obsolete traditional discrete connector-plus-cable configurations across hyperscale data center deployments. Material science advances and regulatory harmonization pressures are simultaneously reshaping product roadmaps and supplier qualification protocols.
Miniaturized push-pull fiber connectors with expanded beam technology tolerate dust and vibration in desert environments without protective caps. Saudi Aramco and Emirates airline maintenance divisions are specifying these for field-deployable systems. Expanded beam architecture is rendering obsolete traditional physical contact ferrules that require cleaning protocols impractical for oilfield technicians.
SFDA medical device connector standards now incorporate biocompatibility and sterilization cycle requirements adapted from EU MDR frameworks. Industrial consequence includes mandatory third-party testing for all patient-contacting electrical interfaces. Cardiac device and imaging equipment suppliers serving Saudi hospitals are restructuring supply chains to retain single-source certification documentation.
Aftermarket service revenue is fragmenting across the regional landscape as OEMs and distributors compete for lifecycle maintenance contracts. Technical support and refurbishment margins previously captured by manufacturers now split with authorized regional logistics hubs. This unbundling is most visible in telecom infrastructure across the Gulf states, where base station operators negotiate separate connector replacement and field engineering agreements.
Middle East Connector Market Segmentation
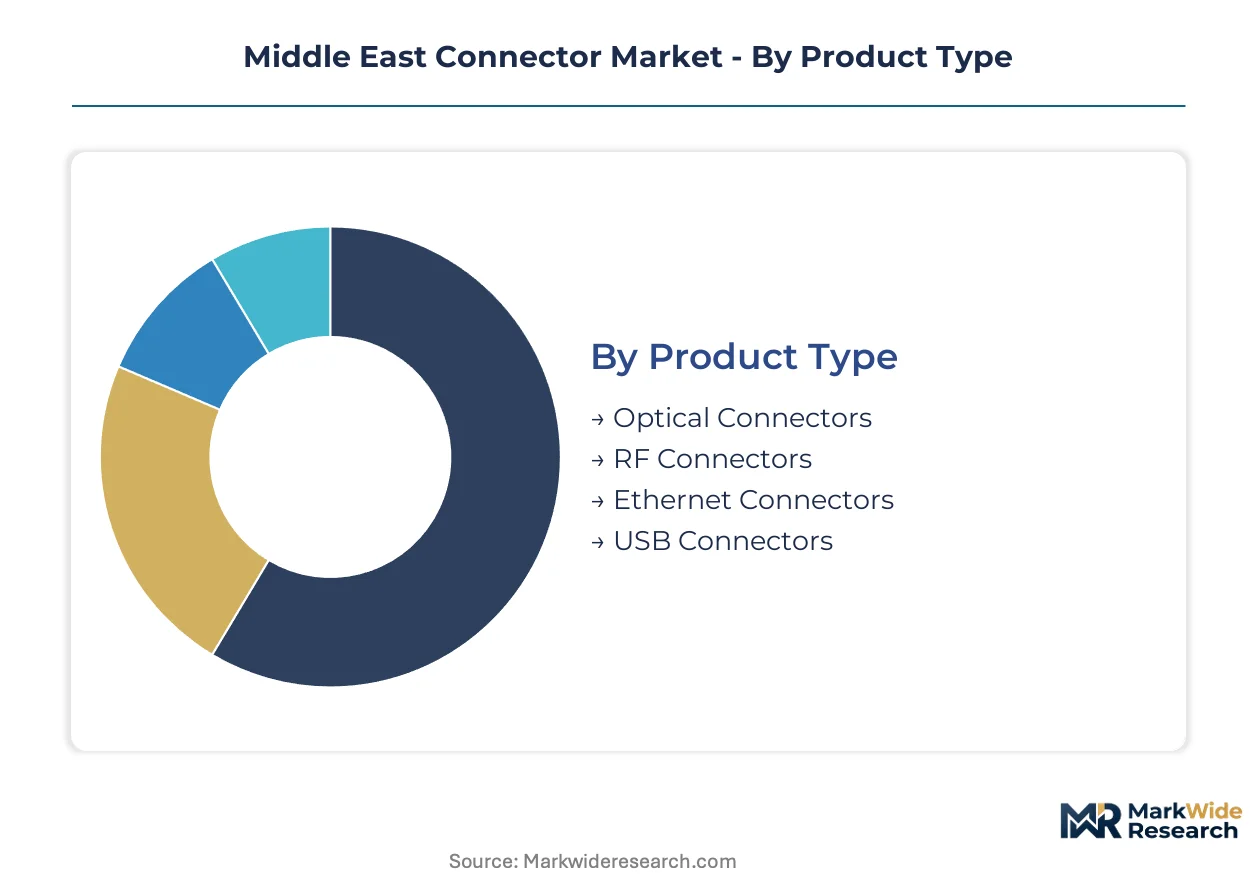
Connector procurement across the Middle East diverges sharply by signal type and environmental exposure, with bandwidth density requirements and desert operating conditions dictating specification choices. Suppliers must align product portfolios to four distinct technical axes—each commanding separate certification pathways and margin structures.
Product Type:
Cost tier separation runs deepest across connector families, with material content and precision tolerances driving 10-20x price spreads between commodity and mission-critical variants.
- Optical Connectors:Expanded-beam ferrule designs tolerate dust intrusion without cleaning protocols required by physical-contact alternatives. Saudi Aramco field-deployable systems and Emirates airline maintenance divisions specify these for desert oilfield and tarmac environments where technician access is limited.
- RF Connectors:Precision impedance-matched interfaces support 5G base station deployments across Saudi Arabia and the UAE, with phase stability specifications tightening as millimeter-wave spectrum auctions advance. Gulf telecom operators prioritize suppliers with in-region calibration facilities.
- Ethernet Connectors:Industrial-grade shielded variants dominate smart grid and automation installations, with PoE++ power delivery requirements expanding conductor gauge specifications.
- USB Connectors:Consumer electronics and point-of-sale terminal demand concentrates in UAE free zone manufacturing, with Type-C migration displacing legacy Micro-USB inventories.
Optical connectors hold installed capacity. RF connectors are rotating up the share rankings.
End User:
Application exposure severity—thermal cycling range, vibration amplitude, and moisture ingress risk—determines which connector families each vertical specifies.
- Telecommunication:5G macro cell and fiber backhaul buildouts across the Gulf Cooperation Council consume high-reliability optical and RF connector volumes, with SFDA-influenced quality benchmarks elevating supplier qualification thresholds for network infrastructure components.
- Aerospace:Emirates and Saudia maintenance divisions specify MIL-DTL-derived circular connectors with extended temperature ratings for avionics bay installations, where thermal cycling between ground and altitude extremes exceeds commercial-grade tolerances.
- Automotive:Electric vehicle charging infrastructure across the UAE deploys high-current power connectors with IP67 sealing, though regional EV adoption lags European penetration rates.
- Industrial Applications:Oilfield SCADA retrofits in Saudi Arabia's Eastern Province require backward-compatible connector architectures that bridge legacy 4-20mA analog systems with digital fieldbus protocols.
Telecommunication dominates current procurement volumes. Aerospace is climbing the fastest on reliability-premium pricing.
Technology:
Signal propagation physics—bandwidth-distance tradeoffs and electromagnetic immunity—segment procurement specifications across Gulf infrastructure projects.
- Fiber Optic:Single-mode and multimode cable assemblies for Dubai and Abu Dhabi metro fiber ring expansions, with submarine cable landing stations driving disproportionate R&D allocation toward marine-grade connector sealing.
- Coaxial:Harsh-environment variants with corrosion-resistant plating serve desert oilfield telemetry and satellite ground station applications where humidity and salt spray coexist.
- Twisted Pair:Industrial Ethernet deployments in smart city utility networks, with Category 6A shielded systems specified for electromagnetic compatibility in high-voltage substation proximity.
- Wireless:Connectorized antenna interfaces for 5G small cell densification, though true wireless power transmission remains peripheral to Gulf infrastructure planning.
Fiber optic commands the steepest expansion trajectory. Coaxial maintains entrenched positions in legacy energy infrastructure.
Application:
Customer type differentiation—hyperscale operator versus industrial utility versus consumer OEM—shapes volume, customization, and service attachment rates.
- Data Centers:Active optical cable assemblies are displacing discrete connector-plus-cable configurations in hyperscale facilities, with push-pull MPO-16 interfaces dominating spine-leaf architectures.
- Networking:Enterprise and carrier router deployments across Saudi Arabia's NEOM and UAE smart city projects require field-terminable fiber connectors that reduce installation skill barriers.
- Consumer Electronics:UAE free zone assembly operations source USB and HDMI connectors at high volume but compress margins through consolidated procurement consortia.
- Smart Grid:Qatar's Lusail integrated utility network and Saudi smart meter rollouts specify outdoor-rated connectors with extended temperature ranges and surge protection integration.
Data centers concentrate the highest-value procurement. Smart grid is gaining share fastest on infrastructure modernization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Connector procurement across the Gulf Cooperation Council shows sharp demand-elasticity divergence: telecom operators in the UAE and Saudi Arabia absorb premium pricing for certified optical assemblies, while industrial buyers in Egypt and Turkey remain acutely price-sensitive on commodity interconnects.
Saudi Arabia
SFDA medical device connector standards and NEOM smart city fiber deployments drive procurement volumes. The national regulator enforces biocompatibility testing for patient-contacting electrical interfaces, restricting market access for uncertified suppliers. Riyadh and the Eastern Province concentrate oilfield SCADA retrofits requiring backward-compatible connector architectures bridging legacy analog systems with digital protocols.
United Arab Emirates
MOHAP pharmaceutical equipment standards and Dubai's metro fiber ring expansions sustain high-reliability optical connector demand. The telecommunications regulator mandates EMC compliance for network infrastructure components, adding certification friction for non-European suppliers. Abu Dhabi's submarine cable landing stations and hyperscale data center builds disproportionately allocate R&D toward marine-grade connector sealing.
Qatar
Lusail Smart City's integrated utility and transport networks represent underpenetrated connector demand beyond the Saudi-UAE corridor. The national standardization body aligns with Gulf harmonization efforts on smart grid specifications. Doha's concentrated infrastructure investment creates protected procurement pools for suppliers with in-region technical support capabilities.
Kuwait
Oilfield telemetry modernization and power grid automation sustain industrial connector procurement despite smaller absolute volumes. The national oil company specifies harsh-environment variants with corrosion-resistant plating for desert installations. Ahmadi and Al-Jahra industrial zones concentrate maintenance, repair, and operations demand for legacy system-compatible interconnects.
Egypt
Price-sensitive industrial automation and consumer electronics assembly drive commodity connector volumes. The national telecommunications regulator advances 5G infrastructure planning, though procurement lags Gulf timelines. Cairo-Alexandria manufacturing corridors source consolidated USB and Ethernet connector volumes through procurement consortia compressing supplier margins.
Middle East Connector Market Competitive Landscape
Capability concentration sits with specialized harsh-environment manufacturers; scale advantage sits with diversified global interconnect suppliers. The Middle East connector market structures around three tiers: premium-positioned specialists commanding certification-protected margins in medical and aerospace verticals; mid-scale regional distributors capturing aftermarket service fragmentation; and volume-focused manufacturers competing on lead-time compression for telecom infrastructure. Dominant competitive moves include strategic partnerships with Gulf state-owned enterprises and geographic expansion through authorized logistics hubs in Dubai and Riyadh.
Within the premium-tier specialist archetype, TE Connectivity and Amphenol occupy anchor positions exemplifying divergent strategic approaches to regional positioning. TE leverages its logistics infrastructure to capture lifecycle maintenance contract fragmentation, while Amphenol anchors through product lines suited for desert oilfield and aerospace applications. Molex represents the scale-driven competitive vector, competing aggressively on lead-time reduction for Gulf telecom infrastructure projects. These three entities collectively illustrate how certification depth, regional presence, and operational velocity segment competitive positioning across the Middle East connector landscape.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol |
| Molex |
| Fujitsu |
| American Connectors Inc. |
| Thomas & Betts |
| ITT BIW Connector Systems |
| Emerson Industrial Automation |
| Samtec |
| Others |
Pricing and Supply Chain Analysis
Jebel Ali Port freight corridors impose cost volatility that amplifies price spreads between Gulf-certified premium tiers and commodity imports. Connector procurement across the Middle East stratifies sharply: logistics exposure and certification depth determine which suppliers capture maintenance-contract premiums versus volume-lead-time races.
Pricing Analysis
Aftermarket service contracts and technical support agreements now drive lifetime value more than unit hardware margins. Three-tier pricing structure across SFDA-certified medical, industrial-grade harsh-environment, and standard commercial levels separates compliant Gulf suppliers from price-pressured commodity importers. Cost compression in standard Ethernet and USB connector lines intensifies as Egyptian and Turkish procurement consortia consolidate volumes. Telecom operators in Saudi Arabia and the UAE exhibit lowest price sensitivity, prioritizing certification documentation and in-region calibration facilities over per-unit cost.
Supply Chain Analysis
Foxconn, Flex, and Jabil hold dominant contract-manufacturing capacity for precision connector stamping and plating operations across China, Taiwan, and Malaysia. Raw material dependencies center on copper alloy rod, gold-palladium-nickel plating chemistries, and high-performance thermoplastic resins. Single-source vulnerability concentrates in East Asian precision ferrule grinding and expanded-beam lens molding equipment. Distribution runs through Dubai and Riyadh authorized logistics hubs that split aftermarket service revenue between OEMs and regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connector procurement across the Middle East is restructuring around service-attach revenue faster than hardware shipment growth. Lifecycle maintenance contracts and field engineering agreements now expand at multiples of base connector unit demand.
For Market Incumbents: Entrench certification-protected positions in SFDA medical and aerospace verticals through accelerated third-party testing investments. Vertical integration into regional refurbishment hubs in Jebel Ali and King Abdullah Economic City defends margin pools against distributor encroachment. Threat substitution from active optical cable assemblies demands pre-emptive MPO-16 spine-leaf architecture partnerships with hyperscale data center operators. For New Entrants and Emerging Players: Pursue underpenetrated demand in Qatar's Lusail Smart City integrated utility networks beyond the Saudi-UAE corridor. Oilfield SCADA retrofit applications in Kuwait's Ahmadi industrial zone offer protected procurement pools with lower certification friction than medical verticals. Go-to-market angle: partner with European OEMs on RoHS-REACH aligned joint ventures serving EU-Gulf infrastructure projects. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant connector product lines lacking Gulf certification depth. Long-term viability hinges on regulatory moat sustainability across SFDA-MOHAP harmonization timelines. Signal to watch: technician training center investments by Saudi Aramco or Emirates indicating captive optical assembly capability buildout.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | SFDA and MOHAP multi-jurisdiction compliance unlocks protected revenue pools in medical and telecom verticals. |
| Regional Logistics Hub Establishment | Dubai and Riyadh authorized facilities capture fragmented aftermarket service revenue from distributor networks. |
| Harsh-Environment Product Line Development | Thermal cycling and dust-resistant designs command premium positioning in Saudi Aramco oilfield deployments. |
| Active Optical Cable Assembly Partnership | Hyperscale data center spine-leaf architectures displace discrete connector-plus-cable configurations. |
| Technician Training Center Investment | Regional fiber polishing and ferrule alignment expertise reduces East Asian supply concentration risk. |
Research Methodology
Desk research of trade customs databases, SEC filings from listed connector manufacturers, and Gulf standardization body technical specifications preceded structured interviews with telecom procurement directors, oilfield SCADA engineers, medical device regulatory affairs leads, and aftermarket service managers. Primary fieldwork across Dubai, Riyadh, and Doha validated secondary estimates through bottom-up and top-down triangulation.
Assumptions held fixed include SFDA and MOHAP regulatory enforcement intensity, Gulf Cooperation Council smart city investment timelines, and East Asian contract-manufacturing capacity availability. Variables modeled across the analysis window encompass fiber optic versus copper penetration rates, 5G spectrum auction progressions, and medical device certification pathway durations. CAGRs derive from segment-level volume builds calibrated to disclosed hyperscaler capex and national oil company telemetry modernization budgets.
Sensitivities concentrate around commodity copper and rare earth price volatility, East Asian logistics disruption scenarios, and Gulf standardization harmonization acceleration. Quarterly review of SFDA guidance updates, Jebel Ali Port throughput indices, and Saudi Aramco maintenance division procurement bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Magnetic Connector Market
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
IC Socket Market
Connectors
DIN Connectors Market
Connectors
Asia-Pacific Connector Market
Connectors
Circular Connectors Market
Connectors
High-Reliability Connectors Market
Connectors
Automotive Data Connectors Market
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Circular Waterproof Connector Market
Connectors
Mexico Connector Market
Connectors
Small Bore Connectors Market
Connectors
SATA Connector Market
Connectors
Connector Kits Market
Connectors
AS-Interface Market
Connectors
Canada Connector Market