
 5G BTS Antenna Market | 2026-2036
5G BTS Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
5G BTS Antenna Market Analysis
The FCC's mid-band spectrum reallocation is broadening the cost-of-entry calculus for antenna suppliers targeting North American 5G rollouts. Nokia Corporation leverages its end-to-end portfolio to sustain R&D intensity across massive MIMO architectures. Huawei Technologies anchors manufacturing scale through captive semiconductor supply chains despite trade restrictions. Ericsson differentiates through Open RAN interoperability commitments that reduce operator lock-in.
A 5G BTS antenna is a radio frequency transducer that converts electrical signals to electromagnetic waves for cellular base station transmission, typically operating across 600 MHz to 39 GHz with beamforming arrays that enable spatial multiplexing for higher spectral efficiency. Panel antennas dominate outdoor macro deployments due to established supply chains and proven wind-load tolerances, while mmWave active antenna systems represent the fastest-growing technology segment as operators densify urban networks. MIMO configurations concentrate margin pools in 64T64R and 32T32R variants where RF component integration complexity limits new entrants.
The FCC, ETSI, and MIIT collectively shape product standards through spectrum allocation rules, electromagnetic exposure limits, and domestic content requirements that determine market access eligibility. ETSI's harmonized standards for 5G NR radio conformance testing create compliance barriers that favor incumbents with established certification laboratories. Stakeholders must monitor spectrum auction timelines and Open RAN interoperability mandates as decisive variables for procurement strategy and partnership selection.
Market Dynamics
Beamforming array density requirements are compressing supplier margins as RF component integration complexity escalates across massive MIMO architectures. The shift from passive to active antenna systems concentrates procurement power among operators with sufficient capex scale to absorb upfront unit costs.
Growth Catalysts
- MIIT deployment mandates:China's national broadband strategy imposes aggressive base station installation targets that lock in multi-year procurement commitments from state-owned carriers.
- mmWave spectrum densification:Urban network capacity constraints are accelerating active antenna system adoption in high-traffic metropolitan clusters.
- FCC mid-band reallocation:The United States spectrum policy shift is expanding addressable hardware configurations for antenna suppliers targeting North American rollouts.
Market Restraints
- Gallium nitride substrate costs:Power amplifier material input price volatility constrains margin expansion for high-frequency antenna variants.
- Captive semiconductor supply:Concentrated fabrication capacity in East Asian foundries creates geopolitical exposure for European and North American equipment vendors.
- Electromagnetic exposure thresholds:ETSI field strength limits impose design constraints that extend certification timelines for new product introductions.
Strategic Opportunities
- Indian spectrum auctions:TRAI 5G allocation rounds create first-mover positioning for suppliers establishing local assembly partnerships.
- Open RAN interoperability mandates:Operator procurement specifications favoring multi-vendor integration open incumbent displacement pathways.
- AI-driven beam management:Convergence of machine learning inference with radio control software enables predictive optimization services as recurring revenue streams.
Industry Challenges
- RF systems integration expertise:Scarcity of engineers with combined antenna design and digital signal processing capabilities extends product development cycles.
- Multi-band certification sequencing:Sequential regulatory approval across FCC, ETSI, and MIIT regimes delays revenue recognition for globally targeted platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G BTS Antenna Market |
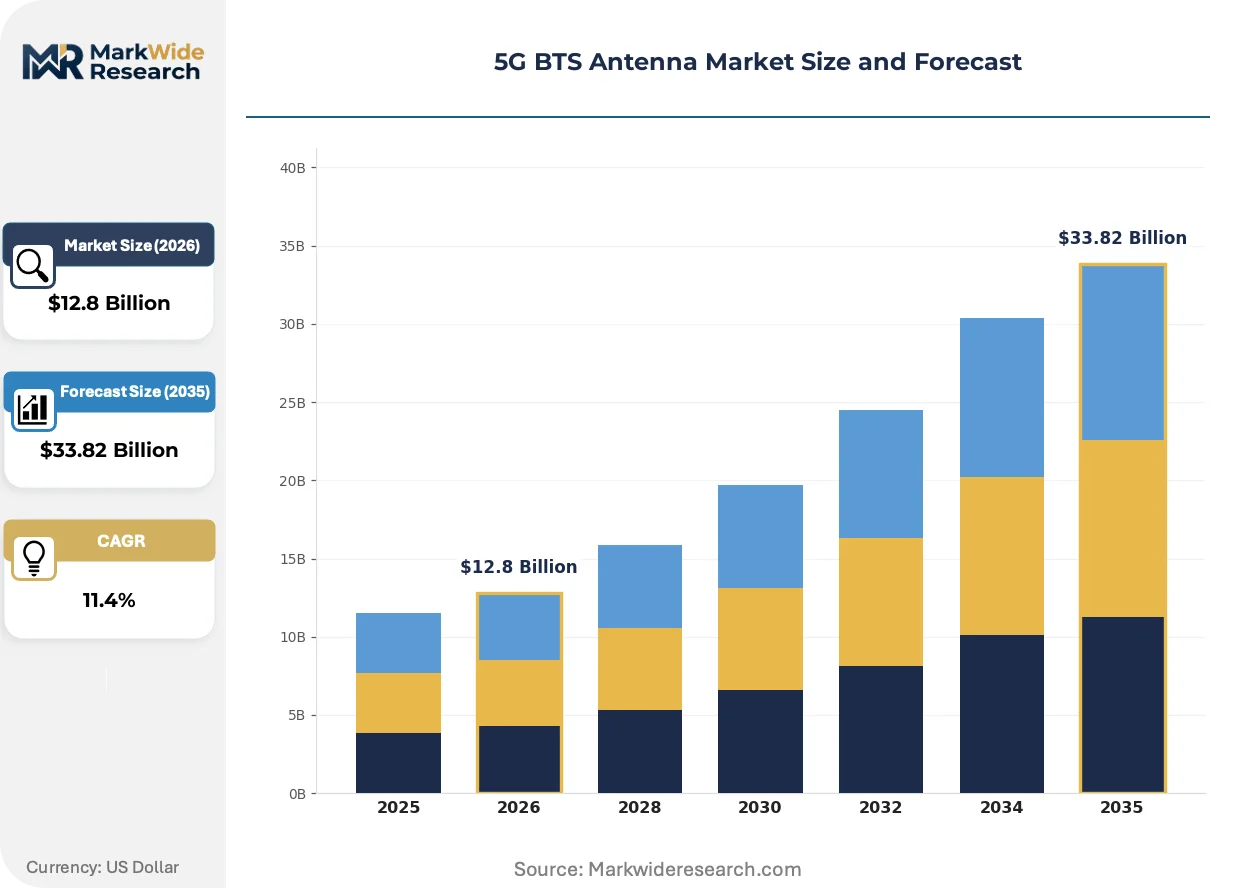
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Antennas, Omnidirectional Antennas, MIMO Antennas, Remote Radio Units Technology: Sub-6 GHz, mmWave, Active Antenna Systems, Hybrid Systems Deployment Type: Indoor, Outdoor, Roof-Top, Small Cells End User: Telecom Operators, Enterprises, Governments, Others |
| Companies Covered | Nokia Corporation, Amphenol Corporation, Huawei Technologies, Kathrein, ZTE Corporation, CommScope Holding Company, Comba Telecom Systems Holdings, PCTEL, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G BTS Antenna Market Emerging Trajectories
Software-defined radio architectures are dissolving traditional hardware-software boundaries in base station equipment. This convergence is compressing vendor specialization advantages and enabling new entrants with computational rather than RF heritage.
Integrated active antenna units with embedded baseband processing are electrifying deployment economics for dense urban networks. Telecom operators in South Korea and Japan are accelerating procurement of these consolidated platforms. The technology is electrifying competitive positioning by collapsing the historical separation between radio head and antenna suppliers.
ETSI harmonized standards for 5G NR radio conformance testing are elevating certification laboratory capacity as a strategic bottleneck. Equipment vendors with captive testing facilities are compressing rival time-to-market by six to nine months. Mid-tier suppliers without European laboratory access are redirecting development resources toward regional spectrum bands with lower compliance burdens.
Buyer concentration among tier-one mobile network operators is hardening procurement leverage and extending payment terms. Equipment vendors are responding by unbundling hardware from software maintenance contracts to preserve margin visibility. This contractual restructuring is most visible in North American and Western European markets where operator consolidation has reduced qualified bidder pools to fewer than five national carriers.
5G BTS Antenna Market Segmentation
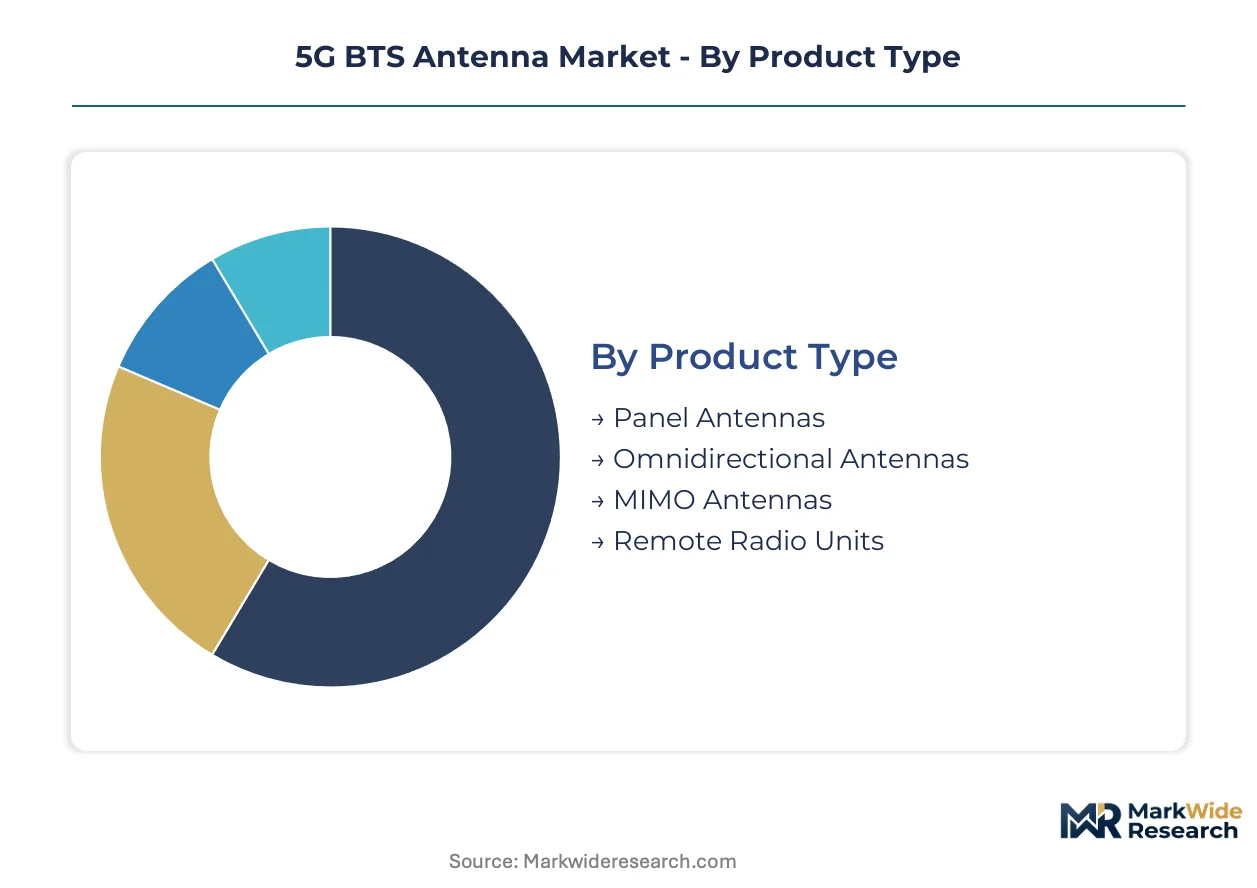
Antenna segmentation in 5G BTS markets determines certification pathways, integration complexity, and procurement eligibility. Product type and technology choices lock suppliers into specific regulatory approval sequences and manufacturing scale requirements.
Product Type:
FCC, ETSI, and MIIT certification requirements vary sharply across product architectures, with passive and active systems triggering different electromagnetic exposure testing protocols.
- Panel Antennas:Directional radiating elements arranged in planar arrays with fixed electrical downtilt, typically housing 8 to 16 radiating columns. Demand concentrates in China where MIIT-mandated base station targets require proven wind-load tolerances for macro tower deployments. ETSI field strength limits extend certification timelines for new panel variants entering European markets.
- MIMO Antennas:Multiple-input multiple-output configurations integrating 32T32R or 64T64R transceiver chains with beamforming ASICs. South Korean operators are accelerating procurement of massive MIMO variants as spectrum densification intensifies in Seoul metropolitan clusters. RF component integration complexity limits new entrants to this segment.
- Omnidirectional Antennas:Cylindrical radiating elements providing 360-degree horizontal pattern coverage for uniform cell fill.
- Remote Radio Units:Integrated RF transceiver modules with antenna interfaces, collapsing historical separation between radio head and passive antenna suppliers.
Leading the category by volume: Panel Antennas. Growing fastest: MIMO Antennas.
Technology:
Cost tiers separate legacy sub-6 GHz platforms from premium active antenna systems, with price differentials exceeding 4x per channel.
- Sub-6 GHz:TDD and FDD radio units operating below 6 GHz with established semiconductor supply chains using silicon LDMOS and gallium nitride power amplifiers. China's state-owned carriers anchor procurement volume under national broadband deployment mandates. FCC mid-band reallocation is expanding addressable hardware configurations for North American rollouts.
- Active Antenna Systems:Integrated platforms embedding baseband processing, RF transceivers, and radiating elements in single enclosures with embedded cooling. Urban network capacity constraints in Japan and South Korea are accelerating adoption in high-traffic metropolitan clusters. Gallium nitride substrate costs constrain margin expansion despite premium pricing.
- mmWave:Beam-steering arrays operating above 24 GHz with phased-array architectures for dense urban hotspots.
- Hybrid Systems:Multi-band platforms combining sub-6 GHz coverage with mmWave capacity layers in single mechanical packages.
Sub-6 GHz dominates installed base. Active Antenna Systems are expanding most quickly in procurement value.
Deployment Type:
Application environment dictates IP ratings, wind-load specifications, and zoning approval requirements across municipal jurisdictions.
- Outdoor:Macro cell towers and monopoles requiring IP67 environmental sealing and IEC wind-load certification for structural integrity. Rural coverage obligations in India and Indonesia are sustaining procurement volume for extended-range outdoor variants. TRAI spectrum allocation rounds create first-mover positioning for suppliers establishing local assembly partnerships.
- Small Cells:Low-power nodes with integrated antennas for street-level densification in urban canyons and indoor-outdoor transition zones. Japanese operators are accelerating procurement of consolidated small cell platforms that collapse radio head and antenna separation. Buyer concentration among tier-one mobile network operators extends payment terms for this segment.
- Indoor:Distributed antenna systems and indoor small cells for stadium, airport, and enterprise coverage.
- Roof-Top:Compact form-factor antennas for building-mounted deployments with landlord aesthetic constraints.
Outdoor installations lead deployment count. Small Cells are gaining share fastest as urban densification accelerates.
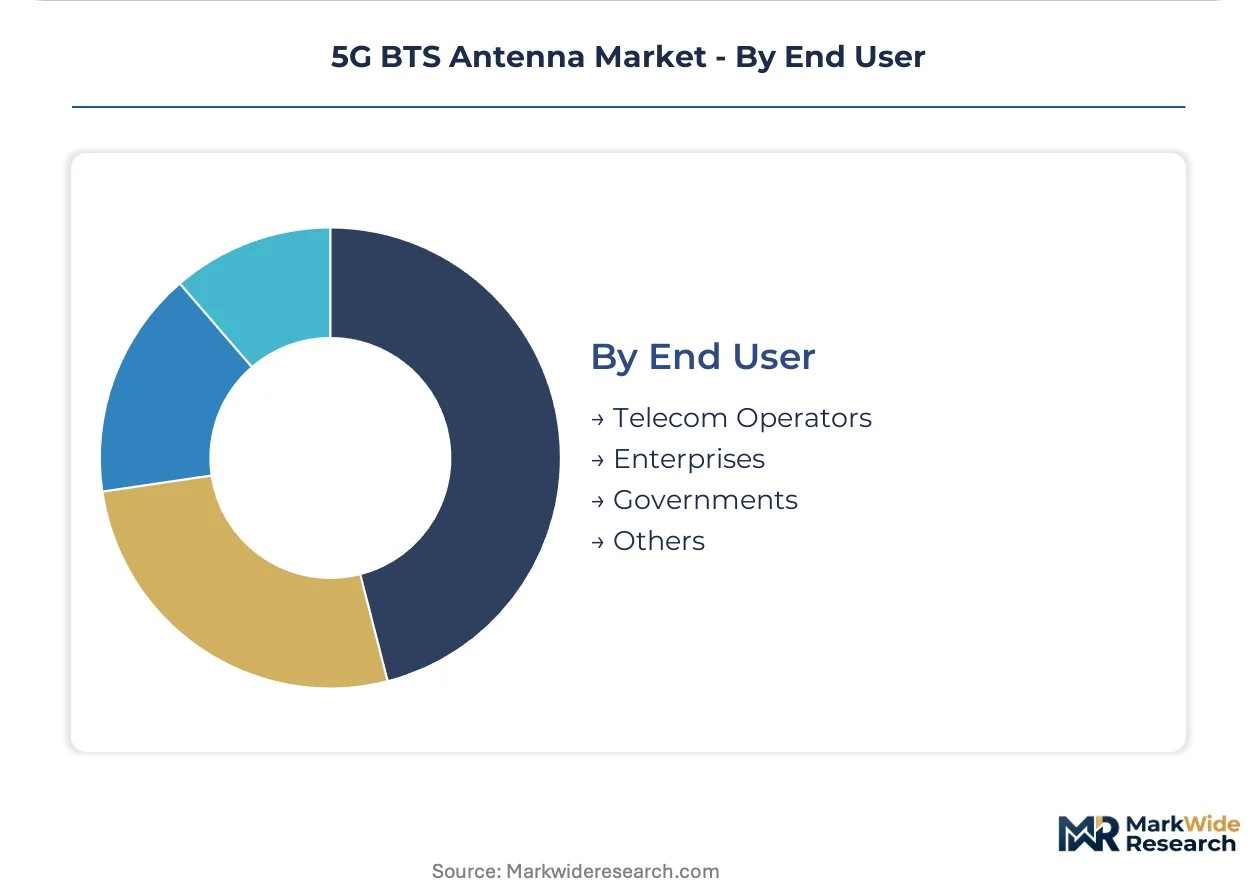
End User:
Customer type determines procurement scale, contract structure, and software maintenance bundling preferences.
- Telecom Operators:Tier-one mobile network operators with national spectrum licenses and multi-year capex cycles. Consolidated bidder pools in North America and Western Europe—fewer than five national carriers per market—harden procurement leverage and extend payment terms. Equipment vendors respond by unbundling hardware from software maintenance contracts.
- Enterprises:Manufacturing campuses, logistics hubs, and mining operations deploying private 5G networks with localized spectrum allocations. German industrial conglomerates are accelerating private network builds under BNetzA local licensing frameworks. Open RAN interoperability mandates favor multi-vendor integration for this customer segment.
- Governments:Defense, public safety, and transportation authorities with hardened security requirements.
- Others:Neutral host providers and venue owners offering infrastructure-as-a-service to multiple operators.
Telecom Operators command procurement volume. Enterprises are climbing the fastest as private network deployments multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian special economic zones concentrate 5G antenna manufacturing through tax-advantaged export processing regimes. Shenzhen's Qianhai zone anchors integrated supply chains for active antenna systems. Seoul's Magok district houses R&D clusters for massive MIMO architectures.
China
MIIT-mandated base station targets lock in multi-year procurement from China Mobile, China Telecom, and China Unicom. The ministry's national broadband strategy imposes aggressive installation schedules across all provincial jurisdictions. Yangtze River Delta manufacturing clusters in Suzhou and Hangzhou supply 64T64R beamforming arrays for domestic carrier rollouts.
United States
FCC mid-band spectrum reallocation between 3.45-3.98 GHz expands addressable hardware configurations for C-band deployments. The commission's auction framework prioritizes rapid infrastructure buildout across rural coverage obligations. Texas and California data center corridors drive demand for high-capacity small cell densification in Dallas-Fort Worth and Silicon Valley metro clusters.
South Korea
Seoul metropolitan capacity constraints accelerate active antenna system procurement from SK Telecom, KT, and LG Uplus. The Korea Communications Commission enforces electromagnetic exposure thresholds that extend certification timelines for new product introductions. Busan-Ulsan industrial zones host assembly partnerships for mmWave phased-array exports to Japanese operators.
Germany
BNetzA local licensing frameworks enable private 5G network builds for industrial conglomerates in manufacturing and logistics. The regulator's spectrum allocation for campus networks favors multi-vendor integration under Open RAN procurement specifications. Bavaria's automotive corridor around Munich and Ingolstadt deploys dedicated antenna systems for connected vehicle testing facilities.
India
TRAI 5G spectrum auctions create first-mover positioning for suppliers establishing local assembly partnerships. The Department of Telecommunications mandates domestic content requirements under production-linked incentive schemes. Maharashtra and Karnataka state governments offer land and power subsidies for antenna manufacturing parks in Pune and Bengaluru electronics clusters.
5G BTS Antenna Market Vendor Landscape
East Asian producers anchor one tier; European specialists hold differentiated positions in testing and certification services. The vendor base concentrates among integrated equipment suppliers with captive semiconductor supply chains and established regulatory laboratory access. Three archetypes dominate: vertically integrated telecom equipment giants, RF component specialists with antenna heritage, and contract manufacturers serving neutral host providers. Competitive moves center on Open RAN interoperability commitments and strategic partnerships with regional system integrators.
Among Nordic-heritage equipment vendors, Nokia Corporation and Ericsson exemplify the integrated platform archetype through end-to-end portfolio breadth. Huawei Technologies occupies a position as a scale-driven manufacturer with captive supply chain control. Amphenol Corporation represents the component-specialist tier with established connector and antenna product lines. These anchors illustrate how geographic origin and corporate structure shape strategic positioning across massive MIMO and active antenna system segments.
| Leading Market Players |
|---|
| Nokia Corporation |
| Amphenol Corporation |
| Huawei Technologies |
| Kathrein |
| ZTE Corporation |
| CommScope Holding Company |
| Comba Telecom Systems Holdings |
| PCTEL |
| Ericsson |
| Others |
Supply Flow & Price Mechanics
Captive semiconductor fabrication in East Asian foundries anchors both supply security and pricing leverage for active antenna system vendors. This integration pattern concentrates cost control among vertically integrated equipment suppliers while fragmenting margin pools for RF component specialists dependent on merchant wafer supply.
Pricing Analysis
Lead-time compression commands premium positioning in active antenna system procurement, with operators paying escalation clauses for sub-quarter delivery against standard six-month cycles. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified massive MIMO arrays from uncertified panel variants and surplus sub-6 GHz inventory. Price differentiation hinges on gallium nitride power amplifier grade and ETSI electromagnetic exposure certification tier. Cost compression in entry-level panel antennas is intensifying because Chinese state-owned carriers consolidate procurement volume under multi-year framework agreements. Enterprise private network buyers exhibit highest price sensitivity, while South Korean tier-one operators absorb premium positioning for Seoul metropolitan densification timelines.
Supply Chain Analysis
RF systems integration engineering scarcity in Shenzhen and Suzhou manufacturing clusters constrains capacity expansion for 64T64R beamforming array production. Supply concentration rests on China for printed circuit board fabrication, South Korea for gallium nitride epitaxial wafer supply, and Japan for high-frequency substrate materials. Raw material dependencies include ceramic dielectric substrates, copper-clad laminates, and precision machined aluminum enclosures. Single-source vulnerability in East Asian gallium nitride foundry capacity exposes European and North American equipment vendors to geopolitical disruption. Distribution runs through direct operator procurement teams for tier-one carriers, with systems integrators and neutral host providers handling mid-tier enterprise and small cell deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride substrate fabrication capacity acts as the binding constraint propping pricing power across high-frequency antenna tiers. Foundry slot allocation determines which equipment vendors capture procurement windows from operators accelerating urban densification schedules.
For Market Incumbents: Extend captive testing laboratory capacity in European and North American jurisdictions to compress rival certification timelines by six to nine months. Fortify beamforming ASIC design teams through targeted acquisition of fabless semiconductor specialists in South Korea and Taiwan. Emerging Open RAN interoperability mandates threaten hardware-software bundling advantages, making certification velocity the priority defensive lever. For New Entrants and Emerging Players: AI-driven beam management software layers offer entry positioning without massive MIMO hardware fabrication investment. Target Indian TRAI spectrum auction procurement cycles through local assembly partnerships in Maharashtra and Karnataka electronics clusters. German BNetzA private network licensing frameworks present the most penetrable regulatory entry point for enterprise-focused antenna configurations. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by tier-one equipment vendors seeking RF systems integration expertise. Long-term viability favors specialists with captive gallium nitride supply agreements and ETSI certification laboratory access. Watch FCC mid-band auction completion timelines as inflection indicator for North American addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | ETSI conformance testing unlocks procurement eligibility across European tier-one operator frameworks. |
| Gallium Nitride Supply Agreement | Captive wafer supply from South Korean foundries secures margin visibility for high-frequency variants. |
| Local Assembly Partnership | TRAI domestic content requirements favor suppliers with Pune and Bengaluru manufacturing presence. |
| AI Beam Management Platform | Machine learning inference integration enables recurring software revenue streams beyond hardware sales. |
| Massive MIMO R&D Expansion | Seoul Magok district engineering clusters accelerate 64T64R product development cycles. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with RF systems integration engineers, telecom operator procurement directors, semiconductor foundry planning officers, and ETSI certification laboratory managers combined with FCC equipment authorization databases, MIIT base station deployment statistics, and carrier capex disclosure filings. Bottom-up antenna shipment estimates triangulated against top-down infrastructure investment projections.
Data-stream reconciliation across operator procurement schedules, foundry capacity announcements, and spectrum auction timelines informed the analytical framework. Segmentation dimensions modeled include product architecture, frequency band, deployment environment, and end-user category across the projection horizon. CAGRs derived from fitted growth curves applied to infrastructure investment trajectories. Industry-specific forecast inputs encompass MIIT-mandated installation targets and FCC mid-band reallocation implementation pace.
Several conditions sit outside the modeled scope, including geopolitical trade restriction expansion, gallium nitride substrate price volatility beyond historical bands, and electromagnetic exposure threshold regulatory tightening. Forecasts reflect assumptions regarding carrier capex commitment continuity and foundry capacity expansion schedules. Material deviation in spectrum auction timing or Open RAN procurement mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecom Hardware
4G Equipment Market
Telecom Hardware
Laser Communications Terminals (Lcts) Market
Telecom Hardware
Telecom Electronic Manufacturing Services (EMS) Market
Telecom Hardware
Global Mobile Phone Loudspeaker Market
Telecom Hardware
Set-Top Box Market
Telecom Hardware
Communication Base Station Equipment Pcb Market
Telecom Hardware
Base Station Antenna Market
Telecom Hardware
LPWAN Market
Telecom Hardware
DWDM Transceiver Market
Telecom Hardware
Global Ultra Portable Internet Device Market
Telecom Hardware
Satellite Communication Terminal Market
Telecom Hardware
Repeaters Market
Telecom Hardware
Global LTE Modems Market
Telecom Hardware
Global Volte Market
Telecom Hardware
Land Mobile Radio System Market
Telecom Hardware
United States Set-Top Box Market