
 Global Gan RF Devices Market | 2026-2036
Global Gan RF Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gan RF Devices Market Analysis
Defense radar procurement is hardening as the dominant demand driver for GaN RF devices. Wolfspeed Inc. anchors wide-bandgap substrate supply through its vertically integrated SiC materials operation. Qorvo Inc. competes across the defense and telecom base station segments with foundry partnerships in the United States. Sumitomo Electric Device Innovations dominates high-frequency transistor supply for Japanese and export radar programs.
GaN RF devices are compound-semiconductor components built on gallium-nitride epitaxial layers, typically fabricated on silicon-carbide or silicon substrates, operating at frequencies from L-band through millimeter-wave with power densities exceeding those of legacy LDMOS or GaAs technologies. They serve as power amplification and switching elements in systems requiring high efficiency, thermal resilience, and broadband performance. GaN on SiC technology leads in military and satellite applications where thermal management and reliability standards are most stringent, while GaN on Si occupies expanding positions in cost-sensitive telecom infrastructure. Power amplifiers command the largest value share across product types, though switches gain traction in phased-array architectures.
The US Department of Defense's Trusted Foundry program, administered through DARPA and Defense Microelectronics Activity, shapes domestic sourcing requirements for strategic GaN components. EAR and ITAR export controls administered by the US Bureau of Industry and Security restrict technology transfer to designated countries, fragmenting supply chain access. REACH and RoHS frameworks in Europe impose material composition and substance restriction standards on device packaging and metallization. Stakeholders must monitor foundry qualification timelines against defense program schedules, as trusted supply constraints outpace design activity in critical radar and electronic warfare platforms.
Market Dynamics
The Trusted Foundry program administered by the US Defense Microelectronics Activity is reshaping competitive positioning by restricting domestic GaN sourcing to qualified facilities, creating supply constraints that outpace design activity in critical radar platforms.
Growth Catalysts
- ITAR export controls:Bureau of Industry and Security restrictions on strategic GaN components fragment supply chain access, forcing domestic capacity expansion in the United States and allied nations.
- Electronic warfare modernization:Pentagon procurement of next-generation jamming and countermeasure systems accelerates GaN-on-SiC adoption for thermal resilience under extreme operational loads.
- 5G base station deployment:Telecom infrastructure buildouts in South Korea and Japan drive volume demand for cost-optimized GaN-on-Si power amplifiers.
Market Restraints
- Silicon carbide substrate scarcity:Limited 6-inch SiC wafer supply concentrates in Wolfspeed's captive production, constraining foundry output for defense-qualified devices.
- REACH substance restrictions:ECHA frameworks on device packaging and metallization impose compliance costs that disadvantage European packaging houses against Asian competitors.
- LDMOS residual competitiveness:Legacy silicon LDMOS technology retains cost advantages in sub-3 GHz broadcast and industrial heating applications, delaying GaN displacement.
Strategic Opportunities
- India defense indigenization:PLI scheme incentives and domestic radar programs create demand for local GaN foundry partnerships with technology transfer from established suppliers.
- Satellite constellation proliferation:Low-earth orbit broadband terminals require millimeter-wave GaN switches and amplifiers for phased-array user terminals.
- GaN-SiC convergence with AI thermal management:Machine learning-driven adaptive biasing circuits enable dynamic power optimization in radar systems, opening new design service revenue streams.
Industry Challenges
- Compound semiconductor process engineering talent:Foundries in the United States and China compete for limited pools of MOCVD reactor operators and epitaxial growth specialists.
- Trusted facility qualification timelines:DARPA-administered certification cycles extend 18-36 months, misaligning with rapid defense program schedules and forcing design freezes.
- Heterogeneous integration complexity:Combining GaN power amplifiers with silicon CMOS control logic in multi-chip modules requires new thermal co-design methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gan RF Devices Market |
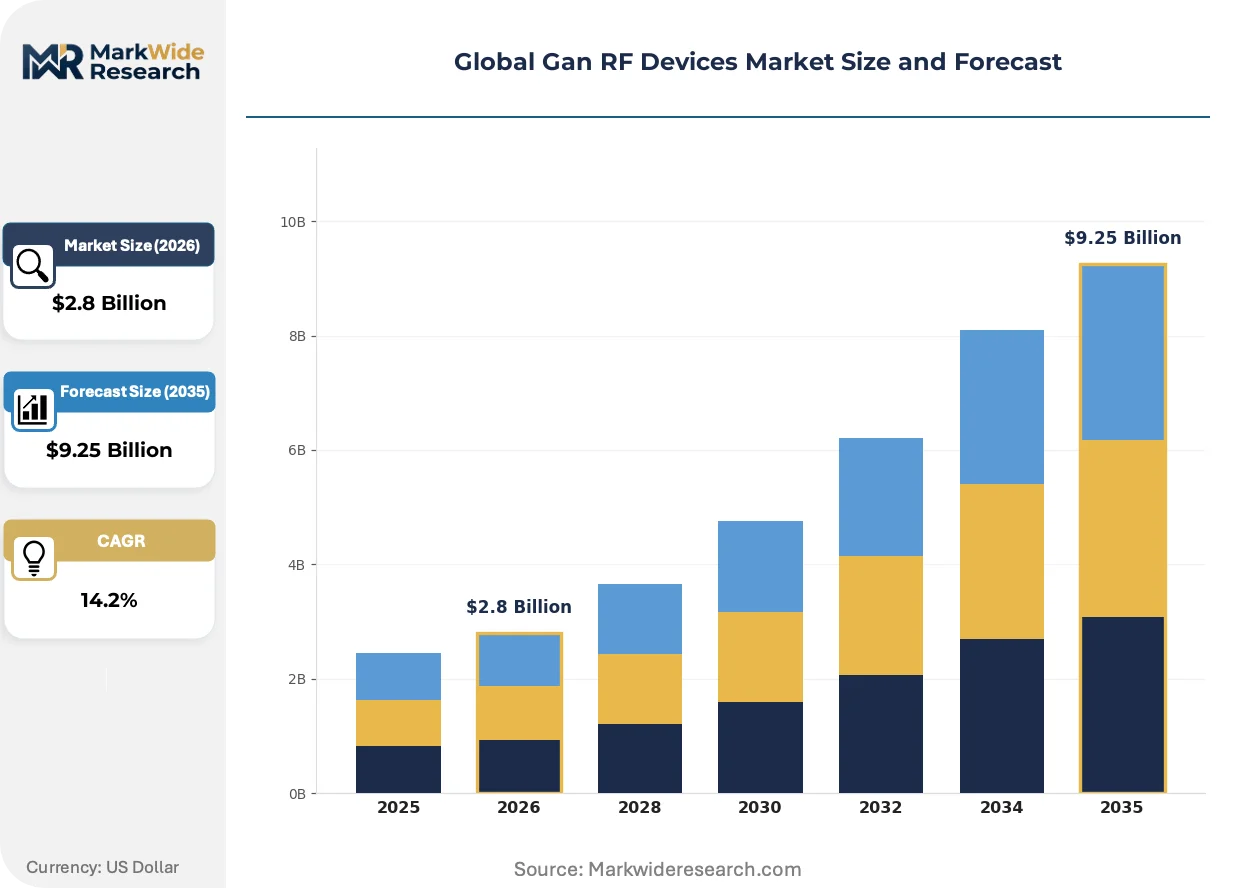
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Amplifiers, Switches, Transistors, Filters End User: Telecom, Aerospace, Automotive, Industrial Application: Wireless Communication, Radar Systems, Satellite Communication, Medical Devices Technology: GaN on Si, GaN on SiC, Hybrid Technology, Others |
| Companies Covered | Wolfspeed Inc., Qorvo Inc., MACOM Technology Solutions, Sumitomo Electric Device Innovations, NXP Semiconductors, Infineon Technologies AG, Analog Devices Inc., STMicroelectronics, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gan RF Devices Market Emerging Trajectories
Active electronically scanned arrays are compressing component count while elevating performance requirements, forcing device architectures toward higher integration and digital predistortion compatibility.
GaN-on-SiC technology is decentralizing radar system architectures by enabling solid-state transmit-receive modules to replace centralized tube-based transmitters. Pentagon procurement offices are mandating this transition for next-generation fighter and surface ship programs. The structural consequence is fragmenting supply contracts across module integrators rather than concentrating them with prime contractors.
REACH and RoHS frameworks in Europe are forcing metallization redesigns to eliminate restricted substances in device packaging and wire bonding. German and French packaging houses are accelerating gold-alternative interconnect development to maintain defense export eligibility. High-reliability satellite and military segments face the steepest compliance cost increases.
Defense procurement offices are consolidating vendor pools through long-term sole-source agreements for qualified GaN components. Prime contractors are responding by acquiring captive foundry capacity or exclusive supply agreements. This concentration is most visible in United States radar programs, where program offices prioritize supply security over unit cost competition.
Global Gan RF Devices Market Segmentation
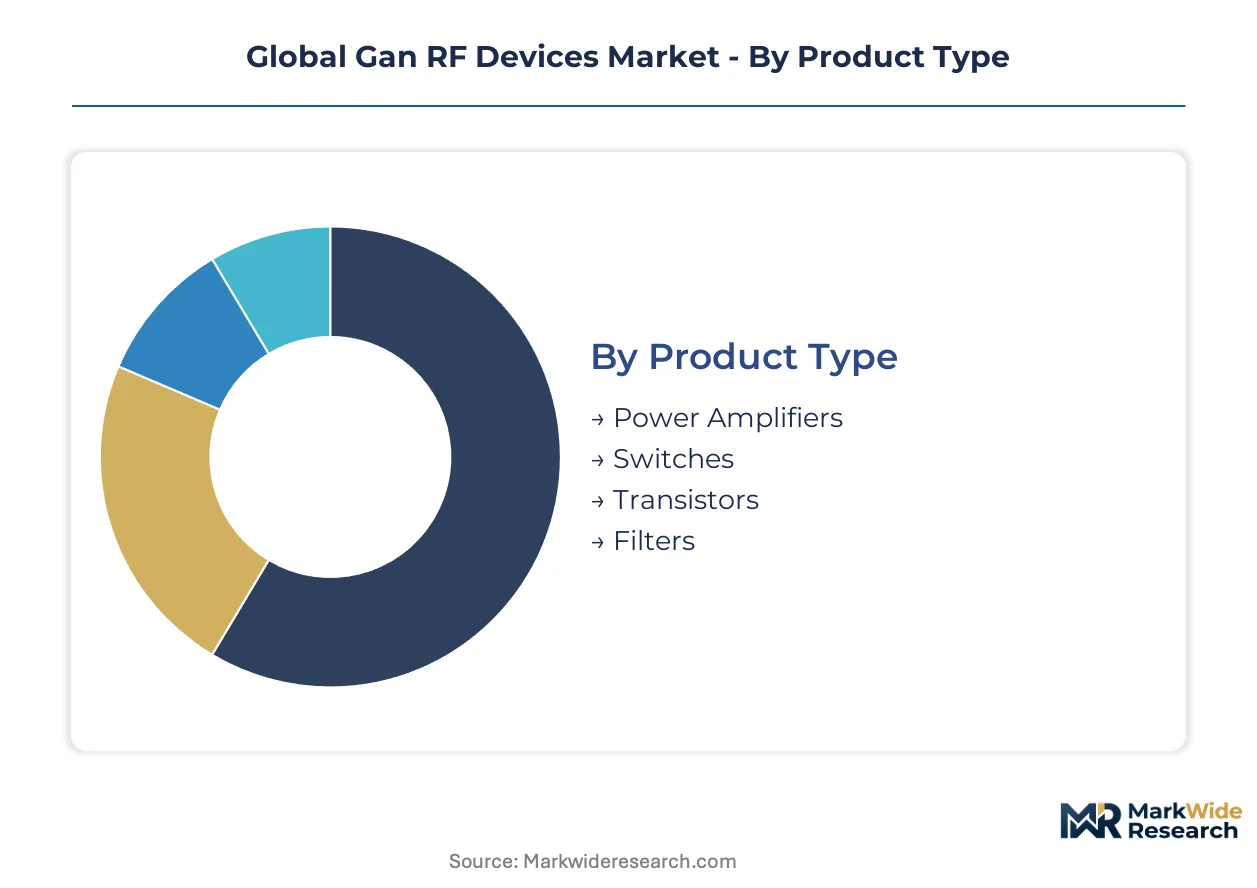
GaN RF device manufacturers configure production lines around substrate material and frequency specifications, with capital allocation decisions locking in multi-year competitive positioning. Segmentation clarity enables buyers to match thermal performance requirements against foundry qualification status and trusted supply availability.
Product Type:
Capital intensity varies sharply across product categories, with power amplifiers demanding the highest upfront epitaxial growth and thermal management investment.
- Power Amplifiers:These devices integrate multiple GaN HEMT cells with combining networks to deliver output power exceeding 100W in L-band through Ka-band configurations. Defense radar programs in the United States and Japan concentrate procurement for active electronically scanned array transmit-receive modules, where thermal resilience under pulsed operation is non-negotiable.
- Switches:Solid-state switches exploit GaN's high breakdown voltage and low on-resistance to achieve microsecond switching speeds with minimal insertion loss. Phased-array architectures in satellite communication terminals drive volume demand, particularly for low-earth orbit constellation ground stations requiring rapid beam steering.
- Transistors:Discrete GaN HEMT devices serve as building blocks for custom amplifier designs in research and specialized industrial heating applications.
- Filters:Surface acoustic wave and bulk acoustic wave filters incorporating GaN layers address high-power handling in base station front-ends.
Power amplifiers absorb the bulk of installed capacity; switches are expanding most quickly.
End User:
Margin structures diverge across customer categories, with defense procurement offering price stability against long qualification cycles while telecom volumes reward scale efficiency.
- Telecom:Base station OEMs in South Korea and Japan specify GaN-on-Si power amplifiers for sub-6 GHz massive MIMO deployments, prioritizing cost-per-watt over absolute thermal performance. 5G infrastructure buildouts sustain foundry utilization between defense program peaks.
- Aerospace:Satellite manufacturers and military prime contractors mandate GaN-on-SiC devices for space-qualified and airborne radar applications, with ITAR and EAR compliance requirements restricting supplier pools to trusted foundries in the United States and allied nations.
- Automotive:Radar module suppliers for advanced driver assistance systems evaluate GaN devices for 77-81 GHz long-range detection, though silicon-based alternatives currently dominate cost-sensitive volume segments.
- Industrial:RF plasma generation and industrial heating equipment manufacturers adopt GaN transistors for efficiency gains in continuous-wave operation, with European packaging houses facing REACH compliance cost disadvantages.
Aerospace commands premium pricing; telecom generates the steepest volume expansion trajectory.
Application:
Application-level demand correlates with frequency range and duty cycle requirements, determining substrate choice and foundry process node.
- Wireless Communication:Macro base stations and small cells deploy GaN power amplifiers across 700 MHz to 6 GHz bands, with South Korean operators accelerating 5G mid-band densification. Cost-optimized GaN-on-Si variants capture share from LDMOS in this frequency range.
- Radar Systems:Fighter aircraft, surface ships, and ground-based air defense platforms drive GaN-on-SiC adoption for X-band and S-band operation, with the US Department of Defense mandating solid-state replacement of tube-based transmitters.
- Satellite Communication:Geostationary and low-earth orbit terminals require millimeter-wave GaN components for Ka-band and Q-band uplinks, with user terminal manufacturers sourcing from Japanese and US suppliers.
- Medical Devices:MRI RF amplifiers and diathermy equipment utilize GaN devices for magnetic field immunity and precise power control, representing a niche but stable demand segment.
Radar systems anchor defense foundry commitment; satellite communication is climbing the fastest.
Technology:
Substrate selection dictates thermal performance ceiling and cost structure, with heterogeneous integration emerging as a third pathway.
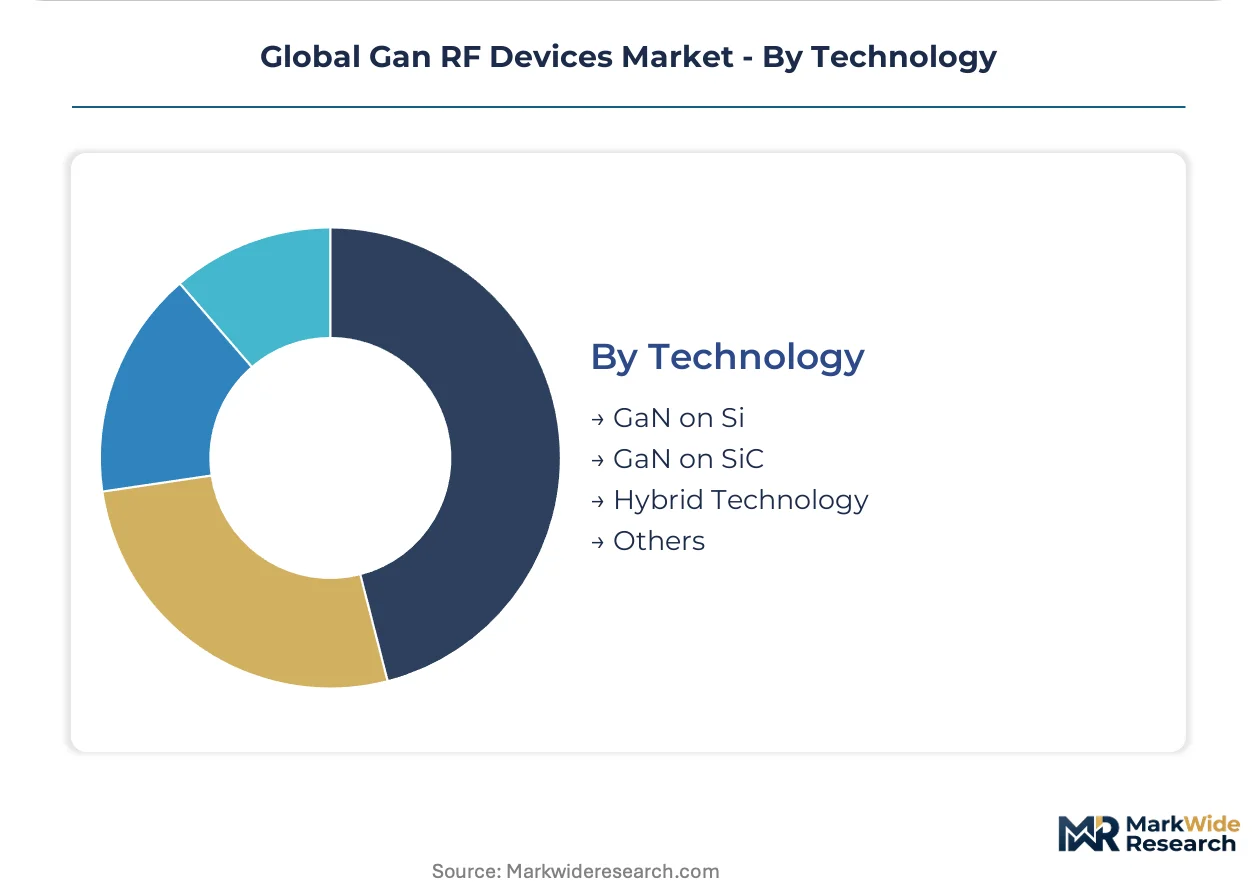
- GaN on SiC:Silicon carbide substrates enable the highest power density and junction temperature operation, essential for military radar and satellite payloads. Wolfspeed's captive 6-inch SiC wafer supply constrains industry-wide output for this premium tier.
- GaN on Si:Silicon substrates reduce material costs and leverage existing 8-inch CMOS foundry infrastructure, supporting telecom base station volumes where thermal requirements are less severe.
- Hybrid Technology:Multi-chip modules combining GaN power stages with silicon CMOS control and protection circuits address heterogeneous integration challenges in compact radar modules.
- Others:Emerging approaches including GaN on diamond and GaN on sapphire target specialized high-frequency or thermal management applications with limited current commercial traction.
GaN on SiC holds the dominant installed base; GaN on Si is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity concentrates in the United States and China, while defense procurement anchors consumption in Washington's military-industrial corridor and Tokyo's radar supply chains.
United States
The Department of Defense's Trusted Foundry program and electronic warfare modernization drive procurement of GaN-on-SiC devices for fighter radar and shipboard systems. DARPA-administered qualification cycles restrict sourcing to domestic facilities, fragmenting supply access. The Research Triangle in North Carolina hosts vertically integrated substrate production feeding defense-qualified foundries.
China
Domestic radar programs and 5G infrastructure buildouts sustain dual-use demand for GaN power amplifiers and switches. MIIT industrial policy directs state investment toward compound semiconductor foundry capacity in the Yangtze River Delta. Shanghai and Suzhou clusters concentrate MOCVD reactor installation for both military and civilian RF applications.
Japan
Self-Defense Force radar upgrades and satellite communication terminals anchor demand for high-frequency transistors. METI technology roadmaps prioritize wide-bandgap semiconductor supply chain security. Kansai industrial corridors around Osaka house precision epitaxial growth operations serving domestic and export defense programs.
Germany
Automotive radar module suppliers and industrial RF equipment manufacturers evaluate GaN devices for 77-81 GHz applications. REACH substance restrictions on packaging metallization impose compliance costs on domestic packaging houses. Bavaria's semiconductor clusters near Munich pursue gold-alternative interconnect development for defense export eligibility.
South Korea
Telecom operators accelerating 5G mid-band densification specify cost-optimized GaN-on-Si power amplifiers for massive MIMO deployments. National industrial strategy under the Ministry of Trade, Industry and Energy targets compound semiconductor self-sufficiency. Seoul Capital Area foundries leverage existing 8-inch CMOS infrastructure for RF device scaling.
Global Gan RF Devices Market Vendor Landscape
Top-tier vendors anchor defense-qualified foundry operations, while mid-scale specialists occupy telecom infrastructure segments. The vendor base stratifies across substrate-integrated pure-plays, diversified semiconductor conglomerates, and fabless design houses. Three archetypes dominate: captive substrate suppliers controlling silicon carbide wafer supply, defense-focused foundries with trusted facility status, and telecom-optimized volume producers. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with prime contractors acquiring captive foundry access to secure program eligibility.
Among substrate-integrated vendors, Wolfspeed Inc. and Sumitomo Electric Device Innovations occupy positions exemplifying vertical control over wide-bandgap material supply. Qorvo Inc. represents the defense-telecom hybrid archetype, bridging qualified foundry access with commercial base station volumes. These three entities anchor competitive positioning across the technology spectrum from GaN-on-SiC military applications to cost-optimized GaN-on-Si telecom deployment.
| Leading Market Players |
|---|
| Wolfspeed Inc. |
| Qorvo Inc. |
| MACOM Technology Solutions |
| Sumitomo Electric Device Innovations |
| NXP Semiconductors |
| Infineon Technologies AG |
| Analog Devices Inc. |
| STMicroelectronics |
| Mitsubishi Electric Corporation |
| Others |
Supply Flow & Price Mechanics
Pentagon procurement offices mandating Trusted Foundry qualification for defense radar programs force suppliers to absorb 18-36 month certification cycles, compressing margins on qualified GaN-on-SiC devices while spot-market GaN-on-Si amplifiers for telecom face steeper price competition.
Pricing Analysis
Short-lead-time premiums for ITAR-qualified GaN-on-SiC power amplifiers run 40-60% above standard delivery schedules as defense program offices accelerate radar platform timelines. Three-tier pricing structure across defense-qualified, industrial-grade, and commercial-telecom tiers reflects certification burden and substrate cost differentials. Cost compression in the GaN-on-Si telecom tier intensifies as South Korean and Chinese foundries scale 8-inch silicon substrate capacity. Telecom base station OEMs exhibit highest price sensitivity, while aerospace prime contractors prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from the US Department of Defense and Japanese Ministry of Defense compel prime contractors to qualify second-source foundries, fragmenting volume across domestic and allied-nation facilities. Wolfspeed's captive silicon carbide substrate production in North Carolina, Sumitomo Electric's epitaxial operations in Osaka, and emerging Chinese MOCVD clusters in the Yangtze River Delta anchor geographic supply concentration. MOCVD reactor equipment, high-purity gallium metal, and 6-inch SiC wafers constitute critical input dependencies. Single-source vulnerability in SiC substrate supply poses the dominant structural risk. Distribution runs through defense prime contractor procurement channels and telecom OEM direct sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Trusted Foundry program and ITAR export controls erect a cost-of-compliance barrier that favors incumbent suppliers with established DARPA certification cycles, locking out unqualified competitors from Pentagon radar and electronic warfare procurement streams.
For Market Incumbents: Deploy exclusive long-term supply agreements with defense prime contractors to lock out emerging foundry competitors before qualification timelines complete. Acquire captive silicon carbide substrate capacity or secure offtake contracts with Wolfspeed to defend against raw material scarcity threatening GaN-on-SiC output. Accelerate gold-alternative interconnect R&D to preempt REACH compliance cost disadvantages in European packaging operations. For New Entrants and Emerging Players: The 25-30% price-point gap between defense-qualified GaN-on-SiC amplifiers and commercial-telecom GaN-on-Si devices creates entry space for cost-optimized foundries serving South Korean and Indian 5G infrastructure buildouts. Target India's PLI-scheme subsidized domestic radar programs for technology transfer partnerships with established suppliers. Pursue satellite constellation ground station switch demand as a lower-certification-barrier entry vector. For Investors and Strategic Acquirers: The window for entry favors compound semiconductor foundries with existing Trusted Foundry qualification or clear pathways through DARPA-administered certification. Long-term viability hinges on substrate supply security and defense program backlog visibility. Watch for acceleration in low-earth orbit constellation terminal procurement as an inflection signal for millimeter-wave GaN switch demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Qualification Acceleration | DARPA-administered certification opens sole-source Pentagon procurement channels for qualified GaN-on-SiC suppliers. |
| Silicon Carbide Substrate Supply Security | Captive or contracted SiC wafer access insulates defense-qualified foundries from Wolfspeed supply constraints. |
| Gold-Alternative Interconnect Development | REACH-compliant packaging metallization preserves European defense export eligibility for German and French houses. |
| GaN-on-Si Cost Optimization Scale-Up | 8-inch CMOS foundry leveraging enables South Korean and Chinese suppliers to capture 5G base station volumes. |
| Satellite Terminal Phased-Array Partnership | Low-earth orbit constellation ground station demand drives millimeter-wave switch and amplifier procurement growth. |
Methodological Framework
Independent corroboration across defense procurement officers, compound semiconductor foundry executives, and telecom base station OEM procurement teams underwrites the qualitative findings in this analysis. Primary interviews with MOCVD reactor operators, epitaxial growth specialists, and radar platform systems engineers combined with secondary validation from SEC 10-K filings, Department of Defense budget justification documents, and METI technology roadmaps. Bottom-up triangulation across foundry capacity announcements and top-down reconciliation against defense program spending profiles anchored market sizing.
Rate-of-change decomposition across the analysis window separates volume growth from price trajectory and mix-shift effects. Segmentation dimensions modeled include substrate technology, frequency band, end-user category, and regional defense procurement cluster. CAGRs derive from fitted growth curves against historical defense electronics spending patterns and 5G infrastructure deployment schedules. Forecast inputs incorporate Trusted Foundry qualification pipeline visibility and silicon carbide substrate capacity expansion announcements.
Underlying measurement precision varies by segment; defense-qualified GaN-on-SiC power amplifiers carry tighter precision than emerging GaN-on-diamond experimental devices. Forecasts reflect assumptions on defense budget continuity and ITAR regime stability that material shifts in congressional appropriations or export control policy would revise. A model refresh is warranted upon material change in Pentagon electronic warfare modernization funding or Wolfspeed substrate capacity expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
High Reliability Oscillators Market
RF Components
Digital Radio Frequency Memory Market
RF Components
RF Transceiver Chip Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
Millimeter Wave Equipment Market
RF Components
Smart Antenna Market
RF Components
RF Mixers Market
RF Components
Multi-Mode Receiver Market
RF Components
Radio Frequency Components Market
RF Components
Multiband Booster Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
Flat Antenna Market
RF Components
Tunable Inductors Market
RF Components
RF Duplexer Market
RF Components
Global Inductors Market
RF Components
CATV RF Amplifiers Market