
 RF Gan Market | 2026-2036
RF Gan Market Size, Share, and Industry Trends Forecast 2026-2036
RF Gan Market Outlook
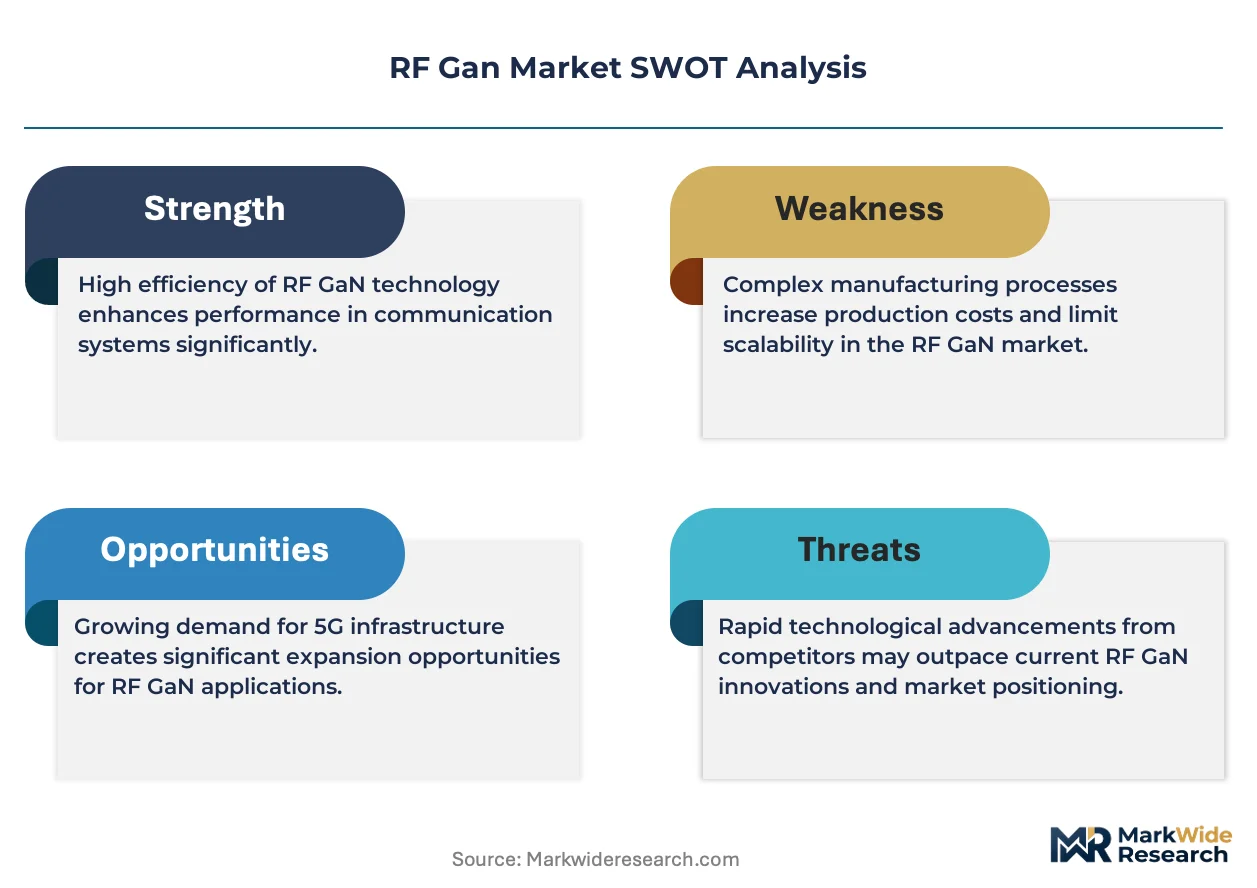
Gallium nitride is repositioning RF power economics away from legacy gallium arsenide substrates in high-frequency applications. Wolfspeed leverages captive SiC substrate capacity to anchor GaN-on-SiC supply chains for defense and telecom customers. Qorvo sustains broad technology leadership spanning GaN HEMT and integrated circuit architectures. MACOM Technology Solutions specializes in cost-optimized GaN-on-Silicon variants targeting commercial base station volume.
RF GaN denotes gallium nitride semiconductor devices engineered for radio frequency power amplification and signal processing, typically fabricated as high-electron-mobility transistors on silicon carbide or silicon substrates with operating frequencies extending through millimeter-wave bands. These devices deliver higher power density, improved thermal conductivity, and superior efficiency relative to silicon LDMOS or GaAs alternatives in base stations, radar systems, and satellite communications. GaN-on-SiC technology commands premium positioning in aerospace and military applications where thermal and reliability requirements are most stringent. Discrete power amplifier products retain the largest revenue share while integrated circuit formats gain traction in phased array architectures demanding tighter component integration. Telecommunications application revenue is expanding fastest as 5G macro and small cell deployments drive amplifier refresh cycles across OEM and telecommunications provider supply chains.
FCC spectrum auctions and NHTSA vehicular radar mandates in the United States shape product roadmaps by defining frequency allocation and power emission boundaries for commercial and defense equipment. ETSI and CE marking requirements in Europe enforce electromagnetic compatibility and safety standards that filter non-compliant GaN module suppliers from addressable markets. Military end users face additional ITAR and DoD acquisition regulations that constrain vendor eligibility and sustain premium pricing for qualified domestic sources. Stakeholders must weigh substrate technology bets against evolving spectrum policy and defense procurement localization trends that will determine which fabrication approaches capture the next wave of contract awards.
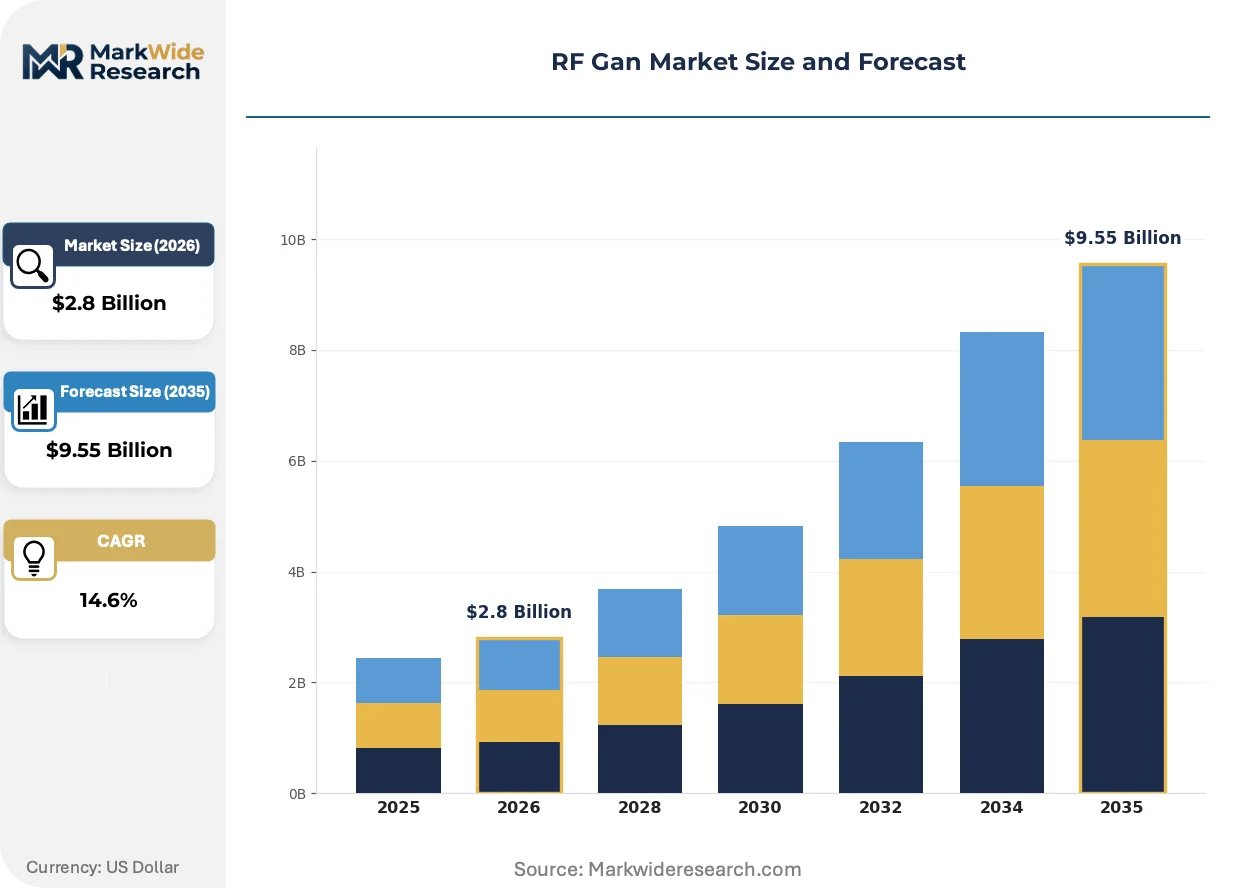
Market Dynamics
The transition from gallium arsenide to gallium nitride substrates is compressing amplifier refresh cycles across defense and telecommunications supply chains, forcing substrate technology bets that will determine contract awards for the next decade.
Growth Catalysts
- 5G base station deployment:Massive MIMO architectures in China and India are absorbing GaN HEMT output for macro and small cell power amplifiers, with domestic tower companies specifying GaN-on-SiC for thermal performance.
- FCC spectrum reallocation:C-band and mmWave auctions in the United States are mandating higher-frequency, higher-power amplifiers that silicon LDMOS cannot satisfy, accelerating GaN qualification timelines.
- Electronic warfare modernization:Pentagon procurement of GaN-on-SiC radar modules for next-generation jamming and surveillance systems is creating dedicated foundry capacity reserved for ITAR-qualified vendors.
Market Restraints
- Substrate supply concentration:High-purity SiC boule production concentrates among three qualified suppliers, creating allocation risk during defense procurement surges.
- Capital intensity of epitaxy:MOCVD reactor costs and cleanroom requirements exceed $50 million per production line, limiting new entrant participation.
- Gallium arsenide persistence:Lower-frequency legacy radar and satellite systems continue specifying GaAs MMICs where GaN performance advantages do not justify cost premiums.
Strategic Opportunities
- GaN-on-Silicon cost optimization:Commercial base station volume in Southeast Asia is creating demand for lower-cost GaN-on-Si variants that trade thermal performance for die size economics.
- Automotive radar integration:NHTSA vehicular radar mandates are opening 77-81 GHz frequency bands where GaN MMICs can displace silicon germanium in long-range detection modules.
- LEO satellite constellations:Phased array terminal demand from Starlink and competing networks is requiring GaN IC formats with tighter component integration than discrete amplifiers permit.
Industry Challenges
- Compound semiconductor talent scarcity:Foundry engineering expertise in GaN epitaxy and device physics concentrates among veterans of defense programs, constraining capacity expansion.
- ITAR compliance timelines:Defense qualification cycles for GaN-on-SiC modules extend 18-24 months, delaying revenue recognition for foundries serving dual-use markets.
- Legacy system integration friction:Existing radar and communications platforms require GaN amplifiers to match GaAs form factors and bias conditions, complicating drop-in replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Gan Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete, Integrated Circuit, Power Amplifier, Low Noise Amplifier Technology: GaN HEMT, GaN-on-Silicon, GaN-on-Sapphire, GaN-on-SiC Application: Telecommunications, Aerospace, Military, Industrial End User: OEMs, Telecommunications Providers, Defense Contractors, Broadcast Companies |
| Companies Covered | Wolfspeed, Qorvo, MACOM Technology Solutions, Sumitomo Electric Device Innovations, Infineon Technologies, NXP Semiconductors, Analog Devices, Ampleon, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Gan Market Strategic Shifts
RF GaN technology is compressing the traditional separation between discrete power amplification and integrated signal processing, enabling new phased array architectures that demand tighter functional integration.
GaN-on-SiC HEMT technology is unifying power amplification and low-noise reception functions in single-chip T/R modules for active electronically scanned arrays. Defense prime contractors in the United States and China are qualifying these monolithic ICs for fighter radar and naval fire control systems. This unification is collapsing the historical supplier tiering that separated power amplifier specialists from MMIC foundries, forcing component vendors to integrate or exit.
ETSI electromagnetic compatibility standards and CE marking requirements in Europe are tightening spurious emission limits for base station amplifiers above 6 GHz. Equipment OEMs must now pre-certify GaN module designs before network operator acceptance, extending product development timelines. Commercial telecommunications suppliers are responding by consolidating vendor lists to those with established European notified body relationships.
Network operators in South Korea and Japan are compressing amplifier procurement cycles from five-year replacement schedules to three-year refresh intervals as 5G-Advanced specifications demand wider bandwidth and improved efficiency. This behavioral shift is forcing GaN suppliers to hold finished goods inventory closer to regional hub warehouses rather than manufacturing-to-order from central foundries. The operational burden falls most heavily on vendors serving NTT DOCOMO and SK Telecom supply chains.
RF Gan Market Segmentation
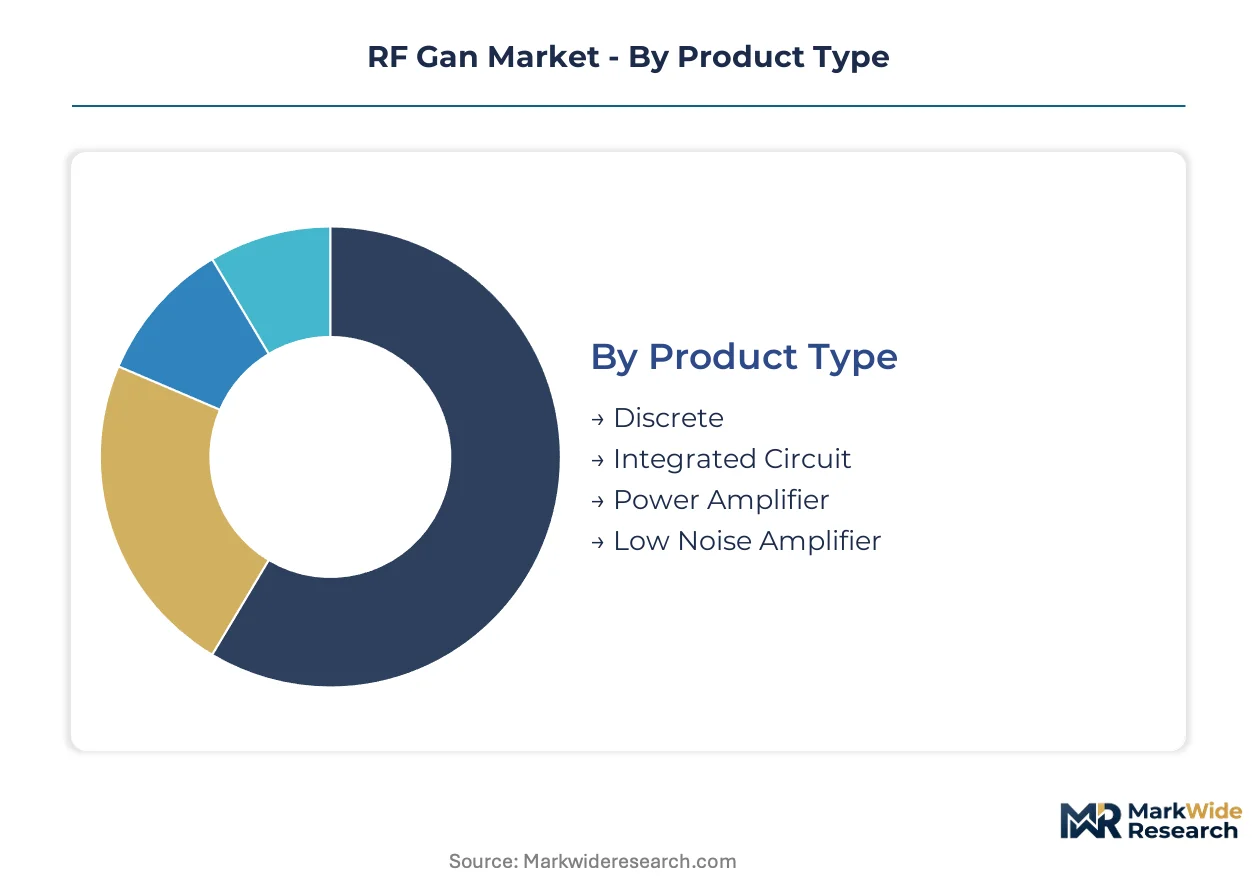
RF GaN procurement patterns diverge sharply between defense programs demanding radiation-hardened GaN-on-SiC and commercial base stations prioritizing cost-optimized GaN-on-Silicon. Segment boundaries are blurring as integrated circuit formats absorb discrete amplifier functions in phased array architectures.
Product Type:
Discrete power amplifiers command premium positioning in high-reliability defense applications, while integrated formats capture volume in telecommunications infrastructure refresh cycles.
- Discrete:Standalone transistor packages deliver maximum power density and thermal headroom for radar transmit chains. Pentagon procurement of fire control systems reserves foundry capacity for qualified discrete suppliers.
- Integrated Circuit:Monolithic GaN ICs combine amplification with phase-shifting and switching functions in single-die T/R modules. Starlink terminal demand is accelerating qualification of these compact formats for LEO ground stations.
- Power Amplifier:Discrete and module-level amplification products dominate base station radio heads across China Mobile and Verizon deployment schedules.
- Low Noise Amplifier:Reception-stage GaN devices exploit the material's low noise figure at millimeter-wave frequencies for satellite downlink chains.
Today's leader: Discrete. Tomorrow's challenger: Integrated Circuit.
Technology:
Substrate selection determines thermal performance ceilings and foundry capital requirements, with SiC variants anchoring aerospace margins and silicon alternatives unlocking commercial volume.
- GaN HEMT:High-electron-mobility transistor architecture delivers superior electron velocity and breakdown voltage compared to silicon LDMOS. 5G massive MIMO deployments in India and Southeast Asia are absorbing HEMT output for macro cell power stages.
- GaN-on-SiC:Silicon carbide substrates provide thermal conductivity exceeding 400 W/mK for radar and electronic warfare modules. ITAR-qualified foundries in the United States maintain dedicated epitaxy lines for defense prime contractors.
- GaN-on-Silicon:Leveraging existing 200mm silicon foundry infrastructure slashes substrate costs for commercial base station volume. Tower companies in Indonesia and Vietnam are specifying these variants for cost-constrained small cell rollouts.
- GaN-on-Sapphire:Transparent substrates suit optoelectronic integration and specialized RF-transparent packaging for space applications.
Defense procurement concentrates in GaN-on-SiC. Commercial volume is climbing fastest in GaN-on-Silicon.
Application:
Telecommunications infrastructure refresh cycles are compressing from five-year to three-year intervals, while military modernization programs sustain decade-long qualification timelines.
- Telecommunications:5G macro and small cell deployments drive amplifier replacement across NTT DOCOMO, SK Telecom, and China Mobile networks. FCC C-band reallocation is mandating GaN qualification for new frequency allocations.
- Aerospace:Satellite communications terminals and airborne radar systems demand hermetic packaging and radiation tolerance. Starlink and competing LEO constellations are requiring phased array formats with tighter integration than legacy platforms permitted.
- Military:Next-generation jamming, surveillance, and fire control systems specify GaN-on-SiC for thermal and reliability margins. Pentagon procurement is reserving domestic foundry capacity for ITAR-compliant supply chains.
- Industrial:RF heating, plasma generation, and medical equipment exploit GaN efficiency at ISM band frequencies.
Telecommunications claims current volume leadership. Military programs anchor margin concentration.
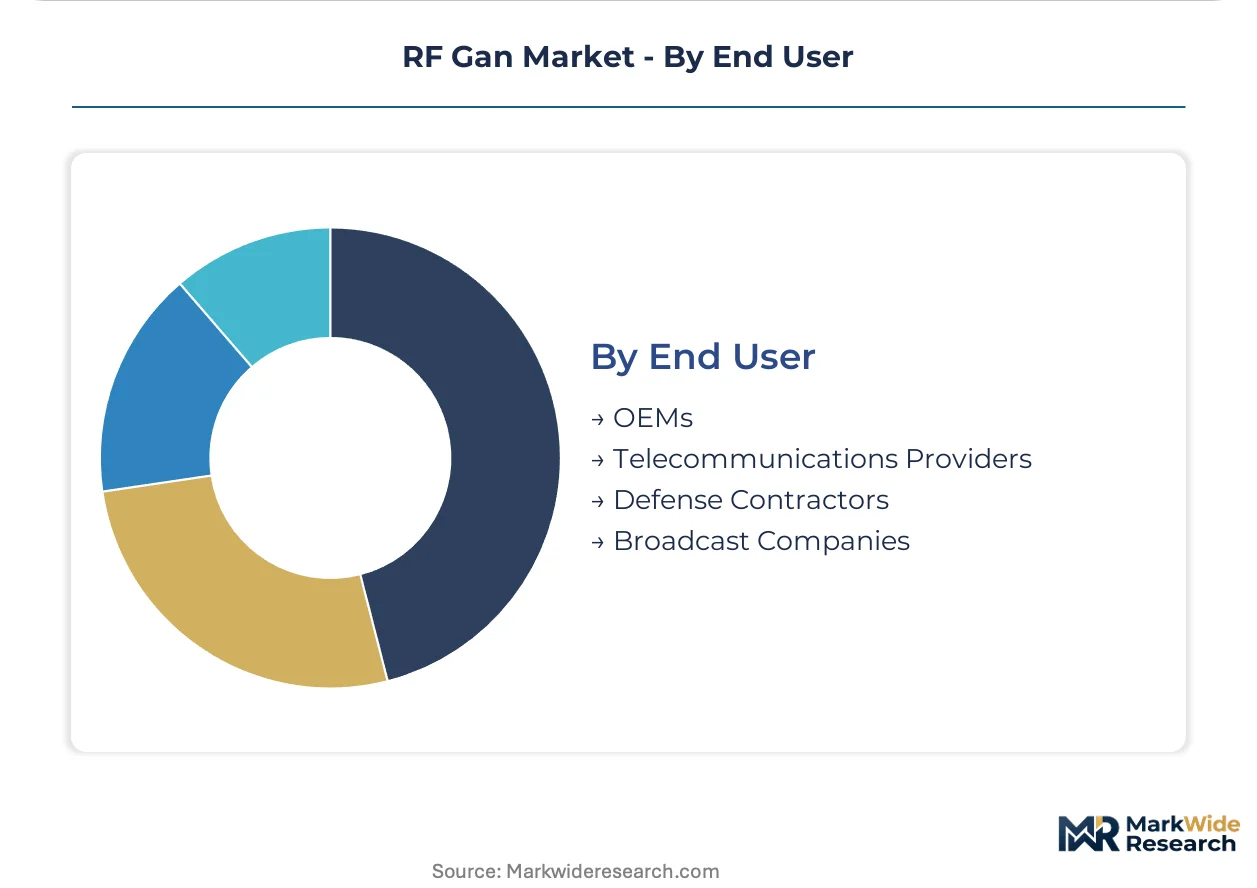
End User:
OEM procurement patterns split between integrated device manufacturers serving defense primes and merchant foundries supplying telecommunications equipment vendors.
- OEMs:Ericsson, Nokia, and Samsung Networks specify GaN modules for radio unit production, consolidating vendor lists to qualified suppliers with established European notified body relationships.
- Telecommunications Providers:China Tower, American Tower, and Cellnex are absorbing GaN HEMT output directly through equipment procurement frameworks that specify thermal performance thresholds.
- Defense Contractors:Lockheed Martin, Raytheon, and Northrop Grumman qualify GaN-on-SiC modules through 18-24 month defense acquisition cycles.
- Broadcast Companies:UHF and VHF transmitter operators specify GaN for efficiency improvements in terrestrial television and radio infrastructure.
Defense Contractors sustain premium pricing. Telecommunications Providers are expanding fastest in unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Jose-Santa Clara corridor anchors RF GaN foundry concentration, with Wolfspeed and MACOM Technology Solutions operating epitaxy facilities serving Pentagon procurement cycles. Defense prime contractors in the United States absorb premium GaN-on-SiC output for radar and electronic warfare modernization programs.
United States
Pentagon procurement of next-generation jamming systems and FCC C-band reallocation are dual demand drivers. ITAR qualification requirements filter vendor eligibility for defense contracts. The San Jose-Santa Clara corridor concentrates foundry capacity serving Lockheed Martin and Raytheon qualification timelines.
China
China Tower's massive MIMO deployment schedules and military modernization programs absorb domestic GaN HEMT production. MIIT spectrum allocation policies favor higher-frequency base station architectures. The Yangtze River Delta cluster houses epitaxy facilities supplying Huawei and ZTE radio unit production.
Germany
Automotive radar integration for NHTSA-equivalent EU mandates and industrial RF heating applications drive module demand. CE marking requirements under ETSI electromagnetic compatibility standards enforce spurious emission limits. The Munich-Stuttgart corridor concentrates Infineon Technologies fabrication serving Continental and Bosch automotive programs.
Japan
NTT DOCOMO's 5G-Advanced amplifier refresh cycles and satellite communications terminal production compress procurement timelines. METI technology roadmaps prioritize millimeter-wave device qualification. The Kanto region around Tokyo hosts Sumitomo Electric Device Innovations foundries serving domestic OEM supply chains.
South Korea
SK Telecom's small cell rollout schedules and Samsung Networks radio unit production specify GaN module performance thresholds. MFDS certification requirements align with international electromagnetic compatibility standards. The Seoul Capital Area concentrates packaging facilities supplying telecommunications equipment vendors.
RF Gan Market Competitive Environment
Global majors compete with regional champions across substrate technology and end-use specialization. The vendor base stratifies between ITAR-qualified defense suppliers and commercial telecommunications foundries. Three archetypes dominate: captive SiC substrate-integrated fabricators, merchant epitaxy specialists, and cost-optimized GaN-on-Silicon scale players. Capacity expansion and strategic partnerships constitute the dominant competitive moves as foundries secure substrate allocation and qualification timelines.
Within the defense-qualified tier, Wolfspeed anchors GaN-on-SiC supply chains through captive silicon carbide substrate production. Qorvo occupies a position spanning HEMT and integrated circuit architectures for dual-use markets. MACOM Technology Solutions exemplifies cost-optimized GaN-on-Silicon targeting commercial base station volume in Southeast Asia.
| Leading Market Players |
|---|
| Wolfspeed |
| Qorvo |
| MACOM Technology Solutions |
| Sumitomo Electric Device Innovations |
| Infineon Technologies |
| NXP Semiconductors |
| Analog Devices |
| Ampleon |
| STMicroelectronics |
| Others |
Value Chain & Pricing Dynamics
Defense prime contractors and sovereign wealth-backed semiconductor foundries anchor RF GaN supply chains through multi-year offtake agreements, translating substrate scarcity into disciplined pricing tiers that separate ITAR-qualified defense modules from commercial telecommunications volume.
Pricing Analysis
High-purity SiC substrate costs pass through directly to GaN-on-SiC module pricing, with three-tier pricing structure across ITAR-qualified defense, telecommunications infrastructure, and cost-optimized commercial tiers. Price differentiation hinges on thermal performance certification and volume scale, with China Tower procurement specifications demanding premium thermal thresholds. Pricing pressure stems from gallium arsenide persistence in legacy radar refresh cycles. Defense contractors exhibit lowest price sensitivity; Southeast Asian tower companies show highest.
Supply Chain Analysis
Dual-sourcing mandates from Pentagon procurement officers and NTT DOCOMO supply chain teams require qualification of at least two epitaxy suppliers per module category. Supply concentrates in the United States, China, and Japan, drawing from high-purity SiC boules, MOCVD reactor capacity, and qualified cleanroom infrastructure. Single-source vulnerability concentrates in SiC substrate production among three qualified suppliers. Distribution runs through defense prime contractor qualification pipelines and telecommunications OEM vendor consolidation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RF GaN functions as a stable compounder anchored by decade-long defense modernization cycles and successive telecommunications infrastructure refresh waves that sustain replacement demand regardless of macroeconomic softness.
For Market Incumbents: Anchor GaN-on-SiC supply security through backward integration into substrate production or captive long-term offtake agreements with qualified SiC boule suppliers. Defend against GaN-on-Silicon cost erosion by accelerating integrated circuit format qualification for phased array architectures that discrete specialists cannot replicate.
For New Entrants and Emerging Players: Capture commercial base station volume in Vietnam and Indonesia through GaN-on-Silicon variants that trade thermal performance for die size economics. Partner with established European notified bodies to compress CE marking timelines before network operator vendor consolidation closes.
For Investors and Strategic Acquirers: Valuations sit cheapest among merchant epitaxy specialists lacking captive substrate access but holding qualified defense program relationships. Long-term viability rests on substrate technology bets crystallizing across the analysis window. Monitor Pentagon procurement acceleration as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Substrate Integration | Wolfspeed's in-house boule production secures allocation priority during defense procurement surges. |
| GaN-on-Silicon Scale-Up | MACOM leverages existing 200mm foundry infrastructure to serve Indonesia tower deployment schedules. |
| Monolithic IC Qualification | Qorvo combines amplification with phase-shifting for Starlink terminal T/R module procurement. |
| European Notified Body Partnership | Sumitomo Electric compresses ETSI pre-certification timelines for NTT DOCOMO acceptance. |
| ITAR-Qualified Foundry Expansion | Domestic epitaxy lines reserve capacity for Lockheed Martin radar module qualification cycles. |
Study Parameters
Direct dialogue with defense procurement officers, telecommunications equipment vendor supply chain managers, compound semiconductor foundry engineering directors, and substrate materials specialists combined with secondary validation against SEC 10-K filings, FCC spectrum auction records, Pentagon budget justification documents, and ETSI electromagnetic compatibility standards. Bottom-up and top-down triangulation reconciled unit shipment estimates with value aggregation across substrate technology tiers.
Bottom-up modeling projected segment-level demand through the forecast period across product type, substrate technology, application, and end-user dimensions, with top-down cross-checks against national spectrum allocation policies and defense modernization budget trajectories. CAGRs derived from fitted growth curves incorporating 5G base station deployment schedules, radar platform refresh timelines, and satellite constellation terminal procurement waves.
Defense procurement acceleration, FCC spectrum reallocation delays, and SiC substrate supply disruption are the dominant revision risks to the outlook. Deviation in Pentagon qualification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Smartphone RF Power Amplifier Market
RF Components
Radio Frequency Front End Module Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Analog Phase Shifter Market
RF Components
Acoustic Wave Filters Market
RF Components
RF Tunable Filters Market
RF Components
SMD Resonator Market
RF Components
RFID Tags Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
RF Isolator Market
RF Components
Gaas RF Switch Market
RF Components
Multilayer Coupled Inductor Market
RF Components
Multiband Booster Market
RF Components
433MHz Active RFID Reader Market
RF Components
RF Semiconductor Market
RF Components
High-Volume RF Front-End Module Test Systems Market