
 RFID Tags Market | 2026-2036
RFID Tags Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Tags Market Analysis
East Asian semiconductor foundries is pivoting toward specialized RFID inlay production to serve escalating automotive and pharmaceutical serialization contracts. Impinj, Inc. leverages its RAIN RFID chip portfolio to dominate reader-to-tag interoperability standards. Avery Dennison Corporation anchors global adhesive antenna manufacturing through captive film-converting facilities across multiple continents. Zebra Technologies Corp. competes by bundling printers, readers, and enterprise software into vertically integrated workflow platforms.
RFID tags are wireless data carriers composed of a microchip bonded to an antenna substrate, typically operating between 125 kHz and 960 MHz depending on protocol, designed to store and transmit identifier data via electromagnetic coupling for automated object recognition. Passive tags draw operating energy from the interrogating reader field and dominate unit economics in high-volume supply chain deployments, while active tags carrying onboard power sources command premium positioning in cold-chain and real-time location systems. Ultra High Frequency technology leads volume shipments due to rapid bulk-reading capability in warehouse gate applications, whereas Near Field Communication tags concentrate margin pools in consumer-facing payment and authentication interfaces.
The Federal Communications Commission governs UHF spectrum allocation in the United States, directly constraining reader power thresholds and tag read-range performance in dense industrial environments. The European Commission's Radio Equipment Directive mandates CE marking and electromagnetic compatibility testing, elevating compliance costs for non-European suppliers seeking market access. China's Ministry of Industry and Information Technology administers GB standards for radio frequency identification in logistics, creating a dual-track certification burden for multinational vendors. Stakeholders must monitor spectrum reallocation proceedings and material substitution mandates as determinants of next-generation tag architecture and regional manufacturing placement.
Market Dynamics
The EU Green Deal's e-waste directives are forcing substrate material substitution across antenna manufacturing, while China's port digitization programs absorb passive tag volumes at unprecedented scale, compressing production cycles and reshaping supplier economics.
Growth Catalysts
- Smart logistics corridors:China's Ministry of Industry and Information Technology administers GB standards that mandate RFID tracking across bonded port zones, creating guaranteed demand pools for passive UHF inlays.
- REACH material compliance:The European Chemicals Agency's substance restrictions are accelerating recyclable antenna substrate adoption, opening premium positioning for compliant European suppliers.
- Pharmaceutical serialization:Cold-chain mandates from the FDA and EMA require item-level temperature logging, pulling active tag volumes into vaccine and biologics distribution networks.
Market Restraints
- Copper and aluminum volatility:Etched antenna production depends on thin-gauge metal foils whose commodity pricing swings compress inlay margins unpredictably.
- East Asian foundry concentration:Specialized RFID chip fabrication clusters in Taiwan and South Korea create single-source vulnerability for RAIN RFID silicon supply.
- Read-range physics limits:Passive UHF tags face inherent performance ceilings in liquid-rich or metal-dense environments, restricting deployment in certain automotive and food applications.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are drawing assembly capacity away from traditional Chinese hubs toward Gujarat and Tamil Nadu corridors.
- NFC payment authentication:Convergence between RAIN RFID infrastructure and Near Field Communication handsets is opening hybrid-tag architectures for retail loyalty programs.
- SAMR carbon labeling:China's State Administration for Market Regulation is piloting digital product passports that would mandate embedded RFID for lifecycle tracking.
Industry Challenges
- RF engineering talent scarcity:Antenna design optimization for specific substrate dielectrics requires specialized electromagnetic simulation expertise that outpaces university pipeline output.
- Dual-track certification burden:Multinational vendors must simultaneously satisfy FCC Part 15 rules, CE marking under the Radio Equipment Directive, and MIIT GB standards, extending product launch timelines.
- Legacy warehouse management integration:Enterprise resource planning systems at major retailers often lack native RAIN RFID middleware, forcing costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Tags Market |
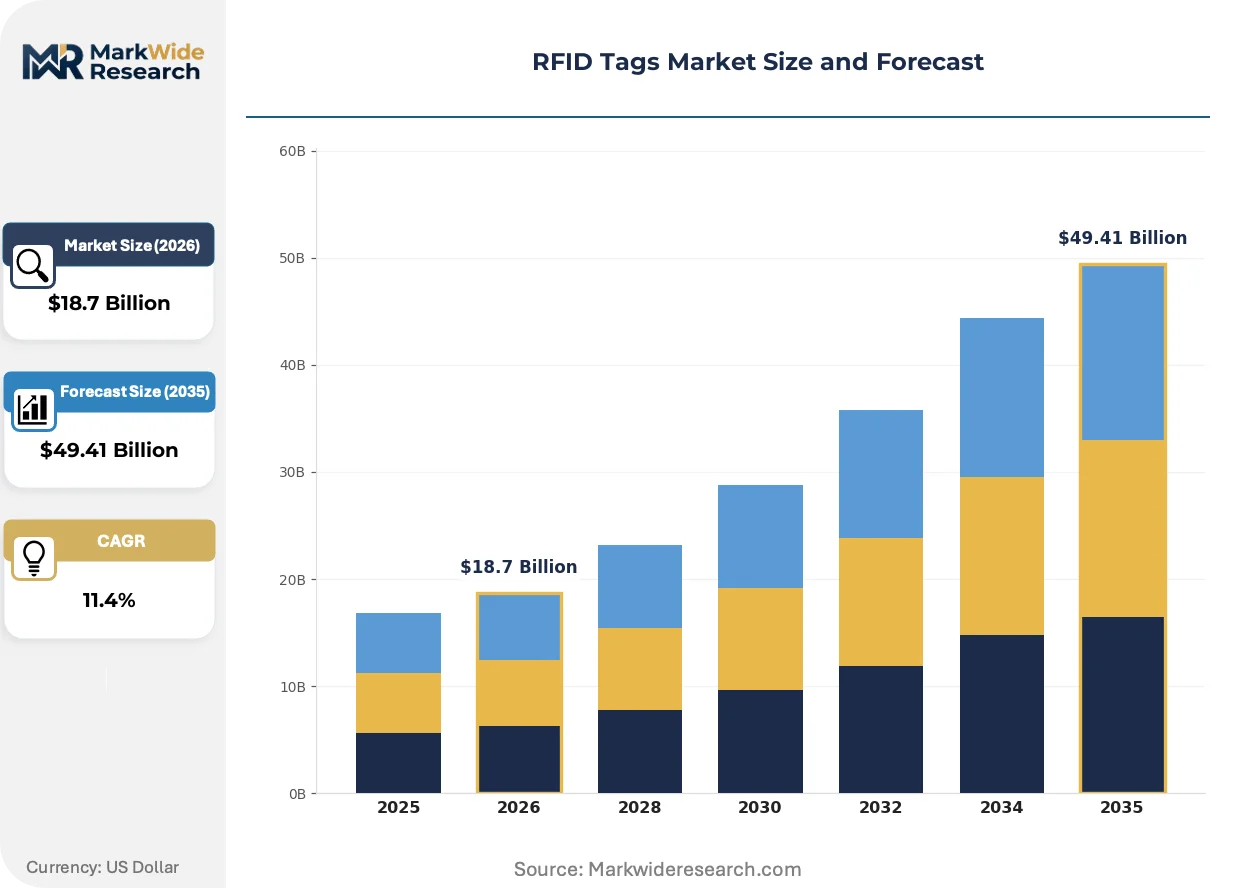
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Tags, Passive Tags, Semi-Passive Tags, NFC Tags Application: Inventory Management, Access Control, Supply Chain Management, Asset Tracking End User: Retail, Healthcare, Transportation, Manufacturing Technology: Low Frequency, High Frequency, Ultra High Frequency, Infrared |
| Companies Covered | Alien Technology, LLC, Honeywell International Inc., Zebra Technologies Corp., CAEN RFID S.r.l., Smartrac Technology, Avery Dennison Corporation, HID Global Corporation, GAO RFID Inc., Impinj, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Tags Market Emerging Trajectories
Chipless RFID encoding is compressing unit economics while printed electronics manufacturing is dissolving traditional silicon-antenna bonding constraints, enabling substrate-level integration that was previously technically infeasible.
Printed graphene antennas are decentralizing tag production geography by eliminating vacuum-metalization equipment requirements. Pharmaceutical contract packagers in Eastern Europe and Southeast Asia are piloting roll-to-roll conductive ink deposition for short-run serialization contracts. This distributed manufacturing model is compressing lead times for regional compliance batches while reducing exposure to transoceanic shipping volatility.
The EU AI Act's risk classification framework is mandating auditable supply chain provenance for high-risk AI system components. Electronics assemblers serving European medical device and automotive OEMs must now demonstrate component-level traceability from raw material to finished good. Passive RFID inlays with encrypted TID memory are becoming the default data carrier for this compliance architecture, displacing barcode-human readable hybrid labels in premium tier sourcing.
Retailer buying committees are consolidating tag procurement through managed print services contracts rather than discrete hardware purchases. Walmart and Carrefour are bundling printer-reader fleets with cloud-based inventory analytics, shifting supplier relationships from component transactions to multi-year platform commitments. This servitization pattern is most advanced in North American and Western European grocery and general merchandise verticals, where real-time stock visibility directly ties to online order fulfillment SLAs.
RFID Tags Market Segmentation
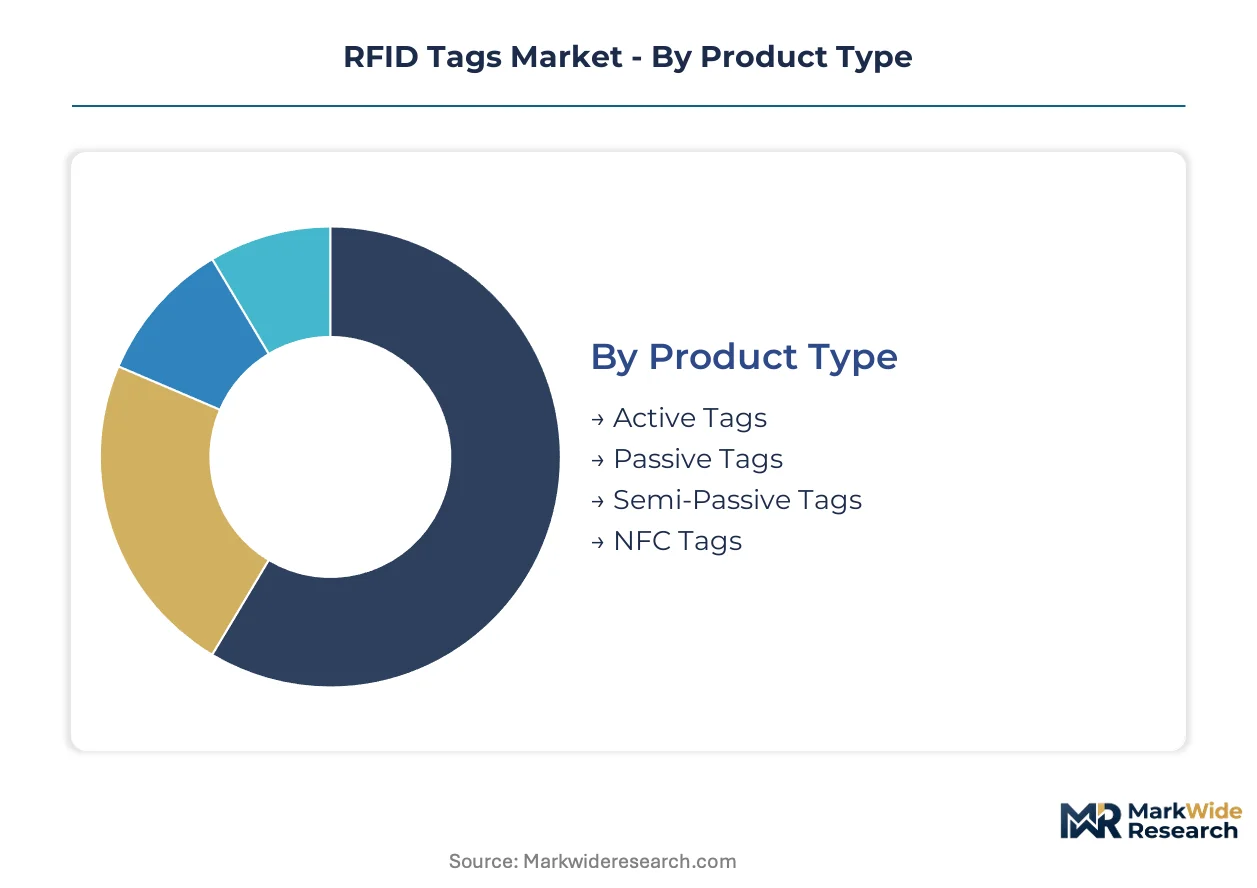
RFID tag architectures diverge sharply across power sourcing, frequency allocation, and integration depth. Procurement decisions hinge on read-range requirements, environmental constraints, and total cost of ownership across deployment lifecycles.
Product Type:
Customization versus standardization tensions peak in power architecture, where battery integration multiplies unit cost by orders of magnitude while unlocking functionality impossible for field-powered alternatives.
- Passive Tags:These field-powered inlays harvest interrogation energy through inductive or radiative coupling, eliminating onboard power sources. Chinese bonded port zones and smart logistics corridors absorb these units at unprecedented scale, compressing production cycles through high-volume, low-margin contracts.
- Active Tags:Battery-assisted designs embed coin cells or thin-film power sources to broadcast over extended ranges. Cold-chain mandates from FDA and EMA for vaccine distribution networks pull these volumes into pharmaceutical serialization, where temperature logging and real-time location justify premium positioning.
- Semi-Passive Tags:Hybrid architectures use batteries to power sensors and memory while relying on reader fields for communication. Battery-assisted sensor tags monitor shock and humidity in high-value automotive component shipments.
- NFC Tags:Near Field Communication variants operate at 13.56 MHz with standardized protocols for handset interoperability. Retail loyalty programs and payment authentication interfaces concentrate margin pools in consumer-facing deployments.
Leading the category by volume: Passive Tags. Growing fastest: Active Tags.
Application:
Cost tier stratification separates high-frequency, item-level deployments from infrastructure-heavy enterprise systems requiring middleware integration and change management.
- Inventory Management:Shelf-level stock visibility systems dominate retail adoption as merchants automate cycle counting and reduce out-of-stock events. Walmart and Carrefour bundle printer-reader fleets with cloud analytics, shifting procurement from discrete hardware to multi-year platform commitments.
- Supply Chain Management:Pallet and container-level tracking across multimodal networks demands bulk-reading capability at warehouse gates. Ultra High Frequency passive inlays enable rapid throughput in distribution centers serving e-commerce fulfillment SLAs.
- Asset Tracking:Returnable transport item monitoring and high-value equipment location systems deploy ruggedized tags for multi-year outdoor exposure. Construction and rental equipment fleets utilize these for utilization optimization.
- Access Control:Credential-based entry systems utilize High Frequency and Low Frequency cards for personnel authentication. Corporate campuses and healthcare facilities standardize on these for integrated security platforms.
Supply Chain Management commands the largest addressable spend. Asset Tracking climbs fastest as servitization models spread.
End User:
Customer type maturity varies dramatically, with retail and logistics operators treating RFID as table-stakes infrastructure while healthcare and manufacturing navigate regulatory complexity and legacy system constraints.
- Retail:Merchants automate stock visibility to bridge physical and digital inventory for omnichannel fulfillment. Real-time shelf availability directly ties to online order pickup promises and customer retention metrics.
- Healthcare:Hospitals track medical devices, pharmaceuticals, and patient specimens through sterile supply chains. FDA Unique Device Identification mandates and EMA serialization requirements embed compliance-driven demand.
- Transportation:Airlines, railways, and port operators tag baggage, rolling stock, and intermodal containers for flow optimization. China's Ministry of Industry and Information Technology GB standards mandate RFID across bonded logistics zones.
- Manufacturing:Automotive and electronics assemblers implement component-level traceability for quality recall and warranty management. EU AI Act risk classifications now mandate auditable provenance for high-risk AI system inputs.
Retail generates the highest tag consumption volume. Healthcare exhibits the steepest expansion trajectory as cold-chain regulations tighten.
Technology:
Frequency allocation directly determines read range, penetration capability, and regulatory jurisdiction, with UHF dominating warehouse economics while HF and LF retain defensible niches in liquid-rich or access-control environments.
- Ultra High Frequency:Operating between 860-960 MHz, these tags enable rapid bulk-reading at distances exceeding ten meters. FCC Part 15 power thresholds and ETSI EN 302 208 allocation frames constrain deployment density in North American and European industrial environments.
- High Frequency:13.56 MHz operation delivers reliable performance near liquids and metals, with standardized NFC protocols enabling handset interoperability. Payment terminals and access readers concentrate installed base in consumer and security applications.
- Low Frequency:125-134 kHz designs penetrate water and metal with minimal interference, serving animal identification and industrial automation where environmental harshness exceeds UHF tolerance.
- Infrared:Optical line-of-sight systems complement radio frequency in specialized short-range identification where electromagnetic interference must be eliminated. Cleanroom and explosive atmosphere deployments utilize these for intrinsic safety.
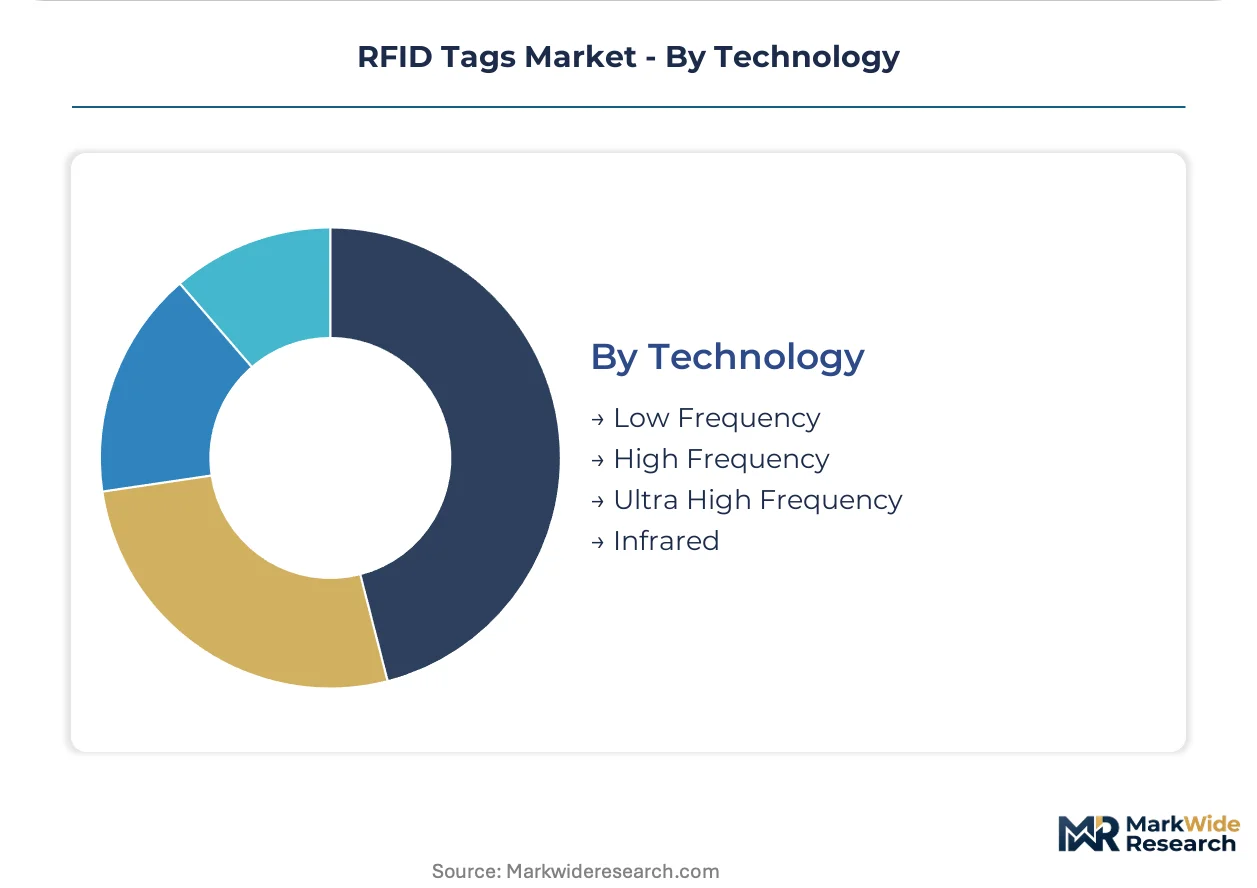
UHF leads technology shipments by unit volume. NFC-enabled HF applications gain share fastest as handset convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper foil mills in Germany's industrial heartland supply etched antenna substrates to European converters, while East Asian foundries in Taiwan and South Korea fabricate the RAIN RFID silicon that powers global tag volumes.
United States
Walmart's shelf-level inventory mandates drive passive UHF tag consumption across grocery and general merchandise networks. The FCC governs 860-960 MHz spectrum allocation through Part 15 rules, constraining reader power thresholds in dense warehouse environments. Silicon Valley software vendors and Boston-area RFID middleware specialists cluster around enterprise platform integration for retail fulfillment SLAs.
China
Smart logistics corridors and bonded port digitization programs absorb passive tag volumes at unprecedented scale. The Ministry of Industry and Information Technology administers GB standards mandating RFID tracking across Yangtze River Delta port zones. Shenzhen and Dongguan manufacturing clusters host roll-to-roll antenna converting lines serving domestic e-commerce fulfillment networks.
Germany
Automotive component traceability requirements pull encrypted TID memory tags into premium OEM supply chains. The EU Green Deal's e-waste directives pressure substrate manufacturers toward recyclable antenna materials under ECHA substance restrictions. Bavarian industrial automation vendors integrate RAIN RFID readers into factory floor systems for quality recall management.
India
Pharmaceutical contract packagers pilot serialization tags for export compliance to FDA and EMA markets. The Production-Linked Incentive scheme for electronics manufacturing draws assembly capacity toward Gujarat and Tamil Nadu corridors. Mumbai-based logistics operators deploy passive UHF infrastructure for domestic pharmaceutical cold-chain monitoring.
Japan
Precision component manufacturers implement item-level tracking for warranty management and counterfeit prevention. METI standards coordination ensures interoperability between domestic RFID systems and global RAIN protocols. Osaka-area electronics assemblers specialize in high-frequency tags for consumer payment authentication interfaces.
RFID Tags Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue chipless encoding and printed electronics architectures. The vendor base clusters around three archetypes: semiconductor foundries controlling RAIN RFID silicon supply, adhesive antenna converters with captive film facilities, and enterprise platform bundlers integrating hardware with cloud analytics. Capacity expansion and strategic partnerships dominate competitive moves, while technology licensing agreements accelerate geographic reach without capital-intensive facility builds.
Within the integrated platform tier, Zebra Technologies Corp. and Honeywell International Inc. exemplify the bundling strategy combining printers, readers, and enterprise software into vertically aligned workflow systems. Impinj, Inc. occupies a foundational position in reader-to-tag interoperability standards through its RAIN RFID chip portfolio. Avery Dennison Corporation anchors global adhesive antenna manufacturing with multi-continent film-converting operations.
| Leading Market Players |
|---|
| Alien Technology, LLC |
| Honeywell International Inc. |
| Zebra Technologies Corp. |
| CAEN RFID S.r.l. |
| Smartrac Technology |
| Avery Dennison Corporation |
| HID Global Corporation |
| GAO RFID Inc. |
| Impinj, Inc. |
| Others |
Supply Flow & Price Mechanics
RFID antenna design engineers concentrated in Taiwan and South Korea command compensation premiums that widen pricing spreads between commodity passive inlays and encrypted TID memory tags for automotive traceability. Labor-cost differentials between East Asian foundry clusters and European substrate converters directly stratify tier positioning across the value chain.
Pricing Analysis
Warranty and field-service bundling separate enterprise platform contracts from discrete hardware transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under FCC Part 15, CE marking, and MIIT GB standards. Cost compression in standard-tier passive UHF inlays intensifies because Chinese bonded port zones absorb volumes at unprecedented scale. Retail buying committees exhibit highest price sensitivity, while pharmaceutical contract packagers show lowest sensitivity due to cold-chain compliance mandates.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Dongguan, and Hamburg anchor hub-and-spoke patterns for antenna substrate and finished inlay movement. Manufacturing gravity centers on Taiwan, South Korea, and China for RAIN RFID silicon fabrication, with Germany and the United States hosting specialized converting for encrypted automotive tags. Copper and aluminum thin-gauge foils, PET film substrates, and conductive inks constitute critical input dependencies. Single-source vulnerability in East Asian foundry concentration threatens supply continuity. Distribution runs through bonded logistics zones and OEM direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU AI Act risk classifications and FDA Unique Device Identification mandates erect barrier-to-entry moats for certified suppliers.
For Market Incumbents: Extend platform bundling into multi-year managed print services contracts to lock out emerging chipless RFID entrants. Deepen backward integration into captive film-converting capacity across Gujarat and Tamil Nadu corridors to offset Chinese hub concentration. Secure MIIT GB pre-certification for next-generation antenna substrates before SAMR carbon labeling pilots expand.
For New Entrants and Emerging Players: Capture pharmaceutical serialization white space in Eastern European contract packaging where FDA and EMA cold-chain mandates outpace incumbent capacity. Target India's PLI scheme corridors for assembly cost advantages. Deploy roll-to-roll conductive ink deposition as the go-to-market angle for short-run regional compliance batches.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-tag architecture specialists given NFC-RAIN convergence in retail loyalty programs. Long-term viability favors vendors controlling reader-to-tag interoperability standards rather than commodity inlay converters. Watch for SAMR digital product passport mandate expansion as the inflection signal for lifecycle-tracking RFID demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Walmart and Carrefour bundle printer-reader fleets with cloud analytics, shifting procurement from transactions to multi-year commitments. |
| Backward Integration | Avery Dennison's captive film-converting facilities across multiple continents secure adhesive antenna substrate supply against copper volatility. |
| Geographic Expansion | India's PLI scheme draws assembly capacity toward Gujarat and Tamil Nadu corridors, reducing transoceanic shipping exposure. |
| Certification Investment | EU AI Act risk classifications mandate encrypted TID memory tags for auditable supply chain provenance in medical device inputs. |
| Strategic Partnership | Impinj leverages RAIN RFID chip portfolio dominance to anchor reader-to-tag interoperability standards across enterprise deployments. |
Methodological Framework
Trade publications, customs databases, and SEC filings formed the secondary backbone, supplemented by primary interviews with RFID antenna design engineers, pharmaceutical contract packaging executives, retail procurement directors, and logistics technology officers. Bottom-up tag volume estimates triangulated against top-down supply chain spend analysis across the projection horizon.
Historical trendline analysis anchored growth trajectory modeling across power architecture, frequency allocation, application depth, and end-user maturity dimensions. CAGRs derived from segment-level volume elasticities tied to named regulatory mandates and infrastructure deployment cycles. Forecast inputs incorporated MIIT GB standard adoption curves and EU Green Deal material substitution timelines.
The model holds under stable spectrum allocation and certification reciprocity; deviation in FCC Part 15 power threshold revisions or REACH substance restriction expansions would shift antenna substrate cost structures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency Front End Market
RF Components
EMI Microwave Absorber Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Analog Phase Shifter Market
RF Components
RF Acoustic Wave Filters Market
RF Components
High-Power Microwave Source Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
Acoustic Wave Filters Market
RF Components
Global RF Power Semiconductor Market
RF Components
Global RF Transceiver Market
RF Components
Toroid Inductor Market
RF Components
SMD Resonator Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
Multiband Booster Market
RF Components
5G Driver Amplifier Market
RF Components
High-Frequency RF Evaluation Board Market