

5G Driver Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
5G Driver Amplifier Market Insights
Telecommunication service providers is redrawing procurement priorities across the 5G driver amplifier value chain as network densification accelerates. Qorvo leverages its GaN technology leadership to dominate high-frequency infrastructure deployments. Skyworks Solutions anchors its position through backward integration into compound semiconductor fabrication. Broadcom competes by sustaining R&D intensity across CMOS and SiGe process nodes for integrated small-cell solutions.
A 5G driver amplifier is a radio frequency power amplification stage that boosts signal strength from milliwatt-level inputs to watt-level outputs, typically operating across sub-6 GHz and mmWave bands with linearity metrics measured by adjacent channel power ratio. Its primary purpose is to ensure sufficient transmit power at the antenna interface of base stations, small cells, and distributed antenna systems while preserving signal fidelity under wide bandwidth modulation schemes. Monolithic Microwave Integrated Circuits are capturing margin pools as OEMs prioritize footprint reduction in massive MIMO arrays. GaN technology leads in macro cell applications where thermal efficiency and power density requirements are most stringent. Small cell deployments represent the fastest-growing application segment as operators fill coverage gaps in dense urban corridors.
The FCC governs spectrum allocation and equipment authorization in the United States, directly shaping amplifier bandwidth requirements and emission compliance testing. ETSI and 3GPP standards in Europe define performance benchmarks that manufacturers must meet for network operator qualification, while China's MIIT sets domestic certification protocols that influence regional supply chain configurations. Stakeholders must monitor evolving spectrum band designations and efficiency mandates across these jurisdictions to align product roadmaps with procurement timelines.
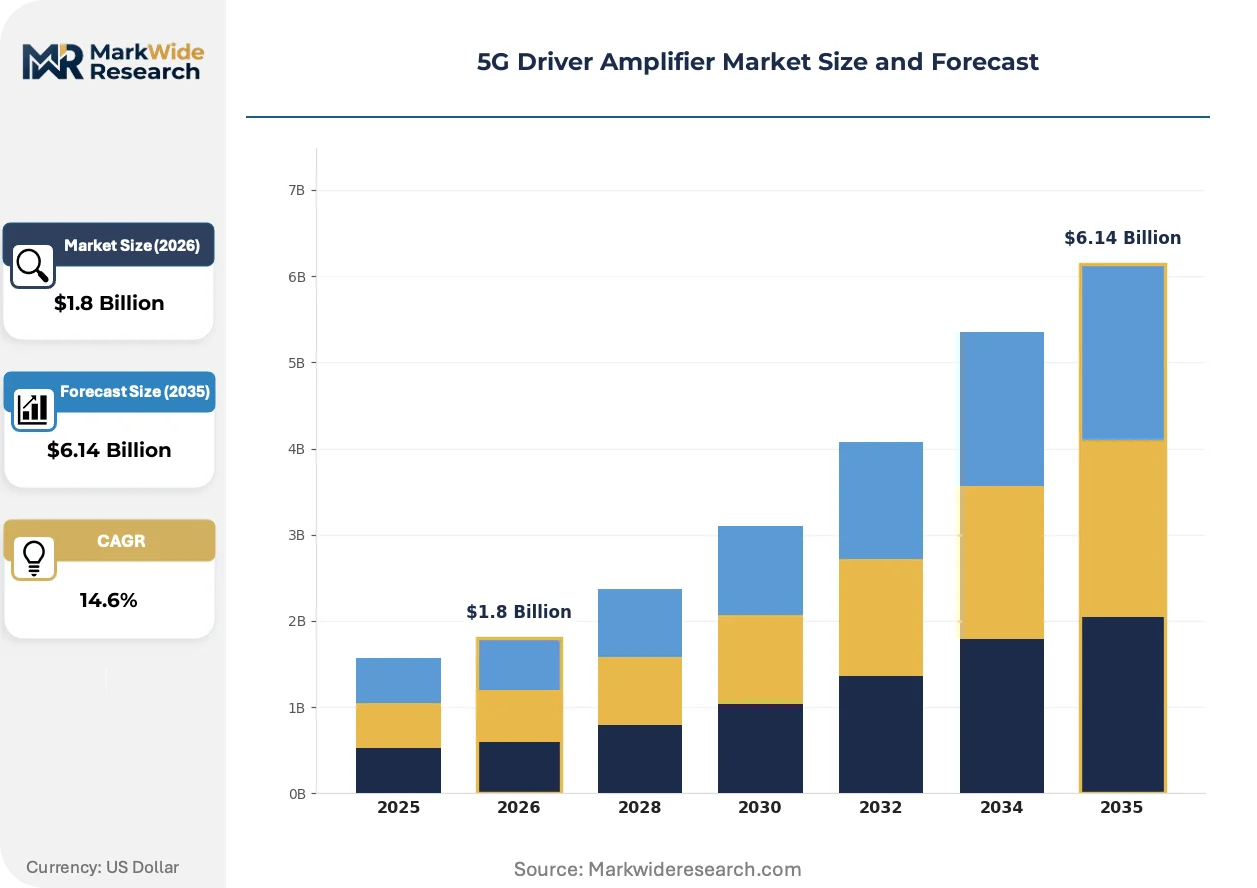
Market Dynamics
Network densification mandates from telecommunications regulators are compressing procurement cycles and forcing amplifier vendors to reconfigure product portfolios around thermal efficiency and spectral agility.
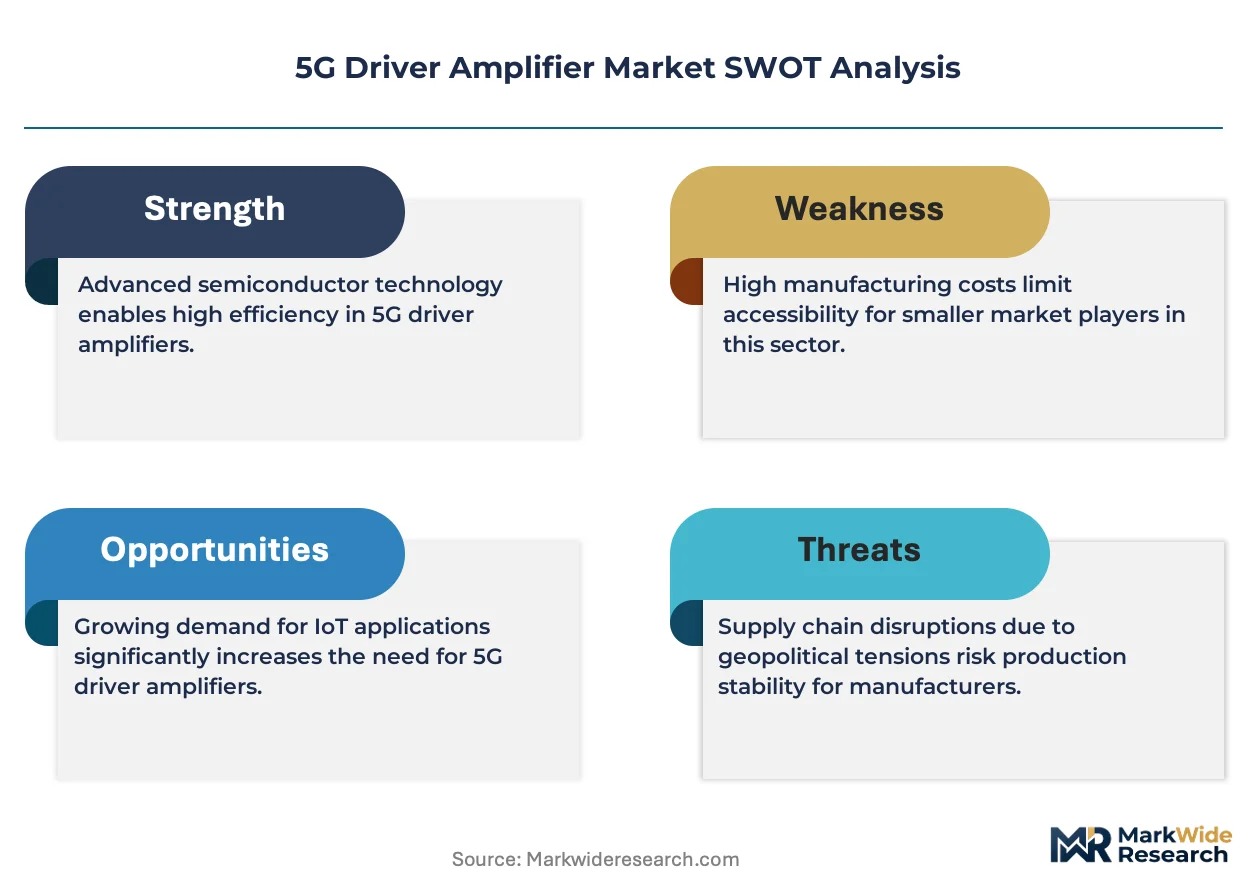
Growth Catalysts
- MIIT Base Station Targets:China's Ministry of Industry and Information Technology has set aggressive deployment quotas that pull procurement volumes for high-power GaN amplifiers into domestic supply chains.
- FCC Spectrum Reallocation:The Federal Communications Commission's auction framework in the United States is accelerating equipment refresh cycles as carriers acquire mid-band licenses.
- Millimeter Wave Backhaul:Fixed wireless access networks are adopting E-band driver stages for urban small-cell connectivity, expanding addressable unit demand.
Market Restraints
- GaN Substrate Concentration:Epitaxial wafer supply concentrates among Japanese and U.S. substrate specialists, creating input cost volatility for amplifier foundries.
- REACH Compliance Burden:The European Union's chemical registration requirements impose testing overhead on compound semiconductor packaging materials.
- SiGe Performance Ceiling:Silicon-germanium processes face thermal dissipation limits above 6 GHz that constrain their deployment in macro-cell transmit chains.
Strategic Opportunities
- Open RAN Disaggregation:Interface standardization by the O-RAN Alliance creates white space for specialized amplifier vendors to bypass incumbent integrated equipment suppliers.
- India Production-Linked Incentives:The PLI scheme for telecom equipment manufacturing is attracting assembly investments that localize final test and calibration operations.
- Integrated Doherty Architectures:Convergence of digital pre-distortion with analog Doherty combiners enables single-chip solutions for massive MIMO arrays.
Industry Challenges
- Compound Semiconductor Talent Scarcity:RF device physics expertise concentrates among aging specialists in GaN HEMT design, constraining R&D team scaling.
- Multi-Band Certification Timelines:3GPP conformance testing for carrier aggregation configurations extends qualification cycles by six to nine months.
- Legacy Infrastructure Integration:Retrofitting 4G remote radio heads with 5G-capable driver stages requires thermal and mechanical redesign of existing enclosures.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Driver Amplifier Market Trends and Innovations
Semiconductor process diversification and procurement model restructuring are reconfiguring competitive positioning across frequency bands and deployment scales.
GaN-on-SiC technology is fragmenting the high-power amplifier landscape by enabling output densities above 8 W/mm at 28 GHz. Base station OEMs are adopting these devices for macro-cell massive MIMO implementations where thermal budgets are constrained. The technology is fragmenting procurement patterns as carriers bifurcate supplier bases between GaN specialists and legacy LDMOS incumbents.
The FCC's 3.45 GHz auction and subsequent band clearing mandates are compressing deployment timelines for C-band infrastructure. Equipment vendors must now certify amplifiers across contiguous 280 MHz blocks rather than fragmented 40 MHz assignments. Macro-cell deployments in the United States are absorbing the bulk of compliance engineering resources, delaying small-cell product releases by two quarters.
Telecom operators are consolidating vendor panels and demanding multi-year service agreements that bundle hardware with predictive maintenance analytics. Distributor relationships are thinning as direct procurement contracts with compound semiconductor foundries proliferate. This consolidation is most visible in China, where state-owned carriers have reduced qualified amplifier suppliers from twelve to four across their 2024-2026 deployment windows.
5G Driver Amplifier Market Segmentation
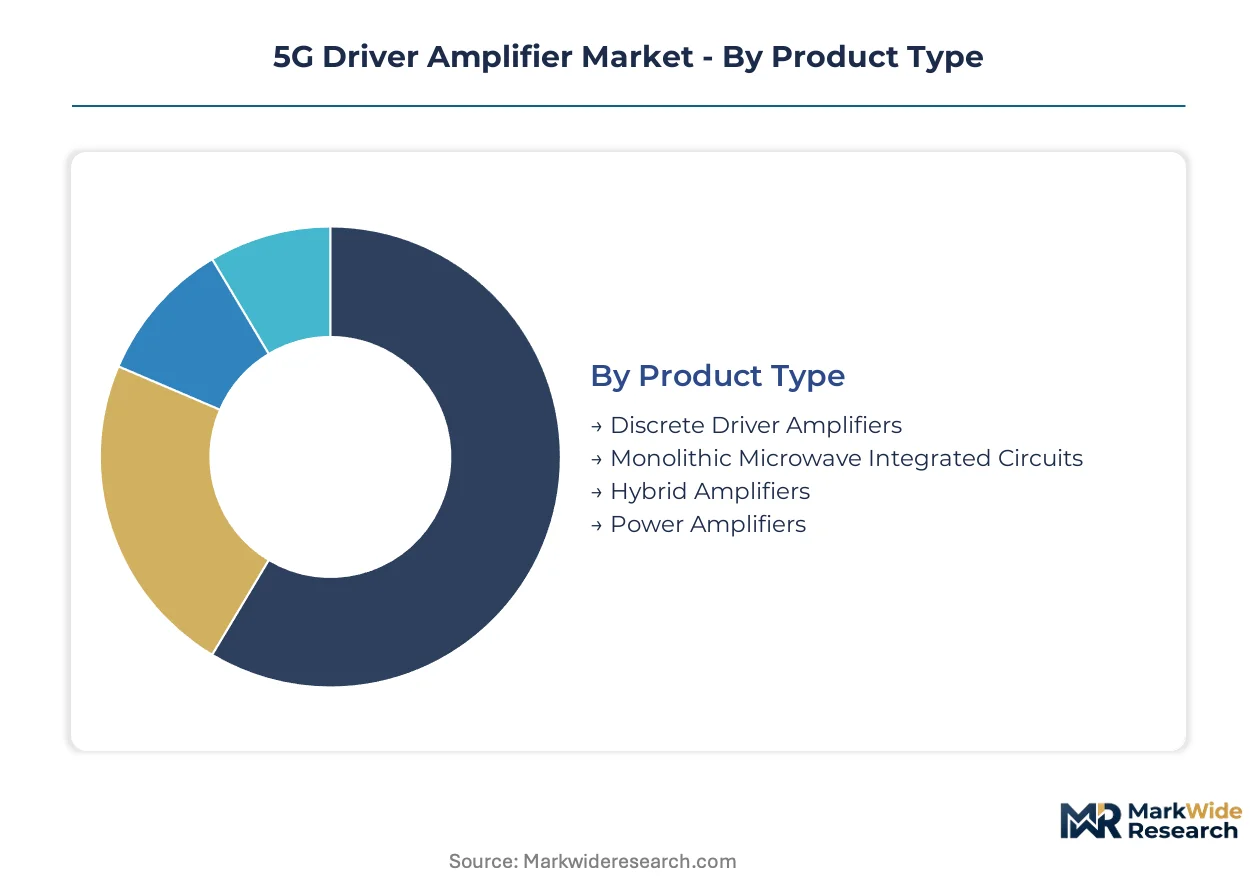
Amplifier procurement patterns diverge sharply across product architectures and frequency requirements. Network densification timelines and thermal efficiency mandates are forcing buyers to rebalance portfolios across discrete and integrated solutions.
Product Type:
Domestic supply chains in China and India favor locally assembled discrete and hybrid formats, while export-led demand from North American and European carriers concentrates in MMIC solutions for massive MIMO density.
- Discrete Driver Amplifiers:Standalone transistor packages with external matching networks enable custom tuning across non-contiguous spectrum blocks. Procurement concentrates among infrastructure equipment manufacturers serving legacy macro-cell retrofits where design flexibility outweighs integration density.
- Monolithic Microwave Integrated Circuits:Fully integrated RF front-ends combine amplification, switching, and filtering on single die. Demand clusters in China's state-owned carrier base station programs where footprint reduction in 64T64R arrays drives volume commitments to domestic foundries.
- Hybrid Amplifiers:Multi-chip modules balance performance with thermal management.
- Power Amplifiers:Final-stage devices deliver watt-level outputs for macro-cell transmit chains.
Monolithic Microwave Integrated Circuits commands the established base. The steepest expansion runs through Discrete Driver Amplifiers.
Technology:
Cost tiers separate premium compound semiconductor processes from silicon-based alternatives, with GaN and GaAs commanding 3-4x unit premiums over CMOS and SiGe variants.
- GaN:Gallium nitride HEMT devices achieve power-added efficiencies above 60% at 28 GHz with 8 W/mm output density. Deployment concentrates in United States C-band macro cells where FCC-mandated timelines compress qualification cycles for thermal-efficient solutions.
- GaAs:Gallium arsenide pHEMT technology dominates sub-6 GHz small-cell applications with established reliability records. Infrastructure equipment manufacturers in South Korea and Japan specify these devices for urban densification projects balancing performance against mature supply chains.
- CMOS:Silicon CMOS enables lowest-cost integration for integrated transceivers.
- SiGe:Silicon-germanium BiCMOS serves sub-6 GHz massive MIMO where thermal ceilings constrain.
- LDMOS:Laterally-diffused metal oxide semiconductor retains share in sub-3 GHz legacy infrastructure.
LDMOS retains the installed base. The steepest climb belongs to GaN.
Application:
Volume concentration tracks deployment scale, with macro cells absorbing high-unit-value GaN amplifiers while small cells drive aggregate shipment counts.
- Small Cells:Low-power distributed nodes require 100-500 mW driver stages with tight integration. China's MIIT urban densification mandates in tier-2 cities are pulling procurement volumes for compact modules with integrated digital pre-distortion.
- Macro Cells:High-power base stations demand 10-100 W driver stages with linearity metrics measured by adjacent channel power ratio. United States carriers responding to FCC 3.45 GHz clearing deadlines are absorbing the bulk of high-frequency GaN-on-SiC capacity.
- Distributed Antenna Systems:In-building coverage solutions require multi-band linearity.
- Repeaters:Signal regeneration equipment serves coverage extension in rural corridors.
Macro Cells anchor revenue concentration. Small Cells is gaining share fastest.
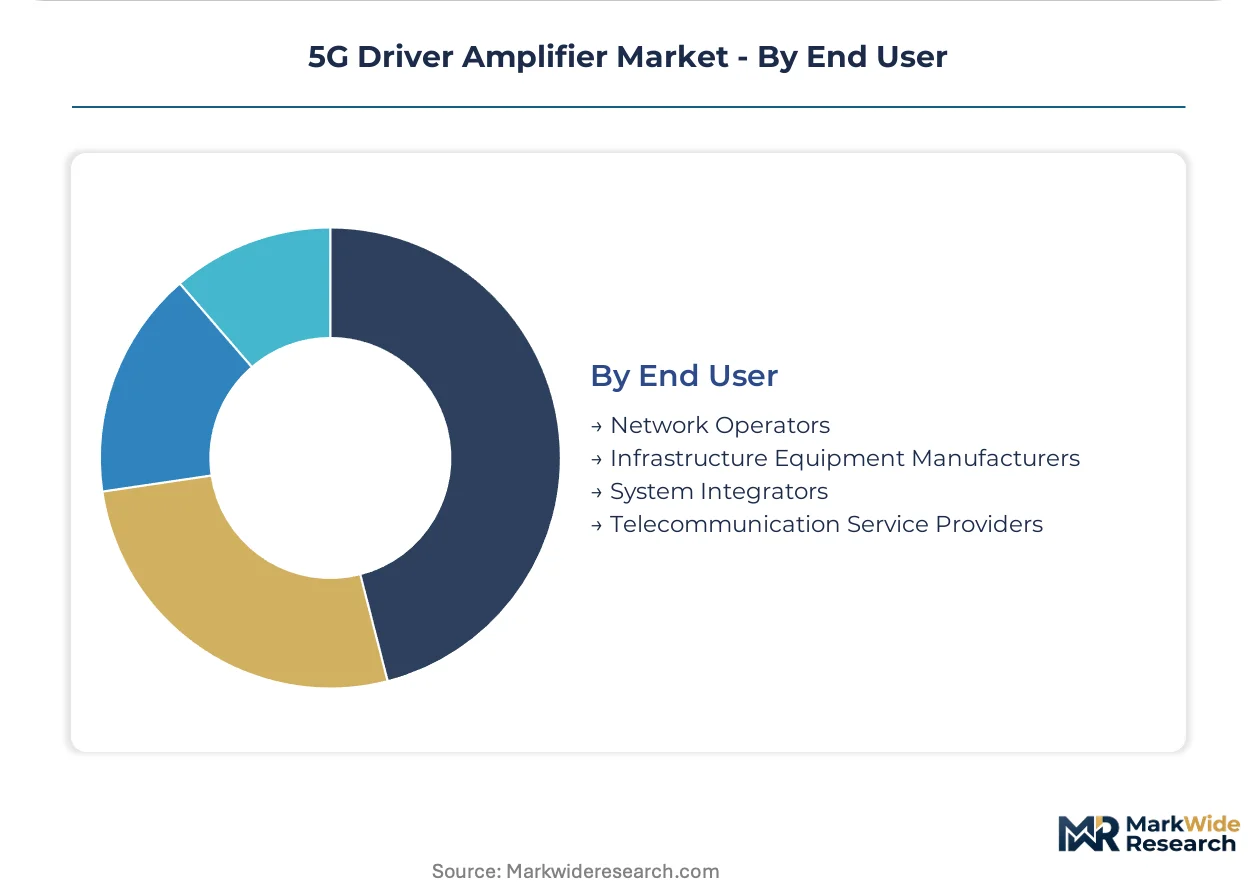
End User:
Customer type determines contracting structure, with network operators consolidating vendor panels while equipment manufacturers disaggregate component sourcing.
- Network Operators:Verizon, AT&T, China Mobile, and Deutsche Telekom specify amplifier performance benchmarks in RFPs and negotiate multi-year service agreements bundling hardware with predictive maintenance analytics.
- Infrastructure Equipment Manufacturers:Ericsson, Nokia, Huawei, and ZTE design amplifier stages into integrated radio units and maintain qualified vendor lists of 4-6 compound semiconductor foundries.
- System Integrators:Deployment contractors procure amplifier modules for site-specific configurations.
- Telecommunication Service Providers:Regional carriers and MVNOs source through distributor channels with shorter procurement cycles.
Infrastructure Equipment Manufacturers dominate design-in authority. Network Operators is expanding procurement control most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese amplifier shipments flow primarily toward domestic base station programs and secondary export channels serving Southeast Asian network buildouts. Equipment procurement cycles in the United States and Germany now dominate high-frequency GaN demand.
United States
Verizon and AT&T are absorbing GaN-on-SiC capacity for C-band massive MIMO deployments following the FCC's 3.45 GHz auction clearing mandates. The FCC's equipment authorization framework compresses qualification timelines for thermal-efficient amplifier designs. Austin and Richardson host concentrated RF design operations where fabless firms interface with domestic compound semiconductor foundries.
China
China Mobile and China Telecom are pulling procurement volumes for 64T64R arrays under MIIT's urban densification quotas for tier-2 cities. MIIT's domestic certification protocols steer supply chain localization toward captive foundry relationships. Shenzhen and Suzhou manufacturing clusters are scaling MMIC test and calibration capacity for state-owned carrier programs.
Germany
Deutsche Telekom's Open RAN vendor consolidation is creating qualification pathways for specialized amplifier suppliers outside incumbent integrated equipment bases. ETSI performance benchmarks define adjacent channel power ratio requirements for network operator certification. Munich and Stuttgart host RF device engineering centers where GaN HEMT design expertise concentrates among established semiconductor specialists.
South Korea
SK Telecom and KT are specifying GaAs pHEMT devices for sub-6 GHz small-cell urban densification projects balancing performance against mature supply chain reliability. The Ministry of Science and ICT's spectrum allocation decisions shape amplifier bandwidth requirements for 28 GHz fixed wireless access backhaul. Suwon and Seoul semiconductor corridors maintain qualified vendor relationships with Japanese epitaxial wafer suppliers.
Japan
NTT Docomo and SoftBank are retrofitting 4G remote radio heads with 5G-capable driver stages requiring thermal and mechanical enclosure redesigns. METI's dual carbon goals impose efficiency mandates on base station power amplification stages. Yokohama and Nagoya industrial zones concentrate compound semiconductor packaging operations serving domestic equipment manufacturers.
5G Driver Amplifier Market Competitive Landscape
Player mix skews toward integrated RF front-end specialists with captive compound semiconductor fabrication capabilities. The supplier base concentrates among GaN technology leaders, silicon-based integrated device manufacturers, and discrete component specialists serving infrastructure equipment qualification lists. Three archetypes dominate: GaN HEMT technology specialists, CMOS/SiGe integrated solution providers, and compound semiconductor foundry-integrated module suppliers. Capacity expansion and backward integration into epitaxial wafer sourcing represent the primary competitive vectors.
Among GaN technology specialists, Qorvo, Skyworks Solutions, and Broadcom occupy positions exemplifying the premium-tier amplifier archetype. Qorvo represents the GaN HEMT design leadership pattern visible in high-frequency infrastructure deployments. Skyworks Solutions sits within the backward-integrated compound semiconductor fabrication tier. Broadcom exemplifies the R&D-intensive CMOS and SiGe process node strategy for integrated small-cell solutions.
| Leading Market Players |
|---|
| Qorvo |
| Skyworks Solutions |
| Broadcom |
| Qualcomm |
| Analog Devices |
| NXP Semiconductors |
| Infineon Technologies |
| MACOM |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
3GPP conformance testing gates both supplier qualification and price differentiation simultaneously, compressing procurement timelines for multi-band amplifiers while creating certification-premium tiers that separate qualified foundries from speculative entrants.
Pricing Analysis
GaN-on-SiC technology-generation pricing gaps separate mature LDMOS alternatives from premium compound semiconductor offerings, with CMOS and SiGe occupying mid-tier positions. Three-tier pricing structure across premium GaN HEMT, standard GaAs pHEMT, and economy CMOS levels reflects certification grade and thermal efficiency benchmarks. Pricing pressure stems from carrier panel consolidation in China reducing qualified suppliers from twelve to four. Infrastructure equipment manufacturers exhibit highest price sensitivity due to direct foundry contracting, while network operators prioritize performance metrics over unit cost.
Supply Chain Analysis
Inventory lead times for GaN epitaxial wafers extend qualification cycles as Japanese and U.S. substrate specialists concentrate supply. Raw material dependencies center on silicon carbide substrates, gallium nitride epitaxy, and advanced ceramic packaging. Single-source vulnerability concentrates in epitaxial wafer supply where Sumitomo and Cree anchor capacity. Distribution runs through direct procurement contracts with compound semiconductor foundries, bypassing traditional distributor channels as carriers consolidate vendor panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through 3GPP and FCC certification timelines protects incumbents from rapid displacement.
For Market Incumbents: Shield GaN HEMT technology leadership through backward integration into epitaxial wafer sourcing, countering substrate concentration risk among Japanese suppliers. Deepen captive foundry relationships in Richardson and Austin to compress lead times for C-band massive MIMO deployments. Prioritize certification investment across contiguous 280 MHz blocks rather than fragmented assignments. For New Entrants and Emerging Players: Open RAN interface standardization gaps expose white space for specialized amplifier vendors to bypass incumbent integrated equipment suppliers. Target India's PLI scheme for telecom equipment manufacturing where localized test and calibration operations attract assembly investment. Pursue predictive maintenance analytics bundling as the primary go-to-market angle against hardware-only incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compound semiconductor foundries holding qualified vendor status at Ericsson and Nokia. Five-to-ten year viability hinges on GaN-on-SiC capacity expansion timing relative to MIIT deployment windows. Monitor FCC spectrum auction clearing deadlines as the inflection indicator for equipment refresh cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Sourcing | Secures supply continuity against Japanese substrate concentration for GaN HEMT production. |
| Open RAN Alliance Certification Investment | Enables interface standardization compliance for specialized amplifier vendors entering disaggregated procurement. |
| India PLI Scheme Manufacturing Localization | Attracts final test and calibration capacity to serve Southeast Asian network buildouts. |
| Integrated Doherty Architecture Development | Converges digital pre-distortion with analog combiners for single-chip massive MIMO solutions. |
| Predictive Maintenance Analytics Bundling | Aligns with carrier multi-year service agreements consolidating vendor panels in China. |
Research Methodology
Cross-validation between primary interviews with RF device engineering directors and secondary validation through FCC equipment authorization databases anchors the qualitative findings. Conversations with base station procurement managers at state-owned carriers, GaN HEMT design specialists at compound semiconductor foundries, and Open RAN integration engineers at telecom operators inform supply chain dynamics. Secondary sources include 3GPP technical specifications, MIIT deployment quota announcements, SEC 10-K filings from listed RF component suppliers, and ETSI performance benchmark documentation. Bottom-up amplifier shipment modeling triangulates against top-down infrastructure capex projections.
Sensitivity analysis around MIIT base station targets and FCC clearing timelines tests forecast robustness across the projection horizon. Segmentation dimensions encompass product architecture, semiconductor process node, deployment scale, and end-user contracting structure. CAGRs derive from unit shipment trajectories weighted by average selling price evolution across technology tiers. Industry-specific inputs include GaN-on-SiC yield improvement curves and carrier panel consolidation rates.
Forecasts assume regulatory continuity in FCC equipment authorization and MIIT certification protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.