
 Global RF and Microwave Power Transistors Market | 2026-2036
Global RF and Microwave Power Transistors Market Size, Share, and Industry Trends Forecast 2026-2036
Global RF and Microwave Power Transistors Market Foresight
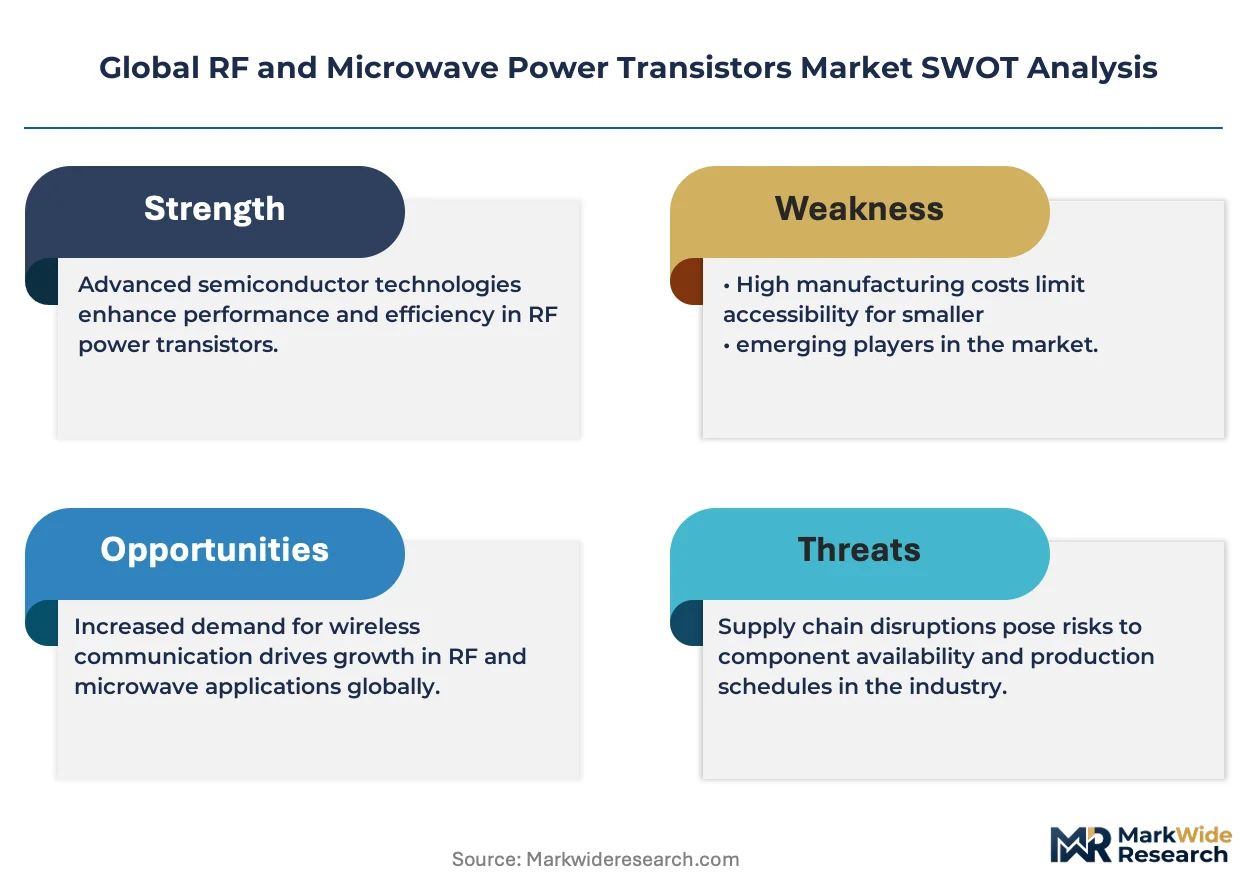
Gallium nitride is decoupling RF power transistor economics from legacy silicon LDMOS cost structures across high-frequency applications. Qorvo leverages captive GaN-on-SiC foundry capacity to anchor its position in defense and 5G infrastructure. Infineon Technologies sustains bipolar junction transistor production lines for legacy radar and broadcasting customers. MACOM specializes in GaN HEMT designs for electronically scanned arrays and satellite communication terminals.
RF and microwave power transistors are semiconductor devices engineered to amplify signals across frequencies from hundreds of megahertz to tens of gigahertz, with GaN HEMTs achieving power densities exceeding ten watts per millimeter at X-band frequencies. Solid-state technology dominates commercial wireless infrastructure, while vacuum tube and hybrid architectures persist in megawatt-class radar transmitters. GaN HEMT product types command premium positioning in defense and space applications, whereas LDMOS retains cost advantages in sub-6 GHz broadcasting. Electronically scanned arrays represent the fastest-growing application dimension, driven by active electronically scanned array radar proliferation across fighter aircraft and naval platforms.
FCC spectrum allocation rulings and ITAR export controls shape product roadmaps and market access for US-based manufacturers serving defense contractors. EAR dual-use regulations and EU REACH substance restrictions impose material traceability burdens across GaN epitaxy supply chains. Stakeholders must monitor pending spectrum reallocation decisions and compound semiconductor substrate supply constraints.
Market Dynamics
Defense radar modernization programs are compressing procurement cycles for GaN-on-SiC power transistors, while REACH chemical compliance requirements force foundries to requalify epitaxy chemistries. This dual pressure is restructuring supplier-buyer relationships across the value chain.
Growth Catalysts
- Active Electronically Scanned Array proliferation:Fighter aircraft and naval platform upgrades are mandating solid-state radar architectures that demand high-power-density transistors. Defense procurement offices in the United States are accelerating contract awards for GaN-based transmit-receive modules.
- China's 5G base station rollout:Domestic carriers are deploying massive MIMO arrays requiring LDMOS and GaN power amplifiers across sub-6 GHz spectrum allocations. Base station OEMs are qualifying second-source transistor suppliers to meet deployment timelines.
- REACH material compliance frameworks:EU chemical registration requirements are disqualifying legacy substrate cleaning processes, creating certified-supplier premiums for compliant GaN epitaxy houses.
Market Restraints
- Silicon carbide substrate scarcity:Six-inch SiC wafer supply concentrates among Japanese and US substrate manufacturers, creating allocation bottlenecks for GaN-on-SiC foundry capacity.
- ITAR export control friction:US State Department licensing requirements delay international shipments of defense-grade transistors, constraining non-US prime contractor access to qualified suppliers.
- LDMOS cost floor:Mature silicon foundry economics sustain price pressure on GaN alternatives in sub-3 GHz broadcasting and cellular infrastructure applications.
Strategic Opportunities
- LEO satellite constellation terminals:Phased-array user terminals for broadband constellations require Ku-band and Ka-band GaN power amplifiers. Terminal manufacturers in Germany and the United States are qualifying multi-source transistor supply.
- India's defense indigenization mandates:Local content requirements under the Make in India framework create captive demand for domestic transistor packaging and test capabilities.
- GaN-on-silicon process convergence:Foundries are integrating GaN epitaxy onto standard CMOS lines, collapsing cost structures for consumer radar and automotive sensing applications.
Industry Challenges
- Compound semiconductor process engineering talent:MOCVD reactor operation and GaN device physics expertise concentrates among a small cohort of experienced technologists, constraining foundry expansion.
- Multi-year qualification cycles:Aerospace and defense customers require extended reliability testing under MIL-STD conditions, freezing design wins for 24-36 months.
- Legacy radar system interoperability:New solid-state transmitters must interface with existing waveguide and cooling infrastructure, complicating retrofit program engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RF and Microwave Power Transistors Market |
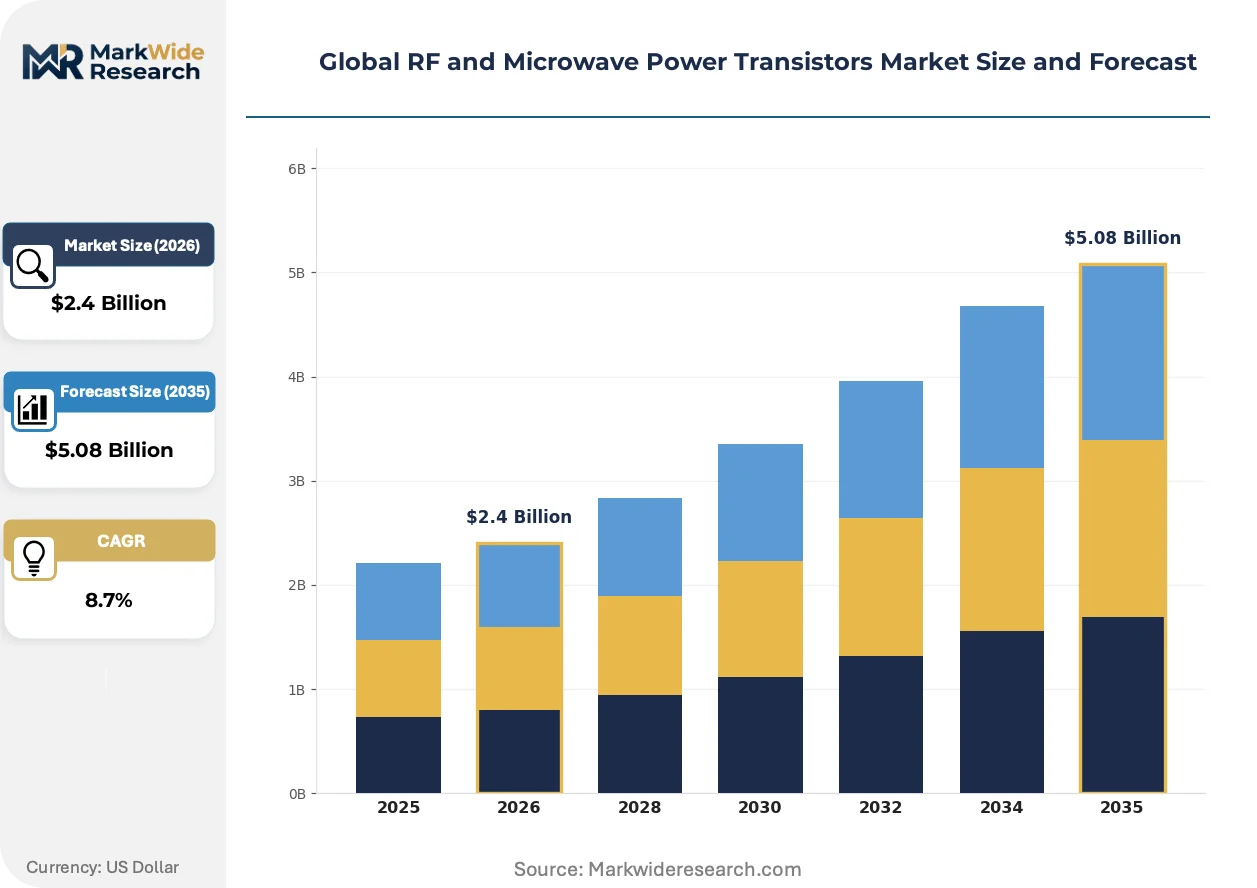
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LDMOS, GaN HEMT, GaAs MESFET, Bipolar Junction Transistor, Silicon Carbide, Others Application: Satellite Communication, Radar Systems, Wireless Infrastructure, Electronically Scanned Arrays, Broadcasting, Space & Defense Technology: Solid State, Vacuum Tube, Hybrid, Monolithic Microwave Integrated Circuit, Discrete Components End User: Telecom Operators, Defense Contractors, Space Agencies, Broadcasting Companies, Research Institutions |
| Companies Covered | Qorvo, Ampleon, NXP Semiconductors, Toshiba Corporation, Microchip Technology, Infineon Technologies, MACOM, Renesas Electronics, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RF and Microwave Power Transistors Market Shifts & Advancements
GaN device architectures are unifying previously separate amplifier functions, while regulatory chemical frameworks and defense procurement models are forcing concurrent adaptations across supply chains. These intersecting pressures are compressing traditional technology transition timelines.
GaN monolithic microwave integrated circuits are unifying power amplification with phase-shifting and switching functions in single-die implementations. Defense prime contractors are adopting these multifunction chips for AESA radar tile density improvements. This integration is unifying previously discrete component supply chains into consolidated MMIC vendor relationships.
EU REACH substance restrictions are prohibiting hexavalent chromium surface treatments and specific fluorinated compounds in GaN device fabrication. Foundries are reformulating passivation chemistries and requalifying processes under ECHA oversight. European defense and space programs are prioritizing REACH-compliant suppliers in source selection criteria.
Defense procurement offices are consolidating transistor awards under multi-year indefinite-delivery contracts with technical data package ownership clauses. Prime contractors are responding by qualifying alternative foundries and securing second-source epitaxy supply. This behavioral shift is most visible in US Navy and Air Force radar modernization programs.
Global RF and Microwave Power Transistors Market Segmentation
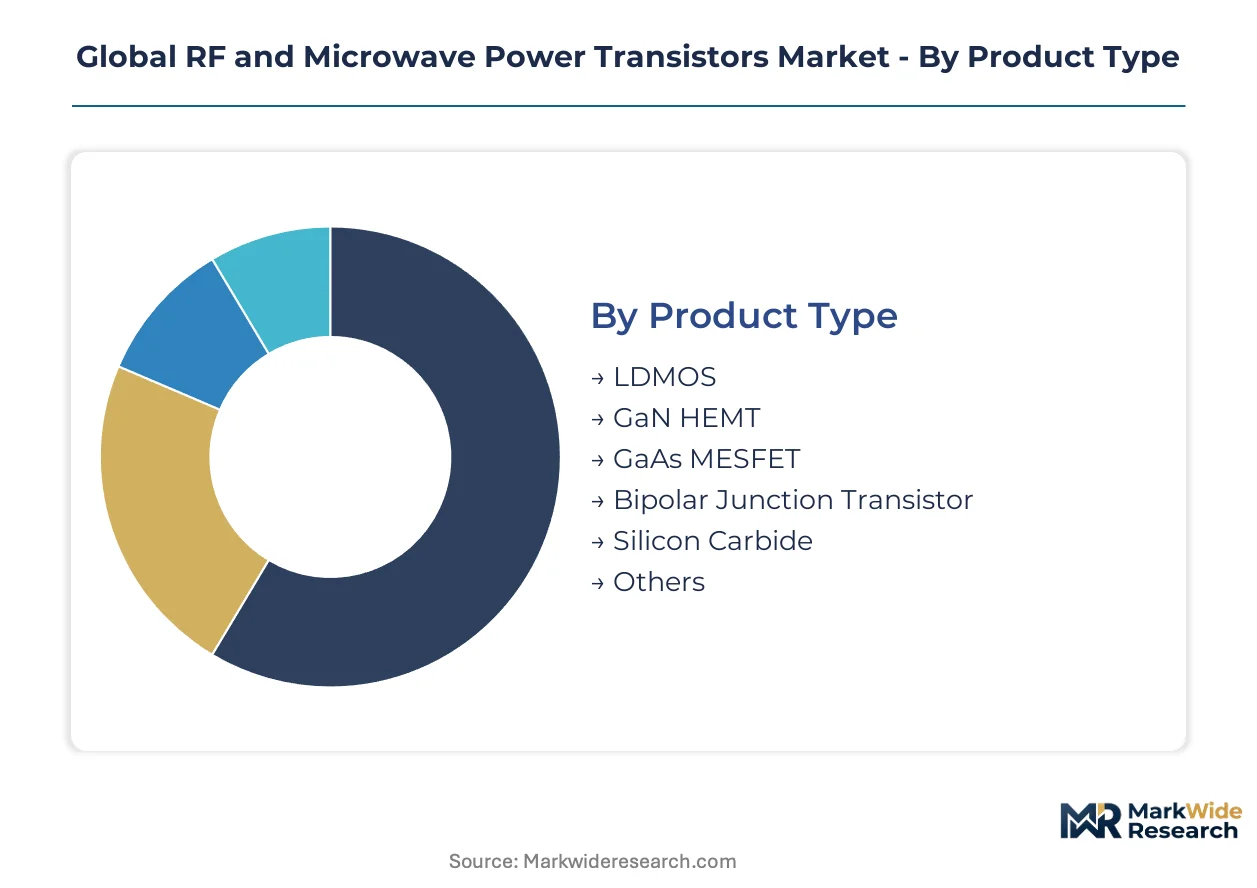
RF and microwave power transistor procurement cycles diverge sharply across end-use verticals, with defense radar upgrades demanding GaN-on-SiC qualification timelines that stretch 24-36 months while 5G infrastructure OEMs compress LDMOS supplier selection into quarterly windows. Segmentation clarity enables suppliers to align foundry capacity investments with predictable demand corridors.
Product Type:
Technology replacement cycles define competitive positioning across product categories, with GaN architectures displacing legacy silicon in high-frequency defense applications while mature LDMOS fabs retain cost advantages below 3 GHz.
- LDMOS:Silicon-based lateral diffusion metal oxide semiconductor devices sustain dominance in sub-6 GHz cellular base stations and UHF/VHF broadcasting transmitters. Chinese carriers deploying massive MIMO arrays account for concentrated procurement volumes, though price erosion from depreciated 200mm foundry assets compresses margins.
- GaN HEMT:Gallium nitride high electron mobility transistors achieve power densities exceeding ten watts per millimeter at X-band frequencies through wide bandgap properties. US Navy and Air Force radar modernization programs are accelerating contract awards for GaN-on-SiC transmit-receive modules, creating allocation bottlenecks among qualified foundries.
- GaAs MESFET:Gallium arsenide metal semiconductor field effect transistors retain niche positioning in legacy Ku-band satellite terminals and phased-array subsystems.
- Bipolar Junction Transistor:Silicon BJTs persist in legacy radar and broadcasting infrastructure where customers prioritize form-factor compatibility over efficiency gains.
- Silicon Carbide:SiC power devices address extreme thermal environments in space-qualified transmitters and high-power radar transmitters.
- Others:Emerging wide bandgap materials including diamond and aluminum nitride occupy pre-commercial research phases.
LDMOS sits at the top of the volume ranking, with GaN HEMT climbing the fastest.
Application:
Application-specific qualification requirements fragment supplier relationships, with defense primes demanding ITAR-compliant foundry traceability while commercial wireless OEMs prioritize second-source flexibility.
- Electronically Scanned Arrays:Active electronically scanned array architectures unify phase-shifting and amplification functions in solid-state radar tiles. Fighter aircraft and naval platform upgrades across the United States, Japan, and Germany are mandating AESA retrofits that displace mechanically scanned legacy systems.
- Radar Systems:Ground-based and airborne radar transmitters span L-band through X-band frequencies with power requirements from hundreds of watts to megawatts. REACH chemical compliance restrictions are disqualifying legacy substrate cleaning processes, creating certified-supplier premiums for European defense procurement offices.
- Satellite Communication:Geostationary and low earth orbit terminals require Ku-band and Ka-band power amplifiers with radiation tolerance.
- Wireless Infrastructure:Macro base stations and small cells deploy LDMOS and GaN Doherty amplifiers across sub-6 GHz spectrum allocations.
- Broadcasting:Terrestrial television and radio transmitters sustain demand for ruggedized silicon devices with decades-long service life expectations.
- Space & Defense:Radiation-hardened components for satellite payloads and strategic systems command qualification premiums.
Radar Systems capture the largest revenue concentration, with Electronically Scanned Arrays expanding most quickly.
Technology:
Integration intensity determines cost structures and supplier consolidation potential, with monolithic microwave integrated circuits collapsing multi-chip module assemblies into single-die solutions.
- Monolithic Microwave Integrated Circuit:MMICs unify power amplification, phase-shifting, and switching functions in gallium nitride implementations. Defense prime contractors in the United States are adopting these multifunction chips for AESA tile density improvements, consolidating previously discrete component supply chains.
- Solid State:Fully transistorized architectures dominate commercial wireless infrastructure and emerging defense applications. China's domestic 5G base station rollout and satellite programs are concentrating procurement among vertically integrated OEMs with captive GaN epitaxy partnerships.
- Vacuum Tube:Traveling wave tubes and magnetrons persist in megawatt-class radar transmitters where power-combining solid-state alternatives remain economically prohibitive.
- Hybrid:Combinations of solid-state driver stages with vacuum tube final amplifiers bridge performance and cost requirements.
- Discrete Components:Individual transistor packages retain relevance in repair and upgrade programs for legacy systems.
Solid State leads volume deployment, with Monolithic Microwave Integrated Circuit gaining share fastest.
End User:
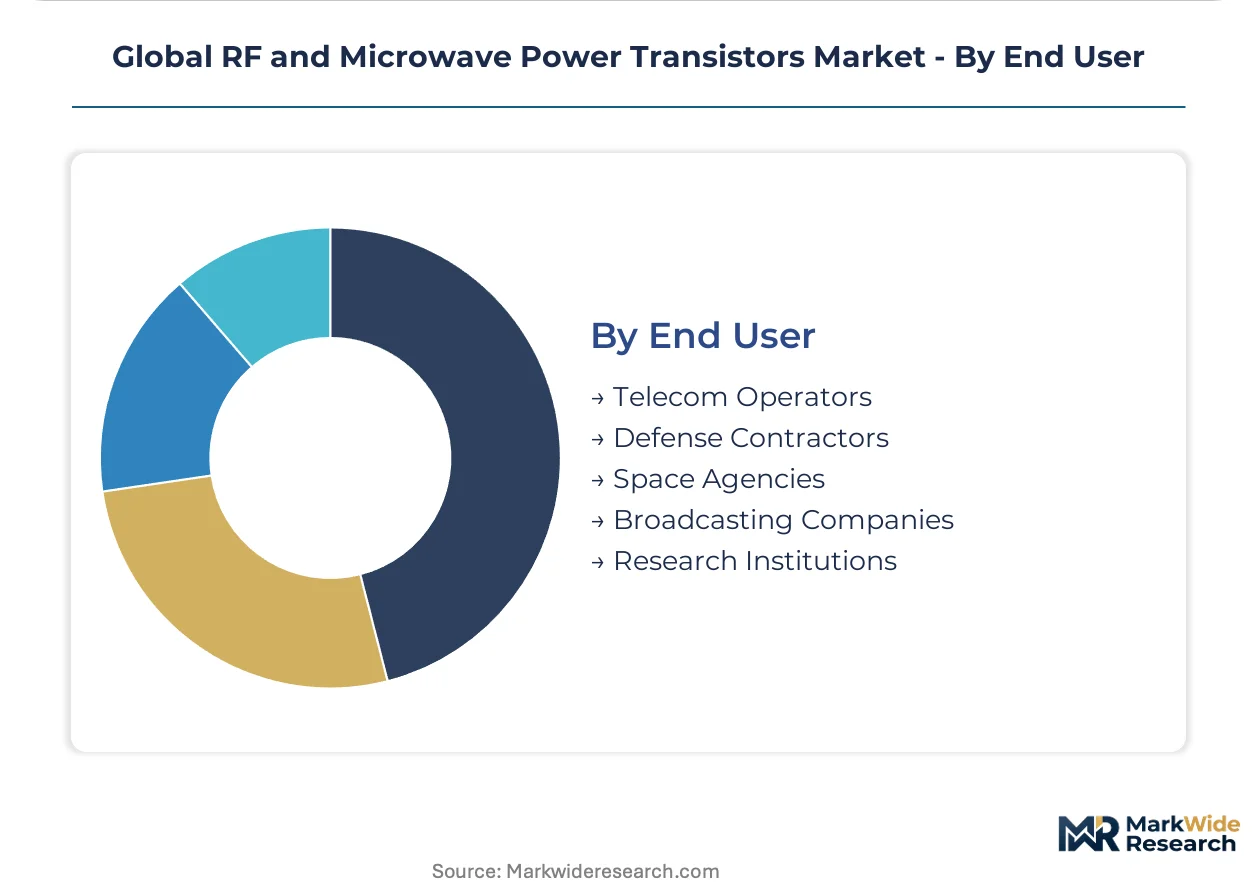
Procurement authority concentration varies dramatically across end users, with defense contractors wielding multi-year indefinite-delivery contract mechanisms while telecom operators negotiate quarterly price resets.
- Defense Contractors:Prime contractors including Lockheed Martin, Raytheon, and Northrop Grumman specify GaN HEMT performance parameters for radar and electronic warfare programs. US State Department ITAR licensing requirements delay international shipments, constraining non-US prime contractor access to qualified suppliers.
- Telecom Operators:Mobile network operators in China, the United States, and India drive volume demand for base station power amplifiers. FCC spectrum allocation rulings shape product roadmaps for sub-6 GHz and mmWave deployments.
- Space Agencies:NASA, ESA, and national space programs mandate radiation-hardened qualification protocols.
- Broadcasting Companies:Terrestrial network operators prioritize device longevity and field serviceability.
- Research Institutions:National laboratories and university programs drive pre-commercial technology validation.
Telecom Operators sit at the top of the volume ranking, with Defense Contractors climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics corridor anchors the densest concentration of 5G base station manufacturing, while defense procurement offices in Washington and Brussels accelerate GaN qualification timelines. Substrate supply constraints and chemical compliance frameworks are redrawing supplier maps across three continents.
United States
The Pentagon's radar modernization programs and Navy AESA retrofits compress procurement cycles for GaN-on-SiC transmit-receive modules. ITAR export controls administered by the US State Department delay international shipments, constraining allied prime contractor access. Boston's defense technology corridor hosts qualification laboratories where foundries endure 24-36 month reliability testing under MIL-STD conditions.
China
Domestic carriers deploying massive MIMO arrays across sub-6 GHz spectrum drive concentrated LDMOS and GaN power amplifier demand. MIIT spectrum allocations shape product roadmaps for base station OEMs qualifying second-source transistor suppliers. Yangtze River Delta packaging houses are expanding captive test capabilities to meet deployment timelines.
Germany
ECHA REACH substance restrictions are prohibiting hexavalent chromium surface treatments in GaN device fabrication, forcing foundry requalification of passivation chemistries. Defense procurement offices prioritize REACH-compliant suppliers in source selection criteria for AESA radar programs. Bavarian semiconductor clusters are reformulating epitaxy processes under regulatory oversight.
Japan
Six-inch SiC wafer supply concentrates among Japanese substrate manufacturers, creating allocation bottlenecks for GaN-on-SiC foundry capacity worldwide. METI industrial policy supports domestic compound semiconductor ecosystem development. Kyushu's silicon carbide production corridor supplies epitaxy houses across Asia-Pacific defense programs.
India
Make in India local content requirements under defense indigenization mandates create captive demand for domestic transistor packaging and test capabilities. TRAI spectrum management frameworks influence base station power amplifier specifications for emerging 5G rollouts. Bengaluru's defense electronics cluster is qualifying indigenous suppliers for radar subsystem integration.
Global RF and Microwave Power Transistors Market Competitive Landscape
Global majors compete with regional champions across defense-grade GaN qualification and commercial wireless volume segments. The vendor base stratifies between captive foundry operators and fabless design houses serving multi-source procurement strategies. Three archetypes dominate: vertically integrated defense suppliers, wireless infrastructure volume players, and compound semiconductor specialists. Capacity expansion and strategic foundry partnerships constitute the primary competitive moves as substrate scarcity intensifies.
Within the vertically integrated tier, Qorvo anchors captive GaN-on-SiC foundry positioning, while Infineon Technologies exemplifies sustained production of legacy bipolar junction transistor lines for radar and broadcasting customers. MACOM occupies a specialist position in GaN HEMT designs for electronically scanned arrays. These three represent divergent strategic bets on technology transition timelines and customer retention across defense and commercial verticals.
| Leading Market Players |
|---|
| Qorvo |
| Ampleon |
| NXP Semiconductors |
| Toshiba Corporation |
| Microchip Technology |
| Infineon Technologies |
| MACOM |
| Renesas Electronics |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Vertically integrated defense contractors with captive GaN-on-SiC foundry capacity exercise asymmetric pricing power over fabless competitors, while REACH compliance investments and SiC substrate scarcity compress margins for second-tier suppliers. This ownership structure concentrates volume discounts among prime contractors and fragments pricing discipline across the commercial wireless tier.
Pricing Analysis
Silicon carbide wafer cost pass-through dominates GaN HEMT pricing, with six-inch substrate scarcity forcing foundries to index contracts to Japanese and US supplier allocations. Three-tier pricing structure across ITAR-restricted defense grade, REACH-compliant commercial grade, and uncertified industrial grade separates qualified from unqualified supply. Pricing pressure stems from depreciated 200mm LDMOS foundries underbidding GaN alternatives in sub-3 GHz cellular infrastructure. Telecom operators in China exhibit highest price sensitivity through quarterly supplier renegotiations, while US defense primes accept premiums for technical data package ownership.
Supply Chain Analysis
Freight costs for SiC substrates from Kyushu to US and European epitaxy houses add non-trivial landed cost premiums, compounding allocation bottlenecks during demand surges. Supply concentrates in Japan for six-inch SiC wafers, the United States for ITAR-compliant GaN foundries, and China for LDMOS packaging and test. Raw material dependencies span high-purity gallium metal, ammonia precursor gases, and specialized ceramic packaging substrates. Single-source vulnerability concentrates in Japanese SiC substrate manufacturers. Distribution runs through defense prime contractor qualification laboratories for GaN HEMTs, and direct OEM relationships for cellular infrastructure LDMOS.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through India's Make in India indigenization mandates, where local content requirements create cost advantages unavailable to import-dependent competitors serving European REACH-restricted defense programs.
For Market Incumbents: Deepen captive GaN epitaxy partnerships to lock in six-inch SiC substrate allocations before Japanese manufacturers expand capacity. Secure second-source qualification with alternative foundries to mitigate ITAR licensing delays constraining international shipments. Prioritize REACH-compliant process requalification to capture European defense procurement premiums as ECHA restrictions disqualify legacy suppliers. For New Entrants and Emerging Players: EU REACH substance restrictions in Germany and France open a window for compliant GaN epitaxy houses to displace non-certified competitors in European AESA radar programs. Target LEO satellite constellation terminal manufacturers in Germany and the United States, where multi-source qualification requirements create entry pathways for new transistor suppliers. Lead with GaN-on-silicon process offerings for automotive radar and consumer sensing applications where cost structures collapse against GaN-on-SiC alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless GaN design houses without captive foundry capacity, as substrate scarcity discounts their revenue predictability. Long-term viability hinges on securing qualified foundry relationships before defense procurement consolidation freezes design wins. Watch for US Navy and Air Force multi-year indefinite-delivery contract awards as inflection signals for qualified supplier revenue visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaN-on-SiC Foundry Expansion | Qorvo's internal capacity anchors defense contract awards against fabless competitors. |
| REACH-Compliant Process Requalification | European foundries reformulating passivation chemistries capture ECHA-mandated supplier premiums. |
| Second-Source Epitaxy Partnership | Prime contractors qualifying alternative foundries mitigate ITAR licensing delay risks. |
| GaN-on-Silicon Process Migration | Foundries integrating onto CMOS lines collapse cost structures for automotive radar applications. |
| Indigenous Packaging Capability Buildout | Bengaluru test houses under Make in India capture domestic content requirement value. |
Research Methodology
Coverage spans the United States, China, Germany, Japan, and India, with primary inputs from each defense procurement office and semiconductor cluster. Primary interviews with GaN device physicists, MOCVD reactor operators, defense prime contractor procurement directors, and base station OEM supply chain managers combined with secondary validation from SEC filings, ECHA substance restriction databases, and MIIT spectrum allocation notices. Bottom-up transistor shipment estimates triangulated against top-down defense budget appropriations and carrier capex disclosures.
Rate-of-change decomposition separates volume effects from mix-shift and pricing across the analysis window. Segmentation dimensions modeled include product type, application, technology, and end user, with additional granularity on ITAR compliance tier and REACH certification status. CAGRs derived from historical shipment correlations with defense modernization program timelines and 5G base station deployment schedules. Forecast inputs incorporate SiC substrate supply constraints and FCC spectrum reallocation proceedings.
Revisions become necessary when Japanese SiC wafer allocation policies shift, US State Department ITAR licensing procedures change, or EU ECHA expands restricted substance lists beyond hexavalent chromium and fluorinated compounds. Forecasts reflect assumptions about defense procurement cycle continuity and Chinese carrier deployment momentum. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
Embedded Antenna Systems Market
RF Components
RF Isolator Market
RF Components
Phase Shifters Market
RF Components
China Small Signal Transistor Market
RF Components
RFID Tags Market
RF Components
Radio Frequency Components Market
RF Components
Digital Radio Frequency Market
RF Components
Radio Frequency Filters Market
RF Components
RF Acoustic Wave Filters Market
RF Components
RF Filters Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
RF Front End Module Market
RF Components
RF Tester Market
RF Components
Global Inductors Market
RF Components
RF Passive Component Market