
 Frequency Synthesizer Market | 2026-2036
Frequency Synthesizer Market Size, Share, and Industry Trends Forecast 2026-2036
Frequency Synthesizer Market Analysis
The shift from single-source to multi-source procurement of high-frequency components is realigning vendor relationships across the frequency synthesizer supply chain. Texas Instruments Incorporated leverages its analog semiconductor heritage to sustain design-in relationships with defense contractors. Analog Devices, Inc. competes through precision clocking architectures that anchor test equipment portfolios at Keysight Technologies, Inc.
A frequency synthesizer generates stable, precise output frequencies from a reference oscillator through phase-locked loops, direct digital synthesis, or hybrid architectures, with phase noise performance often specified below −100 dBc per Hz at 10 kHz offset for radar applications. RF Synthesis and Digital Frequency Synthesis occupy the technology frontier where margin pools deepen on software-defined radio demand. Phase-Locked Loop Synthesizers retain volume leadership in aerospace applications, while Direct Digital Synthesizers gain ground in telecommunications base stations for their microsecond switching speed.
The FCC enforces stringent electromagnetic interference standards that shape frequency synthesizer spectral purity requirements for commercial equipment sold in the United States. ETSI and CE marking frameworks in Europe mandate coexistence testing that filters non-compliant suppliers from cellular infrastructure tenders. China's MIIT issues GB standards for satellite navigation equipment that dictate reference oscillator stability thresholds. Stakeholders must monitor spectrum auction outcomes and defense budget appropriations to calibrate R&D allocation between wideband and narrowband synthesis architectures.
Market Dynamics
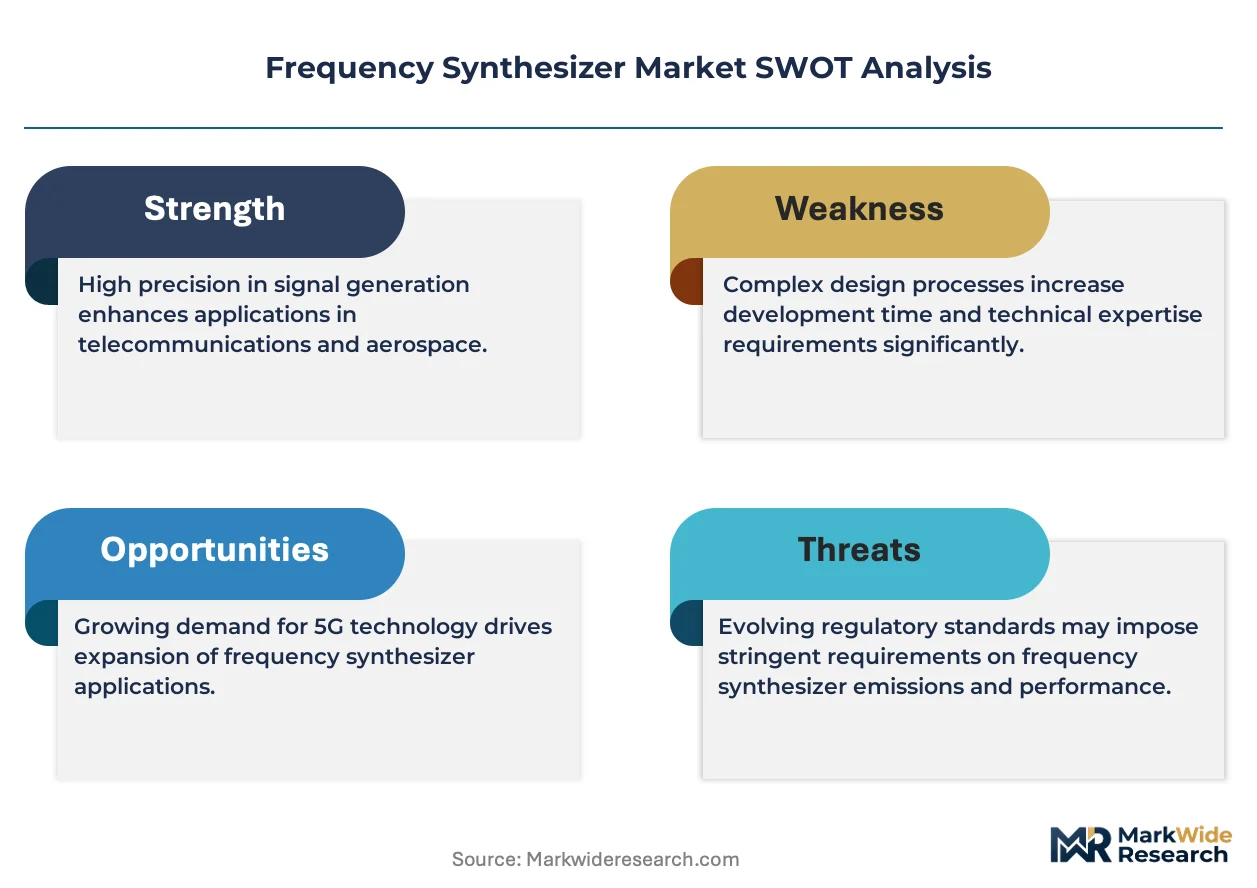
Defense procurement of radar and electronic warfare systems is expanding frequency synthesizer adoption, while the FCC's spectrum reallocation mandates push manufacturers toward higher-frequency-capable designs. This dual pressure from military demand and commercial spectrum policy is compressing development cycles and reshaping vendor priorities.
Growth Catalysts
- 5G Infrastructure Deployment:China's base station rollout demands high-precision clocking solutions for massive MIMO arrays. Base station OEMs require synthesizers with sub-microsecond switching speeds.
- Satellite Navigation Modernization:China's MIIT issues GB standards mandating tighter reference oscillator stability for BeiDou-3 receivers. Equipment manufacturers must upgrade synthesis architectures to meet these thresholds.
- Electronic Warfare Procurement:Defense contractors in the United States are sourcing wideband synthesizers for next-generation jamming and signal intelligence platforms. Phase noise performance below −100 dBc per Hz at 10 kHz offset is now standard.
Market Restraints
- High-Purity Crystal Oscillator Supply Concentration:OCXO and TCXO production concentrates in Japanese and Swiss suppliers. Geopolitical friction risks input cost volatility and extended lead times.
- EMI Compliance Burden:The FCC enforces stringent electromagnetic interference standards that lengthen certification timelines for commercial equipment. Non-compliant designs face market exclusion.
- Direct Digital Synthesis Limitations:Spurious signal performance in DDS architectures constrains adoption for high-end radar applications. Hybrid PLL-DDS designs add cost and complexity.
Strategic Opportunities
- Software-Defined Radio Convergence:The integration of RF synthesis with FPGA-based digital signal processing is creating new product categories. Defense and telecommunications OEMs seek unified platforms.
- India's Defense Modernization:The country's offset procurement policies favor local assembly of frequency control components. Foreign vendors can establish captive production to meet indigenization mandates.
- Spectrum Auction Tailwinds:FCC auctions of millimeter-wave bands are accelerating demand for synthesizers operating above 40 GHz. Test equipment manufacturers are expanding calibration service offerings.
Industry Challenges
- Phase Noise Engineering Talent Scarcity:Specialized RF design expertise for low-noise PLL architectures is concentrated among experienced practitioners. Universities produce insufficient graduates with relevant mixed-signal training.
- Legacy System Integration Complexity:Upgrading synthesizer subsystems in existing radar and communications platforms requires backward-compatible form factors. Retrofit programs demand extended qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frequency Synthesizer Market |
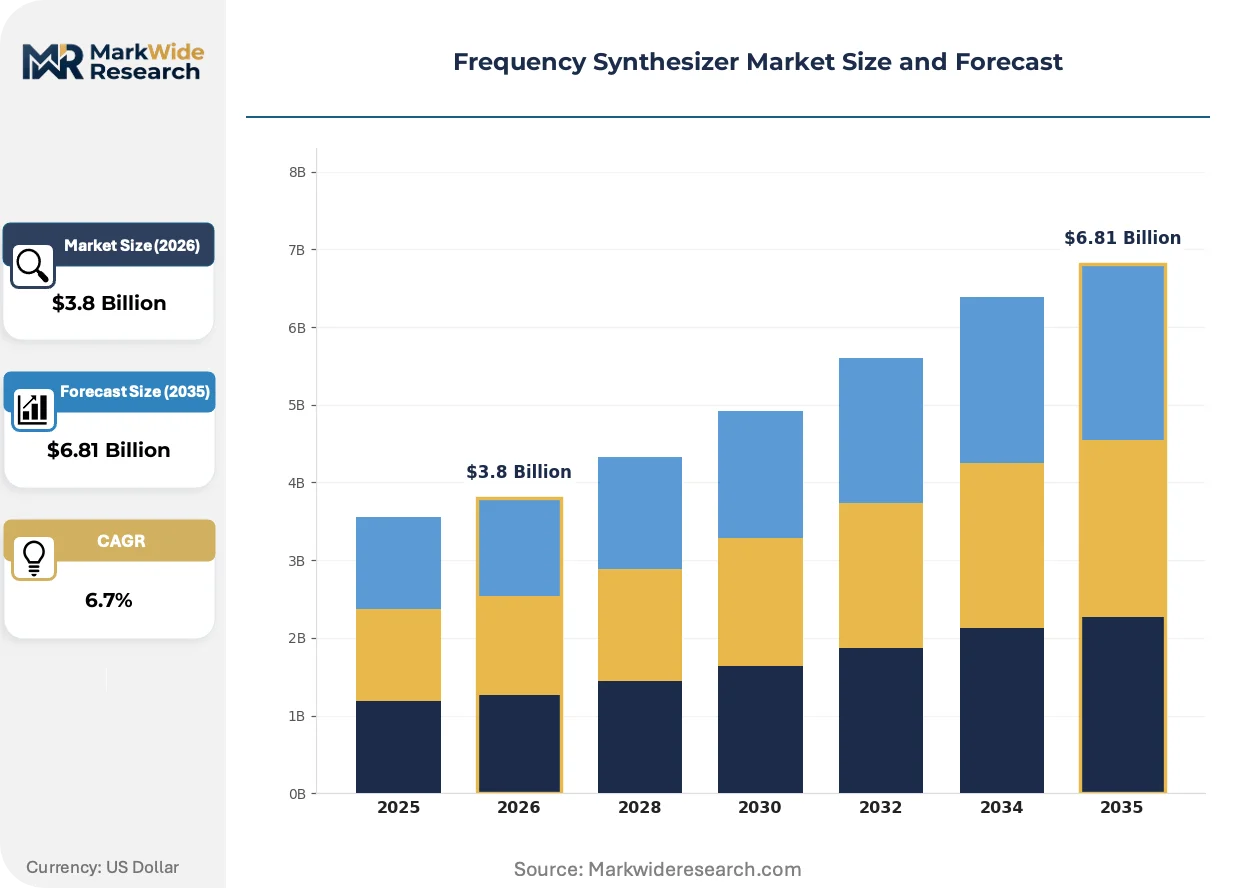
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Synthesizers, Digital Synthesizers, Direct Digital Synthesizers, Phase-Locked Loop Synthesizers Technology: RF Synthesis, Direct Frequency Synthesis, Integer-N Synthesis, Digital Frequency Synthesis Application: Telecommunications, Aerospace, Broadcasting, Test Equipment End User: Defense, Consumer Electronics, Automotive, Industrial Automation |
| Companies Covered | Qorvo, Inc., Renesas Electronics Corporation, Analog Devices, Inc., Synergy Microwave Corporation, Mini-Circuits, Texas Instruments Incorporated, Keysight Technologies, Inc., Microchip Technology, National Instruments Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frequency Synthesizer Market Emerging Trajectories
Hybrid frequency synthesis architectures are displacing pure analog or digital approaches across defense and telecommunications equipment. This convergence is compressing switching times while extending operational bandwidths.
Direct digital synthesis is decentralizing frequency generation across distributed antenna systems and phased arrays. Telecommunications infrastructure OEMs are embedding DDS cores at the element level rather than centralizing synthesis. This architecture reduces cable losses and enables beam-steering agility that centralized designs cannot match.
The FCC's spectrum reallocation mandates are forcing equipment manufacturers to redesign for higher-frequency operation. Commercial synthesizer portfolios must now cover millimeter-wave bands previously reserved for specialized applications. Test and measurement vendors are expanding calibration capabilities to serve this transition.
Buyer concentration among defense primes and telecommunications OEMs is compressing vendor margins and elongating payment cycles. Smaller synthesizer suppliers are cultivating relationships with tier-two equipment manufacturers as alternative channels. This diversification is most visible in the United States, where mid-tier radar contractors seek qualified second-source components.
Frequency Synthesizer Market Segmentation
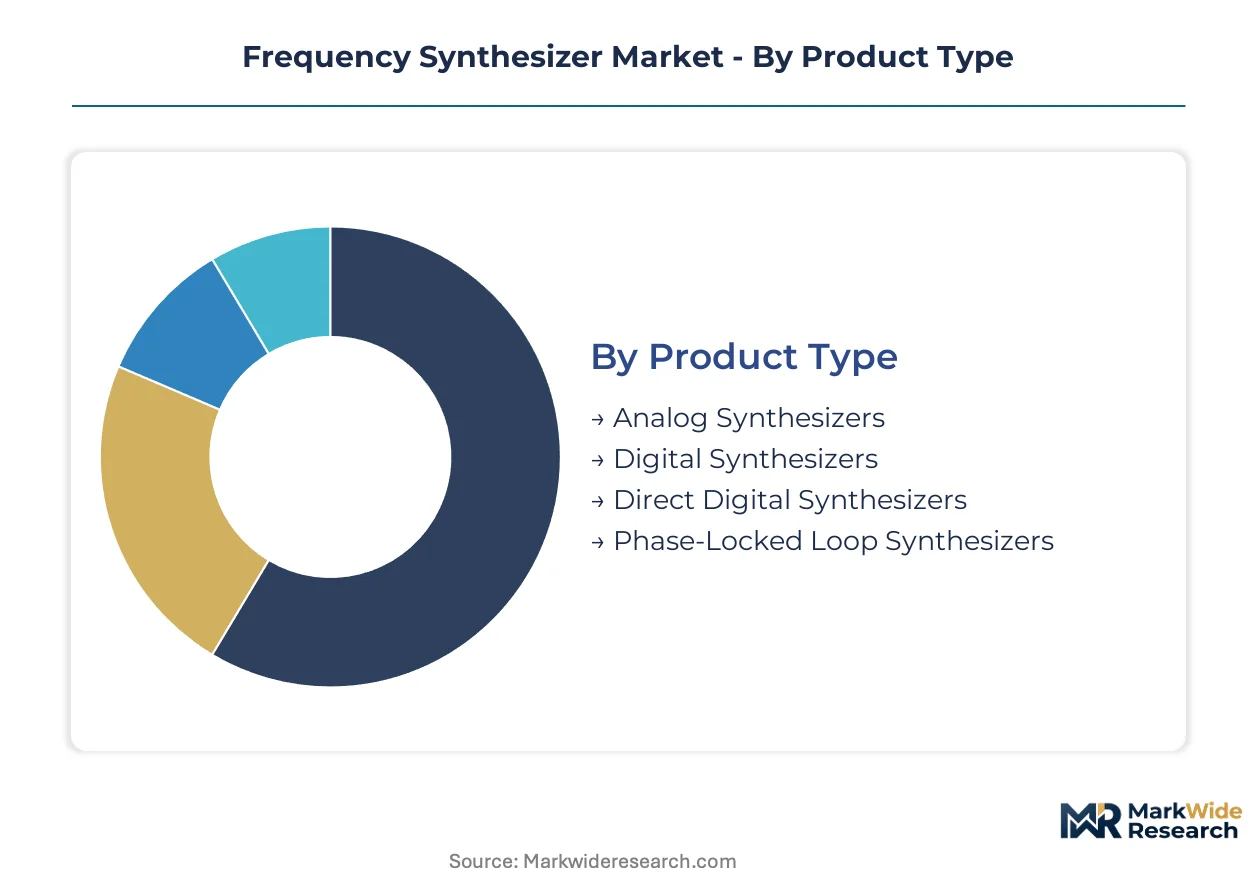
Frequency synthesizer procurement decisions hinge on phase noise thresholds, switching speed requirements, and spectral purity mandates that vary sharply across defense, telecommunications, and test equipment applications. Buyers segment the market by architectural approach, frequency generation method, deployment environment, and end-user certification standards to align component selection with system-level performance specifications.
Product Type:
Defense contractors prioritize phase noise performance and frequency agility when selecting synthesizer architectures, driving tiered procurement strategies across analog, digital, and hybrid implementations.
- Analog Synthesizers:Voltage-controlled oscillators with varactor-tuned resonant circuits deliver continuous frequency coverage across multi-octave ranges. United States radar platform integrators specify these architectures for electronic warfare suites where harmonic suppression exceeds 60 dBc.
- Digital Synthesizers:FPGA-based frequency generation with numerically controlled oscillators enables real-time reconfiguration through software updates. China's 5G base station OEMs embed these cores for channel-agile massive MIMO implementations requiring sub-microsecond hopping.
- Direct Digital Synthesizers:Accumulator-and-lookup-table architectures from Analog Devices and Texas Instruments achieve nanosecond switching speeds for agile waveform generation.
- Phase-Locked Loop Synthesizers:Feedback-loop architectures with fractional-N dividers dominate aerospace applications where reference stability must exceed parts-per-billion accuracy.
Phase-Locked Loop Synthesizers lead on scale; Direct Digital Synthesizers lead on momentum.
Technology:
Equipment manufacturers select synthesis methodologies based on spurious-free dynamic range requirements and the trade-off between frequency resolution and switching latency.
- RF Synthesis:Heterodyne mixing of multiple reference frequencies generates microwave and millimeter-wave outputs through upconversion chains. United States test equipment vendors at Keysight Technologies deploy these architectures for spectrum analyzers covering 110 GHz with phase noise below −120 dBc per Hz at 1 MHz offset.
- Direct Frequency Synthesis:Crystal oscillator banks with diode-switching matrices produce coherent outputs without phase-locked loop settling delays. European satellite navigation receiver manufacturers favor these for BeiDou-3 and Galileo multi-constellation timing modules.
- Integer-N Synthesis:Whole-number divider ratios in PLL feedback paths minimize fractional spurs for clean spectral performance.
- Digital Frequency Synthesis:DSP-centric approaches with sigma-delta modulators enable fractional-N resolution without analog noise penalties.
RF Synthesis commands the largest installed base; Digital Frequency Synthesis gains share fastest in software-defined radio platforms.
Application:
Spectral regulatory frameworks and signal integrity standards dictate synthesizer selection across deployment environments with divergent electromagnetic compatibility requirements.
- Telecommunications:Base station transceivers demand low-jitter clocking for CPRI and eCPRI interfaces in 5G NR deployments. China's MIIT GB standards for cellular infrastructure mandate specific reference oscillator stability thresholds that filter non-compliant suppliers.
- Aerospace:Satellite payloads and airborne radar require radiation-hardened synthesizers with temperature-compensated reference stability. United States Department of Defense procurement specifications drive adoption of hermetically sealed OCXO-based designs.
- Broadcasting:ATSC 3.0 and DVB-T2 transmission systems require precise frequency control for orthogonal frequency-division multiplexing signal integrity.
- Test Equipment:Calibration laboratories and manufacturing test floors source modular synthesizers with automated amplitude and frequency sweep capabilities.
Telecommunications leads on volume deployment; Aerospace leads on unit value and qualification rigor.
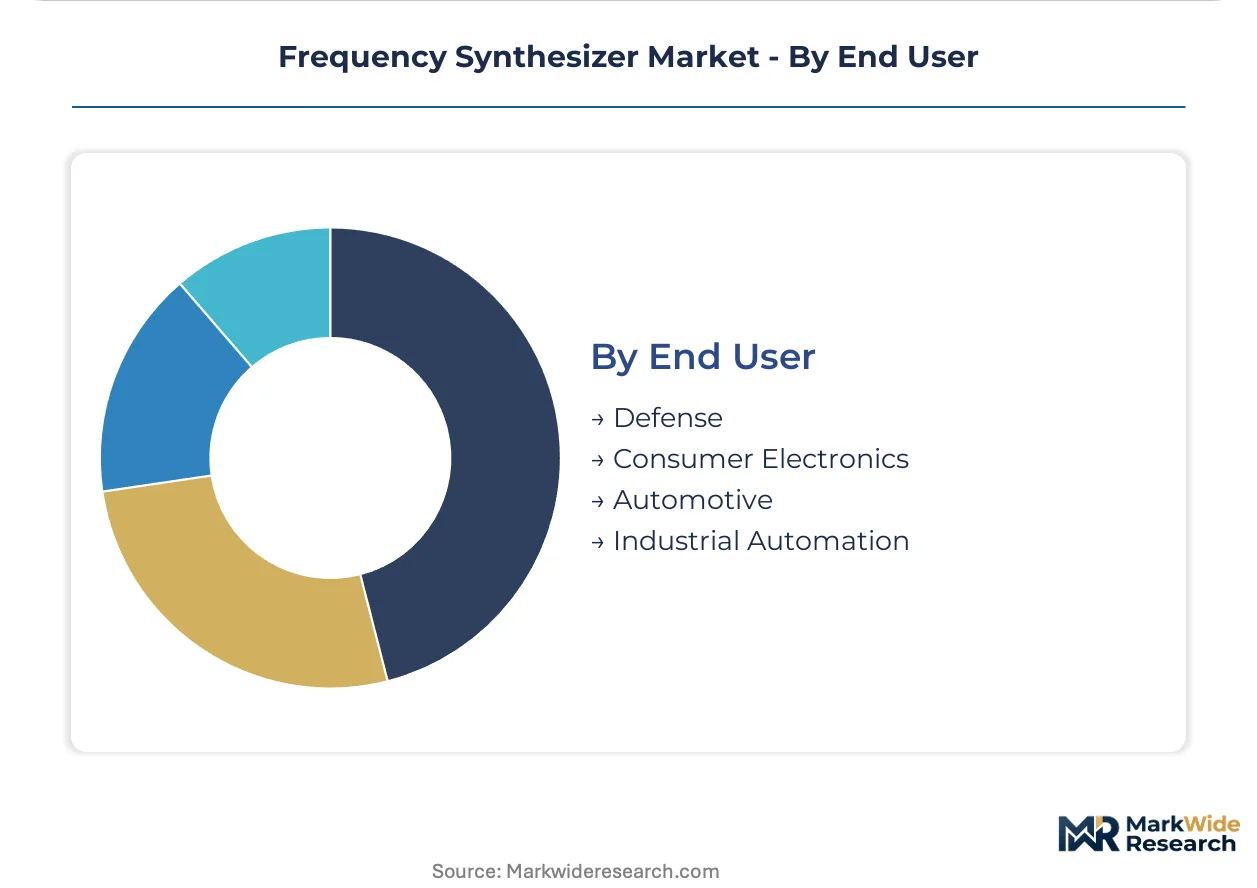
End User:
Procurement authority structures and offset policies shape vendor engagement models across defense primes, consumer electronics OEMs, automotive Tier 1s, and industrial automation integrators.
- Defense:Prime contractors including Lockheed Martin and Northrop Grumman source wideband synthesizers for electronic attack and signals intelligence platforms under ITAR-controlled supply chains. The United States Defense Advanced Research Projects Agency funds next-generation quantum-enhanced frequency reference programs.
- Consumer Electronics:Smartphone and Wi-Fi router manufacturers integrate CMOS-based synthesizers from Silicon Labs and Skyworks for cost-optimized connectivity subsystems.
- Automotive:V2X communication modules and radar-based ADAS sensors require automotive-grade synthesizers with AEC-Q100 qualification.
- Industrial Automation:Wireless sensor networks and precision motion control systems deploy synchronized frequency references for distributed timing.
Defense leads on contract value and technology specification; Automotive leads on qualification-driven growth as connected vehicle architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors frequency synthesizer demand through its concentration of 5G base station OEMs and telecommunications equipment exporters serving domestic and international markets.
United States
Defense primes in Maryland and Massachusetts drive procurement of wideband synthesizers for electronic warfare and radar modernization programs. The FCC's spectrum reallocation mandates push manufacturers toward millimeter-wave-capable designs above 40 GHz. Boston's Route 128 technology cluster houses test equipment vendors expanding calibration services for higher-frequency operation.
China
Beijing-Tianjin-Hebei's satellite navigation equipment manufacturers upgrade synthesis architectures to meet MIIT's GB standards for BeiDou-3 receiver stability. Yangtze River Delta base station OEMs embed direct digital synthesizer cores for massive MIMO implementations. Shenzhen's component distributors report concentrated demand from telecommunications infrastructure exporters.
Germany
Automotive Tier 1s in Bavaria integrate AEC-Q100 qualified synthesizers for V2X communication modules and radar-based ADAS sensors. The country's national telecommunications regulator enforces electromagnetic compatibility standards that filter non-compliant suppliers from cellular infrastructure tenders. Munich's industrial automation cluster deploys synchronized frequency references for precision motion control systems.
Japan
OCXO and TCXO production concentrates among precision crystal oscillator manufacturers serving global defense and aerospace supply chains. METI's industrial standards framework shapes reference oscillator stability requirements for satellite payload applications. Tokyo-Yokohama's RF component distributors manage extended lead times for high-purity oscillator inputs.
South Korea
Seoul Capital Area semiconductor foundries produce CMOS-based synthesizers for consumer electronics connectivity subsystems. The country's national spectrum regulator coordinates millimeter-wave band assignments that accelerate demand for synthesizers operating above 40 GHz. Busan-Ulsan's test equipment manufacturers expand automated calibration capabilities for telecommunications OEMs.
Frequency Synthesizer Market Vendor Landscape
Global majors compete with regional champions across defense procurement channels and telecommunications infrastructure tenders. The vendor base organizes around analog semiconductor heritage, precision clocking specialization, and test equipment integration capabilities. Three archetypes dominate: integrated semiconductor conglomerates with broad analog portfolios, RF-focused specialists with deep phase noise engineering expertise, and test equipment vendors with captive synthesis technology. Competitive moves concentrate on strategic partnerships with defense primes and portfolio diversification into software-defined radio platforms.
Among integrated semiconductor conglomerates, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions anchored by analog design heritage and precision clocking architectures. Texas Instruments exemplifies the broad-portfolio archetype serving defense contractor design-in relationships. Analog Devices represents the precision-timing specialist tier with fractional-N PLL implementations. Qorvo, Inc. sits within the RF-focused specialist category addressing higher-frequency millimeter-wave applications.
| Leading Market Players |
|---|
| Qorvo, Inc. |
| Renesas Electronics Corporation |
| Analog Devices, Inc. |
| Synergy Microwave Corporation |
| Mini-Circuits |
| Texas Instruments Incorporated |
| Keysight Technologies, Inc. |
| Microchip Technology |
| National Instruments Corporation |
| Others |
Supply Flow & Price Mechanics
China's MIIT-mandated reference oscillator stability thresholds for BeiDou-3 receivers are forcing synthesizer manufacturers to source higher-grade OCXO inputs from Japanese and Swiss suppliers, compressing margins on mid-tier telecommunications contracts while widening spreads on aerospace-qualified components.
Pricing Analysis
Input-cost pass-through from concentrated OCXO and TCXO suppliers in Japan and Switzerland is reshaping contract structures across the frequency synthesizer market. Pricing stratifies across aerospace-qualified, automotive-grade, and commercial tiers, with phase noise certification below −100 dBc per Hz commanding substantial premiums. Cost compression in commercial telecommunications segments is intensifying because Chinese base station OEMs consolidate procurement volumes. Defense contractors exhibit the least price sensitivity, prioritizing guaranteed supply and traceability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from United States defense primes and European automotive Tier 1s are fragmenting procurement across Japanese, Swiss, and South Korean crystal oscillator suppliers. High-purity quartz substrates, precision-machined resonator housings, and hermetic sealing materials draw from geographically concentrated specialty chemical and precision manufacturing clusters. Single-source vulnerability in OCXO production creates exposure to geopolitical friction and extended qualification cycles. Distribution runs through authorized distributors serving defense procurement channels and direct OEM relationships in telecommunications infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frequency synthesizer market functions as a stable compounder anchored by defense procurement cycles and telecommunications infrastructure refresh mandates that sustain demand across economic cycles.
For Market Incumbents: Extend fractional-N PLL design leadership into software-defined radio platforms through FPGA-integrated synthesis cores. Lock in multi-year supply agreements with Japanese OCXO manufacturers before geopolitical friction escalates input costs. Counter emerging RF CMOS specialists from South Korean foundries by accelerating AEC-Q100 qualification timelines for automotive radar applications. For New Entrants and Emerging Players: Enter via India's offset-driven defense modernization programs where local assembly mandates create captive production opportunities for foreign vendors. Target test equipment calibration services as the most penetrable segment, where Keysight and National Instruments maintain pricing power but lack agile service expansion. Pursue partnerships with Shenzhen-based telecommunications OEMs seeking qualified second-source synthesizer components for 5G base station exports. For Investors and Strategic Acquirers: Asymmetric upside sits with precision timing specialists possessing deep phase noise engineering benches and established ITAR-compliant supply chains. The five-to-ten-year viability window favors vendors with hybrid PLL-DDS architectures that span defense and commercial applications. Monitor FCC spectrum auction outcomes for millimeter-wave bands as the critical inflection signal for synthesizer demand above 40 GHz.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Development | Combines PLL stability with DDS switching speed for software-defined radio platforms at Lockheed Martin and Northrop Grumman. |
| Automotive Qualification Investment | AEC-Q100 certification unlocks V2X and ADAS sensor opportunities with Bavarian Tier 1 suppliers. |
| India Captive Production | Offset compliance enables defense procurement access under local assembly mandates from Delhi's Ministry of Defence. |
| Calibration Service Expansion | Boston test equipment vendors extend recurring revenue streams supporting FCC millimeter-wave transition. |
| FPGA Integration Partnership | Xilinx and Intel collaborations embed synthesis cores for channel-agile massive MIMO at Chinese base station OEMs. |
Methodological Framework
Bottom-up telecommunications and defense equipment modeling reconciled against top-down semiconductor component tracking forms the analytical core of this study. Primary interviews with RF design engineers at defense primes, procurement managers at base station OEMs, test equipment calibration specialists, and crystal oscillator manufacturing executives combined with secondary validation from FCC spectrum auction records, MIIT GB standard publications, ETSI electromagnetic compatibility frameworks, and SEC filings from Analog Devices and Texas Instruments.
Input-output matrices mapping synthesizer content per radar platform, base station transceiver, and spectrum analyzer unit across the analysis window generated volume and value estimates. Segmentation dimensions modeled include architectural approach, frequency generation method, deployment environment, and end-user certification standards. CAGRs were derived from equipment deployment schedules and component bill-of-materials analysis, with phase noise performance thresholds and switching speed requirements serving as key forecast inputs.
Inputs from defense procurement databases and telecommunications infrastructure deployment trackers were available through the study window; gaps in classified electronic warfare program specifications introduce uncertainty bands around military segment projections. Forecasts reflect assumptions regarding spectrum reallocation timelines and defense budget appropriations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RFID Tags Market
RF Components
5G Gain Block Amplifier Market
RF Components
RF Antenna Market
RF Components
433MHz Active RFID Reader Market
RF Components
RF Switches Market
RF Components
Radio Frequency Front End Market
RF Components
RF Acoustic Wave Filters Market
RF Components
Acoustic Wave Filters Market
RF Components
RF Transceiver Chip Market
RF Components
Latin America RFID Tags Market
RF Components
Digital Radio Frequency Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
Small Signal Mosfets Market
RF Components
Global RF Power Semiconductor Market
RF Components
China Small Signal Transistor Market
RF Components
Wi-Fi Module Market