
 RF Power Amplifiers Market | 2026-2036
RF Power Amplifiers Market Size, Share, and Industry Trends Forecast 2026-2036
RF Power Amplifiers Market Analysis
South Korea is tilting its semiconductor capacity toward RF compound semiconductor foundries serving power amplifier demand. Qorvo Inc. leverages vertical integration from wafer fabrication to module assembly for defense and telecom customers. MACOM Technology Solutions Holdings Inc. specializes in silicon-based alternatives for cost-sensitive wireless infrastructure deployments.
RF power amplifiers are electronic circuits that increase the power of radio-frequency signals to drive antenna loads, typically operating from hundreds of megahertz to millimeter-wave frequencies with output power ranging from milliwatts to kilowatts depending on application. Solid state amplifiers dominate commercial wireless infrastructure due to reliability and thermal efficiency, while traveling wave tube amplifiers retain structural importance in satellite downlink and high-power radar systems where kilowatt-scale output remains essential. Gallium nitride technology captures the fastest-growing margin pool as base station OEMs prioritize efficiency and bandwidth density over silicon bipolar legacy platforms.
The FCC enforces stringent spectral efficiency and out-of-band emission standards that force amplifier redesigns for US telecom deployments, while ETSI harmonizes power amplifier test protocols across European member states for cross-border equipment certification. China's MIIT mandates domestic GaN supply chain qualification for 5G infrastructure tenders, reshaping vendor eligibility. Stakeholders must monitor evolving spectrum auction schedules and material export controls to calibrate technology roadmaps and geographic sourcing strategies.
Market Dynamics
GaN-on-SiC technology is collapsing the cost-performance frontier for macro base station power amplifiers, forcing incumbent silicon LDMOS suppliers to accelerate qualification timelines or surrender share in the most profitable frequency bands.
Growth Catalysts
- 5G-Advanced spectrum mandates:China's MIIT has assigned additional millimeter-wave bands for 5G-Advanced deployment, requiring new amplifier architectures capable of linearizing wider modulation bandwidths.
- Defense radar modernization:Active electronically scanned array upgrades across NATO member states are consuming GaN monolithic microwave integrated circuits for phased-array transmit modules.
- Semiconductor foundry clustering:South Korea's Pyeongtaek corridor is expanding dedicated GaN epitaxy capacity to serve fabless RF design houses.
Market Restraints
- Substrate supply concentration:Silicon carbide substrates for GaN-on-SiC amplifiers depend on a concentrated supplier base in Japan and the United States.
- Capital intensity threshold:GaN epitaxy equipment requires cleanroom investments that exclude mid-tier contract manufacturers from technology migration.
- Thermal management complexity:Kilowatt-scale solid-state amplifiers face fundamental heat dissipation limits that preserve traveling wave tube relevance for satellite downlink terminals.
Strategic Opportunities
- Open RAN disaggregation:Virtualized baseband architectures are decoupling amplifier procurement from integrated radio unit sourcing, enabling direct component sales to neutral host operators.
- Dual-use technology convergence:Commercial GaN processes qualified for telecom efficiency standards are penetrating military electronic warfare systems with minimal redesign.
- India's PLI scheme:Production-linked incentives for telecom equipment manufacturing are attracting module assembly investments to offset tariff exposure.
Industry Challenges
- Compound semiconductor talent scarcity:GaN device physics expertise concentrates within a limited pool of engineers trained at specific university-industry partnerships.
- Multi-band certification timelines:FCC and ETSI test protocols for carrier aggregation configurations extend product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Power Amplifiers Market |
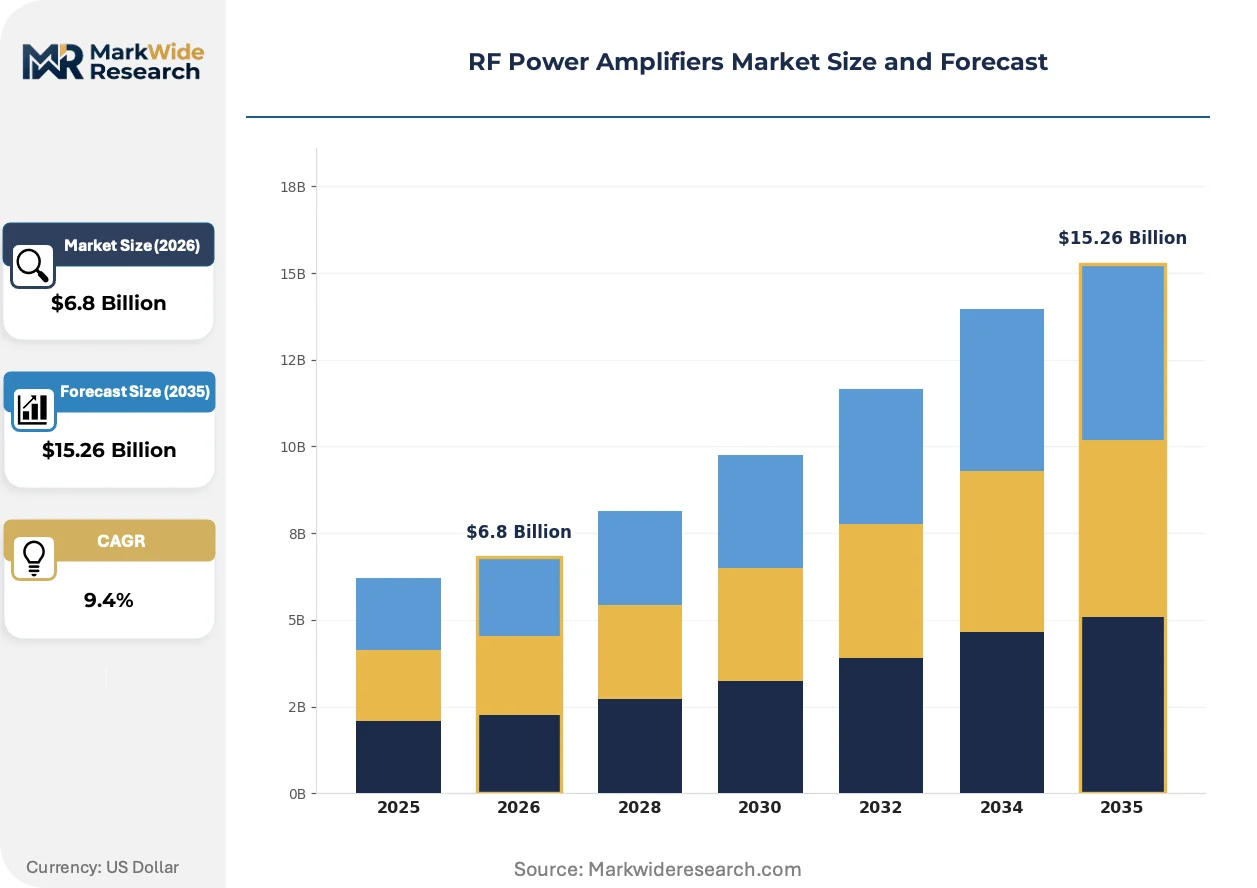
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State, Traveling Wave Tube, Hybrid, Electron Tube Technology: Gallium Nitride, Gallium Arsenide, Silicon Carbide, Silicon Bipolar Application: Wireless Infrastructure, Radar Systems, Satellite Communication, Test & Measurement Equipment End User: Telecom Equipment Manufacturers, Defense Contractors, Broadcasting Companies, Space Agencies |
| Companies Covered | Analog Devices Inc., Skyworks Solutions Inc., Qorvo Inc., MACOM Technology Solutions Holdings Inc., Renesas Electronics Corporation, Broadcom Ltd., Infineon Technologies AG, Wolfspeed, NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Power Amplifiers Market Emerging Trajectories
Digital pre-distortion algorithms and envelope tracking techniques are converging with widebandgap semiconductors to redefine amplifier efficiency benchmarks across terrestrial and satellite platforms.
GaN high-electron-mobility transistors are collapsing the historical trade-off between operating frequency and power density in macro base station transmit chains. Tier-one telecom equipment manufacturers are qualifying these devices for 3.5 GHz and 28 GHz massive MIMO arrays. The technology is collapsing the addressable market for silicon LDMOS above 2 GHz as OEMs prioritize efficiency over legacy platform familiarity.
The FCC's out-of-band emission rules for 5G NR are forcing amplifier redesigns to suppress adjacent channel leakage ratios below stringent thresholds. Base station OEMs must retune linearization architectures or risk certification delays for US market entry. High-power macro deployments face the most severe compliance pressure, driving demand for advanced digital pre-distortion chipsets.
Neutral host infrastructure operators are unbundling amplifier procurement from traditional radio unit vendor relationships. Tower companies and private network deployers now source power amplifier modules directly from component specialists, bypassing integrated equipment suppliers. This pattern concentrates in North American and European markets where open interface specifications have gained regulatory endorsement.
RF Power Amplifiers Market Segmentation
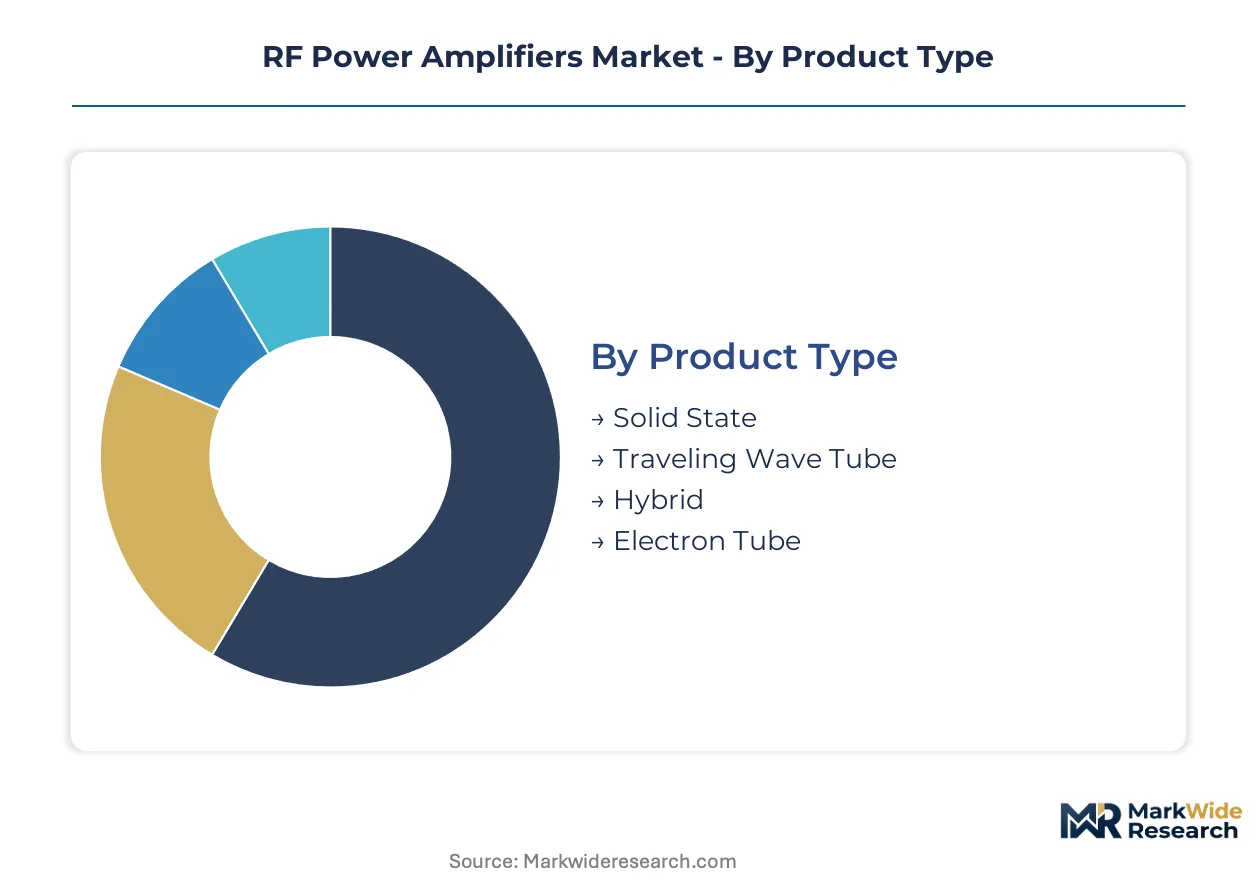
RF power amplifier procurement patterns diverge sharply across deployment contexts, with after-sales service intensity ranging from minimal for commodity solid-state modules to extensive field engineering for satellite ground terminals. Component selection hinges on thermal management requirements, spectral compliance mandates, and qualification timelines that vary by end-use sector.
Product Type:
After-sales service intensity escalates from solid-state replacements to traveling wave tube refurbishment programs requiring specialized vacuum facilities.
- Solid State:Transistor-based architectures using GaN or LDMOS devices dominate commercial wireless infrastructure. South Korean foundries in Pyeongtaek supply the majority of epitaxial wafers for 5G macro base station deployments facing FCC efficiency mandates.
- Traveling Wave Tube:Vacuum electron devices deliver kilowatt-scale output for satellite downlink terminals and high-power radar systems. Japan and the United States concentrate the limited supplier base for these thermionic amplifiers.
- Hybrid:Combines solid-state driver stages with tube output sections for intermediate power applications in legacy broadcasting transmitters.
- Electron Tube:Remains relevant for specialized industrial heating and scientific applications requiring extreme power density.
Solid State holds the largest share; momentum sits with Traveling Wave Tube in satellite communication refresh cycles.
Technology:
Cost tiers separate wide-bandgap compound semiconductors from mature silicon platforms, with qualification expenses determining accessible market tiers.
- Gallium Nitride:GaN high-electron-mobility transistors achieve superior power density and efficiency for massive MIMO arrays. China's MIIT mandates domestic supply chain qualification for 5G-Advanced infrastructure tenders, reshaping vendor eligibility.
- Gallium Arsenide:GaAs pseudomorphic HEMTs retain dominance in handset power amplifiers and low-noise receive chains below 6 GHz.
- Silicon Carbide:SiC substrates enable GaN epitaxy for high-voltage RF applications; substrate supply concentrates in Japanese and American vendors.
- Silicon Bipolar:Silicon LDMOS persists in cost-optimized sub-2 GHz installations where efficiency requirements remain less stringent.
Silicon Bipolar retains volume leadership in installed base; Gallium Nitride gains share fastest in new 5G-Advanced deployments.
Application:
Customer type differentiation separates capital-intensive infrastructure operators from project-driven defense procurement cycles.
- Wireless Infrastructure:Macro base stations and small cells consume the majority of high-power amplifiers. Neutral host operators in North America and Europe now source modules directly from component specialists, bypassing integrated radio unit vendors.
- Radar Systems:Active electronically scanned arrays for NATO defense modernization programs drive GaN MMIC demand for phased-array transmit modules.
- Satellite Communication:Ground station terminals and space-qualified payloads require radiation-hardened amplifiers with extensive qualification documentation.
- Test & Measurement Equipment:Broadband signal generators and vector network analyzers demand linear amplifiers with minimal harmonic distortion.
Wireless Infrastructure commands the largest revenue pool; Satellite Communication shows steepest expansion trajectory from low-earth-orbit constellation deployments.
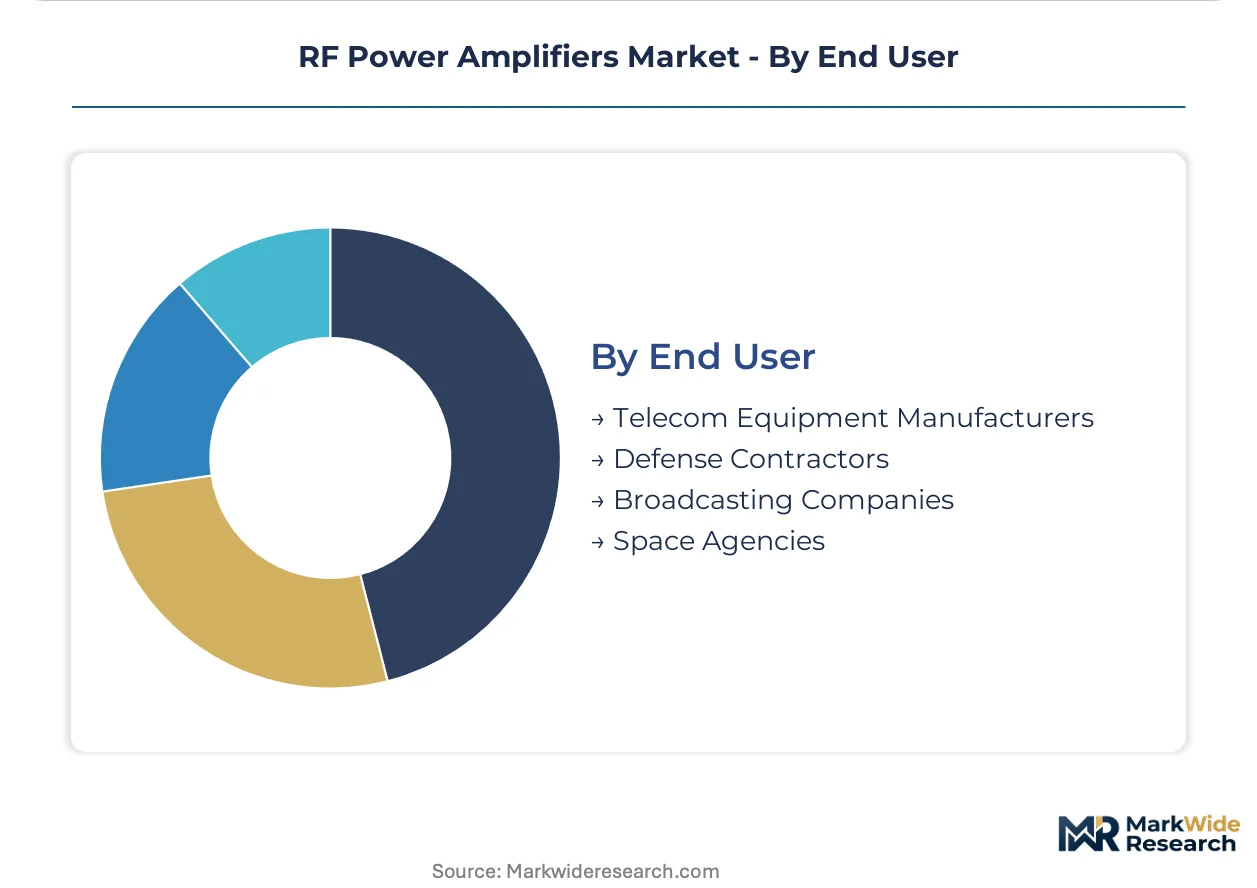
End User:
Margin structures vary dramatically between price-sensitive telecom volume procurement and cost-plus defense contracting mechanisms.
- Telecom Equipment Manufacturers:Ericsson, Nokia, and Samsung Networks drive qualification roadmaps for 5G radio units. Open RAN disaggregation enables direct amplifier procurement from fabless design houses.
- Defense Contractors:Raytheon, Lockheed Martin, and BAE Systems integrate GaN modules into electronic warfare and radar platforms with dual-use technology convergence from commercial telecom processes.
- Broadcasting Companies:Television and radio transmitters transition from tube-based to solid-state architectures for operating cost reduction.
- Space Agencies:NASA, ESA, and national programs impose rigorous qualification protocols for radiation-tolerant amplifiers in orbital environments.
Telecom Equipment Manufacturers represent the largest addressable base; Defense Contractors offer the highest margin capture per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GaN epitaxy capacity clusters around Pyeongtaek in South Korea, while substrate supply concentrates among Japanese and American vendors. Regulatory mandates in Washington, Beijing, and Brussels reshape procurement patterns across three continents.
United States
The FCC enforces stringent out-of-band emission standards for 5G NR deployments, forcing amplifier redesigns to suppress adjacent channel leakage. Defense radar modernization programs consume GaN monolithic microwave integrated circuits for phased-array transmit modules. Boston-area defense contractors and California-based fabless design houses anchor the dual-use technology convergence.
China
MIIT mandates domestic GaN supply chain qualification for 5G-Advanced infrastructure tenders, reshaping vendor eligibility for millimeter-wave base station deployments. The country's dual carbon goals intensify efficiency requirements for telecom equipment. Shenzhen and Beijing host the principal design centers serving state-backed carrier procurement cycles.
South Korea
Samsung Networks drives qualification roadmaps for massive MIMO arrays at 3.5 GHz and 28 GHz. Government-backed semiconductor initiatives expand dedicated GaN epitaxy capacity in the Pyeongtaek corridor. The foundry cluster now serves fabless RF design houses from across East Asia.
Germany
ETSI harmonizes power amplifier test protocols across European member states for cross-border equipment certification. Automotive radar integration for autonomous driving systems creates secondary demand for high-frequency amplification. Munich and Stuttgart anchor the industrial electronics supply chain serving both telecom and automotive verticals.
Japan
METI coordinates national investment in wide-bandgap semiconductor manufacturing infrastructure. Domestic vendors concentrate silicon carbide substrate production for GaN-on-SiC amplifiers. The Kyushu region hosts specialized facilities serving satellite communication and high-power radar applications.
RF Power Amplifiers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete amplifiers and modules to neutral host operators. The vendor base spans vertically integrated semiconductor conglomerates, fabless RF design houses, and specialized substrate manufacturers. Three archetypes dominate: epitaxy-capable foundries, module assembly specialists, and silicon-alternative advocates. Capacity expansion in South Korean foundries and strategic partnerships around Open RAN interfaces constitute the primary competitive vectors.
Among American semiconductor conglomerates, Analog Devices Inc., Skyworks Solutions Inc., and Qorvo Inc. occupy positions across the amplification chain from wafer fabrication through module assembly. These entities exemplify the vertical integration archetype serving defense and telecom customers with divergent procurement cycles. Their geographic concentration in Massachusetts, California, and North Carolina reflects historical defense electronics clustering and subsequent commercial telecom expansion.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Skyworks Solutions Inc. |
| Qorvo Inc. |
| MACOM Technology Solutions Holdings Inc. |
| Renesas Electronics Corporation |
| Broadcom Ltd. |
| Infineon Technologies AG |
| Wolfspeed |
| NXP Semiconductors N.V. |
| Others |
Supply Flow & Price Mechanics
Silicon carbide substrate concentration in Japanese and American vendors determines both pricing tier spreads and supply chain shape, forcing amplifier OEMs into long-term offtake commitments or tariff-exposed spot procurement. FCC efficiency mandates and China's MIIT domestic qualification rules amplify cost differentials between certified and uncertified supply channels.
Pricing Analysis
FCC out-of-band emission standards dictate the pricing tier structure for 5G macro base station amplifiers, separating premium-tier GaN-on-SiC modules with advanced digital pre-distortion from standard silicon LDMOS alternatives. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with neutral host operators in North America showing highest price sensitivity due to disaggregated procurement models. Cost compression in the standard tier is intensifying because South Korean foundry expansion is collapsing GaN epitaxy costs. Defense contractors remain least price-sensitive, absorbing premium pricing for radiation-hardened satellite communication amplifiers.
Supply Chain Analysis
Samsung Foundry and key Pyeongtaek corridor facilities hold the majority of GaN epitaxy capacity for commercial wireless infrastructure, while Wolfspeed and Japanese substrate vendors anchor silicon carbide supply. Raw material dependencies center on high-purity gallium metal, silicon carbide boules, and specialized ceramic packaging materials. Single-source vulnerability concentrates in SiC substrate supply, where Japanese and American vendors control qualification pathways for defense-grade applications. Distribution runs through integrated radio unit OEMs for traditional telecom procurement, with direct module sales to neutral host operators emerging as a parallel channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN device physics expertise pools within a narrow band of university-industry partnerships, constraining technology migration speed and amplifying acquisition premiums for qualified engineering teams. This scarcity dynamic rewards early capability-building investments and penalizes delayed market entry.
For Market Incumbents: Harden supply chain position through captive GaN epitaxy capacity in South Korea or backward integration into silicon carbide substrate sourcing. Accelerate FCC pre-certification programs for 5G-Advanced architectures before China's MIIT tenders reshape vendor eligibility. Lock in long-term offtake agreements with Pyeongtaek foundries to neutralize emerging fabless competitors.
For New Entrants and Emerging Players: India's PLI scheme for telecom equipment manufacturing offers the most penetrable geographic entry point, with tariff-offset module assembly attracting first-mover investments. Target private network deployers and neutral host operators in North American markets where Open RAN disaggregation has broken integrated vendor lock-in. Pursue direct component sales bypassing traditional radio unit OEMs as the primary go-to-market angle.
For Investors and Strategic Acquirers: Fabless RF design houses with qualified GaN process libraries represent the priority acquisition archetype, offering technology leverage without capital-intensive cleanroom investments. Long-term viability hinges on dual-use technology convergence trajectories spanning commercial telecom and defense electronic warfare applications. Monitor FCC spectrum auction schedules and China's MIIT tender timelines as inflection indicators for demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Epitaxy Capacity Expansion | South Korea's Pyeongtaek corridor investments serve fabless design houses across East Asia. |
| Silicon Carbide Backward Integration | Captive substrate supply neutralizes Japanese and American vendor concentration risk. |
| FCC Pre-Certification Investment | Early compliance with out-of-band emission rules secures US market entry timing. |
| Open RAN Module Direct Sales | Neutral host procurement bypasses integrated radio unit vendor relationships. |
| Dual-Use Process Qualification | Commercial telecom GaN platforms penetrate NATO defense radar modernization programs. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with RF design engineers at fabless houses, procurement leads at telecom equipment manufacturers, and GaN process specialists at South Korean foundries contributing operational data. Secondary validation drew from FCC equipment authorization databases, MIIT tender documentation, SEC 10-K filings of listed semiconductor conglomerates, and ETSI harmonized standards publications. Bottom-up unit economics triangulated against top-down addressable market sizing to anchor volume and value estimates.
Calibration against historical qualification timelines and foundry capacity ramp patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, compound semiconductor technology, deployment application, and end-user procurement mechanism. CAGRs derived from installed base replacement cycles and 5G-Advanced spectrum rollout schedules, with GaN penetration curves and silicon LDMOS erosion rates serving as primary industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed semiconductor initiatives or accelerated Open RAN regulatory mandates would shift outcomes materially. Cross-checking against FCC equipment authorization approval rates and MIIT tender award disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Power Detector Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Latin America RFID Tags Market
RF Components
Global Inductors Market
RF Components
LTCC Power Dividers Market
RF Components
Europe Small Signal Transistor Market
RF Components
Global RF Power Semiconductor Market
RF Components
Radio Frequency Front End Market
RF Components
Radio Frequency Components Market
RF Components
Digital Radio Frequency Market
RF Components
RF Passive Component Market
RF Components
Phase Shifters Market
RF Components
Global RF Plasma Generator Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
RF Tester Market
RF Components
Dielectric Resonator Market