
 Americas Small Signal Transistor Market | 2026-2036
Americas Small Signal Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Small Signal Transistor Market Insights
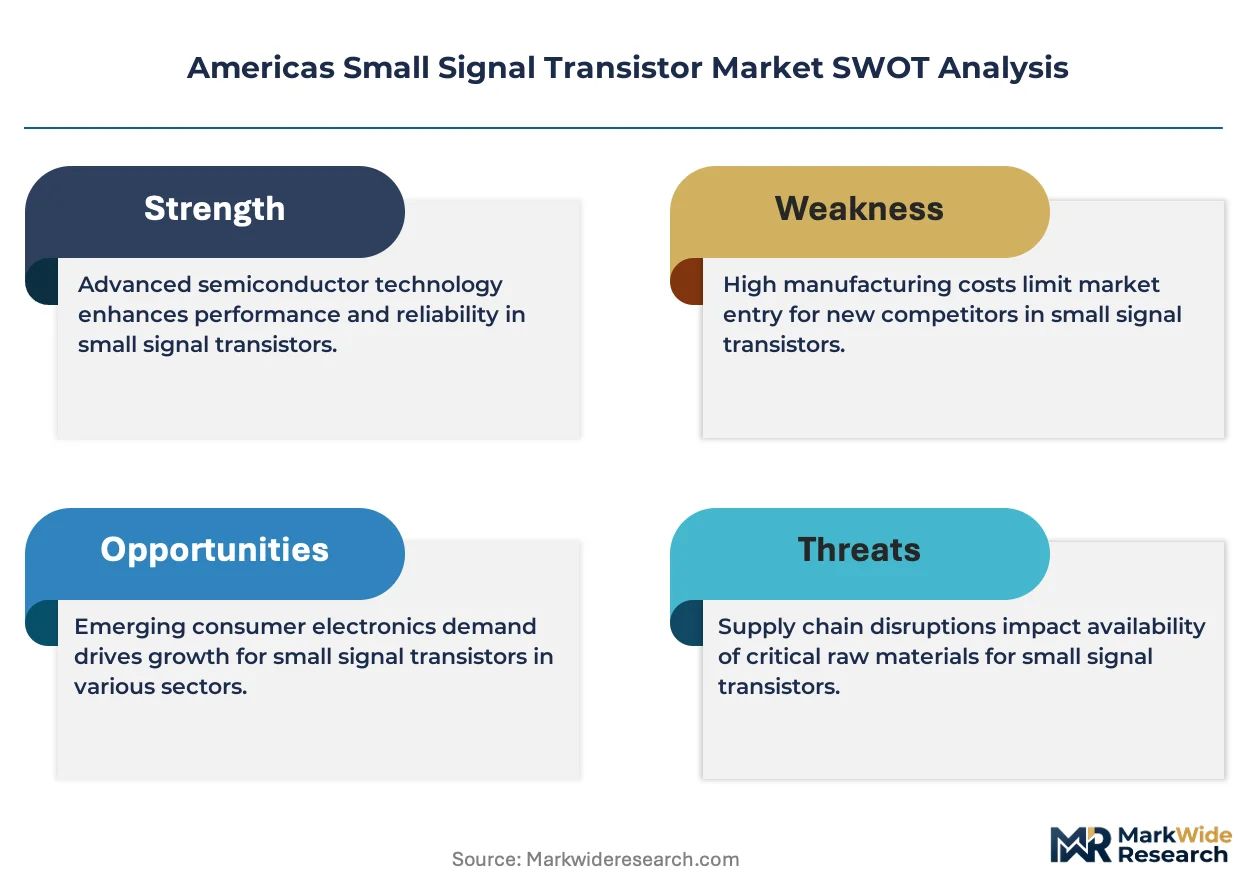
Asset-light foundry partnerships and fabless leasing arrangements is reconfiguring competitive entry barriers for smaller transistor specialists. Texas Instruments leverages captive fabrication in Sherman, Texas to sustain margin control across analog small-signal lines. NXP Semiconductors N.V. anchors its Americas position through automotive-qualified BJT and MOSFET portfolios. Diodes Inc. competes via aggressive backward integration into wafer-level packaging for cost-sensitive consumer applications.
Small signal transistors are low-power semiconductor devices engineered to amplify, switch, or buffer electronic signals below one watt, typically fabricated on silicon or silicon-germanium substrates with sub-micron channel geometries and operating frequencies from DC through several gigahertz. These components serve as fundamental building blocks in precision analog circuits, RF front-ends, and sensor interfaces where noise figure and linearity outweigh raw power handling. Bipolar junction transistors retain structural dominance in audio equipment and precision signal processing applications where low-noise performance commands premium positioning. Field-effect transistors, particularly enhancement-mode MOSFETs, represent the fastest-expanding category within RF amplification and power management circuits across telecommunications infrastructure deployments. Surface mount packaging now occupies the majority of unit volume, though through-hole formats persist in industrial equipment requiring manual serviceability and extended thermal cycling reliability.
FCC equipment authorization requirements shape RF transistor specifications for wireless applications across the United States, while Mexico's national standards body enforces electromagnetic compatibility testing that gates market access for imported semiconductor components. The U.S. CHIPS and Science Act directs subsidy flows toward domestic small-signal device fabrication, altering foundry location decisions for fabless suppliers serving automotive and industrial end users. Stakeholders must monitor how evolving EPA hazardous substance rules and state-level extended producer responsibility frameworks reshape packaging material choices and end-of-life recovery obligations across the Americas supply base.
Market Dynamics
The U.S. CHIPS Act subsidy flows are redirecting foundry location decisions, concentrating domestic fabrication capacity in Texas and Arizona while Mexico's electronics corridor absorbs fabless assembly demand. This policy-driven supply reconfiguration is compressing lead times for automotive-qualified devices.
Growth Catalysts
- Automotive electronics adoption:Electric vehicle powertrain controls and advanced driver-assistance systems consume precision small-signal transistors for sensor interfaces and signal conditioning across U.S. and Mexican assembly plants.
- Federal semiconductor incentives:The CHIPS and Science Act directs capital toward domestic small-signal fabrication, altering foundry economics for suppliers serving industrial and automotive end users in the Americas.
- RF infrastructure deployment:5G base station buildouts and private wireless networks in Brazil and Canada drive demand for low-noise MOSFETs in millimeter-wave front-end modules.
Market Restraints
- Silicon wafer cost volatility:Raw substrate prices fluctuate with energy costs and polysilicon supply constraints, squeezing margin structures for commodity small-signal devices.
- Foundry concentration risk:Advanced node capacity concentrates among three Taiwanese and South Korean suppliers, exposing Americas-based fabless designers to geopolitical supply disruption.
- Discrete component substitution:Integrated RF front-end modules and system-on-chip designs displace individual transistor placements in consumer electronics.
Strategic Opportunities
- Underpenetrated Brazilian industrial automation:Factory modernization programs create demand for ruggedized small-signal switching in programmable logic controllers and motor drives.
- Silicon-germanium process convergence:SiGe BiCMOS integration enables RF performance previously requiring III-V compound semiconductors, opening cost-reduced millimeter-wave applications.
- Extended producer responsibility frameworks:California and Canadian provincial e-waste mandates drive premium pricing for recyclable packaging and lead-free termination finishes.
Industry Challenges
- Analog design talent scarcity:Specialized RF transistor characterization and noise optimization expertise concentrates among aging engineers, constraining new product development pipelines.
- Automotive qualification timelines:AEC-Q101 stress testing and PPAP documentation cycles extend 18-24 months, delaying revenue recognition for new device introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Small Signal Transistor Market |
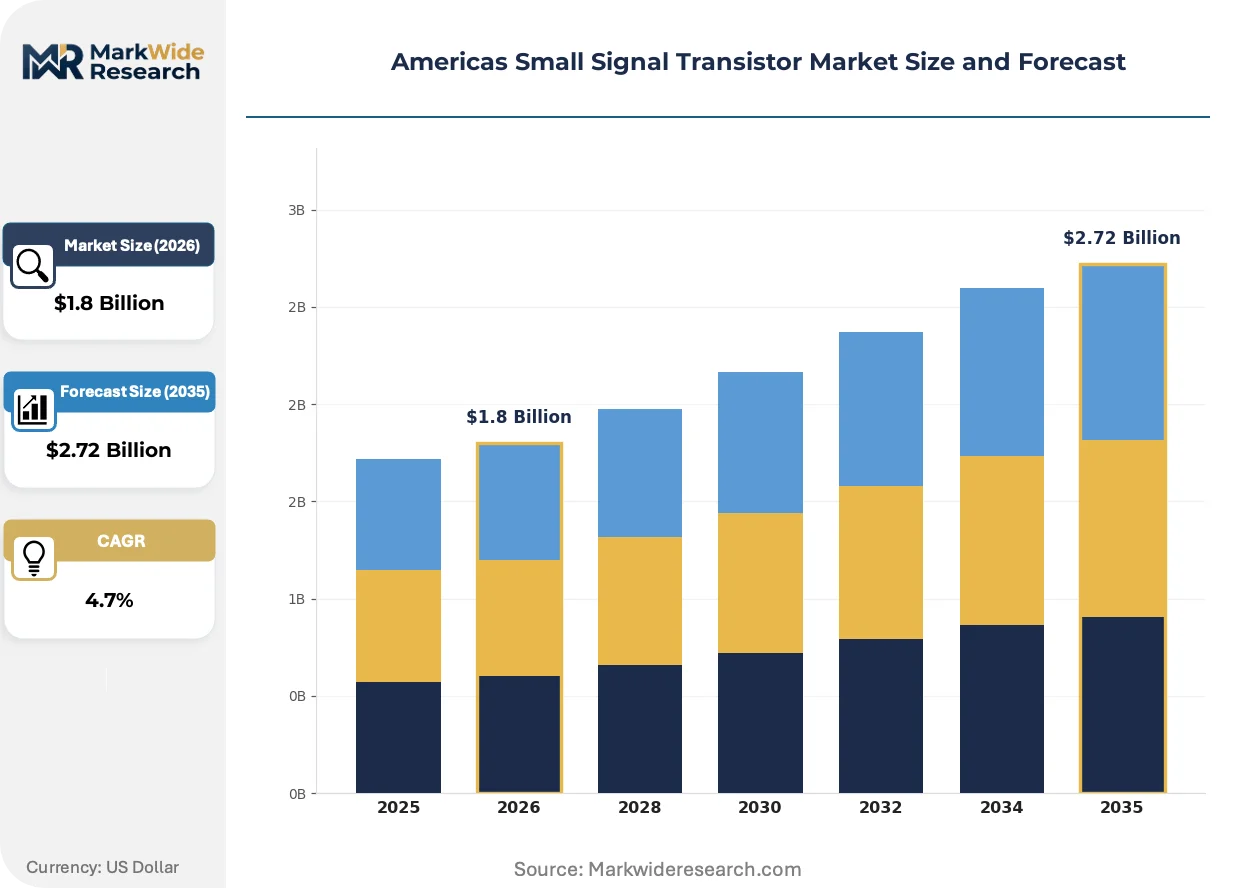
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field-Effect Transistor, Darlington Transistor, Phototransistor End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Application: Audio Equipment, Signal Processing, RF Amplification, Power Management Packaging Type: Surface Mount, Through-Hole, Chip-on-Board, Dual-In-Line |
| Companies Covered | Microchip Technology Inc., NXP Semiconductors N.V, Semiconductor Components Industries, LLC (Onsemi), Diodes Inc., Central Semiconductors Corporation, Texas Instruments Incorporated, STMicroelectronics N.V., Infineon Technologies AG, Renesas Electronics Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Small Signal Transistor Market Trends and Innovations
Process geometry scaling and heterogeneous integration are compressing traditional discrete transistor applications while opening specialized high-frequency niches. Three developments are actively restructuring competitive positioning.
Silicon-germanium heterojunction bipolar transistor technology delivers cutoff frequencies exceeding 300 GHz with CMOS-compatible manufacturing. 5G infrastructure OEMs and satellite terminal manufacturers are adopting SiGe BiCMOS for millimeter-wave power amplifiers. This integration trajectory is rendering obsolete discrete III-V compound transistor sockets below 100 GHz in commercial telecommunications equipment.
The U.S. EPA hazardous substance rules and state-level extended producer responsibility frameworks are reshaping packaging material specifications. RoHS-compliant lead-free solders and halogen-free mold compounds now dominate new designs. Automotive and industrial equipment segments face the steepest compliance cost escalations as they retrofit legacy through-hole product lines.
Direct procurement from foundry-qualified distributors is displacing traditional catalog-based component purchasing. Tier-one automotive and telecommunications OEMs now negotiate wafer-level supply agreements, bypassing standard distribution markups. This channel compression is most visible in Mexico's electronics manufacturing corridor, where contract manufacturers consolidate purchasing across Tijuana and Guadalajara facilities.
Americas Small Signal Transistor Market Segmentation
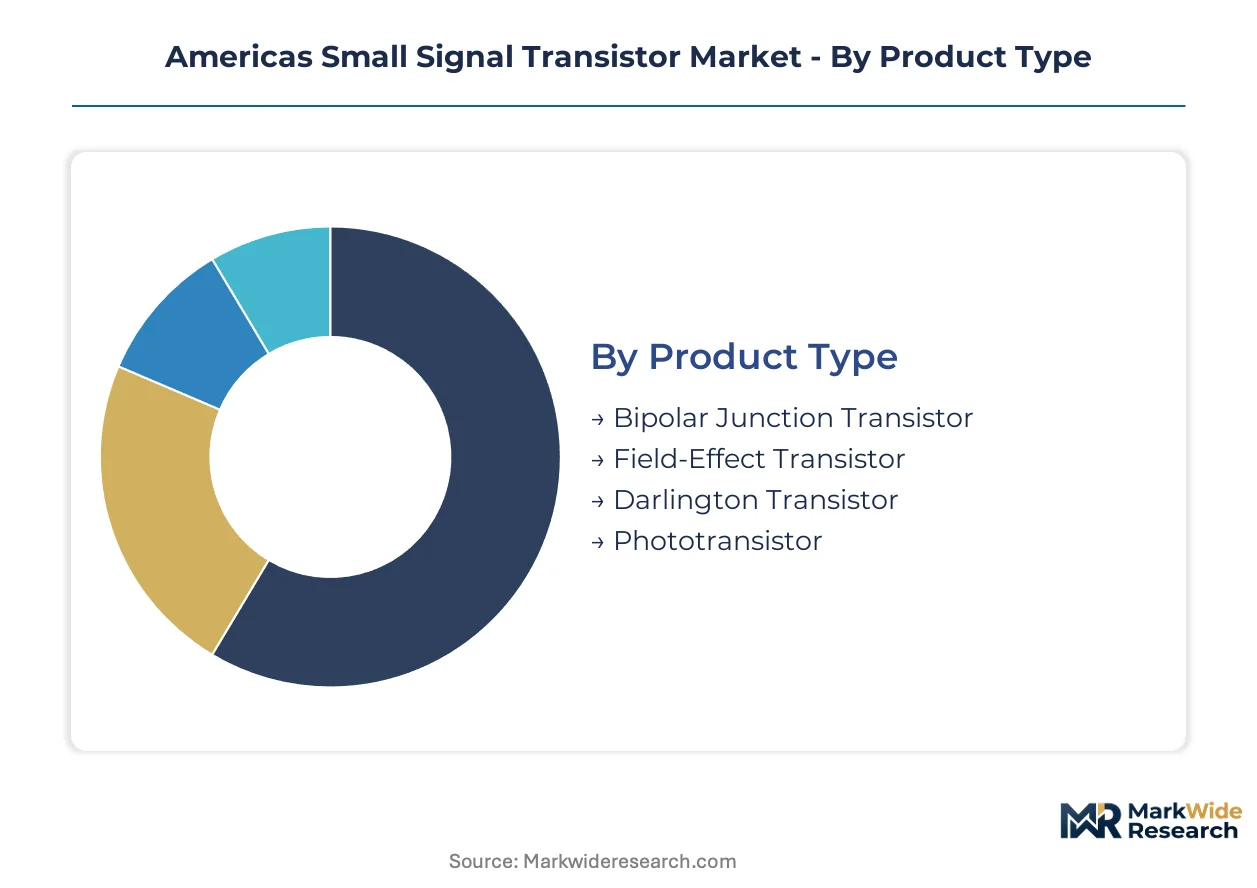
Segmentation reveals how small signal transistor demand fragments across competing technologies, end-use priorities, and manufacturing formats. Each dimension carries distinct margin structures and qualification barriers that reshape supplier economics across the Americas.
Product Type:
Cost tier stratification separates premium RF performance from commodity switching applications, with process complexity determining foundry allocation and pricing power.
- Bipolar Junction Transistor:Silicon-based vertical structures deliver superior transconductance and low-noise figures for precision analog circuits. Automotive sensor interfaces and professional audio equipment in Michigan and Tennessee assembly plants consume AEC-Q101-qualified BJTs for signal conditioning.
- Field-Effect Transistor:Enhancement-mode MOSFETs operate with negligible gate current and scalable threshold voltages suited to battery-powered designs. 5G base station deployments across Brazil and private wireless networks in Canada drive GaAs-compatible low-noise MOSFET demand for millimeter-wave front-ends.
- Darlington Transistor:Cascaded bipolar pairs achieve current gains exceeding 1000x in single packages, serving high-impedance sensor buffers.
- Phototransistor:Light-sensitive base regions enable optoisolation in industrial control systems and medical diagnostic equipment.
BJT holds installed capacity across legacy automotive platforms. FET is rotating up the share rankings on RF infrastructure deployment.
End User:
Application maturity determines procurement sophistication, with automotive and telecommunications buyers commanding wafer-level supply agreements that bypass standard distribution.
- Consumer Electronics:Smartphone audio codecs, wearable sensor hubs, and smart home devices require sub-milliwatt switching in miniature footprints. Mexico's Tijuana and Guadalajara contract manufacturers consolidate purchasing for cost-sensitive consumer assemblies.
- Automotive:Electric vehicle battery management systems and ADAS camera modules demand AEC-Q101-qualified devices with PPAP documentation. Texas and Arizona fab expansions under CHIPS Act subsidies concentrate domestic supply for Detroit and Mexico City automotive clusters.
- Telecommunications:Base station transceivers and satellite ground terminals consume low-noise amplifiers with sub-1 dB noise figures.
- Industrial Equipment:Programmable logic controllers and motor drives specify extended temperature ranges and enhanced moisture resistance.
Automotive holds installed capacity through qualification-locked supply relationships. Telecommunications is climbing the fastest on 5G capital expenditure cycles.
Application:
Performance specifications diverge sharply between precision analog domains and high-frequency RF, with each application imposing distinct characterization requirements.
- Audio Equipment:Discrete BJTs dominate high-fidelity preamplifiers and mixing consoles where harmonic distortion below 0.001% commands premium positioning. Nashville and Los Angeles studio equipment manufacturers specify matched transistor pairs for differential stages.
- Signal Processing:Operational amplifier input stages and active filters demand tight VBE matching and temperature coefficient stability. Industrial automation controllers in São Paulo and Monterrey integrate precision signal conditioning for process variable acquisition.
- RF Amplification:Low-noise amplifiers and power amplifier driver stages operate through millimeter-wave frequencies.
- Power Management:Linear regulators and load switches prioritize low dropout voltage and fast transient response.
Audio Equipment holds installed capacity through enthusiast and professional segment loyalty. RF Amplification is gaining share fastest on wireless infrastructure buildouts.
Packaging Type:
Manufacturing format determines assembly automation compatibility and thermal management, with surface mount dominance challenged by serviceability requirements in heavy industrial settings.
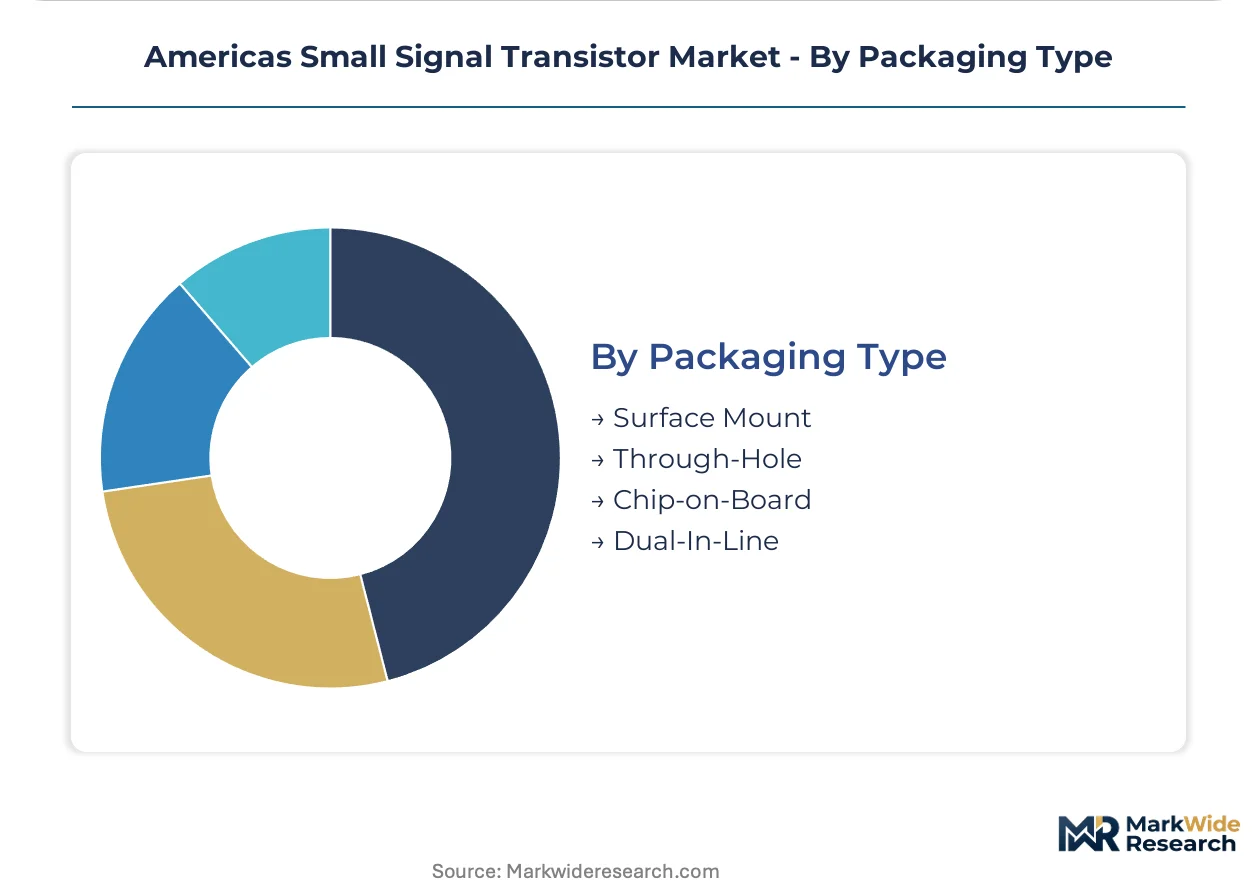
- Surface Mount:Tape-and-reel delivery enables high-speed pick-and-place assembly for consumer and automotive volume production. Mexico's electronics corridor runs predominantly SMT lines for smartphone and telematics module assembly.
- Through-Hole:Axial and radial leaded formats survive in replacement markets and equipment requiring manual soldering repair. Brazilian agricultural machinery and Canadian oilfield instrumentation specify through-hole devices for field serviceability.
- Chip-on-Board:Bare die attachment minimizes parasitic inductance for high-frequency RF modules.
- Dual-In-Line:Legacy socketed formats persist in educational equipment and prototyping systems.
Surface Mount holds installed capacity across volume manufacturing. Chip-on-Board is expanding most quickly on heterogeneous integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. CHIPS Act subsidy flows are redirecting foundry location decisions, concentrating domestic fabrication capacity in Texas and Arizona while Mexico's electronics corridor absorbs fabless assembly demand. This policy-driven supply reconfiguration is compressing lead times for automotive-qualified devices across North American automotive clusters.
United States
Electric vehicle powertrain controls and ADAS camera modules in Michigan and Tennessee assembly plants consume precision small-signal transistors for sensor interfaces. The FCC equipment authorization requirements shape RF transistor specifications for wireless applications. Texas Instruments leverages captive fabrication in Sherman, Texas to sustain margin control across analog small-signal lines.
Mexico
Contract manufacturers in Tijuana and Guadalajara consolidate purchasing for cost-sensitive consumer electronics and telematics modules. The national standards body enforces electromagnetic compatibility testing that gates market access for imported semiconductor components. Mexico's electronics manufacturing corridor near Tijuana and Guadalajara absorbs fabless assembly demand from U.S. designers.
Canada
Private wireless networks and satellite ground terminals drive demand for low-noise MOSFETs in millimeter-wave front-end modules. Provincial e-waste mandates in Ontario and Quebec drive premium pricing for recyclable packaging and lead-free termination finishes. Canadian oilfield instrumentation in Alberta specifies through-hole devices for field serviceability.
Brazil
Factory modernization programs create demand for ruggedized small-signal switching in programmable logic controllers and motor drives. ANVISA regulates medical diagnostic equipment incorporating phototransistors for optoisolation. São Paulo industrial automation controllers integrate precision signal conditioning for process variable acquisition.
Americas Small Signal Transistor Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated device manufacturers with captive fabrication, fabless specialists leveraging foundry partnerships, and discrete component distributors consolidating purchasing power. Texas Instruments and NXP Semiconductors anchor the captive-fabrication tier with automotive-qualified portfolios. Diodes Inc. occupies the aggressive backward-integration position for cost-sensitive consumer applications. The dominant competitive moves are wafer-level supply agreements bypassing standard distribution and qualification-locked supply relationships extending 18-24 month automotive timelines.
Within the integrated-device-manufacturer tier, Texas Instruments Incorporated and NXP Semiconductors N.V. exemplify the captive-fabrication archetype with domestic production footprints. Diodes Inc. represents the backward-integration specialist model, competing via aggressive control over wafer-level packaging for cost-sensitive consumer applications. These three companies anchor the competitive structure across automotive, industrial, and consumer segments in the Americas.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| NXP Semiconductors N.V |
| Semiconductor Components Industries, LLC (Onsemi) |
| Diodes Inc. |
| Central Semiconductors Corporation |
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| Others |
Pricing and Supply Chain Analysis
The Tijuana-Guadalajara freight corridor's logistics cost dynamics compress margin structures for fabless suppliers while amplifying price differentiation between automotive-qualified and consumer-grade small-signal transistors. Supply concentration in Taiwanese foundries and Mexican assembly nodes feeds downstream pricing power to integrated device manufacturers with captive fabrication.
Pricing Analysis
AEC-Q101 certification grade creates the primary spread between automotive and industrial pricing tiers, with PPAP documentation adding substantial qualification premiums. Three-tier pricing structure separates AEC-Q101 automotive from industrial-grade and unqualified consumer devices. Cost compression in consumer-grade MOSFETs is intensifying because Mexico contract manufacturers consolidate purchasing across high-volume SMT lines. Consumer electronics buyers in Tijuana and Guadalajara exhibit the highest price sensitivity, while Detroit and Tennessee automotive clusters accept substantial premiums for qualification-locked supply relationships.
Supply Chain Analysis
Export-control restrictions on advanced node semiconductor manufacturing equipment limit capacity expansion for sub-100 nanometer geometries serving RF applications. Geographic supply concentration centers on Taiwan, South Korea, and the United States for wafer fabrication, with Mexico and Brazil anchoring backend assembly and test. Raw material dependencies draw from high-purity silicon wafers, gold bonding wire, and epoxy mold compounds. Single-source vulnerability in advanced logic foundries exposes Americas-based fabless designers to geopolitical disruption. Distribution runs through foundry-qualified distributors and direct wafer-level agreements with tier-one automotive OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEMs and Mexico contract manufacturers, fragmenting pricing leverage among smaller fabless suppliers. This consolidation demands differentiated defensive positioning across stakeholder archetypes.
For Market Incumbents: Harden qualification-locked supply relationships through accelerated AEC-Q101 certification pipelines for next-generation SiGe devices. Deepen backward integration into wafer-level packaging to defend margin structures against Diodes Inc.'s cost-driven model. Prioritize captive fabrication capacity in Texas and Arizona under CHIPS Act subsidy flows to reduce foundry concentration risk. For New Entrants and Emerging Players: Establish a beachhead in Brazilian industrial automation controllers, where factory modernization programs create demand for ruggedized through-hole small-signal switches. Target São Paulo programmable logic controller manufacturers with extended temperature range BJTs. Pursue direct technical sales bypassing catalog distribution to capture premium positioning in replacement markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized discrete semiconductor portfolios. Five-to-ten year viability hinges on RF millimeter-wave content growth in 5G infrastructure and satellite terminals. Monitor SiGe BiCMOS adoption rates in telecommunications OEMs as the inflection signal for compound semiconductor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q101 Certification Acceleration | Qualification-locked relationships with Detroit automotive OEMs secure pricing premiums and volume commitments. |
| SiGe Process Technology Migration | CMOS-compatible millimeter-wave performance displaces costly III-V compound semiconductors in 5G infrastructure. |
| Wafer-Level Supply Agreement Expansion | Direct procurement contracts with Tijuana contract manufacturers bypass distribution markups and compress lead times. |
| CHIPS Act Fab Capacity Expansion | Domestic fabrication in Texas and Arizona reduces geopolitical exposure to Taiwanese foundry concentration. |
| Extended Producer Responsibility Compliance | Lead-free and halogen-free packaging investments capture California and Canadian provincial e-waste mandate premiums. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with semiconductor procurement managers, analog design engineers, foundry operations directors, and automotive tier-one supplier quality engineers; and secondary validation through SEC 10-K filings, SEMI silicon wafer shipment data, FCC equipment authorization databases, and CHIPS Act subsidy disclosure records. Bottom-up and top-down triangulation cross-checked wafer-level demand estimates against end-use consumption patterns.
Forecast inputs considered technology type, end-use application, packaging format, and regional manufacturing cluster across the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit erosion curves. Industry-specific inputs included AEC-Q101 qualification timelines, SiGe BiCMOS adoption rates in telecommunications infrastructure, and CHIPS Act facility construction progress.
Stress conditions across silicon wafer pricing volatility, foundry capacity allocation shifts, and automotive production cycle downturns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology substitution rates and regulatory subsidy continuity. Material shifts in U.S. export control scope or Mexican electromagnetic compatibility enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency Components Market
RF Components
Tunable Inductors Market
RF Components
Multiband Booster Market
RF Components
Small Signal Mosfets Market
RF Components
Analog Phase Shifter Market
RF Components
Microwave Devices Market
RF Components
RFID Antenna Market
RF Components
Japan Small Signal Transistor Market
RF Components
US RFID Tags Market
RF Components
5G Gain Block Amplifier Market
RF Components
Z-Wave Products Market
RF Components
Toroid Inductor Market
RF Components
RF Acoustic Wave Filters Market
RF Components
Global Inductors Market
RF Components
RFID Tags Market
RF Components
Wireless Module Market