
 Hazardous Area Sensors Market | 2026-2036
Hazardous Area Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Area Sensors Market Outlook
Refinery operators are redrawing procurement priorities as chemical processors scale fixed-mount detection networks. Honeywell International dominates North American flame detector supply through captive manufacturing of infrared sensing cores. ABB Group leverages its IECEx-certified product lines to anchor European petrochemical demand. Siemens AG competes on integrated safety system architecture that bundles gas detection with distributed control platforms.
Hazardous area sensors are engineered devices certified for operation in explosive atmospheres, typically rated for Zone 0 through Zone 2 environments with ingress protection from IP65 to IP67 and temperature classifications from T1 to T6. These instruments continuously monitor for combustible gases, flame signatures, or particulate accumulation to trigger emergency shutdowns before ignition thresholds are breached. Gas detectors lead product type demand as methane and hydrogen sulfide monitoring becomes mandatory across upstream oil and gas facilities. Infrared technology claims the fastest expansion trajectory due to its immunity to poisoning and reduced calibration frequency versus electrochemical alternatives. Fixed-mount installation dominates margin pools because retrofitting permanent detection grids generates multi-year service contracts and recalibration revenue.
The IECEx scheme administered by the IEC governs international equipment certification, while the EU ATEX Directive mandates conformity for all products sold within European explosive atmosphere applications. OSHA process safety management regulations in the United States enforce continuous monitoring in facilities handling threshold quantities of highly hazardous chemicals. EPA risk management plan amendments are tightening leak detection requirements for petrochemical storage and transfer operations. Stakeholders must weigh certification portability against regional regulatory divergence when configuring product portfolios for multi-jurisdiction deployment.
Market Dynamics
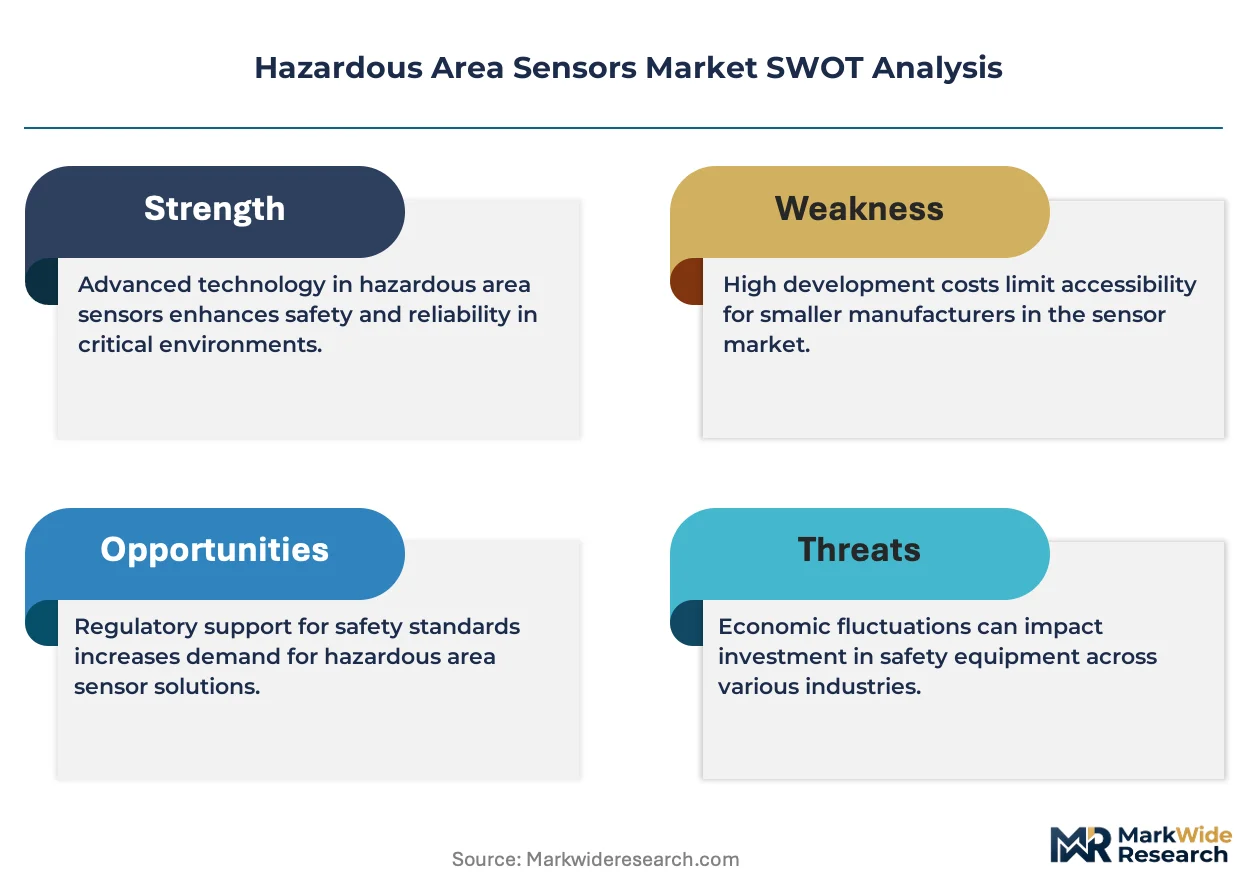
Refinery operators are accelerating fixed-mount sensor deployments across volatile processing zones as IECEx and ATEX certification thresholds tighten worldwide. This regulatory compression is redrawing competitive positioning between integrated safety system vendors and specialized detector manufacturers.
Growth Catalysts
- Upstream methane monitoring mandates:OSHA process safety management regulations now enforce continuous gas detection in facilities handling threshold quantities of highly hazardous chemicals across United States oil and gas basins.
- Infrared sensing immunity:Poisoning-resistant optical detection cores reduce calibration frequency versus electrochemical alternatives, cutting lifecycle service costs for offshore platform operators.
- China's hazardous infrastructure modernization:Petrochemical clusters in Jiangsu and Shandong provinces are retrofitting aging processing units with certified Zone 0 detection networks.
Market Restraints
- Specialized component supply concentration:Infrared emitter and detector subassemblies concentrate among German and Japanese optical component suppliers, creating single-source vulnerability.
- Certification timeline friction:IECEx scheme testing cycles extend 12-18 months for novel sensing architectures, delaying product commercialization.
- Electrochemical sensor poisoning:Hydrogen sulfide and silicone vapor exposure degrades catalytic bead performance in sour gas environments, forcing premature replacement.
Strategic Opportunities
- Hydrogen economy detection gaps:Germany's national hydrogen strategy is creating demand for specialized H2 sensors in emerging electrolyzer and pipeline infrastructure.
- Wireless mesh integration:Battery-powered ISA100.11a and WirelessHART gas detectors eliminate cabling costs in remote tank farm expansions.
- India's refinery capacity additions:Reliance Industries and Indian Oil Corporation are building new processing complexes requiring complete hazardous area detection suites.
Industry Challenges
- Explosion protection engineering scarcity:Qualified professionals capable of Zone 0/1 system design are concentrated among legacy oilfield services firms.
- Legacy DCS integration complexity:Brownfield facilities running proprietary control protocols require costly gateway engineering to connect modern digital sensors.
- ATEX-NEC code divergence:European and North American wiring method standards create product configuration fragmentation for multinational operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Area Sensors Market |
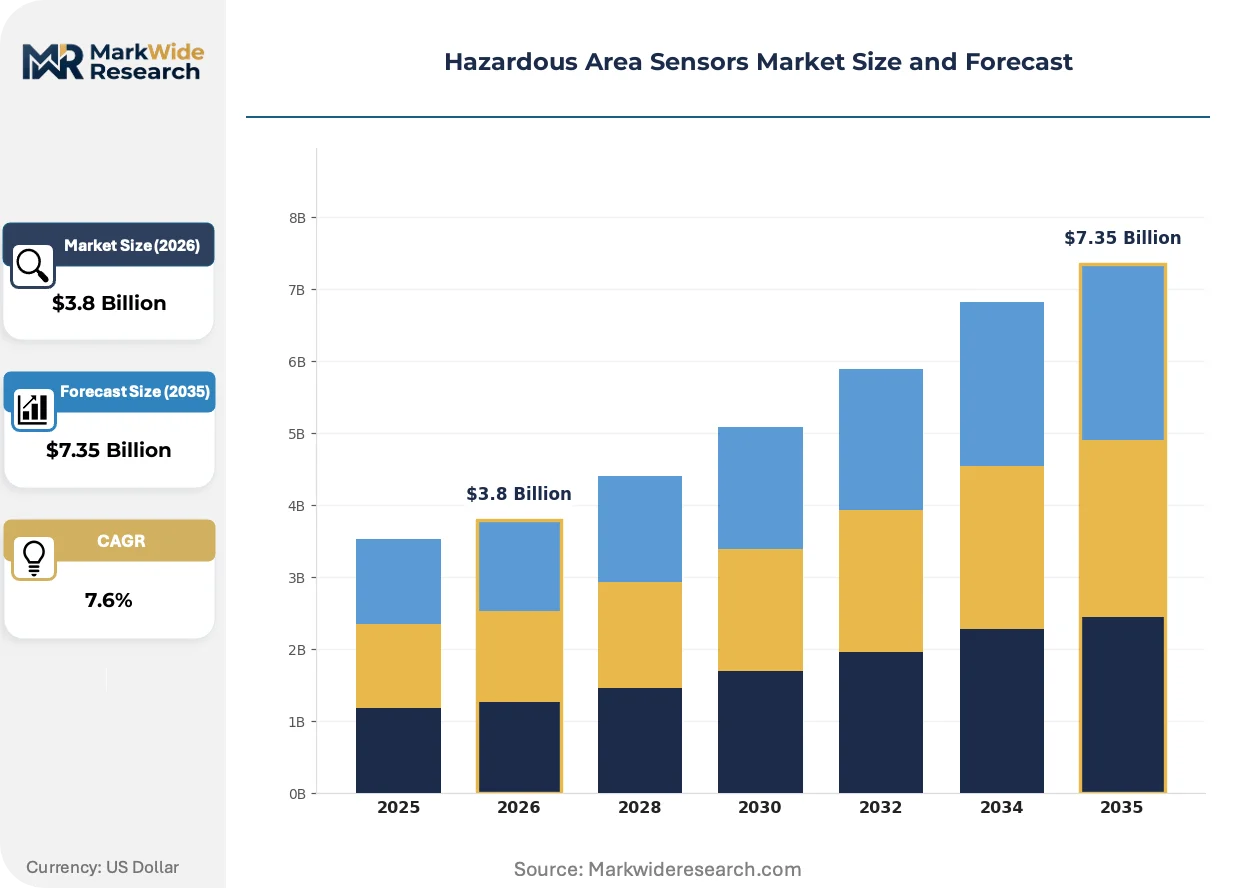
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flame Detectors, Gas Detectors, Smoke Detectors, Intrinsic Safety Devices Technology: Electrochemical, Infrared, Ultrasonic, Photoelectric End User: Mining, Oil & Gas, Chemical, Pharmaceuticals Installation: Fixed Mount, Portable, Wall Mounted, Ceiling Mounted |
| Companies Covered | Honeywell International, ABB Group, Siemens AG, Eaton Corporation, Endress+Hauser AG, Mettler-Toledo International, SICK AG, Yokogawa Electric Corporation, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Area Sensors Market Strategic Shifts
Optical sensing architectures are displacing legacy electrochemical cores across upstream and midstream applications. This technology rotation is compressing maintenance schedules while expanding addressable environments.
Multi-spectral infrared flame detection is decomposing the traditional ultraviolet-infrared dual-band product category. Offshore platform operators in the North Sea are specifying these instruments for hydrocarbon pool fire identification. The technology is decomposing price premiums previously commanded by specialized UV-IR units.
EPA risk management plan amendments are tightening leak detection requirements for petrochemical storage and transfer operations. Facility operators must now demonstrate continuous monitoring capability with documented response protocols. Storage terminal operators in Texas and Louisiana are upgrading fixed gas detection grids to satisfy enhanced audit scrutiny.
Buyer preference is consolidating around integrated safety system procurement rather than standalone detector purchasing. Refinery engineering teams are bundling gas detection with distributed control platforms from single vendors. This pattern is most pronounced in United States Gulf Coast modernization projects where Siemens and Honeywell compete on architecture completeness.
Hazardous Area Sensors Market Segmentation
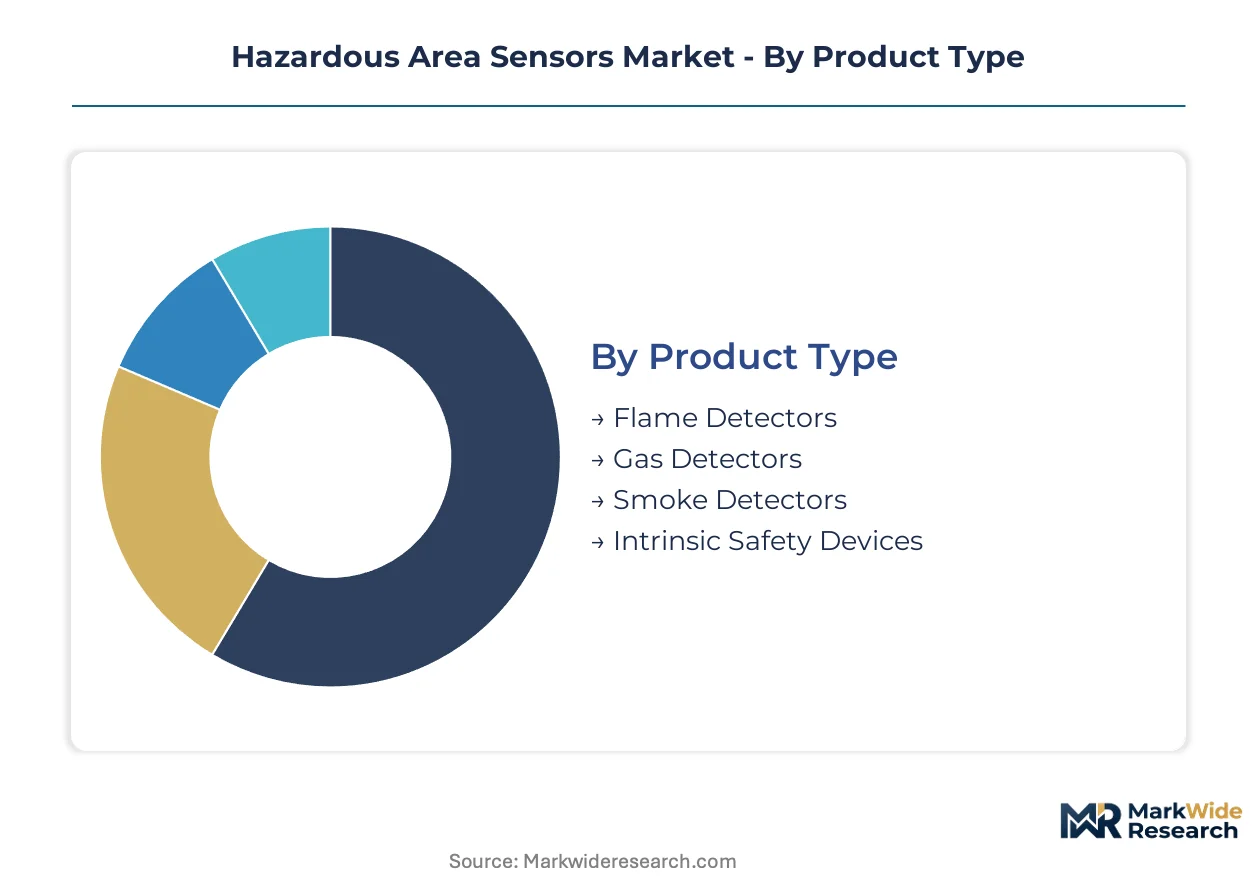
Segmentation in hazardous area sensors reveals how certification requirements and technology substitution pressures reshape procurement patterns across volatile processing environments. Buyers configure detection networks differently based on ignition risk classification, maintenance access constraints, and integration complexity with legacy control systems.
Product Type:
Infrared-enabled instruments face intensifying substitution pressure from multi-spectral optical cores that decompose traditional product categories.
- Flame Detectors:Multi-spectral infrared units identify hydrocarbon pool fires through spectral signature decomposition, displacing UV-IR dual-band alternatives. Offshore platform operators in the North Sea specify these instruments for reduced false alarm rates in high-glare environments.
- Gas Detectors:Methane and hydrogen sulfide monitoring instruments dominate refinery procurement as OSHA process safety management regulations enforce continuous detection in facilities handling threshold quantities of highly hazardous chemicals. Fixed-mount electrochemical and infrared variants anchor upstream oil and gas facility deployments.
- Smoke Detectors:Photoelectric aspiration systems serve enclosed electrical rooms and control buildings within hazardous area boundaries.
- Intrinsic Safety Devices:Zener barrier and galvanic isolation modules protect signal transmission into Zone 0 environments.
Gas detectors anchor the volume base while flame detectors gain share at the steepest rate.
Technology:
Cost tier stratification separates premium optical platforms from maintenance-intensive electrochemical alternatives.
- Electrochemical:Catalytic bead and solid-state polymer sensors provide cost-effective methane and carbon monoxide detection for non-critical monitoring points. Hydrogen sulfide and silicone vapor exposure degrades performance in sour gas environments, forcing premature replacement cycles.
- Infrared:Non-dispersive and tunable diode laser absorption spectroscopy cores deliver poisoning-resistant detection with extended calibration intervals. Offshore platform operators specify these instruments to cut lifecycle service costs in remote locations.
- Ultrasonic:Acoustic leak detection supplements point sensors in open processing areas where gas dispersion patterns complicate fixed-point coverage.
- Photoelectric:Light-scattering smoke detection serves control building and electrical room applications within hazardous area perimeters.
Electrochemical technology holds the installed base while infrared platforms expand most quickly.
End User:
Application severity drives specification divergence between continuous process monitoring and batch operation requirements.
- Oil & Gas:Upstream, midstream, and downstream operators deploy comprehensive detection grids across drilling platforms, pipeline compressor stations, and refinery processing units. EPA risk management plan amendments tighten leak detection requirements for storage and transfer operations in Texas and Louisiana.
- Chemical:Petrochemical clusters in Jiangsu and Shandong provinces retrofit aging processing units with certified Zone 0 detection networks.
- Mining:Underground coal and hard rock operations deploy methane and carbon monoxide sensors for ventilation control and emergency refuge systems.
- Pharmaceuticals:Solvent handling and hydrogenation processes in active pharmaceutical ingredient manufacturing require specialized detection for flammable vapor atmospheres.
Oil and gas anchors procurement volume while chemical processing climbs the fastest.
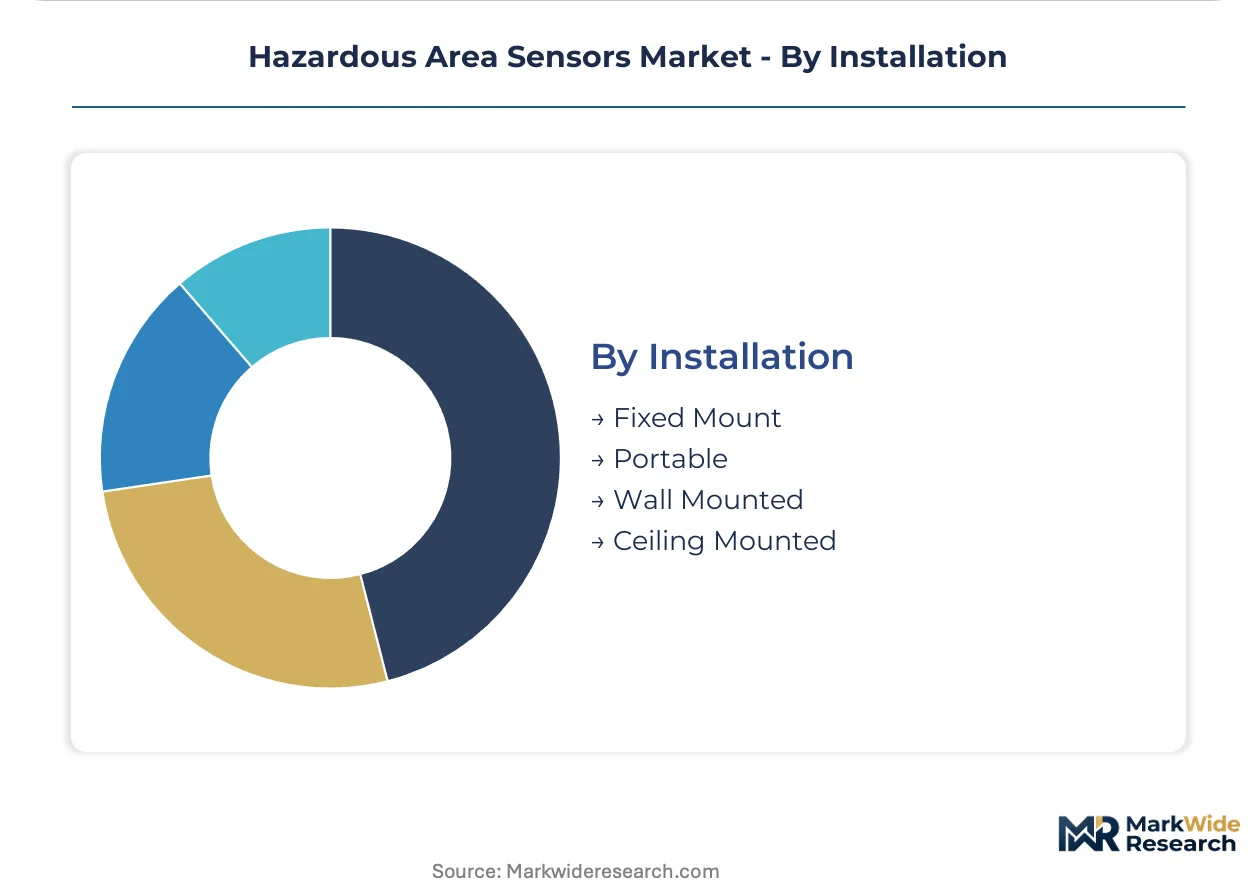
Installation:
Customer type stratification separates capital-intensive permanent installations from flexible maintenance-driven portable deployments.
- Fixed Mount:Permanent detection grids generate multi-year service contracts and recalibration revenue streams. Refinery operators across the United States Gulf Coast specify these installations for volatile processing zone coverage.
- Portable:Personal gas monitors and area sampling instruments serve confined space entry, turnaround maintenance, and emergency response applications.
- Wall Mounted:Enclosed detector housings protect instruments in corrosive or wash-down environments.
- Ceiling Mounted:Overhead positioning captures lighter-than-air gas releases in process buildings and analyzer shelters.
Fixed mount dominates margin pools while portable instruments gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized component suppliers for infrared emitters and detector subassemblies cluster in Germany and Japan, creating geographic chokepoints for sensing core procurement. Refinery operators in the United States, Germany, and China are modernizing volatile processing zones with certified detection networks.
United States
EPA risk management plan amendments tighten leak detection requirements for petrochemical storage terminals in Texas and Louisiana. OSHA process safety management regulations enforce continuous gas monitoring in facilities handling threshold quantities of highly hazardous chemicals. Gulf Coast refinery operators specify fixed-mount detection grids for volatile processing zone coverage.
Germany
The national hydrogen strategy generates demand for specialized H2 sensors in emerging electrolyzer and pipeline infrastructure. ATEX Directive mandates conformity for all products sold within European explosive atmosphere applications. Petrochemical clusters in North Rhine-Westphalia retrofit aging processing units with certified Zone 0 detection networks.
China
Petrochemical clusters in Jiangsu and Shandong provinces retrofit aging processing units with certified Zone 0 detection networks. GB standards and MIIT regulations govern equipment certification for explosive atmosphere applications. Sinopec and PetroChina expand fixed sensor deployments across volatile refining and chemical processing zones.
Japan
METI industrial safety standards enforce continuous monitoring in facilities handling flammable gas threshold quantities. JIS certification requirements tighten product compliance thresholds for domestic and export markets. Osaka-based industrial automation suppliers anchor regional demand for integrated safety system architectures.
India
Reliance Industries and Indian Oil Corporation construct new refinery processing complexes requiring complete hazardous area detection suites. BIS certification mandates equipment conformity for explosive atmosphere applications in domestic installations. Gujarat and Maharashtra petrochemical corridors drive concentrated procurement of fixed-mount gas detection networks.
Hazardous Area Sensors Market Competitive Environment
Concentration sits with diversified industrial conglomerates that bundle gas detection with distributed control platforms. The vendor base separates into integrated safety system architects, specialized detector manufacturers, and component suppliers for optical sensing cores. Two dominant competitive moves are reshaping positioning: certification portfolio expansion across IECEx and ATEX schemes, and wireless mesh integration to eliminate cabling costs in remote facility expansions.
Among diversified industrial technology providers, Honeywell International, ABB Group, and Siemens AG exemplify the integrated safety system archetype that bundles detection instrumentation with control platform architectures. These conglomerates occupy positions where refinery engineering teams consolidate procurement around single-vendor relationships. Specialized detector manufacturers and optical component suppliers sit within adjacent tiers, serving either as captive suppliers or independent competitors depending on vertical integration depth.
| Leading Market Players |
|---|
| Honeywell International |
| ABB Group |
| Siemens AG |
| Eaton Corporation |
| Endress+Hauser AG |
| Mettler-Toledo International |
| SICK AG |
| Yokogawa Electric Corporation |
| Emerson Electric |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts with embedded recalibration obligations lock in both supply access and price visibility for refinery operators deploying fixed-mount detection grids across United States Gulf Coast facilities. These multi-year agreements tether equipment procurement to aftermarket revenue streams, compressing upfront hardware margins while securing lifecycle service profitability.
Pricing Analysis
ATEX Directive certification tiers dictate the pricing structure across European petrochemical procurement, separating Zone 0-rated instruments from Zone 2 alternatives. Three-tier pricing stratifies across premium optical cores, standard electrochemical units, and economy catalytic bead sensors. Pricing pressure intensifies in the electrochemical tier as infrared substitution accelerates in offshore applications. Upstream operators show highest price sensitivity due to capital discipline in volatile commodity cycles, while downstream refiners prioritize certification completeness over unit cost.
Supply Chain Analysis
German and Japanese optical component suppliers anchor the infrared emitter and detector subassembly chokepoint, creating single-source vulnerability for poisoning-resistant sensing cores. Manufacturing draws from precision optics clusters in Stuttgart and Osaka, with final assembly concentrating in United States, Germany, and China. Tariff exposure runs through trans-Pacific semiconductor content in signal processing chips. Distribution runs through integrated safety system vendors who bundle detection hardware with distributed control platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hazardous area sensors market is accelerating through a technology inflection as multi-spectral infrared architectures displace legacy electrochemical cores across upstream and midstream deployments. EPA risk management plan amendments and tightening IECEx certification timelines are compressing product development cycles while expanding addressable safety system budgets.
For Market Incumbents: Fortify certification portfolio breadth across IECEx and ATEX schemes to defend against specialized detector manufacturers encroaching on integrated safety system accounts. Deepen captive supply of infrared sensing cores through backward integration into German and Japanese optical component networks. Prioritize wireless mesh product lines to eliminate cabling cost disadvantages in remote tank farm expansions. For New Entrants and Emerging Players: Anchor in India's refinery capacity buildout where Reliance Industries and Indian Oil Corporation require complete hazardous area detection suites without legacy vendor lock-in. Target hydrogen economy infrastructure in Germany's electrolyzer and pipeline networks as specialized H2 sensor demand outpaces incumbent product development. Pursue ISA100.11a certification as a go-to-market wedge against WirelessHART incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward optical component specialists with captive supply relationships to German and Japanese emitter manufacturers, positioned for infrared technology substitution tailwinds. Long-term viability favors vendors with integrated safety system architecture capabilities bundling gas detection with distributed control platforms. Monitor IECEx scheme testing timeline compression as the signal for product commercialization velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Mesh Certification | ISA100.11a and WirelessHART protocols eliminate cabling costs in remote tank farm expansions. |
| Optical Component Backward Integration | In-house production of infrared cores reduces dependency on German and Japanese subassembly suppliers. |
| Hydrogen Sensor Development | Germany's national hydrogen strategy creates specialized H2 detection demand in electrolyzer infrastructure. |
| Integrated Safety System Bundling | Gas detection packaged with Siemens and Honeywell control platforms dominates Gulf Coast refinery procurement. |
| Zone 0 Certification Expansion | IECEx and ATEX Zone 0 ratings unlock premium positioning in Jiangsu and Shandong petrochemical retrofits. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment certification databases. Interviews with refinery engineering directors, safety system procurement leads, optical component suppliers, and aftermarket service managers inform demand-side validation. IECEx and ATEX certification records, OSHA enforcement actions, and EPA risk management plan disclosures provide supply-side triangulation. Bottom-up sensor deployment counts across United States, German, and Chinese facilities cross-validate against top-down market sizing.
Segmentation dimensions modeled include product type, detection technology, end-use industry, installation configuration, and regional regulatory cluster across the analysis window. CAGRs derive from installed base replacement cycles, technology substitution rates, and regulatory mandate compliance deadlines. Forecast inputs incorporate methane monitoring mandate enforcement timelines, hydrogen infrastructure buildout schedules, and refinery modernization capital commitments.
Underlying assumptions cover regulatory enforcement continuity, optical component supply stability, and certification scheme harmonization, with deviation risk concentrated in IECEx testing timeline extensions and electrochemical sensor poisoning incidents in sour gas environments. Practitioners should keep alternative scenarios live as hydrogen economy infrastructure deployment and wireless mesh adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Absolute Pressure Sensor Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Body Worn Temperature Sensors Market