
 Revenue Cycle Management (RCM) Market | 2026-2036
Revenue Cycle Management (RCM) Market Size, Share, and Industry Trends Forecast 2026-2036
Revenue Cycle Management (RCM) Market Intelligence
The bundling of disparate financial tools into integrated, end-to-end platforms is realigning provider purchasing decisions. Optum leverages its deep integration with payers and providers to offer comprehensive solutions across the care continuum. Oracle Cerner anchors its RCM offerings within its dominant electronic health record (EHR) systems. Meanwhile, athenahealth specializes in cloud-native solutions tailored specifically for independent physician practices.
Revenue Cycle Management comprises the administrative and clinical functions that contribute to the capture, management, and collection of patient service revenue. This process utilizes software to manage standardized medical billing codes, such as ICD-10 and CPT, to facilitate reimbursement from payers. Hospitals constitute the largest end-user segment by revenue, driven by complex, high-volume billing requirements. Among solution types, AI-powered denial management is emerging as a critical component for maximizing financial performance.
Regulatory frameworks impose stringent data handling and security requirements. The U.S. Health Insurance Portability and Accountability Act (HIPAA) and Europe’s General Data Protection Regulation (GDPR) mandate strict patient data protection, influencing software architecture. The central strategic decision for healthcare providers remains whether to outsource these complex functions to a third party or invest in sophisticated in-house technology platforms.
Market Dynamics
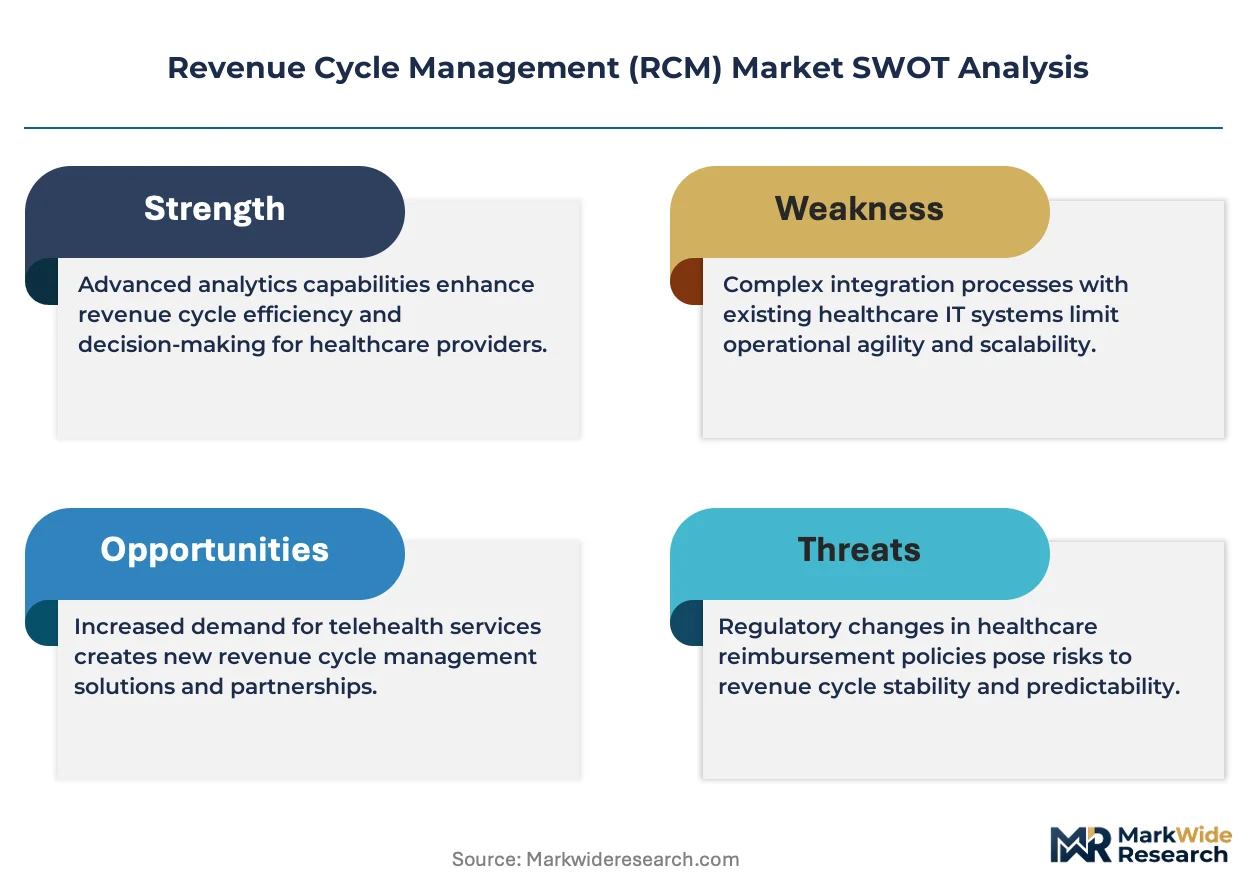
The fundamental shift from fee-for-service to value-based reimbursement models is the central force shaping the Revenue Cycle Management market. This transition compels healthcare providers to adopt more sophisticated financial tools to manage risk, track outcomes, and ensure accurate payment.
Growth Catalysts
- AI-Powered Automation:The application of artificial intelligence and machine learning to automate tasks like medical coding, prior authorization, and denial management reduces administrative costs and improves collection rates for hospitals and physician practices.
- Ambulatory Care Expansion:A structural shift of patient care to outpatient settings, including Ambulatory Surgical Centers, creates demand for scalable, cloud-based RCM solutions tailored to their specific, high-volume, lower-complexity billing workflows.
- Coding System Complexity:The ongoing updates and increasing granularity of medical coding standards, such as ICD-10 and CPT, necessitate advanced software to ensure billing accuracy and compliance, driving provider investment in modern RCM platforms.
Market Restraints
- High Implementation Costs:The significant upfront capital investment and recurring subscription fees associated with enterprise-level RCM platforms and EHR-integrated systems present a substantial financial barrier for smaller, independent practices and rural hospitals.
- Interoperability Deficits:Persistent lack of seamless data exchange between disparate EHR, billing, and payer systems creates data silos, complicates workflows, and limits the effectiveness of end-to-end RCM process automation for many healthcare organizations.
- Data Security Risks:The centralization of sensitive patient health and financial information within RCM systems makes them a high-value target for cyberattacks, requiring continuous and costly investment in security infrastructure to comply with HIPAA and GDPR.
Strategic Opportunities
- Telehealth Billing Solutions:The mainstreaming of virtual care creates an opportunity for specialized RCM solutions that can navigate the complex and evolving reimbursement rules for telehealth services across different payers and geographies.
- Patient Financial Experience Platforms:Integrating RCM with patient-facing tools for price transparency, payment plans, and digital payments offers a significant opportunity to improve patient satisfaction and accelerate cash flow for providers.
- Managed Care in Emerging Economies:As countries in Asia-Pacific and Latin America expand private health insurance and managed care models, a need arises for localized RCM software and services adapted to their specific regulatory and payer landscapes.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of certified medical coders, billing specialists, and RCM analysts capable of managing increasingly complex payer rules and technology platforms constrains both in-house and outsourced operations.
- Legacy System Integration:Healthcare providers face significant technical hurdles and operational disruption when attempting to integrate modern, AI-driven RCM modules with their existing, often outdated, legacy hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Revenue Cycle Management (RCM) Market |
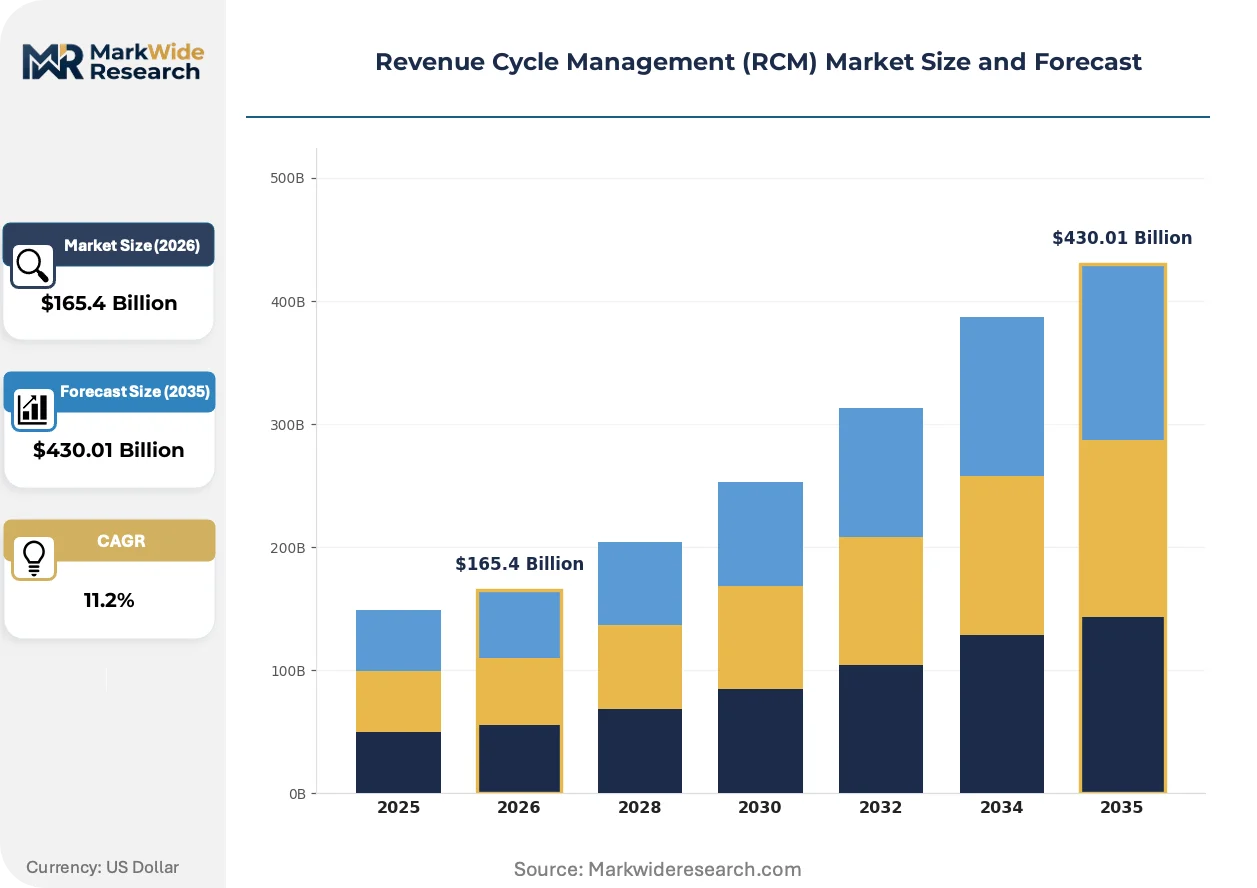
| Market Size in 2026 | $165.4 Billion |
| Market Size in 2035 | $430.01 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Denial Management, Patient Scheduling, Claims Management, Billing & Coding, Payment Processing Deployment Mode: Cloud-based, On-premise, Hybrid, Web-based End User: Hospitals, Physician Practices, Diagnostic Centers, Ambulatory Surgical Centers, Specialty Clinics Pricing Model: Subscription-based, Transaction-based, Per User Licensing, Freemium, Pay-as-you-go |
| Companies Covered | Oracle Cerner, athenahealth, Optum, eClinicalWorks, NextGen Healthcare, R1 RCM, Conifer Health Solutions, Ensemble Health Partners, Change Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Revenue Cycle Management (RCM) Market Strategic Shifts & Innovations
Automation and intelligence are redefining financial operations within healthcare. The market is moving away from fragmented, manual processes toward integrated platforms that use AI to predict and manage revenue from patient registration through final payment, directly impacting provider financial health.
Generative AI is being applied to automate the creation of appeals for denied claims and to summarize complex patient financial histories. Large hospital systems and specialized billing companies are adopting this technology to reduce administrative overhead and improve recovery rates. This advancement is consolidating the denial management function, reducing the need for large teams of manual reviewers and accelerating revenue recovery cycles.
Regulatory mandates like the U.S. No Surprises Act are forcing changes in billing transparency and dispute resolution for out-of-network charges. This legislation requires providers and payers to implement new communication and arbitration workflows within their financial systems. RCM software vendors are most affected, as they must rapidly develop and deploy new features to ensure their healthcare clients remain compliant with these complex rules.
A distinct shift in buying behavior has providers prioritizing RCM platforms that feature integrated patient financial engagement tools. This trend displaces the traditional procurement model of purchasing separate systems for back-office billing and front-office patient payment portals. This pattern is most visible in the United States, where high-deductible health plans make patient collections a critical component of provider viability.
Revenue Cycle Management (RCM) Market Segmentation
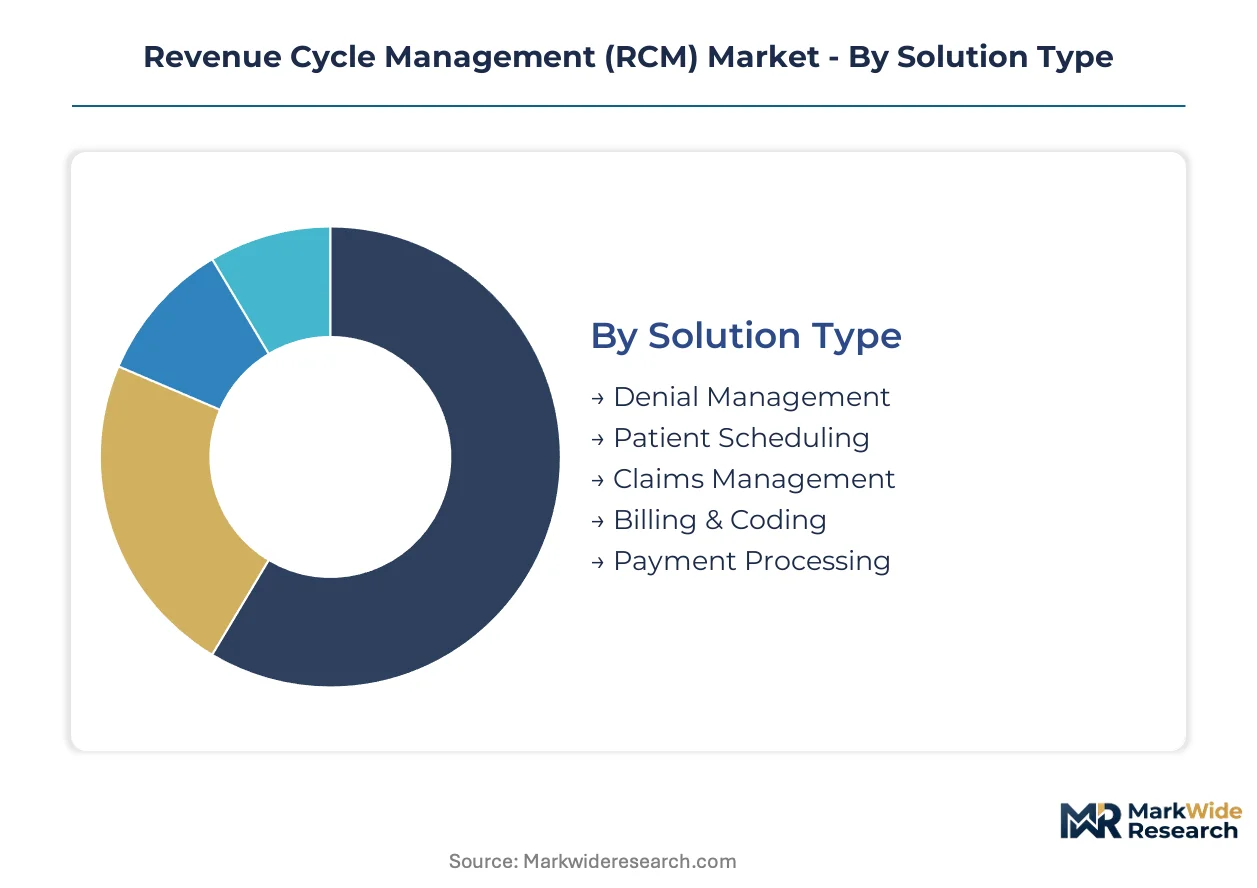
Understanding the varied segmentation within the Revenue Cycle Management market is crucial for assessing vendor capabilities and provider needs. This analysis dissects the market by solution type, deployment mode, end-user, and pricing model, revealing distinct operational and financial considerations for healthcare organizations.
Solution Type:
The capital intensity within RCM solutions varies significantly, with some platforms demanding substantial upfront investment for full integration across complex healthcare systems.
- Denial Management:This solution leverages artificial intelligence and machine learning algorithms to identify, prevent, and appeal denied claims, directly maximizing reimbursement rates for providers. Demand is particularly concentrating in the United States due to its complex payer landscape and high denial rates.
- Billing & Coding:These platforms manage the application of standardized medical codes like ICD-10 and CPT to patient services, ensuring accuracy for payer reimbursement. Large hospital systems require robust, integrated billing and coding solutions to manage high-volume, diverse service offerings.
- Patient Scheduling:These systems optimize appointment booking, resource allocation, and patient flow, aiming to reduce no-shows and improve operational efficiency.
- Claims Management:This segment handles the submission, tracking, and processing of medical claims to various insurance payers.
- Payment Processing:Solutions in this category facilitate secure and efficient patient payments, including digital options and payment plan management.
Billing & Coding absorbs the bulk of installed capacity; Denial Management is expanding most quickly.
Deployment Mode:
Deployment modes differentiate based on accessibility and control requirements, influencing operational flexibility for healthcare providers.
- Cloud-based:These solutions are hosted on remote servers and accessed via the internet, offering scalability, lower upfront costs, and automatic updates. Ambulatory Surgical Centers and independent physician practices increasingly adopt cloud-native RCM for its flexibility and reduced IT overhead.
- On-premise:Software is installed and run directly on a healthcare organization's local servers, providing maximum data control and customization capabilities. Larger hospital systems with existing legacy infrastructure often prefer on-premise solutions for enhanced security protocols and deep integration with proprietary EHRs.
- Hybrid:This model combines elements of both cloud-based and on-premise deployments, balancing data security with accessibility.
- Web-based:Similar to cloud-based but often refers to solutions accessed through a web browser, focusing on ease of access.
Cloud-based deployment is experiencing the highest adoption rates; On-premise solutions maintain relevance for specific security and integration needs.
End User:
End-user segments are differentiated by their volume of patient encounters and the complexity of their billing environments.
- Hospitals:These institutions represent the largest end-user segment, characterized by high patient volumes, diverse service lines, and intricate billing requirements across multiple payers. Hospitals demand comprehensive RCM platforms to manage complex inpatient and outpatient revenue cycles efficiently.
- Ambulatory Surgical Centers:These outpatient facilities require RCM solutions tailored for high-volume, lower-complexity procedures, emphasizing rapid claim processing and efficient patient financial engagement. The shift towards outpatient care drives specific demand for scalable, cloud-based RCM in these settings.
- Physician Practices:This segment includes independent and group practices, often seeking RCM tools that integrate seamlessly with their EHRs to streamline administrative tasks.
- Diagnostic Centers:These facilities focus on specialized billing for laboratory tests, imaging services, and other diagnostic procedures.
- Specialty Clinics:Clinics focused on specific medical areas, such as cardiology or oncology, require RCM solutions that can handle their unique coding and reimbursement rules.
Hospitals constitute the largest revenue contributor; Ambulatory Surgical Centers are demonstrating accelerated demand for tailored solutions.
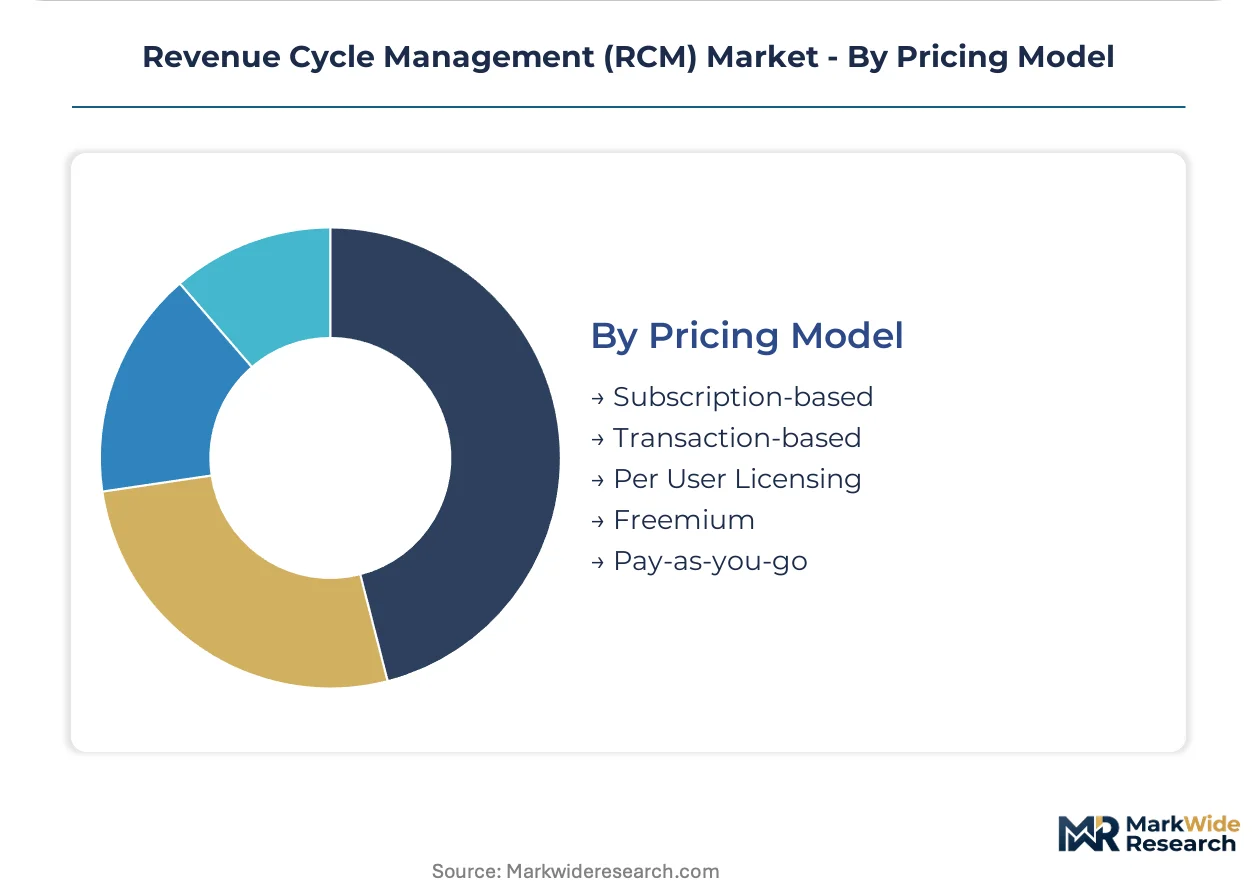
Pricing Model:
Pricing models reflect diverse vendor strategies, balancing predictable revenue streams with usage-based flexibility.
- Subscription-based:Providers pay a recurring fee, typically monthly or annually, for access to the RCM software and its features. This model offers predictable budgeting for healthcare organizations.
- Transaction-based:Fees are levied per claim processed, per patient encounter, or based on a percentage of collected revenue. This model aligns vendor costs directly with the volume of services rendered by the provider.
- Per User Licensing:Charges are based on the number of individual users accessing the RCM system within an organization.
- Freemium:A basic version of the RCM software is offered for free, with advanced features available at a premium cost.
- Pay-as-you-go:Users pay only for the specific RCM services or modules they consume, offering high flexibility for fluctuating needs.
Subscription-based models offer predictable costs for providers; Transaction-based pricing aligns vendor revenue directly with client activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Revenue Cycle Management market exhibits a clear divide between regions with established, complex healthcare systems driving high consumption and emerging economies rapidly developing their RCM capabilities. Mature markets like the United States lead in demand for advanced solutions due to intricate billing requirements.
United States
Demand for advanced RCM solutions concentrates in the United States, driven by its fragmented payer landscape and high healthcare expenditure. The U.S. Health Insurance Portability and Accountability Act (HIPAA) mandates strict patient data protection, influencing software architecture. Technology hubs in Boston and San Francisco innovate in AI-powered denial management and integrated platforms.
Germany
Germany's robust healthcare system and digital health initiatives create significant demand for efficient RCM platforms. Europe’s General Data Protection Regulation (GDPR) profoundly impacts data handling and security requirements for RCM software. Healthcare IT clusters in Berlin and Munich are developing localized solutions for billing and patient management.
India
India presents a substantial opportunity as private health insurance and managed care models expand across its diverse population. The country's national health policies encourage digital transformation within healthcare, necessitating modern RCM tools. Technology hubs like Bengaluru and Hyderabad are developing localized RCM software tailored to the Indian market.
Japan
Japan's aging population and universal healthcare system drive the need for highly efficient and integrated RCM solutions. The Ministry of Health, Labour and Welfare (MHLW) oversees healthcare regulations, impacting billing and coding practices. Tokyo and Osaka's medical technology firms focus on RCM systems to improve operational efficiency and patient financial experience.
United Kingdom
The United Kingdom's blend of public and private healthcare systems fuels demand for RCM tools that manage diverse billing requirements. Data protection regulations, aligned with GDPR principles, are critical for all RCM software deployed in the UK. London hosts numerous health tech companies specializing in cloud-native RCM solutions for both NHS and private providers.
Revenue Cycle Management (RCM) Market Key Industry Players
The competitive structure tilts toward integrated solution providers and specialized RCM pure-plays, reflecting the diverse needs of healthcare organizations from large hospital systems to independent practices. The market features large technology firms offering comprehensive platforms alongside agile, cloud-native specialists targeting specific segments with tailored offerings. Strategic partnerships between EHR vendors and RCM experts are common, alongside continued portfolio diversification by established players to offer more end-to-end solutions and expand their geographic footprint. Mergers and acquisitions remain a key strategy for market consolidation.
Among the leading market players, Oracle Cerner exemplifies the integrated electronic health record vendor archetype, anchoring its RCM offerings directly within its established EHR systems. athenahealth represents a prominent cloud-native specialist, tailoring its solutions specifically for independent physician practices that prioritize flexibility and reduced IT overhead. Optum occupies a distinct position as a comprehensive solution provider, leveraging deep integration with both payers and providers to offer broad services across the healthcare continuum. These companies collectively illustrate the market's segmentation between large-scale enterprise solutions and niche, specialized platforms.
| Leading Market Players |
|---|
| Oracle Cerner |
| athenahealth |
| Optum |
| eClinicalWorks |
| NextGen Healthcare |
| R1 RCM |
| Conifer Health Solutions |
| Ensemble Health Partners |
| Change Healthcare |
Cost & Logistics Intelligence
Skilled labor wage benchmarks, particularly for medical coders and RCM analysts, cascade through the service delivery model, influencing pricing tiers across the Revenue Cycle Management market. This directly impacts the cost structures for both in-house RCM departments and outsourced service providers.
Pricing Analysis
Cost-down pressure on RCM service providers accelerates because healthcare organizations seek greater efficiency and cost predictability. Subscription-based models dominate, offering predictable budgeting for healthcare providers. Price differentiation stems from factors like the level of AI integration, customization for specific EHR systems, and the extent of managed services included. Small, independent physician practices demonstrate higher price sensitivity compared to large hospital systems with complex, high-volume billing requirements.
Supply Chain Analysis
Mandatory multi-vendor qualification for RCM solutions is becoming common, as providers seek to mitigate single-source risk and ensure interoperability. The RCM "supply chain" draws from technology development hubs in the United States, Germany, and India. Key dependencies include access to skilled medical coders, advanced IT infrastructure, and data science talent for AI development. A structural risk involves the persistent scarcity of certified RCM analysts and coders. Distribution runs through direct sales teams and strategic partnerships with dominant EHR vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Revenue Cycle Management market is undergoing a significant technology transition, with AI-powered automation systematically replacing manual administrative processes across the revenue cycle.
For Market Incumbents:
To counter disruption from agile, cloud-native specialists, established RCM providers must deepen integration with dominant EHR platforms. Investing in advanced AI and machine learning capabilities for denial management and predictive analytics is crucial. Strategic partnerships with emerging technology firms can expand solution portfolios. Expanding geographic reach into underserved markets also helps secure long-term revenue streams.
For New Entrants and Emerging Players:
Enter via specialized, cloud-native solutions targeting specific pain points like telehealth billing or patient financial experience. Independent physician practices and Ambulatory Surgical Centers represent highly penetrable segments due to their demand for flexible, low-overhead RCM tools. A successful go-to-market strategy involves offering modular solutions that integrate seamlessly with various existing EHR systems, minimizing implementation hurdles for providers.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor vertically integrated mid-cap specialists in the United States and other developed markets with complex payer landscapes. Long-term viability hinges on the continued shift towards value-based care and the digital transformation of healthcare administration. Acquisition targets should include firms with proprietary AI algorithms for denial prediction or robust patient engagement platforms. A critical signal to watch is the pace of regulatory changes impacting billing transparency and reimbursement models.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamlessly connecting RCM systems with EHRs enhances data flow and operational efficiency for healthcare providers. |
| Strategic Partnership | Collaborating with payers or specialized tech firms expands market reach and improves solution capabilities. |
| Acquisition of Specialist Firm | Gaining expertise in AI-powered denial management or patient financial engagement accelerates product innovation. |
| Product Launch: Telehealth Billing Module | Addressing the evolving reimbursement complexities of virtual care creates new revenue streams for providers. |
| Geographic Expansion into Emerging Economies | Capitalizing on the growing private health insurance markets in regions like Asia-Pacific diversifies revenue sources. |
Research Approach
Independent corroboration across industry association reports, government healthcare expenditure data, and financial filings of public RCM companies underwrites the qualitative findings. Primary interviews with RCM executives, hospital CFOs, independent physician practice managers, and health IT procurement specialists provided crucial insights. This approach ensured bottom-up validation of market dynamics and top-down triangulation of market size estimates.
The comparable-period framing anchored the forecast window to relevant historical reference periods, establishing a robust baseline for projections. Our analytical framework modeled segmentation dimensions including solution type, deployment mode, end-user, pricing model, and regional regulatory frameworks. Compound annual growth rates were derived through a combination of regression analysis and market share projections, incorporating inputs like healthcare spending trends and anticipated regulatory changes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of significant regulatory shifts or major cybersecurity breaches. The forecasts reflect assumptions regarding technological adoption and market evolution. A model refresh is warranted upon material change in global healthcare policy or economic stability affecting provider spending.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Femtech Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Healthcare Business Collaboration Tools Market