
 US Long Term Care Software Market | 2026-2036
US Long Term Care Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Long Term Care Software Market Insights
A shift from fragmented single-vendor installations toward multi-platform ecosystems is realigning procurement patterns across long-term care operators. PointClickCare leverages cloud-native architecture to sustain dominance in skilled nursing interoperability. MatrixCare anchors home health segments with specialized reimbursement workflow tools. Netsmart Technologies, Inc. competes across behavioral health and post-acute intersections, extending its platform into community-based care coordination.
US long-term care software encompasses clinical, operational, and financial applications designed to manage resident records, staff scheduling, medication administration, and claims processing across post-acute and continuing care settings. Core functionality requires HL7 FHIR-compliant data exchange, real-time eMAR integration, and CMS-optimized billing engines to ensure regulatory adherence and revenue integrity. Nursing home management platforms currently occupy the largest revenue pool, while home health care software represents the fastest-expanding segment as hospital-at-home programs gain state Medicaid traction. Cloud-based deployment leads adoption curves, though hybrid solutions retain substantial share among mid-size regional chains managing legacy infrastructure transitions.
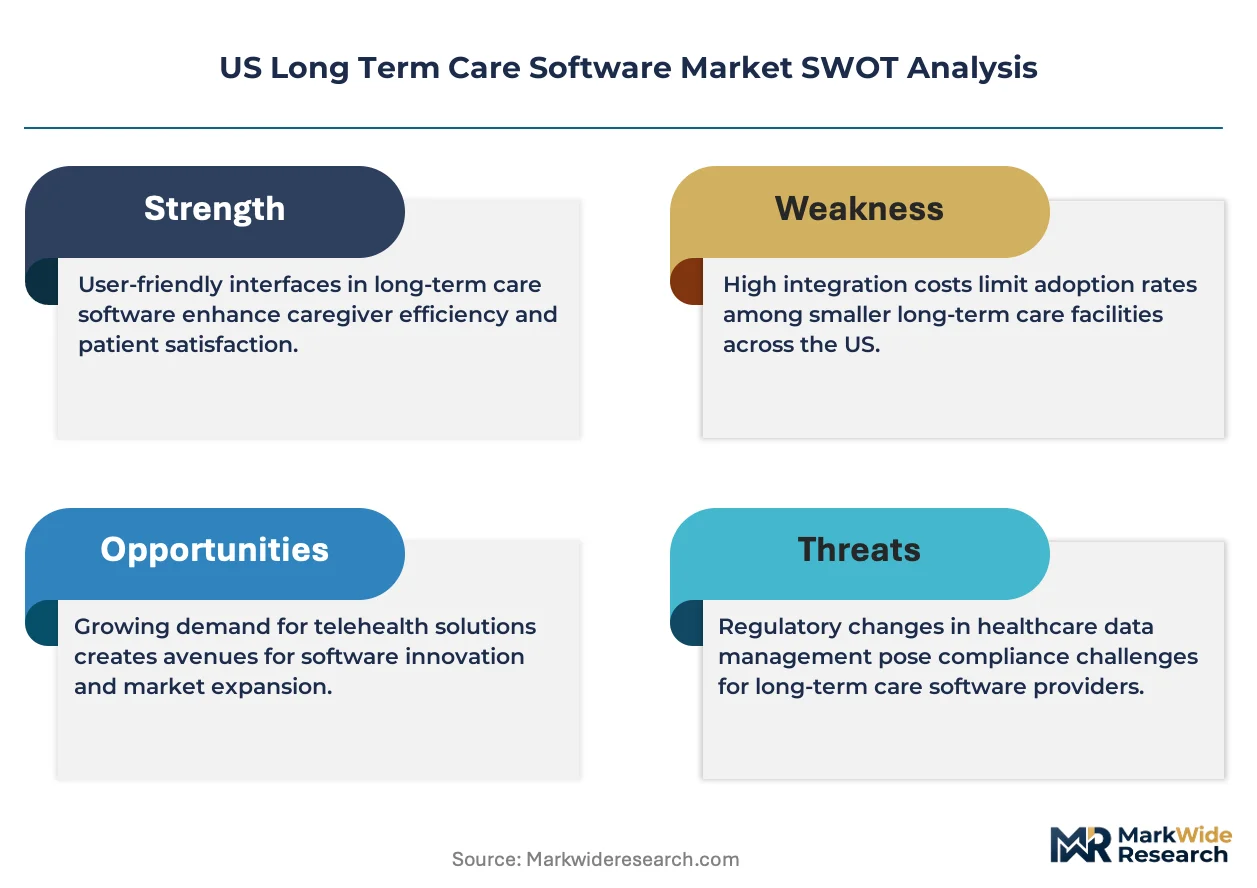
FDA oversight of software-as-medical-device classifications, CMS Conditions of Participation for electronic health records, and state-level Medicaid Management Information System mandates collectively shape product development roadmaps and sales cycles. HIPAA security rule enforcement and state data breach notification laws impose compliance costs that favor established vendors with dedicated legal infrastructure. Stakeholders must monitor CMS Innovation Center waivers and state Medicaid 1115 demonstrations, as these programs determine which functionality bundles achieve reimbursable status and therefore drive purchasing priorities.
Market Dynamics
CMS reimbursement rule changes and state Medicaid modernization programs are compressing technology replacement cycles across skilled nursing and home health segments. Facility consolidation in the Southeast is accelerating demand for interoperable cloud-native platforms that unify clinical, operational, and financial workflows under single vendor relationships.
Growth Catalysts
- Medicaid Management Information System mandates:State-level MMIS upgrades in Texas, Florida, and Georgia are requiring real-time claims processing integration, forcing legacy system replacements.
- Hospital-at-home program expansion:CMS Innovation Center waivers in 14 states now reimburse remote patient monitoring bundled with home health software, creating immediate procurement pull.
- HL7 FHIR interoperability standards:Federal mandate for standardized data exchange is de-risking multi-platform purchases that previously faced integration failures.
Market Restraints
- Cloud infrastructure cost volatility:AWS and Azure pricing fluctuations for healthcare-compliant hosting are squeezing margins for mid-size software vendors serving regional chains.
- HIPAA compliance complexity:State-level breach notification law variations create legal infrastructure requirements that favor established vendors with dedicated compliance teams.
- Legacy system entrenchment:Decades-old on-premise installations in rural Midwest facilities create technical debt that slows cloud migration timelines.
Strategic Opportunities
- Behavioral health-post-acute convergence:Netsmart's platform extension into community-based care coordination demonstrates white space for unified mental health and long-term care records.
- AI-assisted clinical documentation:Natural language processing integration with eMAR systems reduces nursing administrative burden in high-turnover environments.
- Rural health clinic partnerships:Federally Qualified Health Center networks in Appalachia and the Mississippi Delta remain underpenetrated for integrated EHR-long-term care platforms.
Industry Challenges
- Interoperability talent scarcity:Healthcare IT specialists with HL7 FHIR implementation experience command premium salaries that strain vendor hiring pipelines.
- Multi-platform integration complexity:Skilled nursing operators combining PointClickCare clinical modules with MatrixCare reimbursement tools face data synchronization failures requiring costly custom middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Long Term Care Software Market |
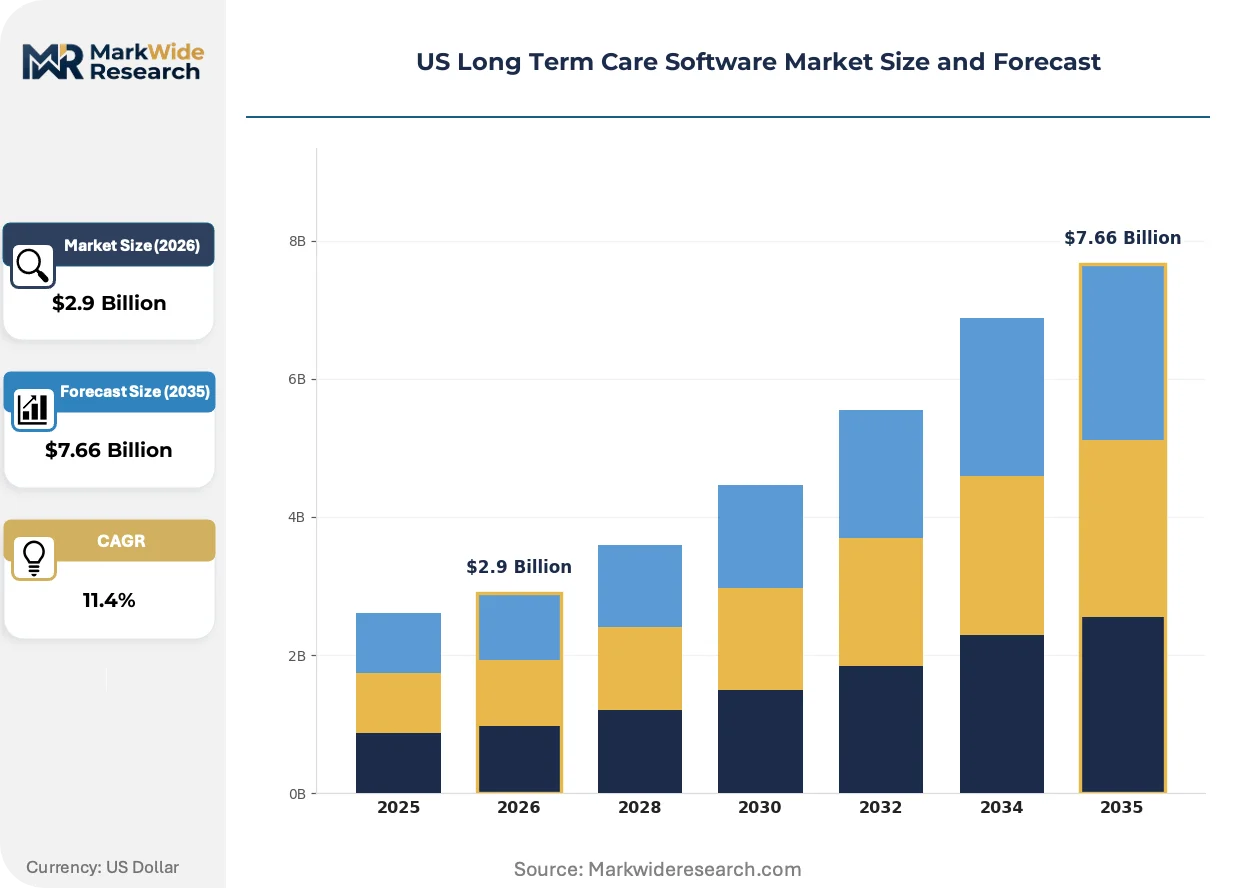
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $7.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
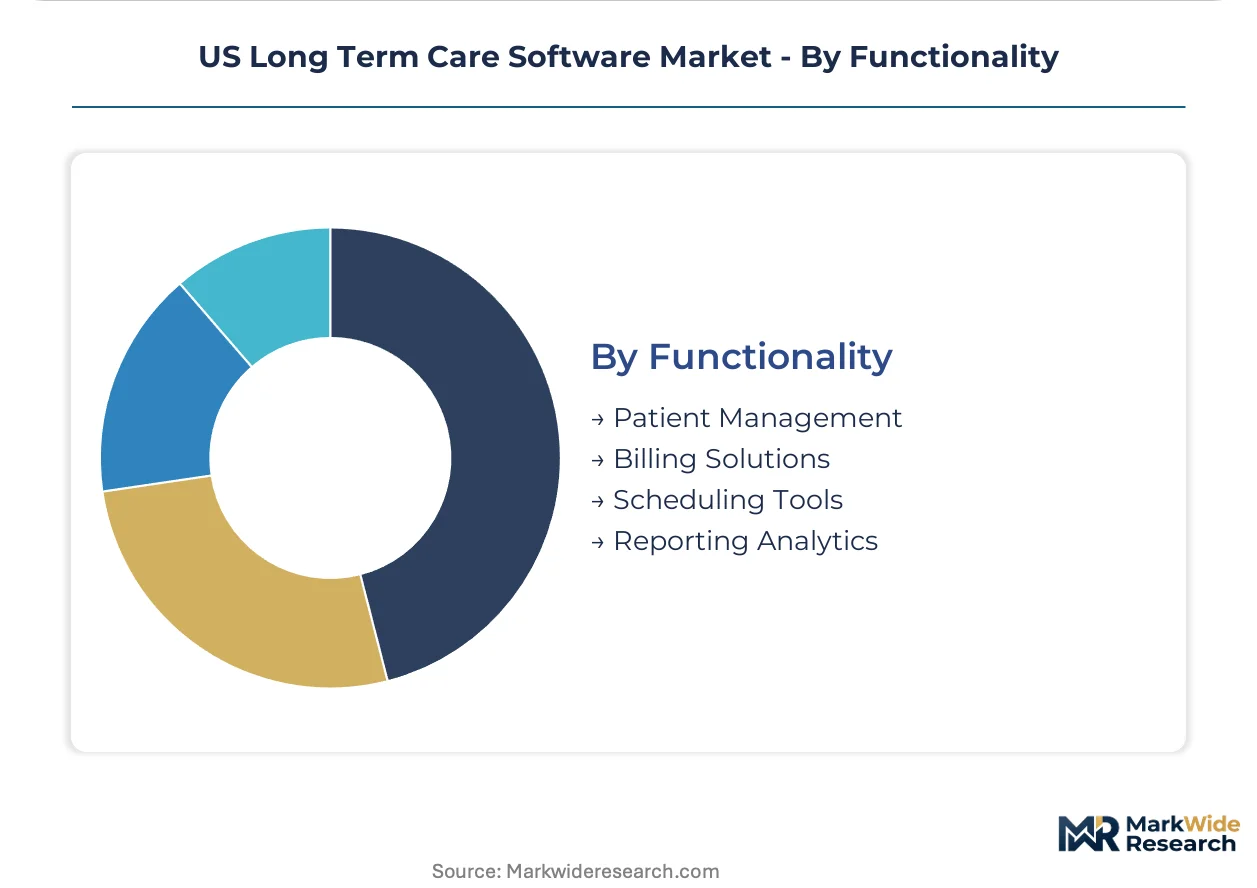
| Segmentation | Product Type: Nursing Home Management, Home Health Care Software, Assisted Living Software, Hospice Solutions End User: Healthcare Providers, Residential Facilities, Family Caregivers, Rehabilitation Centers Deployment: Cloud-Based, On-Premise, Hybrid Solutions, Mobile Applications Functionality: Patient Management, Billing Solutions, Scheduling Tools, Reporting Analytics |
| Companies Covered | PointClickCare, MatrixCare, Netsmart Technologies, Inc., Veradigm LLC, Oracle Corporation, McKesson Corporation, Omnicell, Inc., WellSky, SigmaCare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Long Term Care Software Market Trends and Innovations
Edge computing architectures and ambient clinical intelligence are redrawing competitive boundaries between clinical documentation, operational analytics, and revenue cycle management. Vendor differentiation now hinges on real-time data fluidity across previously siloed care settings.
Cloud-native EHR platforms are decentralizing data storage and processing away from centralized hospital data centers toward distributed edge nodes within individual skilled nursing facilities. Regional chains with 10-50 facilities are adopting these architectures fastest, driven by latency requirements for real-time eMAR alerts and local backup mandates. This shift is decentralizing IT purchasing authority from corporate headquarters to individual facility administrators, fragmenting vendor sales cycles.
CMS Conditions of Participation for electronic health records now require standardized assessment data submission within 24 hours of admission, creating compliance urgency across Medicare-certified nursing homes. The rule compresses implementation timelines for interoperability modules and penalizes facilities using non-compliant legacy systems. Southeast operators in Florida and Georgia are responding fastest, with state Medicaid agencies aligning their own reporting requirements to the federal standard.
Subscription-based pricing models are displacing perpetual license arrangements across mid-size regional chains, unbundling implementation and training costs from core software fees. Direct sales teams are losing ground to value-added resellers specializing in long-term care IT, particularly in secondary Midwest markets. This pattern is most visible in Ohio and Michigan, where independent living facility operators now prefer reseller-managed support over direct vendor relationships.
US Long Term Care Software Market Segmentation
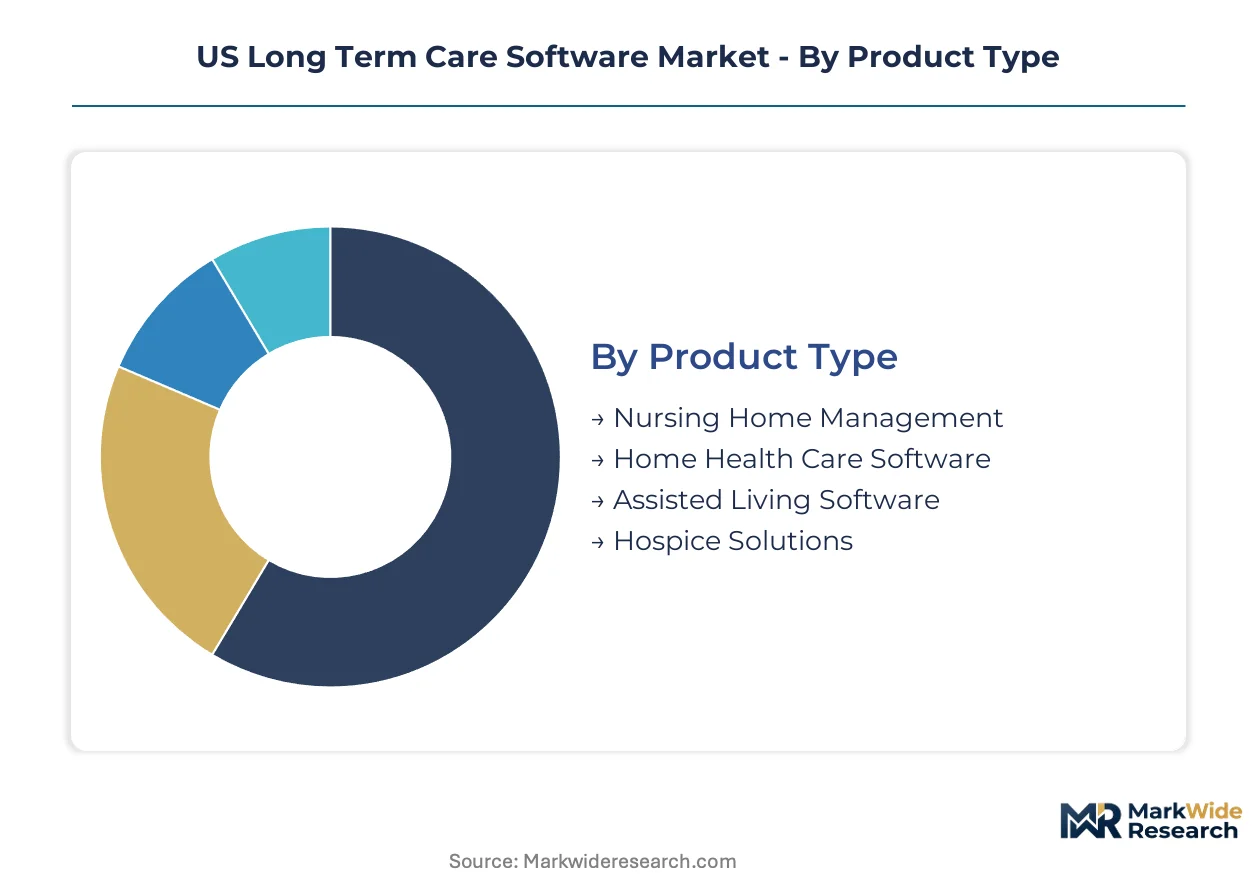
Segmentation in US long-term care software reveals how procurement authority fragments across facility types, deployment constraints, and regulatory exposure zones. Vendors must align product architecture with the specific compliance burdens and workflow patterns of each buyer category.
Product Type:
Supply concentration in this category clusters around platforms that unify clinical and financial workflows under single-vendor relationships, with Southeast regional chains driving procurement volume.
- Nursing Home Management:Comprehensive platforms managing resident records, eMAR integration, and CMS-optimized billing engines for skilled nursing facilities. Demand concentrates in Florida and Georgia where facility consolidation accelerates replacement of fragmented legacy installations. CMS Conditions of Participation mandate 24-hour assessment data submission, compressing implementation timelines.
- Home Health Care Software:Specialized modules for remote patient monitoring, visit documentation, and hospital-at-home reimbursement workflows. Texas and Florida Medicaid agencies now require real-time claims processing integration, pulling procurement forward among regional home health operators. This segment gains share fastest as CMS Innovation Center waivers expand reimbursable status for bundled remote care.
- Assisted Living Software:Medication administration and resident engagement tools designed for lower-acuity continuing care environments.
- Hospice Solutions:Palliative care documentation platforms with Medicare hospice benefit billing specialization and bereavement tracking functionality.
Today's leader: Nursing Home Management. Tomorrow's challenger: Home Health Care Software.
End User:
Cost tier differentiation separates enterprise-grade implementations from scaled-down configurations, with compliance infrastructure requirements widening the procurement gap between national chains and independent operators.
- Healthcare Providers:Physician groups and post-acute care networks requiring HL7 FHIR-compliant data exchange with hospital EHR systems. Southeast integrated delivery networks prioritize interoperability modules that bridge acute and long-term care records. HIPAA security rule enforcement imposes compliance costs that favor established vendors with dedicated legal infrastructure.
- Residential Facilities:Skilled nursing and assisted living operators managing 10-50 facilities across regional chains. Ohio and Michigan independent living operators increasingly prefer reseller-managed support relationships over direct vendor engagement. Procurement authority is decentralizing from corporate headquarters to individual facility administrators.
- Family Caregivers:Consumer-facing applications for care coordination and remote monitoring of home-based seniors.
- Rehabilitation Centers:Inpatient and outpatient therapy providers requiring functional outcome tracking and Medicare Part B billing optimization.
Healthcare Providers command premium pricing. Residential Facilities drive volume expansion.
Deployment:
Volume distribution in this category reflects legacy infrastructure entrenchment in rural markets versus cloud-native urgency in consolidated urban systems.
- Cloud-Based:Fully hosted platforms with AWS or Azure healthcare-compliant infrastructure, automatic updates, and subscription pricing. Southeast operators adopt these fastest due to latency requirements for real-time eMAR alerts and state Medicaid real-time claims mandates. AWS and Azure pricing fluctuations squeeze margins for mid-size vendors serving regional chains.
- Hybrid Solutions:Architectures combining cloud-based clinical modules with on-premise financial systems, retaining substantial share among mid-size regional chains managing legacy infrastructure transitions. Rural Midwest facilities with decades-old installations use hybrid approaches to phase cloud migration without disrupting revenue cycle operations.
- On-Premise:Self-hosted installations requiring dedicated server infrastructure and internal IT maintenance capabilities.
- Mobile Applications:Point-of-care documentation tools for nursing staff and field-based home health clinicians.
Cloud-Based dominates new procurement. Hybrid Solutions capture transition-phase demand.
Functionality:
Customer type segmentation separates clinical workflow tools from revenue integrity systems, with integrated suites commanding pricing premiums over standalone modules.
- Patient Management:Resident admission, assessment, care planning, and clinical documentation modules with CMS-compliant assessment data structures. Demand concentrates in skilled nursing facilities facing compressed implementation timelines from federal and state reporting mandates. Southeast operators in Florida and Georgia respond fastest to compliance urgency.
- Billing Solutions:Claims processing engines optimized for Medicare, Medicaid, and private payor reimbursement rules, including CMS-optimized billing for Medicare-certified nursing homes. Texas, Florida, and Georgia MMIS upgrades require real-time claims processing integration, forcing legacy system replacements among regional operators.
- Scheduling Tools:Staff rostering and visit coordination systems addressing high-turnover nursing workforce management.
- Reporting Analytics:Operational dashboards and regulatory submission tools for quality measure reporting and survey preparation.
Patient Management anchors clinical platform sales. Billing Solutions unlock revenue cycle replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Southeast corridor anchors procurement momentum, where Florida and Georgia facility consolidation accelerates cloud-native platform adoption. State Medicaid agencies in Texas and the Carolinas compress implementation timelines through real-time claims mandates. Regional chains across these markets prioritize interoperable systems that unify clinical and financial workflows.
Southeast
Florida and Georgia lead skilled nursing facility consolidation, driving replacement of fragmented legacy installations with integrated EHR platforms. CMS Conditions of Participation mandate 24-hour assessment data submission, compressing vendor implementation timelines. The Atlanta-Orlando corridor concentrates regional chain headquarters where procurement authority decentralizes to facility administrators.
Southwest
Texas Medicaid Management Information System upgrades require real-time claims processing integration, forcing legacy system replacements among regional home health operators. Hospital-at-home program expansion under CMS Innovation Center waivers creates immediate procurement pull for remote patient monitoring bundled with software. Dallas-Fort Worth anchors the state's largest concentration of post-acute care networks.
Midwest
Ohio and Michigan independent living facility operators increasingly prefer reseller-managed support relationships over direct vendor engagement. Decades-old on-premise installations in rural areas create technical debt that slows cloud migration timelines. The Cleveland-Detroit corridor retains substantial hybrid solution adoption as regional chains phase transitions without disrupting revenue cycle operations.
Northeast
New York and Massachusetts integrated delivery networks prioritize interoperability modules bridging acute and long-term care records. HIPAA security rule enforcement imposes compliance costs favoring established vendors with dedicated legal infrastructure. The Boston-Washington corridor concentrates healthcare IT specialist talent commanding premium salaries.
Mountain West
Colorado and Arizona skilled nursing operators adopt cloud-native architectures fastest outside the Southeast, driven by latency requirements for real-time eMAR alerts. Federally Qualified Health Center networks in rural Appalachia extensions remain underpenetrated for integrated EHR-long-term care platforms. Denver anchors regional purchasing decisions for Mountain West facility chains.
US Long Term Care Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-assisted clinical documentation and edge computing specialization. The vendor base stratifies across three tiers: cloud-native platform specialists, hybrid solution providers managing legacy transitions, and niche reimbursement workflow tool vendors. Two strategic archetypes dominate: interoperability-first architects and revenue-cycle-optimized specialists. Competitive moves concentrate on strategic partnerships with state Medicaid agencies and portfolio diversification into behavioral health-post-acute convergence.
Within the cloud-native platform tier, PointClickCare and MatrixCare exemplify divergent specialization strategies. PointClickCare anchors skilled nursing interoperability through architecture designed for multi-facility data exchange. MatrixCare occupies a position emphasizing home health reimbursement workflows as hospital-at-home programs expand. Netsmart Technologies, Inc. represents the behavioral health-post-acute convergence archetype, extending platform reach into community-based care coordination. These three entities collectively illustrate how vendor differentiation now hinges on real-time data fluidity across previously siloed care settings.
| Leading Market Players |
|---|
| PointClickCare |
| MatrixCare |
| Netsmart Technologies, Inc. |
| Veradigm LLC |
| Oracle Corporation |
| McKesson Corporation |
| Omnicell, Inc. |
| WellSky |
| SigmaCare |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up regional software vendors anchor supply concentration in the US long-term care software market, consolidating fragmented development talent into platform portfolios that extract pricing power through bundled clinical-financial modules. Their ownership structure enforces pricing discipline by prioritizing recurring revenue multiples over perpetual license cash flows, reshaping how mid-size operators negotiate subscription terms.
Pricing Analysis
AWS and Azure healthcare-compliant hosting cost pass-throughs squeeze margins for mid-size vendors serving regional chains, forcing tiered pricing adjustments. Three-tier pricing structure across enterprise, mid-market, and independent facility levels separates functionality bundles by interoperability depth and CMS compliance automation. Pricing pressure stems from cloud infrastructure volatility as hyperscalers adjust healthcare workload rates. Independent living operators in Ohio and Michigan exhibit highest price sensitivity, while Southeast integrated delivery networks accept premium tiers for real-time claims integration.
Supply Chain Analysis
Freight costs for edge computing hardware deployments to rural Midwest facilities inflate implementation margins, particularly for hybrid solution providers managing legacy infrastructure transitions. Software development concentrates in the United States, with specialized healthcare IT talent clusters in the Boston-Washington corridor and Atlanta-Orlando corridor. Raw material dependencies include semiconductor components for on-premise servers, healthcare-grade encryption modules, and FDA-validated medical device software libraries. Supply chain risk centers on single-source vulnerability for HL7 FHIR interoperability specialists commanding premium compensation. Distribution runs through value-added resellers specializing in long-term care IT, particularly in secondary Midwest markets where direct vendor relationships are losing ground.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US long-term care software rests on AI-assisted clinical documentation reducing nursing administrative burden, enabling premium pricing for labor-saving modules while compressing implementation costs through automated training workflows.
For Market Incumbents: Cement dominance by acquiring edge computing specialists to decentralize data processing for regional chains demanding local backup mandates. Deepen vertical integration into behavioral health-post-acute convergence platforms before Netsmart extends its community-based care coordination moat. Prioritize HL7 FHIR talent retention through dedicated compliance infrastructure investments as interoperability specialist scarcity intensifies hiring competition.
For New Entrants and Emerging Players: Rural Federally Qualified Health Center networks in Appalachia and the Mississippi Delta offer white-space penetration with minimal incumbent saturation. Target hospital-at-home reimbursement workflow tools as CMS Innovation Center waivers expand across fourteen states, pulling immediate procurement demand. Pursue reseller-managed support relationships over direct sales to match Ohio and Michigan independent living operator preferences.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid solution providers managing legacy infrastructure transitions for rural Midwest facilities, where technical debt delays cloud migration timelines. Long-term viability favors vendors with dedicated legal infrastructure navigating state-level HIPAA breach notification law variations. Watch CMS Innovation Center waiver expansion as the inflection signal determining which functionality bundles achieve reimbursable status and drive purchasing priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies clinical, operational, and financial workflows under single-vendor relationships for Southeast regional chains. |
| Acquisition of Specialist Firm | Captures HL7 FHIR interoperability talent scarce in vendor hiring pipelines and commanding premium salaries. |
| Strategic Partnership | Aligns with state Medicaid agencies in Texas, Florida, and Georgia for real-time claims processing mandates. |
| Product Launch | Introduces AI-assisted clinical documentation reducing nursing administrative burden in high-turnover environments. |
| Geographic Expansion | Penetrates Federally Qualified Health Center networks in Appalachia and Mississippi Delta underintegrated for EHR platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with long-term care IT directors, skilled nursing facility administrators, home health agency operators, and value-added reseller channel partners with secondary validation. CMS Medicare data, state Medicaid Management Information System procurement records, hospital procurement databases, and GPO contracts anchored volume estimates. Bottom-up facility counts and top-down software spending patterns were triangulated against vendor-reported subscription metrics.
Historical reference periods anchored the forecast window to established technology replacement cycles and regulatory compliance deadlines. Segmentation modeling spanned deployment model, facility size tier, care setting type, and regional Medicaid modernization pattern. CAGRs were derived from fitted adoption curves incorporating CMS Conditions of Participation enforcement timelines and state-level MMIS upgrade schedules. Forecast inputs included cloud infrastructure cost trajectories and HL7 FHIR implementation penetration rates across post-acute networks.
Inputs from CMS Innovation Center waiver announcements and state Medicaid agency procurement databases were available through the study window; gaps in real-time cloud hosting cost forecasting introduce uncertainty bands around vendor margin projections. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Practice Management System (PMS) Market
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Global Pharmacy Inventory Management Software Solutions and Cabinets Market
Healthcare IT
Global Pharmacy Management System Market