
 Healthcare Revenue Cycle Management (RCM) Software Market | 2026-2036
Healthcare Revenue Cycle Management (RCM) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Revenue Cycle Management (RCM) Software Market Foresight
Subscription-based software-defined revenue cycle features is expanding the addressable market beyond traditional perpetual licenses. Oracle leverages its enterprise cloud footprint to anchor hospital system deployments. Waystar competes through specialized claims management automation. athenahealth differentiates via channel control across physician group networks.
Healthcare Revenue Cycle Management (RCM) software comprises integrated financial processing systems that automate patient registration, insurance eligibility verification, medical coding, claims submission, payment posting, and denial management through HL7 FHIR-compliant data exchange protocols. Cloud-based deployments lead product type adoption as hospitals prioritize remote accessibility and reduced infrastructure overhead. Claims Management application segments capture concentrated margin pools due to complexity-driven pricing power. Ambulatory Services end users represent the fastest-growing deployment category as independent practices seek enterprise-grade financial tooling without capital expenditure burdens.
ONC Cures Act Final Rule interoperability mandates and CMS price transparency requirements are reshaping RCM software specifications, forcing vendors to embed real-time patient estimation and API-first architectures. HIPAA security rule enforcement by the Office for Civil Rights sustains demand for private cloud and hybrid deployment models with encrypted audit trails. Stakeholders must monitor evolving CMS reimbursement rulemaking and state-level surprise billing legislation to align product roadmaps with compliance-driven purchasing cycles.
Market Dynamics
Medicare reimbursement complexity and prior authorization digitization mandates are compressing hospital administrative margins, forcing accelerated procurement of integrated claims automation platforms that consolidate fragmented billing workflows into unified cloud architectures.
Growth Catalysts
- ONC Cures Act Final Rule:Interoperability mandates compel health systems to replace siloed billing systems with API-first RCM platforms that enable real-time data exchange across provider networks.
- Prior authorization automation:Payers and providers deploy intelligent prior authorization modules to reduce manual documentation burdens and accelerate approval cycles for high-value procedures.
- Cloud migration imperatives:HIPAA security rule enforcement drives demand for private cloud and hybrid deployment models with encrypted audit trails and remote accessibility.
Market Restraints
- Implementation cost barriers:Mid-sized physician practices face prohibitive upfront migration expenses when transitioning from legacy on-premise billing systems to subscription-based cloud platforms.
- Technical debt accumulation:Decades-old HL7 v2 interfaces in hospital EHR environments create integration friction that delays FHIR-compliant RCM deployment timelines.
- Specialized talent scarcity:Health informaticists with dual expertise in medical coding and cloud architecture command premium compensation that strains vendor delivery capacity.
Strategic Opportunities
- Rural health clinic digitization:Federally Qualified Health Centers in underserved regions seek turnkey RCM solutions to qualify for value-based care reimbursement programs.
- Surprise billing compliance:State-level balance billing legislation creates demand for patient estimation tools that calculate out-of-pocket costs before service delivery.
- AI-augmented coding convergence:Natural language processing engines paired with clinical documentation improvement platforms reduce denial rates through automated code validation.
Industry Challenges
- Interoperability certification delays:ONC certification timelines for new FHIR-based modules extend product release cycles and compress competitive windows.
- Legacy EHR integration complexity:Custom interface development for entrenched hospital information systems consumes disproportionate engineering resources relative to standardized deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Revenue Cycle Management (RCM) Software Market |
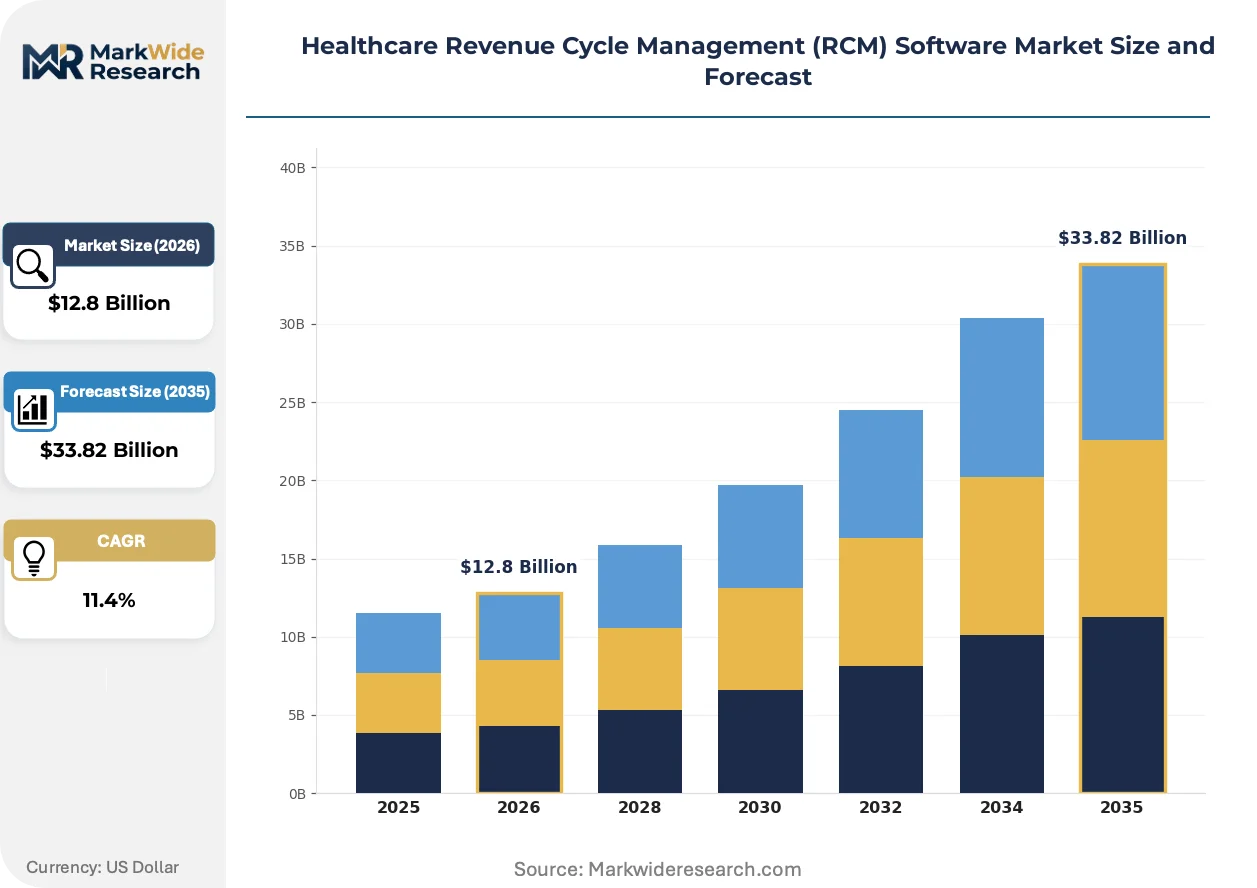
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile End User: Hospitals, Physician Groups, Clinics, Ambulatory Services Deployment Model: Public Cloud, Private Cloud, Managed Service, Hybrid Model Application: Claims Management, Payment Processing, Revenue Management, Patient Access |
| Companies Covered | CureMD, PracticeSuite, athenahealth, CareCloud, AdvancedMD, Waystar, Greenway Health, DrChrono, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Revenue Cycle Management (RCM) Software Market Shifts & Advancements
Artificial intelligence and machine learning capabilities are penetrating core RCM functions, shifting competitive advantage toward vendors that embed predictive analytics directly into claims processing workflows rather than offering bolt-on analytics modules.
Robotic process automation is automating high-volume, rules-based tasks across eligibility verification, payment posting, and denial appeals. Hospital revenue cycle departments deploy software bots to handle repetitive data entry that previously consumed full-time equivalent staff. This automation is compressing cost-to-collect metrics and enabling redeployment of specialized staff toward complex denial resolution.
CMS price transparency requirements and the No Surprises Act implementation are mandating real-time patient cost estimation capabilities. Hospitals must now provide good faith estimates before scheduled services, compelling RCM vendors to integrate chargemaster data with payer-specific benefit engines. Ambulatory surgery centers and hospital outpatient departments face the steepest compliance curves.
Subscription pricing models are displacing perpetual license structures across physician group networks. Independent practices prefer operational expenditure treatment for software costs that aligns with their cash flow patterns. This shift concentrates vendor revenue into recurring streams and extends customer lifetime value calculations.
Healthcare Revenue Cycle Management (RCM) Software Market Segmentation
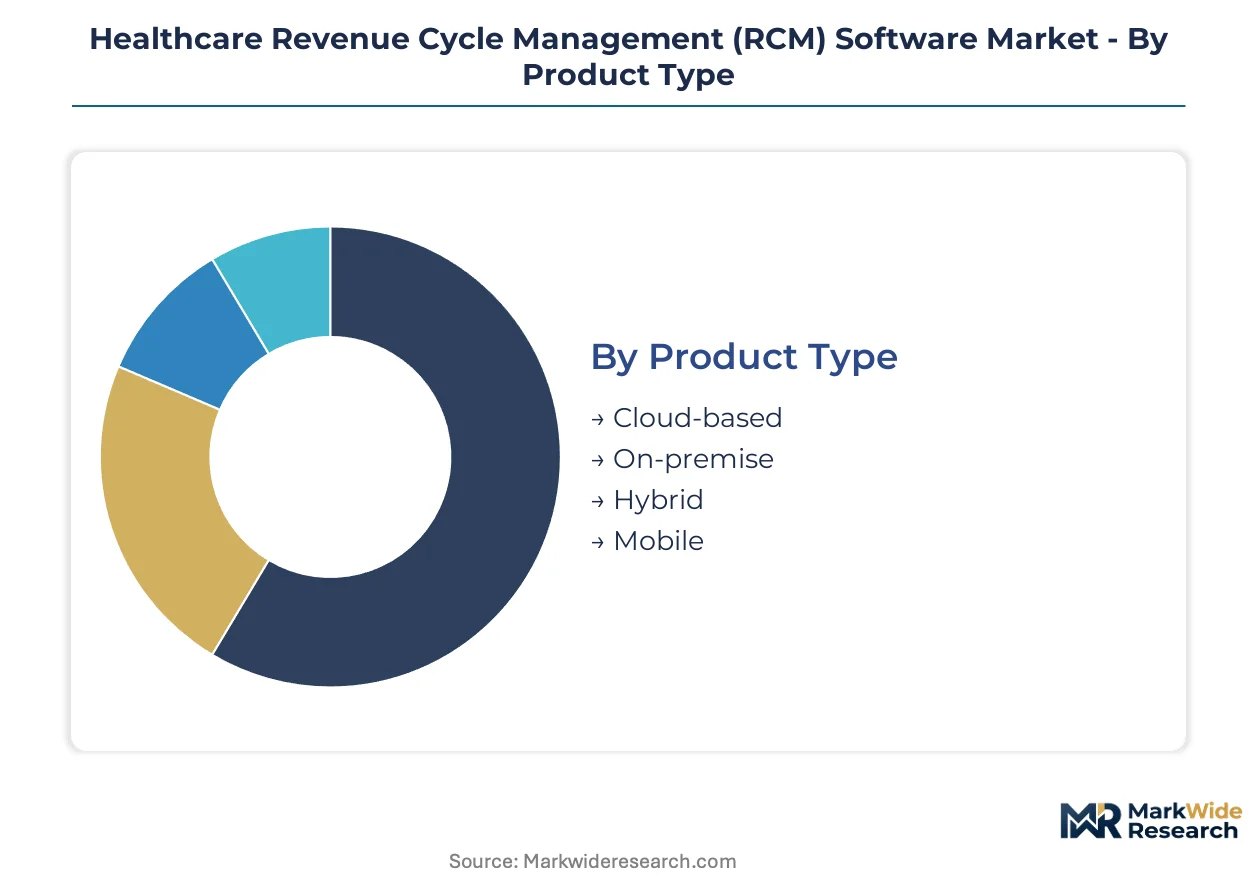
RCM software segmentation reveals how procurement priorities diverge between capital-constrained ambulatory networks and enterprise health systems with dedicated IT infrastructure. Understanding these fault lines enables vendors to align pricing architectures and implementation timelines with buyer capabilities.
Product Type:
Customization intensity varies sharply across this category, from turnkey cloud subscriptions requiring minimal configuration to on-premise deployments demanding extensive workflow engineering.
- Cloud-based:Multi-tenant SaaS architectures deliver automatic updates and remote accessibility through browser-based interfaces. Hospital systems in the United States prioritize these platforms to satisfy HIPAA security rule enforcement while eliminating data center overhead.
- On-premise:Single-tenant installations residing within provider-controlled server environments. Large integrated delivery networks with legacy EHR investments maintain these deployments to preserve custom interface configurations and localized data sovereignty.
- Hybrid:Split architectures combining cloud-based analytics with on-premise transaction processing. Organizations with mixed compliance requirements deploy this model to isolate protected health information while leveraging external compute for reporting workloads.
- Mobile:Native applications and responsive web interfaces enabling revenue cycle staff to perform eligibility verification and payment posting from tablets and smartphones. Field-based patient financial counselors at rural health clinics drive adoption of these tools.
Leading the category by volume: Cloud-based. Expanding most quickly: Mobile.
End User:
Buyer sophistication and procurement authority create distinct margin tiers across this category, from centralized hospital purchasing committees to individual physician practice administrators.
- Hospitals:Acute care facilities and health systems with complex billing operations spanning inpatient, outpatient, and emergency department encounters. These buyers command volume discounts and demand comprehensive implementation support from vendors.
- Physician Groups:Multi-specialty and single-specialty practices with centralized billing operations. Independent practice associations in the United States aggregate purchasing power to negotiate subscription terms that align with their cash flow patterns.
- Clinics:Federally Qualified Health Centers and community health centers serving underserved populations. Medicare reimbursement complexity and value-based care reporting requirements drive these organizations toward integrated platforms.
- Ambulatory Services:Outpatient surgery centers, imaging facilities, and diagnostic laboratories. This segment gains share fastest as independent practices seek enterprise-grade financial tooling without capital expenditure burdens.
Highest contract values: Hospitals. Steepest expansion trajectory: Ambulatory Services.
Deployment Model:
Control over infrastructure stack versus operational burden trade-offs segment this category by organizational risk tolerance and IT staffing levels.
- Public Cloud:Shared infrastructure environments operated by hyperscale providers with healthcare-specific compliance certifications. Smaller physician groups favor this model for predictable monthly costs and minimal technical staffing requirements.
- Private Cloud:Dedicated single-tenant environments with encrypted audit trails and customized security policies. Hospital systems with stringent data residency requirements deploy these to satisfy HIPAA security rule enforcement.
- Managed Service:Outsourced operations where vendors assume responsibility for infrastructure management, patching, and availability monitoring. Organizations with limited health informaticists on staff prefer this hands-off approach.
- Hybrid Model:Combinations of private cloud for protected health information and public cloud for non-sensitive analytics workloads. Health systems navigating ONC Cures Act interoperability mandates adopt this architecture to balance compliance with innovation velocity.
Dominant by installed base: Public Cloud. Climbing fastest: Hybrid Model.
Application:
Workflow complexity and denial rate exposure determine pricing power across functional modules, with claims-intensive applications commanding premium positioning.
- Claims Management:End-to-end automation of claim scrubbing, submission, tracking, and denial appeals through payer-specific rule engines. This module captures concentrated margin pools due to complexity-driven pricing and measurable ROI through reduced denial rates.
- Payment Processing:Integration of patient financial responsibility estimation, point-of-service collections, and payment plan administration. Ambulatory surgery centers facing CMS price transparency requirements deploy these tools to generate good faith estimates.
- Revenue Management:Dashboards and analytics consolidating key performance indicators across the revenue cycle. Chief financial officers at hospital systems rely on these platforms to monitor days in accounts receivable and net collection rates.
- Patient Access:Front-end workflows encompassing scheduling, registration, insurance eligibility verification, and prior authorization initiation. Prior authorization digitization mandates are accelerating procurement of these modules.
Highest vendor margins: Claims Management. Gaining share fastest: Patient Access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nashville anchors North American RCM software concentration, hosting dense clusters of health IT vendors and hospital system headquarters that drive procurement standards across the United States.
United States
Medicare reimbursement complexity and prior authorization digitization mandates compress hospital administrative margins, forcing accelerated procurement of integrated claims automation platforms. HIPAA security rule enforcement by the Office for Civil Rights sustains demand for private cloud deployments with encrypted audit trails. The Nashville-Dallas corridor concentrates vendor engineering talent and health system pilot programs.
Germany
Hospital digitization funding under the Hospital Future Act (KHZG) accelerates EHR-to-RCM integration projects across acute care networks. The EU AI Act and GDPR compliance requirements shape vendor selection criteria for predictive billing analytics. The Rhine-Ruhr metropolitan region hosts concentrated health IT implementation partnerships between university hospitals and software vendors.
United Kingdom
NHS England's Federated Data Platform procurement creates standardization pressure for revenue cycle modules within integrated care systems. The UK GDPR and NHS Digital security standards mandate API-first architectures for patient financial data exchange. London's health tech cluster drives early adoption of AI-augmented coding tools among private hospital groups.
India
Medical tourism billing complexity and NABH accreditation requirements push corporate hospital chains toward automated claims management. The Digital Personal Data Protection Act and Ayushman Bharat digital health mission reshape interoperability specifications for revenue cycle platforms. Bengaluru's health IT export sector delivers RCM implementation services to North American and Middle Eastern markets.
Japan
Aging population demographics and social insurance reimbursement rule revisions drive demand for automated patient access and eligibility verification modules. METI's Society 5.0 healthcare digitization roadmap encourages FHIR-compliant platform adoption. The Tokyo-Osaka corridor concentrates vendor partnerships between regional medical associations and cloud infrastructure providers.
Healthcare Revenue Cycle Management (RCM) Software Market Competitive Landscape
Capital-heavy enterprise cloud providers compete with asset-light specialized vendors across the RCM software market, creating a tiered structure where scale advantages fragment across functional modules. The vendor base clusters around three strategic archetypes: horizontal platform giants extending healthcare verticals, purpose-built revenue cycle specialists, and physician practice-focused SaaS providers. Consolidation pressure intensifies as hospital systems demand unified billing workflows rather than fragmented point solutions. Dominant competitive moves include strategic partnerships with EHR vendors and geographic expansion through channel reseller networks.
Within the enterprise platform tier, Oracle leverages its cloud infrastructure footprint to anchor hospital system deployments. Waystar occupies a specialized position in claims management automation, while athenahealth exemplifies the physician network channel control model. These three anchors represent divergent bets on whether RCM procurement centralizes under IT procurement officers, revenue cycle directors, or practice administrators.
| Leading Market Players |
|---|
| CureMD |
| PracticeSuite |
| athenahealth |
| CareCloud |
| AdvancedMD |
| Waystar |
| Greenway Health |
| DrChrono |
| Oracle |
| Others |
Supply & Pricing Matrix
Enterprise-to-ambulatory tier divergence separates subscription-based SaaS deployments from perpetual license installations, with cloud-native platforms commanding recurring revenue premiums while legacy on-premise systems face cost compression from infrastructure maintenance burdens. This bifurcation concentrates vendor engineering resources in the United States and India while pricing power accumulates with multi-tenant architectures that automate claims processing at scale.
Pricing Analysis
Cost-down pressure on mid-market physician groups accelerates because subscription pricing models displace perpetual licenses, forcing vendors to absorb implementation overhead into recurring fees. Three-tier pricing structure across premium, standard, and economy levels aligns with ONC certification tiers and FHIR compliance depth, with HIPAA-encrypted private cloud deployments capturing margin premiums. Price differentiation rests on integration complexity and prior authorization automation sophistication. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints, while integrated delivery networks negotiate volume discounts based on encounter volume guarantees.
Supply Chain Analysis
Reverse-logistics flows for RCM software center on data migration services and legacy system decommissioning, with vendors offering transition credits to accelerate cloud adoption. Engineering talent concentrates in the United States, India, and Germany, with Bengaluru delivery centers supporting North American implementation timelines. Cloud infrastructure dependencies draw from AWS, Azure, and Google Cloud healthcare sovereign regions. Single-source vulnerability emerges from concentrated FHIR certification bodies delaying product releases. Distribution runs through direct enterprise sales teams, channel reseller networks, and GPO-aggregated purchasing for hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health informaticist scarcity props pricing for implementation services, constraining vendor delivery capacity and extending sales cycles for complex hospital deployments.
For Market Incumbents: Hedge against cloud-native disruptors by embedding AI-augmented coding modules directly into core platforms rather than offering bolt-on analytics. Acquire specialized prior authorization automation firms to consolidate claims management workflows. Strengthen EHR integration partnerships to lock out point-solution competitors. For New Entrants and Emerging Players: Enter via Federally Qualified Health Centers in underserved rural regions, where turnkey RCM solutions address value-based care reporting gaps with minimal incumbent presence. Target surprise billing compliance modules for ambulatory surgery centers facing steep CMS price transparency curves. Pursue channel partnerships with regional health IT consultants for faster credentialing. For Investors and Strategic Acquirers: Re-rating potential sits with AI-augmented coding specialists given denial rate reduction metrics that demonstrate measurable ROI to hospital CFOs. Long-term viability favors vendors with established FHIR certification pipelines and hospital system reference accounts. Monitor ONC certification backlog clearance as inflection indicator for product release velocity and competitive window expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates fragmented billing workflows into unified cloud architectures for hospital systems. |
| Strategic Partnership | EHR vendor alliances accelerate FHIR-compliant data exchange across provider networks. |
| Acquisition of Specialist Firm | Prior authorization automation targets compress approval cycles for high-value procedures. |
| Geographic Expansion | Rural health clinic digitization unlocks value-based care reimbursement program eligibility. |
| Product Launch | Real-time patient estimation tools satisfy CMS price transparency and No Surprises Act mandates. |
Research Methodology
CMS Medicare claims databases, hospital procurement records, and ONC certification registries formed the secondary backbone, supplemented by SEC filings from publicly traded health IT vendors. Revenue cycle directors, hospital CIOs, and GPO contracts managers provided primary perspective on procurement criteria and implementation timelines. Health informaticists and cloud architecture specialists contributed technical validation on FHIR deployment complexity. Bottom-up encounter volume modeling and top-down health IT spending analysis enabled cross-verification of market sizing.
Bottom-up segmentation by deployment model, organization size, and application module generated granular revenue projections across the analysis window. Top-down healthcare IT budget allocation trends from hospital system financial disclosures anchored aggregate market boundaries. CAGRs derived from compound growth trajectory fitting across modeled scenarios. Prior authorization digitization mandates and HIPAA enforcement intensity served as key demand-side forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under delayed ONC certification timelines or accelerated legacy EHR replacement cycles. Practitioners should monitor CMS reimbursement rulemaking velocity and state-level surprise billing legislation passage for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
E-Prescribing Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
US Practice Management Systems Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Healthcare Technology Management Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Femtech Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Healthcare IT Market