
 Post-Acute Transition Care Coordination Platform Market | 2026-2036
Post-Acute Transition Care Coordination Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Acute Transition Care Coordination Platform Market Insights
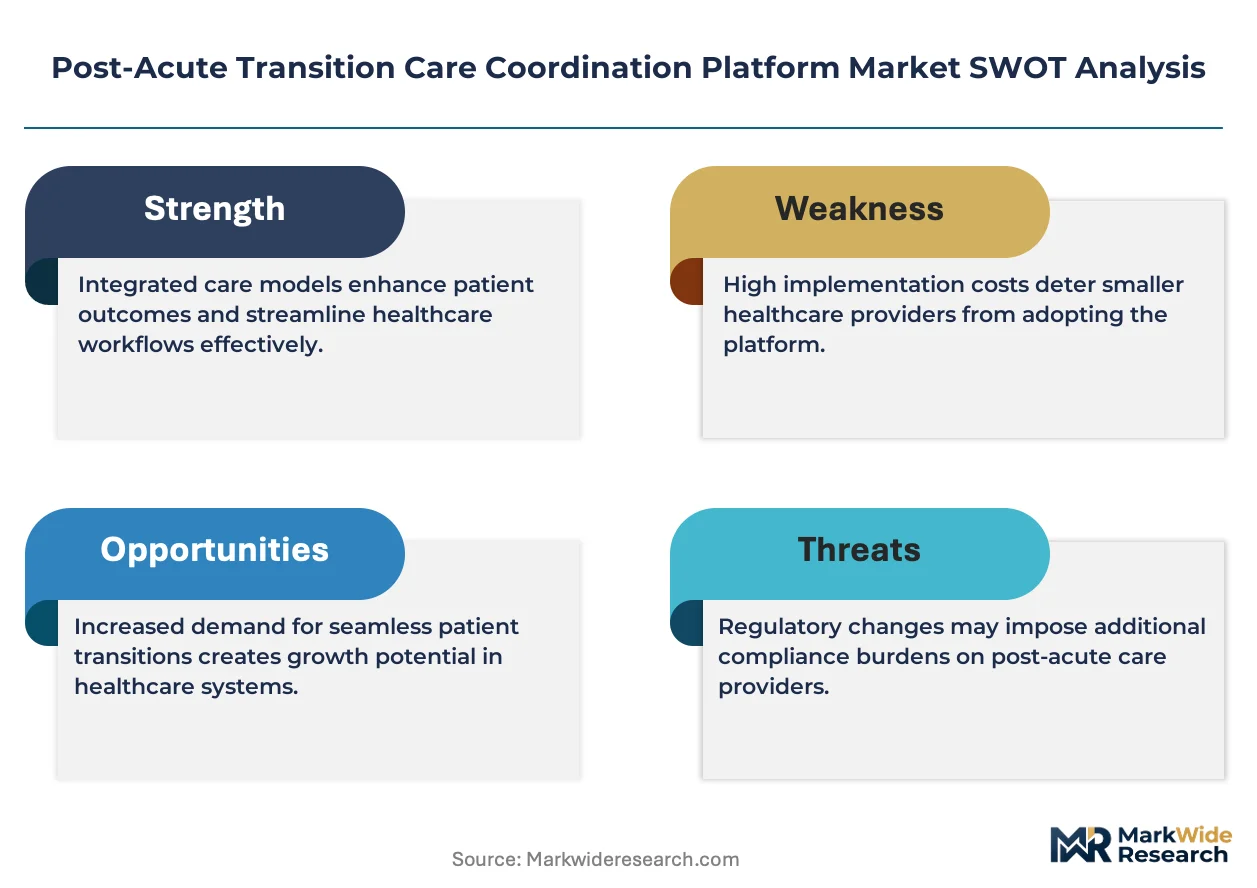
ONC Health IT Certification is rotating competitive dynamics toward vendors with proven interoperability credentials. WellSky leverages deep integration with acute EHR networks to sustain hospital referral relationships. PointClickCare anchors its position through dominance in skilled nursing facility data infrastructure. Oracle Health competes by extending enterprise cloud architecture into post-acute workflows.
Post-acute transition care coordination platforms are software systems that manage patient information exchange, referral routing, and outcome tracking across care settings, typically operating through HL7 FHIR APIs and real-time data pipelines to ensure continuity after hospital discharge. Their primary commercial purpose is reducing preventable readmissions and optimizing reimbursement under value-based contracts. Cloud-based deployment leads platform type adoption because it lowers capital barriers for home health agencies and hospice providers. Skilled nursing facilities represent the most mature care setting segment, though rehabilitation centers show the fastest expansion as bundled payment models tighten. Integration capability with EHR systems captures the largest margin pool, since seamless data exchange commands premium pricing.
FDA oversight of clinical decision support functions, ONC certification requirements under the 21st Century Cures Act, and HIPAA security rule enforcement collectively shape product development timelines and vendor eligibility. These frameworks compel platforms to maintain audit trails, standardized APIs, and patient access portals as baseline market access requirements. Stakeholders must monitor how CMS reimbursement rulemaking shifts financial risk between acute and post-acute providers, as this determines which platform features become essential versus optional.
Market Dynamics
Interoperability mandates under the ONC Cures Act Final Rule are compressing vendor timelines and forcing consolidation around FHIR-certified platforms, while Medicare readmission penalties create immediate financial urgency for hospital-post-acute data bridges.
Growth Catalysts
- Medicare Hospital Readmissions Reduction Program:Financial penalties for excessive 30-day readmissions compel acute care networks to invest in bidirectional data exchange with post-acute partners.
- Skilled nursing facilities:SNFs are accelerating platform procurement to secure hospital referral volume and demonstrate outcome accountability under bundled payment arrangements.
- HL7 FHIR R4 APIs:Standardized data exchange protocols reduce integration friction and enable real-time patient handoff documentation across disparate EHR environments.
Market Restraints
- Legacy EHR technical debt:Proprietary data architectures in incumbent acute care systems resist standardized API integration, forcing expensive middleware development.
- ONC certification timeline:Multi-quarter approval processes for interoperability compliance delay product launches and freeze procurement decisions.
- Rural home health agency capital constraints:Thin operating margins and limited IT staffing block cloud platform adoption outside urban referral corridors.
Strategic Opportunities
- Rehabilitation centers:Bundled payment expansion for joint replacement and cardiac recovery creates demand for episode-specific outcome tracking tools.
- CMS ACO REACH model:Direct contracting entities require advanced attribution and reconciliation capabilities that incumbent platforms underserve.
- AI-enabled risk stratification:Machine learning integration with real-time ADT feeds enables proactive intervention triggers before clinical deterioration.
Industry Challenges
- Health informaticist shortage:Cross-functional expertise spanning clinical workflows, FHIR implementation, and value-based contracting commands premium compensation and extends implementation timelines.
- Multi-stakeholder data governance:Disputed patient record ownership between hospitals, SNFs, and physician groups complicates consent management architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Acute Transition Care Coordination Platform Market |
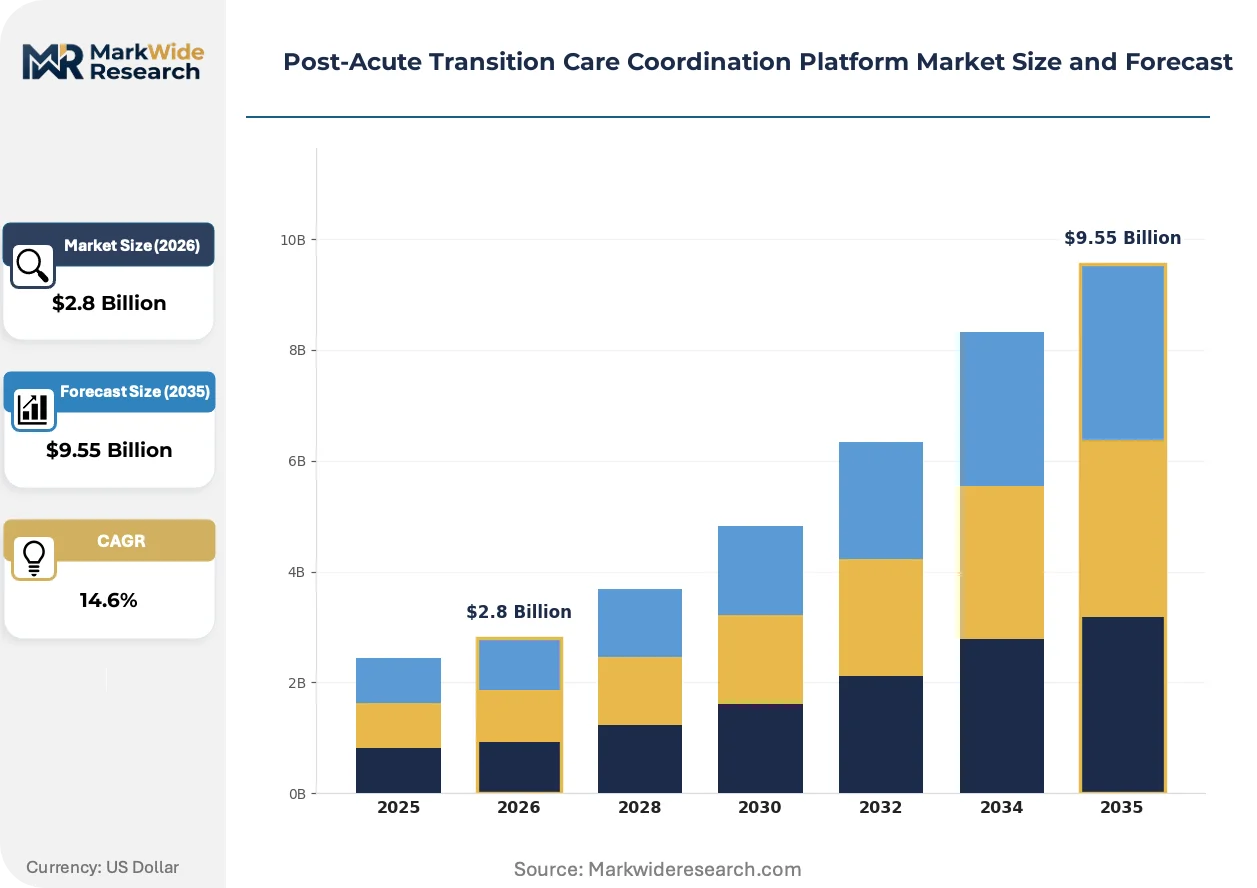
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premise, Hybrid, SaaS Care Setting: Skilled Nursing Facilities, Home Health Agencies, Rehabilitation Centers, Hospice Providers User Role: Case Managers, Discharge Coordinators, Caregivers, Social Workers Integration Capability: EHR Systems, Billing Software, Patient Scheduling, Telehealth Services |
| Companies Covered | WellSky, PointClickCare, Oracle Health, Bamboo Health, Aidin, Dina, Trella Health, MatrixCare, CareCentrix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Acute Transition Care Coordination Platform Market Trends and Innovations
Platform architecture is pivoting from document-based exchange to event-driven streaming, with vendors racing to embed predictive analytics at the point of transition rather than retrospectively.
Modular microservices architecture is decomposing monolithic care coordination suites into interoperable components. Home health agencies and hospice networks are adopting these discrete modules faster than full-platform replacements. This decomposition is compressing vendor maintenance revenue streams while accelerating third-party innovation in specialized transition functions.
The ONC Cures Act Final Rule's information blocking provisions are reshaping data-sharing obligations. Penalties for intentional interference with patient data access now extend to post-acute providers previously exempt from interoperability mandates. Skilled nursing facilities face the steepest compliance curve, driving emergency procurement of certified gateway technologies.
Purchasing committees now require demonstrated ROI in readmission reduction within 12-month payback windows. Health system supply chain functions are displacing departmental IT autonomy in platform selection, centralizing vendor negotiations and demanding outcome guarantees. This concentration is most visible in multi-state Catholic health systems consolidating post-acute technology stacks across dozens of affiliated SNFs.
Post-Acute Transition Care Coordination Platform Market Segmentation
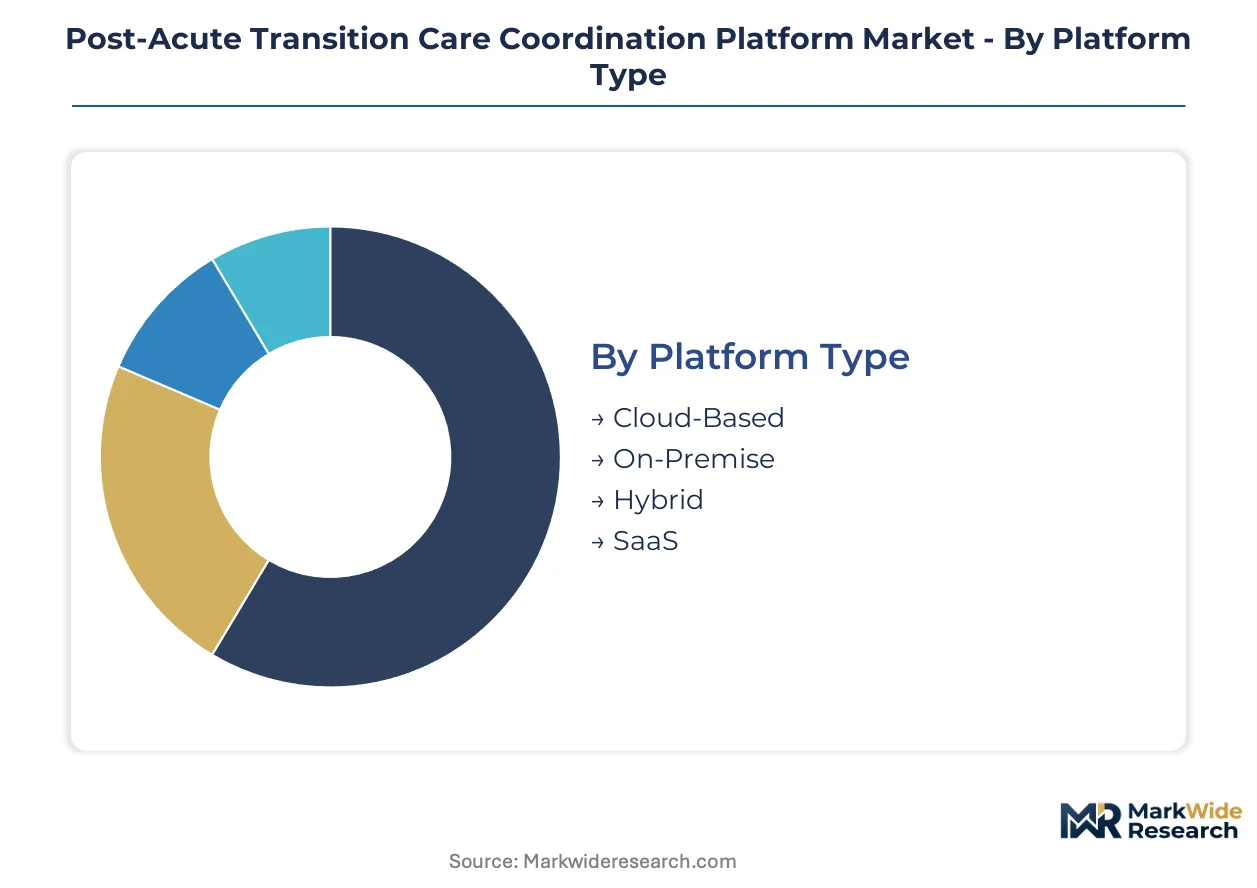
Segmentation in post-acute transition care coordination platforms reveals how procurement priorities diverge across infrastructure preferences, care delivery sites, and workflow integration requirements. Understanding these splits enables vendors to align development roadmaps with buyer readiness and regulatory pressure points.
Platform Type:
Cloud-based deployment dominates domestic procurement, while hybrid architectures find traction in export markets with stringent data residency mandates.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure barriers for independent home health agencies. Demand concentrates in urban Medicare corridors where readmission penalties drive rapid procurement cycles.
- On-Premise:Licensed software running on client-managed servers persists in health systems with legacy security protocols. Large Catholic networks and military health facilities mandate on-premise stacks for audit control.
- Hybrid:Split architectures keep PHI on local servers while routing analytics to cloud environments. Canadian provincial health authorities and German hospital networks favor this model for GDPR-equivalent compliance.
- SaaS:Subscription models with per-bed or per-episode pricing lower entry costs for rural hospice providers. Southeast Asian private hospital chains adopt SaaS to bypass IT staffing constraints.
Cloud-based platforms command the established base. The steepest expansion runs through hybrid deployments.
Care Setting:
Cost tier stratification separates enterprise-grade SNF implementations from lightweight hospice tools.
- Skilled Nursing Facilities:Comprehensive platforms managing ADT feeds, care plans, and quality metrics across 100+ bed facilities. SNFs in Florida and Texas invest heavily to secure hospital referral contracts under bundled payment models.
- Home Health Agencies:Mobile-first solutions with offline documentation for field nurses. California and New York home health networks drive volume for GPS-enabled visit verification.
- Rehabilitation Centers:Episode-specific tracking for joint replacement and cardiac recovery pathways. Outpatient rehab chains in the Midwest expand fastest as CMS tightens bundled payment timelines.
- Hospice Providers:Palliative-focused modules emphasizing family communication and bereavement workflows. Community-based hospices in the Pacific Northwest prioritize these for value-based insurance contracts.
Skilled nursing facilities anchor premium pricing. Rehabilitation centers are gaining share fastest as procedure volumes shift to outpatient settings.
User Role:
Application depth varies sharply—enterprise buyers demand cross-functional workflows while specialized roles drive modular adoption.
- Case Managers:Centralized dashboards for longitudinal patient tracking across acute-to-post-acute handoffs. Case managers in ACOs require attribution reconciliation tools that most platforms underserve.
- Discharge Coordinators:Real-time bed availability and referral routing interfaces. Hospital-employed coordinators in the Northeast represent the most concentrated buyer segment.
- Caregivers:Simplified mobile interfaces for medication adherence and symptom reporting. Family caregivers in Medicare Advantage plans increasingly access these through payer-sponsored programs.
- Social Workers:SDOH assessment tools and community resource directories. Medicaid-managed care organizations in Illinois and Ohio mandate social worker modules for network adequacy.
Case managers command platform design priorities. Caregiver-facing tools are expanding most quickly as payers assume deployment costs.
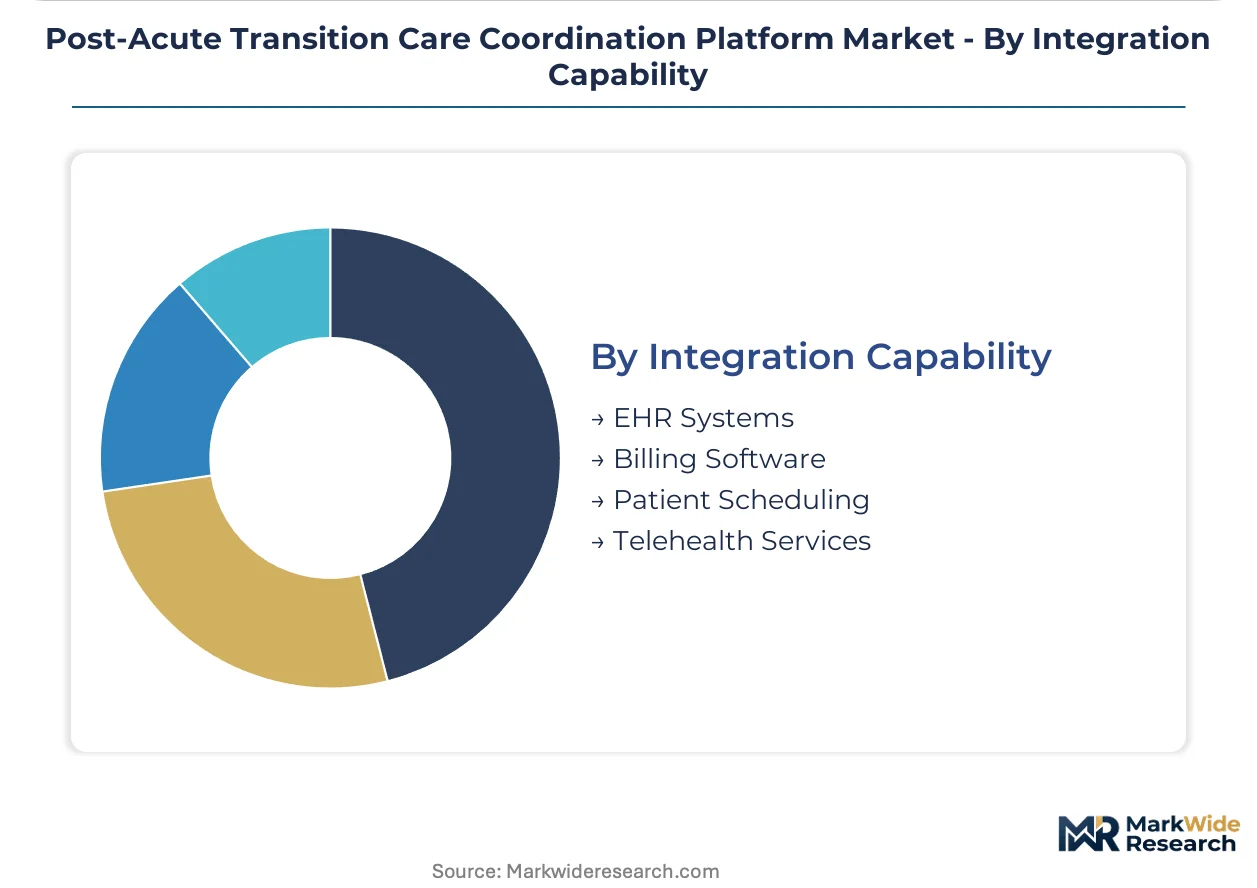
Integration Capability:
Margin concentration follows technical complexity—EHR integration captures premium pricing while scheduling modules commoditize.
- EHR Systems:Bidirectional HL7 FHIR APIs enabling seamless data exchange with Epic, Cerner, and MEDITECH environments. Health systems refuse procurement without demonstrated Epic integration.
- Billing Software:Automated claims scrubbing and prior authorization workflows. Revenue cycle management vendors bundle these capabilities, compressing standalone platform margins.
- Patient Scheduling:Calendar synchronization across multiple post-acute provider networks. Independent home health agencies treat this as table stakes rather than differentiator.
- Telehealth Services:Embedded video visits and remote patient monitoring data streams. Post-acute telehealth adoption accelerated after CMS made virtual visits reimbursable for SNF residents.
EHR integration anchors vendor pricing power. Telehealth services are climbing the fastest as hybrid care models normalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare readmission penalties and ONC interoperability mandates concentrate platform demand in the United States, while Germany and Japan advance through value-based care pilots. Canada and Australia follow with regional health authority procurement.
United States
The Medicare Hospital Readmissions Reduction Program penalizes excessive 30-day readmissions, compelling health systems to invest in bidirectional data exchange with post-acute partners. ONC Cures Act Final Rule enforcement accelerates vendor consolidation around FHIR-certified platforms. Florida and Texas SNFs deploy comprehensive platforms to secure hospital referral contracts under bundled payment arrangements.
Germany
Hospital discharge management reforms and Diagnosis-Related Group reimbursement adjustments drive investments in care transition documentation. The country's national healthcare regulator mandates standardized data exchange between acute hospitals and rehabilitation centers. Bavarian hospital networks pilot integrated platforms for post-acute handoffs to skilled nursing facilities.
Japan
Aging demographics and community-based care integration policies expand demand for home health coordination tools. The Ministry of Economy, Trade and Industry promotes digital health infrastructure standardization across prefectures. Tokyo and Osaka metropolitan areas lead platform adoption for hospital-to-home transitions under long-term care insurance reforms.
Canada
Provincial health authorities consolidate post-acute procurement under shared services organizations to reduce readmission costs. Health Canada enforces interoperability requirements for federal health funding eligibility. Ontario and British Columbia health networks deploy hybrid cloud platforms to meet data residency mandates while enabling real-time patient tracking.
Australia
My Health Record system integration requirements and hospital readmission reduction targets stimulate platform investments. The Therapeutic Goods Administration oversees clinical decision support modules within care coordination software. New South Wales and Victoria health districts prioritize cloud-based solutions for rural home health agency connectivity.
Post-Acute Transition Care Coordination Platform Market Competitive Landscape
Listed leaders compete with private specialists across interoperability certification and EHR integration depth. The vendor base consolidates around three tiers: enterprise cloud platforms with acute network relationships, skilled nursing facility data infrastructure specialists, and modular point-solution providers. Two strategic archetypes dominate: acute-to-post-acute bridge builders and post-acute workflow optimizers. M&A activity targets FHIR certification capabilities and regional referral network access.
Within the enterprise platform tier, WellSky and PointClickCare exemplify divergent anchoring strategies—one through acute hospital network integration, the other through skilled nursing facility data infrastructure dominance. Oracle Health occupies a position as a cloud architecture extender from enterprise acute systems into post-acute workflows. These three represent how scale, vertical focus, and technology heritage segment competitive positioning in a market where procurement committees centralize vendor negotiations and demand outcome guarantees.
| Leading Market Players |
|---|
| WellSky |
| PointClickCare |
| Oracle Health |
| Bamboo Health |
| Aidin |
| Dina |
| Trella Health |
| MatrixCare |
| CareCentrix |
| Others |
Pricing and Supply Chain Analysis
Ninety-day implementation timelines for FHIR-certified platforms compress procurement cycles and concentrate pricing power with vendors holding ONC certification credentials, while thin margins at rural home health agencies force aggressive SaaS bundling that reshapes downstream supplier relationships.
Pricing Analysis
Certification level under the ONC Cures Act Final Rule creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ONC-certified platforms commanding substantial premiums over uncertified alternatives. Cost compression in the economy tier is intensifying because rural home health agencies consolidate purchasing through GPOs. Hospital systems show least price sensitivity due to Medicare readmission penalty exposure, while independent hospice providers exhibit highest sensitivity to per-bed subscription costs.
Supply Chain Analysis
Just-in-time deployment preferences dominate cloud-native platform delivery, though strategic stockpiling of interoperability middleware persists among health systems with legacy EHR technical debt. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure provisioning anchored in domestic data centers to satisfy HIPAA requirements. The supply chain draws from specialized health informaticist labor pools, API gateway technologies, and EHR integration engines. Single-source vulnerability runs through Epic and Cerner integration certification pathways. Distribution runs through direct enterprise sales teams and health system GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face substitution pressure from modular point-solution providers decomposing monolithic care coordination suites into discrete, interoperable components that bypass lengthy procurement cycles.
For Market Incumbents: Shield referral network relationships by deepening Epic and Cerner integration certification investments before bundled payment models tighten further. Acquire FHIR implementation specialists to compress ONC approval timelines and freeze out modular competitors seeking anchor tenant status with hospital systems.
For New Entrants and Emerging Players: ONC certification fast-track programs offer the most viable entry vector for vendors targeting rehabilitation centers and home health agencies underserved by incumbent platform complexity. White-space concentrates in AI-enabled risk stratification modules and caregiver-facing mobile interfaces where payer sponsorship reduces customer acquisition costs.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vendor aggregation around interoperability credentials will compress the competitive set to FHIR-certified platforms with proven acute network access. Target acquisition archetypes include regional referral network data aggregators and specialized ADT feed analytics engines. The signal to watch is CMS ACO REACH model expansion velocity, which determines attribution and reconciliation capability premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Investment | ONC Cures Act compliance secures hospital procurement committee inclusion and referral network access. |
| Epic Integration Partnership | Seamless EHR data exchange commands premium pricing and locks out uncertified competitors. |
| Rehabilitation Center Module Launch | Episode-specific tracking captures bundled payment expansion in joint replacement and cardiac recovery. |
| AI Risk Stratification Acquisition | Machine learning ADT analytics enables proactive intervention triggers before clinical deterioration. |
| Geographic Expansion to Rural Networks | GPO-aggregated hospice and home health procurement bypasses capital constraints outside urban corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CMS reimbursement rulemaking archives, hospital procurement database extracts, and ONC certification registries. Primary interviews engaged care coordination platform executives, hospital discharge coordinators, skilled nursing facility IT directors, and health system supply chain managers. Secondary sources included GPO contract filings, Medicare cost report data, and interoperability standards documentation. Bottom-up segment sizing triangulates against top-down health IT expenditure models.
Segmentation dimensions modeled span platform deployment architecture, care setting type, user role functionality, and EHR integration depth across the analysis window. CAGRs derive from logistic adoption curves fitted to procurement cycle observations and regulatory compliance deadline clustering. Forecast inputs incorporate Medicare readmission penalty exposure matrices and bundled payment model expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained ONC enforcement pressure or accelerated CMS value-based reimbursement shifts would require recalibration. Forecasts reflect assumptions regarding interoperability mandate adherence timelines and health system consolidation velocity. Revision becomes warranted when FHIR R4 API adoption rates cross thresholds that eliminate uncertified vendor viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Medical IoT Software Market
Healthcare IT
Healthcare IT Services Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Patient Referral Management Software Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Epharmacy Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Global Orthopedic Software Market