
 IT-Enabled Healthcare Market | 2026-2036
IT-Enabled Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
IT-Enabled Healthcare Market Outlook
Subscription-based software-defined analytics is broadening what health systems purchase beyond perpetual licenses. Epic Systems Corporation leverages deep integration across clinical and revenue workflows to anchor large academic medical centers. Oracle Health competes aggressively on cloud infrastructure scale, while Philips Healthcare specializes in combining patient monitoring hardware with embedded AI diagnostics.
IT-enabled healthcare comprises digital infrastructure, software platforms, and connected devices that capture, transmit, and analyze clinical and operational data to support care delivery decisions; core systems must meet sub-second latency thresholds for real-time alerts and maintain uptime exceeding 99.9% for critical care applications. Electronic health records still occupy the largest value pool due to mandatory adoption, yet telemedicine solutions represent the fastest expansion path as reimbursement parity solidifies across payer contracts. Artificial Intelligence within the technology dimension attracts disproportionate R&D investment, though cloud computing underpins margin sustainability by converting capital expenditure into recurring operational outlays.
The FDA regulates clinical decision support software as medical devices under evolving guidance, while HIPAA governs data exchange architecture across US provider networks; the EU AI Act imposes risk-classification requirements on diagnostic algorithms that restrict market access for uncertified vendors. Stakeholders must track how converging compliance burdens in Europe and North America reshape vendor qualification timelines and procurement criteria.
Market Dynamics
Cloud infrastructure consolidation is compressing vendor margins while HIPAA interoperability mandates force architectural overhauls across hospital procurement cycles.
Growth Catalysts
- Interoperability Mandates:HIPAA information-blocking rules compel health systems to replace siloed EHR architectures with open APIs, triggering platform refresh cycles.
- AI Diagnostics:FDA breakthrough device designations for machine-learning algorithms accelerate clinical validation timelines and payer reimbursement negotiations.
- Germany:Integrated care legislation (§140a SGB V) drives consolidation among regional hospital alliances, concentrating demand for unified analytics platforms.
Market Restraints
- Cloud Concentration Risk:Three hyperscalers dominate health system infrastructure, creating single-point-of-failure exposure for critical care uptime requirements.
- Cybersecurity Input Costs:Zero-trust architecture mandates inflate implementation budgets by requiring continuous authentication layers across legacy device fleets.
- EU AI Act Friction:Risk-classification requirements for diagnostic algorithms restrict market access for vendors lacking notified body certification.
Strategic Opportunities
- Rural Telemedicine:FCC broadband subsidy programs unlock underpenetrated geographies where specialist scarcity drives asynchronous consultation demand.
- Edge-AI Convergence:Ambulatory surgical centers deploy on-device inference chips to reduce cloud latency for real-time intraoperative guidance.
- Remote Patient Monitoring:CMS reimbursement codes for continuous glucose and cardiac telemetry expand home-based revenue pools beyond acute settings.
Industry Challenges
- Interoperability Engineering Talent:Health systems compete with fintech and defense sectors for FHIR-standard developers, inflating compensation premiums.
- Legacy EHR Integration:Custom interface engines consume implementation timelines as hospitals maintain decades-old database schemas alongside modern APIs.
- Clinical Workflow Redesign:Alert fatigue from predictive algorithms forces operational investment in human-factors validation before deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT-Enabled Healthcare Market |
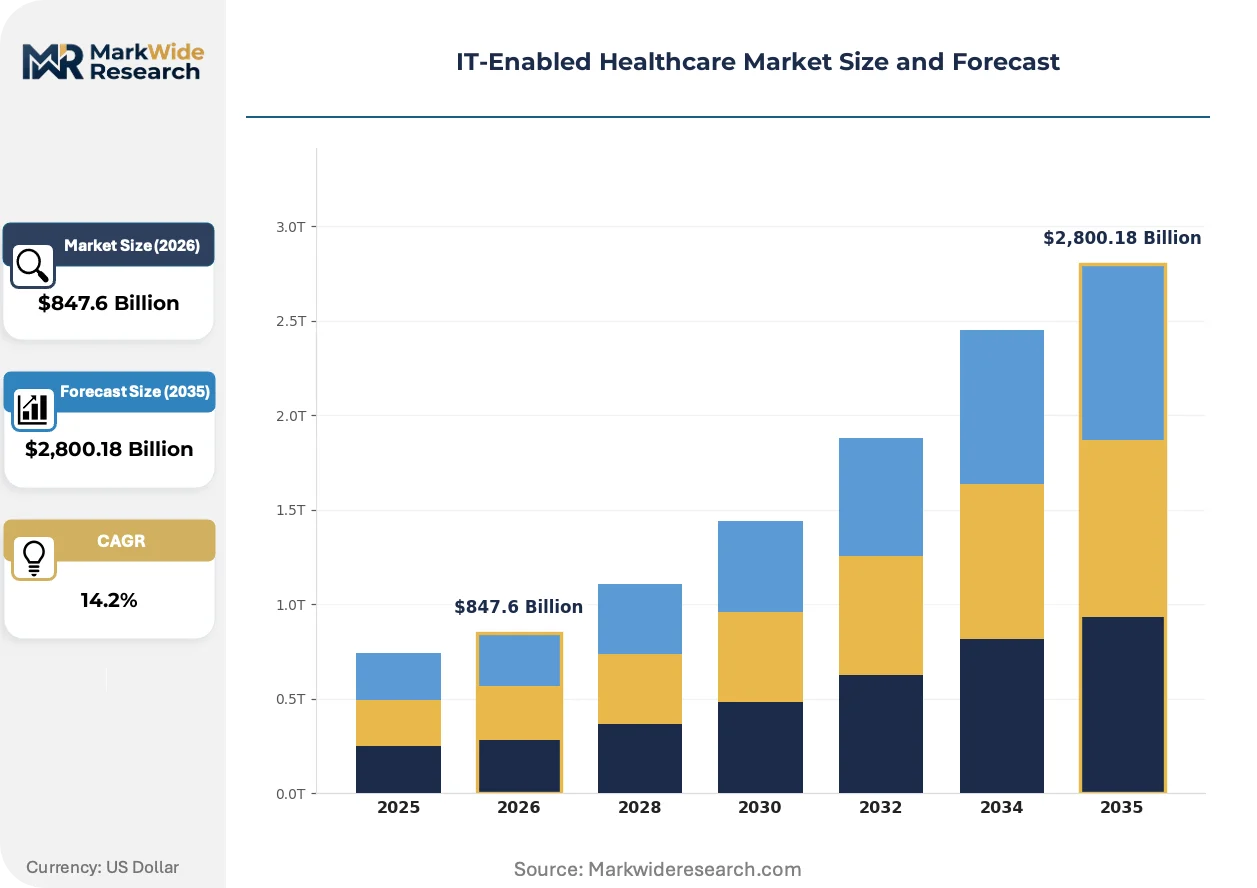
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,800.18 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Telemedicine Solutions, Patient Portals, Workflow Management Systems End User: Hospitals, Physician Practices, Diagnostic Laboratories, Home Healthcare Providers Technology: Artificial Intelligence, Blockchain, Cloud Computing, IoT-enabled Devices Application: Remote Patient Monitoring, Health Information Exchange, Appointment Scheduling, Revenue Cycle Management |
| Companies Covered | Epic Systems Corporation, Oracle Health, Cerner, GE Healthcare, Philips Healthcare, Accenture, Cognizant, Microsoft, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT-Enabled Healthcare Market Strategic Shifts
Real-time data architectures are displacing batch-processed analytics, while regulatory fragmentation between FDA and EU AI Act compliance paths forces dual-track development investments.
Edge computing nodes with embedded GPUs are electrifying point-of-care diagnostics by enabling sub-100-millisecond inference for sepsis prediction and stroke detection algorithms. Emergency departments at academic medical centers deploy these units to bypass cloud round-trips during network congestion. The technology is electrifying competitive positioning for vendors that can bundle hardware-software latency guarantees into procurement contracts.
EU AI Act risk-tier classification is bifurcating vendor development roadmaps, with high-risk diagnostic algorithms requiring conformity assessments that add months to commercialization timelines. Manufacturers serving both markets now maintain parallel documentation systems. European hospital procurement committees increasingly require CE-marked AI modules, filtering out US-only FDA clearances from shortlists.
Subscription-based analytics procurement is replacing perpetual license models as health systems prioritize operational expenditure predictability over capital ownership. Regional hospital alliances negotiate enterprise-wide SaaS contracts that bundle training and model retraining services. This shift concentrates buying power among integrated delivery networks in Germany and the US, squeezing standalone software vendors into niche specialty modules.
IT-Enabled Healthcare Market Segmentation
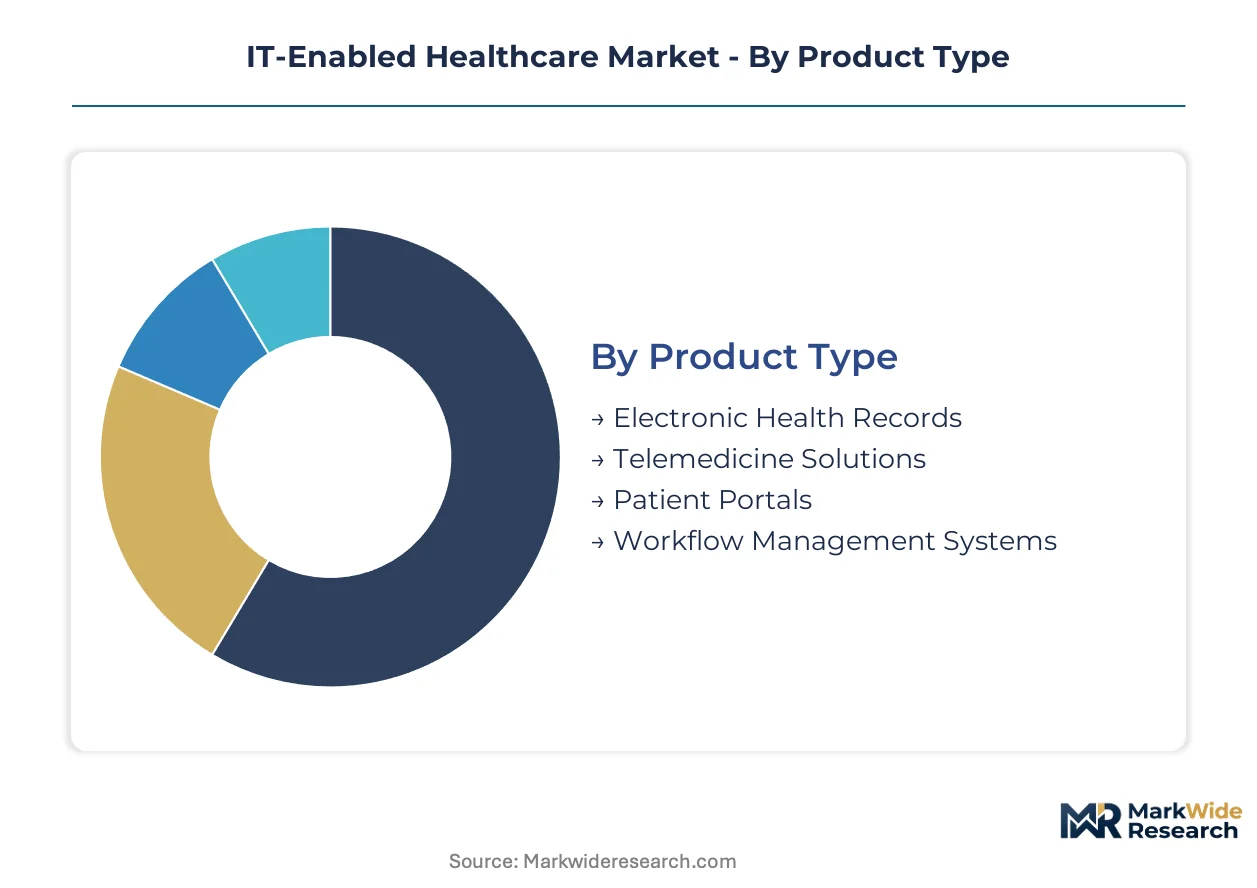
IT-enabled healthcare procurement varies sharply by infrastructure maturity and reimbursement pathways. Capital allocation decisions hinge on whether health systems prioritize core system replacement or incremental digital overlays.
Product Type:
Electronic Health Records demand the heaviest upfront capital deployment, consuming multi-year implementation budgets and specialized integration labor.
- Electronic Health Records:Core clinical data repositories integrating patient history, medication management, and order entry across inpatient and ambulatory settings. Epic Systems and Oracle Health anchor large hospital networks in the United States and Germany through deep workflow integration mandates.
- Telemedicine Solutions:Real-time video consultation platforms with asynchronous messaging and remote diagnostic peripherals. Rural health systems in Texas and Bavaria expand deployment fastest where specialist scarcity meets FCC broadband subsidies and German integrated care legislation.
- Patient Portals:Consumer-facing interfaces for appointment scheduling, lab result access, and secure messaging. HIPAA interoperability rules and GDPR compliance requirements drive standardization investments.
- Workflow Management Systems:Operational orchestration tools for bed management, staffing optimization, and supply chain coordination. Smaller physician practices adopt these as SaaS bundles to avoid capital expenditure.
Electronic Health Records absorb the bulk of installed capacity; Telemedicine Solutions is expanding most quickly.
End User:
Procurement scale and contract complexity diverge dramatically across care settings, with acute facilities commanding enterprise-wide platform negotiations.
- Hospitals:Multi-facility health systems with 24/7 critical care uptime requirements and sub-second latency thresholds for clinical decision support. Academic medical centers in Massachusetts and North Rhine-Westphalia drive demand for AI-embedded diagnostics and cloud-native EHR architectures.
- Physician Practices:Ambulatory settings with lighter infrastructure needs and higher price sensitivity to per-provider licensing costs. Federally qualified health centers in California leverage HRSA funding for telemedicine expansion.
- Diagnostic Laboratories:High-volume testing facilities requiring LIS-EHR interoperability and automated result routing. Quest Diagnostics and LabCorp scale influence vendor roadmaps for HL7 FHIR connectivity.
- Home Healthcare Providers:Post-acute and chronic care agencies deploying remote patient monitoring for CMS-reimbursed conditions. Medicare Advantage penetration in Florida accelerates device procurement for cardiac and glucose telemetry.
Hospitals command the largest contract values; Home Healthcare Providers show the steepest expansion trajectory as reimbursement shifts toward value-based models.
Technology:
Margin sustainability and implementation risk vary by whether technologies convert capital expenditure to recurring operational outlays.
- Artificial Intelligence:Machine learning algorithms for diagnostic imaging, clinical decision support, and operational forecasting. FDA breakthrough device designations and EU AI Act risk-tier classifications create divergent commercialization pathways for vendors.
- Cloud Computing:Hyperscaler infrastructure delivering elastic compute, storage, and disaster recovery with 99.9% uptime SLAs. AWS, Azure, and Google Cloud dominate hospital procurement in the United States, Germany, and United Kingdom.
- Blockchain:Distributed ledger applications for pharmaceutical supply chain integrity and credential verification. Pilot deployments concentrate among specialty pharmacy networks and state-level Medicaid programs.
- IoT-enabled Devices:Connected sensors for continuous vital sign monitoring and environmental tracking in acute and home settings. Bluetooth Low Energy and 5G modules enable battery-efficient form factors.
Cloud Computing underpins the majority of new deployments; Artificial Intelligence attracts disproportionate R&D investment despite regulatory friction.
Application:
Revenue model stability depends on whether applications generate direct reimbursement or operational cost avoidance.
- Remote Patient Monitoring:Continuous data capture from wearable and implantable devices for chronic disease management. CMS reimbursement codes for cardiac and pulmonary monitoring unlock predictable revenue streams for health systems in Texas and Baden-Württemberg.
- Revenue Cycle Management:Claims processing, prior authorization automation, and denial management workflows. Physician practices in Illinois prioritize these tools as payer complexity escalates.
- Health Information Exchange:Cross-organizational data sharing networks enabling care coordination and population health analytics. State-level HIE mandates in New York and California drive public infrastructure investment.
- Appointment Scheduling:Consumer self-service portals with automated reminders and waitlist optimization. Retail health clinics in Ohio deploy these to match primary care access demand.
Revenue Cycle Management retains the deepest incumbent penetration; Remote Patient Monitoring is gaining share fastest as reimbursement parity solidifies across payer contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors health IT deployment density, hosting Epic Systems implementation centers and Oracle Health cloud migration hubs that serve academic medical centers across Massachusetts and neighboring states.
United States
Hospital networks in Texas and California accelerate cloud-based EHR replacement cycles under HIPAA interoperability mandates. FCC broadband subsidies unlock rural telemedicine expansion in the Mountain West. The Mayo Clinic in Rochester, Minnesota drives demand for AI-embedded diagnostic platforms through its specialized care referral network.
Germany
Regional hospital alliances in North Rhine-Westphalia consolidate procurement under §140a SGB V integrated care legislation. The EU AI Act risk-classification requirements reshape vendor certification timelines for diagnostic algorithms. Berlin-Brandenburg health clusters deploy unified analytics platforms across Charité university hospital networks.
United Kingdom
NHS England's Federated Data Platform mandates force architectural standardization across integrated care systems. GDPR compliance investments concentrate in London health tech corridors. Manchester's digital health cluster attracts NHSX procurement for population health analytics.
Japan
Metropolitan hospital networks in Tokyo and Osaka deploy cloud-native EHR architectures under PMDA guidance on clinical decision support software. METI subsidies accelerate edge-AI adoption in rural prefectures facing specialist shortages. Nagoya's medical device manufacturing belt integrates IoT-enabled monitoring into hospital procurement contracts.
India
Apollo Hospitals and Max Healthcare in Delhi-NCR and Mumbai drive EMR standardization across multi-city networks. CDSCO digital health guidelines create compliance benchmarks for diagnostic algorithm deployment. Bengaluru's health tech startup corridor attracts venture funding for telemedicine platforms serving tier-2 and tier-3 cities.
IT-Enabled Healthcare Market Competitive Environment
Capital-heavy infrastructure providers compete with asset-light software specialists for health system procurement contracts. The market structures around three tiers: hyperscale cloud platforms anchoring backend architecture, integrated EHR vendors controlling clinical workflow integration, and boutique AI diagnostic shops filling specialty modules. Consolidation accelerates through strategic partnerships between hardware manufacturers and cloud providers, while vertical integration into patient monitoring devices creates captive demand channels.
Within the integrated platform tier, Epic Systems Corporation and Oracle Health occupy positions as anchor vendors for large academic medical centers, exemplifying divergent strategies around deep workflow embedding versus cloud infrastructure scale. Philips Healthcare represents the hardware-software convergence archetype, bundling monitoring devices with embedded analytics. These three companies illustrate how procurement power concentrates among vendors that can span clinical, operational, and infrastructure domains under unified contracting.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| Cerner |
| GE Healthcare |
| Philips Healthcare |
| Accenture |
| Cognizant |
| Microsoft |
| IBM |
| Others |
Value Chain & Pricing Dynamics
HIPAA interoperability mandates gate qualified supply access for EHR vendors seeking premium-tier hospital contracts, compressing margins for uncertified platforms while concentrating pricing power among Epic Systems and Oracle Health. Cloud infrastructure hyperscalers extract escalating compute fees that feed back into SaaS subscription pricing, forcing regional hospital alliances toward enterprise-wide bundling.
Pricing Analysis
Uptime-guarantee pricing anchors hospital procurement decisions, with 99.9% SLA tiers commanding 40-60% premiums over standard reliability contracts. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with AI-embedded diagnostics from community hospitals with basic cloud EHR modules. Cost compression in mid-tier subscriptions is intensifying because AWS, Azure, and Google Cloud negotiate escalating egress fees. Federally qualified health centers exhibit highest price sensitivity due to HRSA funding constraints, while integrated delivery networks in Germany and Massachusetts demonstrate lowest sensitivity through consolidated enterprise bargaining.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale buyer demand from academic medical centers and regional alliances, bypassing distribution intermediaries for EHR and AI diagnostic platforms. Manufacturing concentration centers on the United States for FDA-cleared software development, Germany for EU AI Act conformity assessment infrastructure, and India for telemedicine platform engineering talent. GPU chipsets for edge-AI inference, FHIR-standard middleware, and 5G IoT modules constitute critical input dependencies. Single-source vulnerability in NVIDIA GPU supply creates procurement bottlenecks for real-time diagnostic algorithms. Distribution runs through GPO contracts and state-level HIE procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure consolidation functions as a forced exit mechanism, squeezing standalone EHR vendors without hyperscaler partnerships or deep workflow integration. Compliance burden divergence between FDA and EU AI Act certification timelines accelerates attrition among undercapitalized AI diagnostic developers.
For Market Incumbents: Deploy backward integration into edge-AI hardware manufacturing to bypass cloud latency penalties and capture telemetry revenue from remote patient monitoring devices. Epic Systems and Oracle Health should deepen FHIR-standard API control to lock out modular competitors, while Philips Healthcare must accelerate CE-marking investments before EU AI Act high-risk algorithm deadlines eliminate US-only FDA clearances from European procurement shortlists.
For New Entrants and Emerging Players: FCC broadband subsidies in Texas and Mountain West states open a window for asynchronous telemedicine platforms targeting specialist-scarce rural counties. Target ambulatory surgical centers with sub-100-millisecond edge inference chips for intraoperative guidance, where incumbent EHR vendors lack hardware-software bundling capability. Pursue white-label partnerships with regional hospital alliances in Germany seeking §140a SGB V compliant analytics platforms without Epic or Oracle lock-in.
For Investors and Strategic Acquirers: FDA breakthrough device designation announcements are the leading indicator that AI diagnostic startups have compressed clinical validation timelines sufficiently to negotiate payer reimbursement. Position acquisitions around boutique imaging algorithm shops with EU notified body relationships, as CE-marking capability scarcity creates acquisition premiums. Monitor CMS reimbursement code expansions for continuous glucose and cardiac telemetry as signals that home-based revenue pools are shifting from pilot to scale deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU AI Act high-risk classification requires notified body assessment before German hospital procurement committees add vendors to shortlists. |
| Hospital System Partnership | Regional alliances in North Rhine-Westphalia consolidate analytics procurement under §140a SGB V integrated care legislation mandates. |
| Software Companion Development | FDA breakthrough device designations for machine-learning algorithms accelerate clinical validation timelines and payer reimbursement negotiations. |
| Reimbursement Strategy | CMS remote patient monitoring codes for cardiac and glucose telemetry unlock predictable revenue streams beyond acute care settings. |
| Strategic Partnership | Hyperscaler alliances with AWS, Azure, or Google Cloud convert capital expenditure into recurring operational outlays for margin sustainability. |
Study Parameters
Multi-period observation of hospital procurement cycle timing, EHR implementation completion rates, and AI diagnostic FDA submission volumes anchored the trend analysis, supplemented by interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and cloud infrastructure procurement officers. Primary fieldwork combined with secondary validation against CMS Medicare reimbursement data, hospital procurement databases, SEC filings from publicly traded health IT vendors, and EU AI Act implementation guidance documents. Bottom-up segment sizing triangulated against top-down macro healthcare IT expenditure estimates.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework, with additional stratification by regional regulatory cluster and infrastructure maturity tier. CAGRs were derived from fitted growth curves calibrated to historical adoption velocity and policy implementation schedules. Cloud infrastructure capex disclosures from hyperscalers, FCC broadband subsidy allocation patterns, and CDSCO digital health guideline development timelines fed into forecast sensitivity testing.
The model assumes a particular technology adoption path; alternative pathways for edge-AI inference chips displacing cloud-based diagnostic algorithms would alter the outlook for latency-sensitive clinical decision support. Forecasts embed assumptions regarding HIPAA interoperability rule enforcement intensity and EU AI Act notified body capacity expansion. Practitioners should monitor FDA breakthrough device designation velocity, CMS remote monitoring reimbursement code additions, and hyperscaler health-vertical partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Non-Clinical Homecare Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Operating Room Software Market
Healthcare IT
E-Prescribing Systems Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Wearable Biosensors Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Global Back-End Revenue Cycle Management Market