
 Clinical Practice Management Software Market | 2026-2036
Clinical Practice Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Practice Management Software Market Outlook
Multi-source vendor strategies is expanding across health systems seeking interoperability without single-platform lock-in. Epic anchors its position through deep EHR integration across academic medical centers. Athenahealth competes via cloud-native architecture and revenue-cycle specialization. Cerner Corporation sustains scale through broad hospital network penetration and federal contract relationships.
Clinical Practice Management Software comprises integrated digital systems that automate scheduling, billing, claims processing, and patient registration, typically operating through HL7 FHIR-compliant data exchange protocols to ensure interoperability with electronic health records. Cloud-based deployment dominates new installations due to lower capital expenditure and automatic regulatory updates. Artificial Intelligence and EHR Integration segments capture disproportionate investment as health systems prioritize automated coding accuracy and seamless data flow. Specialty Clinics represent the fastest-growing end-user category, driven by procedure-specific workflow customization needs.
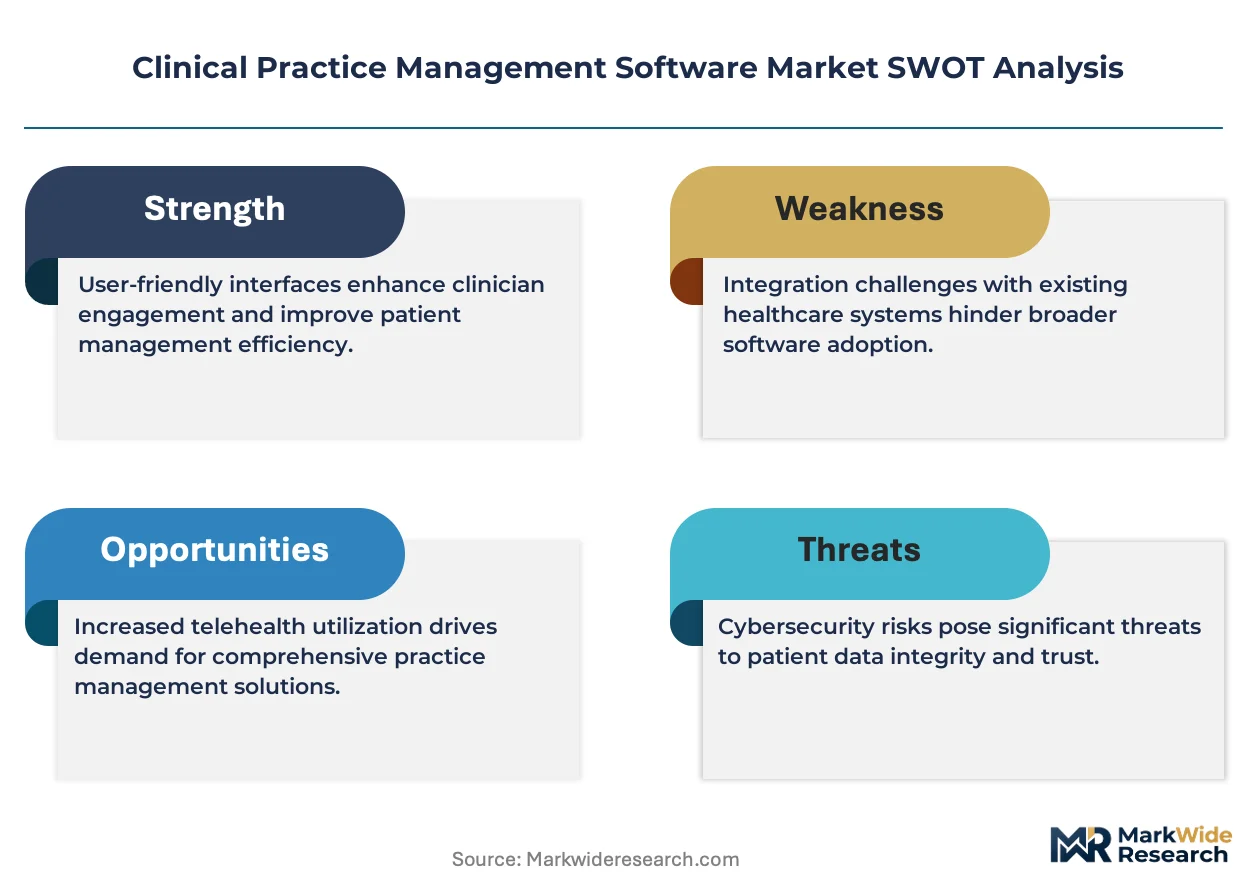
FDA 21 CFR Part 820 quality system requirements and ONC Health IT Certification Program standards shape product development timelines and market access eligibility in the United States. HIPAA security rule compliance remains a non-negotiable baseline for any vendor serving covered entities. Stakeholders must weigh interoperability mandates against the operational friction of migrating legacy on-premise installations.
Market Dynamics
Interoperability mandates from the ONC and FDA are forcing vendors to rebuild core architectures around HL7 FHIR standards, compressing development timelines while opening pathways for modular, best-of-breed procurement strategies.
Growth Catalysts
- Cloud Migration:Specialty clinics in Germany and India are abandoning on-premise servers for SaaS platforms that eliminate capital expenditure and automate HIPAA compliance updates.
- 21 CFR Part 820:FDA quality system requirements are accelerating vendor consolidation as smaller players lack resources to maintain device-level documentation standards.
- Revenue Cycle Automation:AI-powered coding engines are reducing claim denial rates for ambulatory surgery centers, creating measurable ROI that shortens sales cycles.
Market Restraints
- Legacy Data Silos:Decades of proprietary EHR formats in US academic medical centers create extraction costs that rival new software licenses.
- Concentrated Cloud Infrastructure:AWS, Azure, and Google Cloud dominate health system hosting, exposing practices to single-provider pricing power and outage risk.
- Substitution by EHR Native Modules:Epic and Cerner are bundling practice management functions into base EHR contracts, narrowing standalone vendor addressable market.
Strategic Opportunities
- Rural Health Networks:Federally Qualified Health Centers in Texas and Mississippi lack integrated billing systems, creating whitespace for cloud-native entrants with Medicaid specialization.
- Behavioral Health Integration:Convergence of mental health and primary care workflows demands scheduling platforms that handle split billing across CPT code categories.
- India's Ayushman Bharat:The national health insurance scheme is digitizing 150,000 health and wellness centers, requiring practice management software with Hindi interface and Aadhaar integration.
Industry Challenges
- FHIR Implementation Talent Scarcity:Health IT departments lack engineers proficient in SMART on FHIR app development, delaying interoperability roadmaps by 12-18 months.
- ONC Certification Timelines:The 21st Century Cures Act information blocking rules require costly third-party testing that consumes 6-9 months of product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Practice Management Software Market |
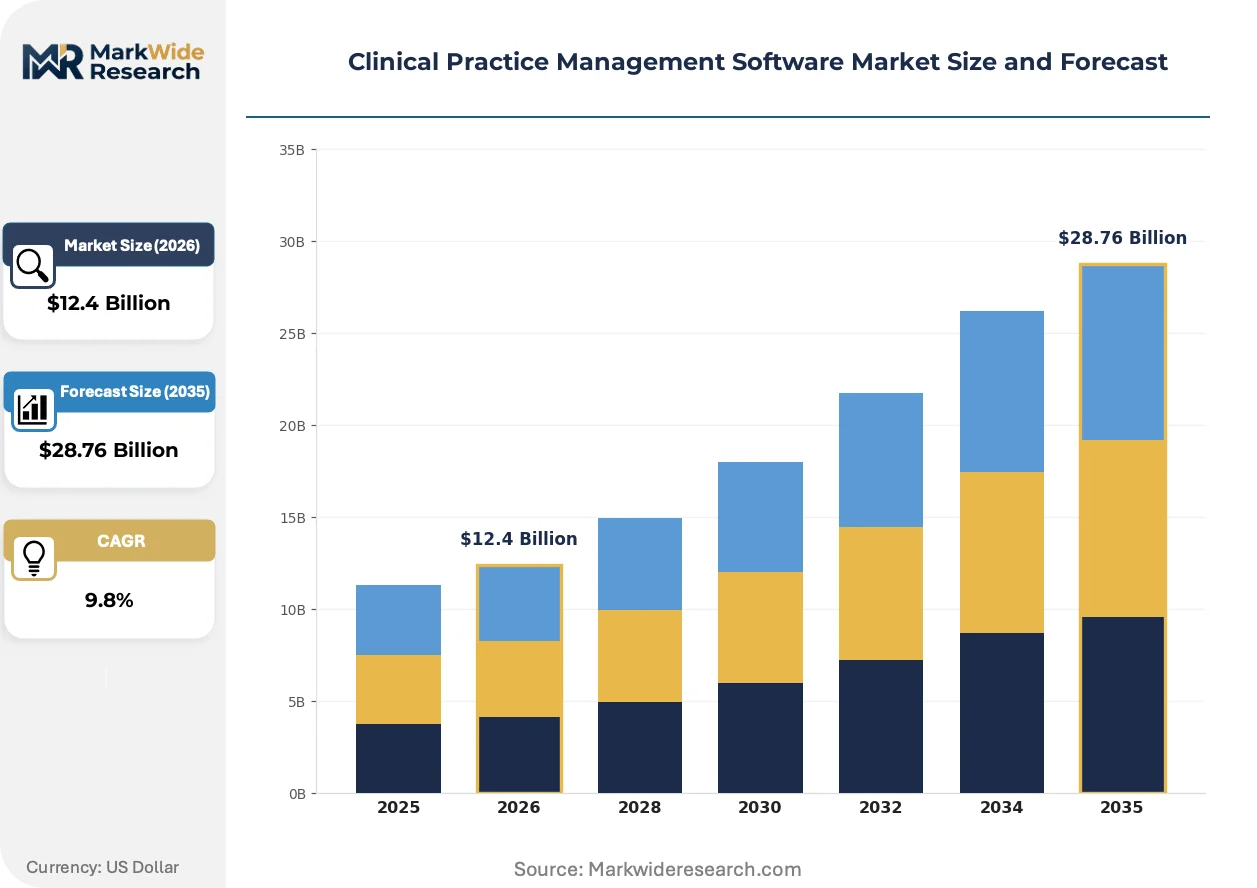
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.76 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, Mobile End User: Hospitals, Specialty Clinics, Primary Care Providers, Laboratories Technology: Artificial Intelligence, Machine Learning, Telehealth Solutions, EHR Integration Deployment Model: Single Tenant, Multi-Tenant, SaaS, Open Source |
| Companies Covered | Athenahealth, Allscripts, eClinicalWorks, Cerner Corporation, Epic, NextGen Healthcare, Greenway Health, CareCloud, Kareo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Practice Management Software Market Strategic Shifts
Artificial intelligence is rewiring core workflows across revenue cycle, clinical documentation, and patient engagement, while regulatory pressure on data exchange is flattening competitive moats around proprietary formats.
Generative AI is integrating into ambient clinical documentation systems that transcribe provider-patient encounters in real time. Multi-specialty group practices in Florida and Arizona are piloting these tools to reduce after-hours charting burden. The technology is integrating previously separate documentation and coding workflows, compressing the revenue cycle from days to hours.
EU AI Act risk classification rules are imposing conformity assessment requirements on clinical decision support features within practice management platforms. Vendors selling into France and Germany must now maintain technical documentation and human oversight protocols for algorithmic billing recommendations. Small and mid-size software firms are responding by stripping AI features from EU deployments or pursuing CE marking through notified body partnerships.
Subscription fatigue among independent physician practices is fragmenting procurement into unbundled point solutions. Buyers in California and New York are assembling scheduling, billing, and telehealth from separate vendors rather than accepting integrated suites. This pattern is most visible in concierge medicine and direct primary care models where owners prioritize workflow customization over administrative consolidation.
Clinical Practice Management Software Market Segmentation
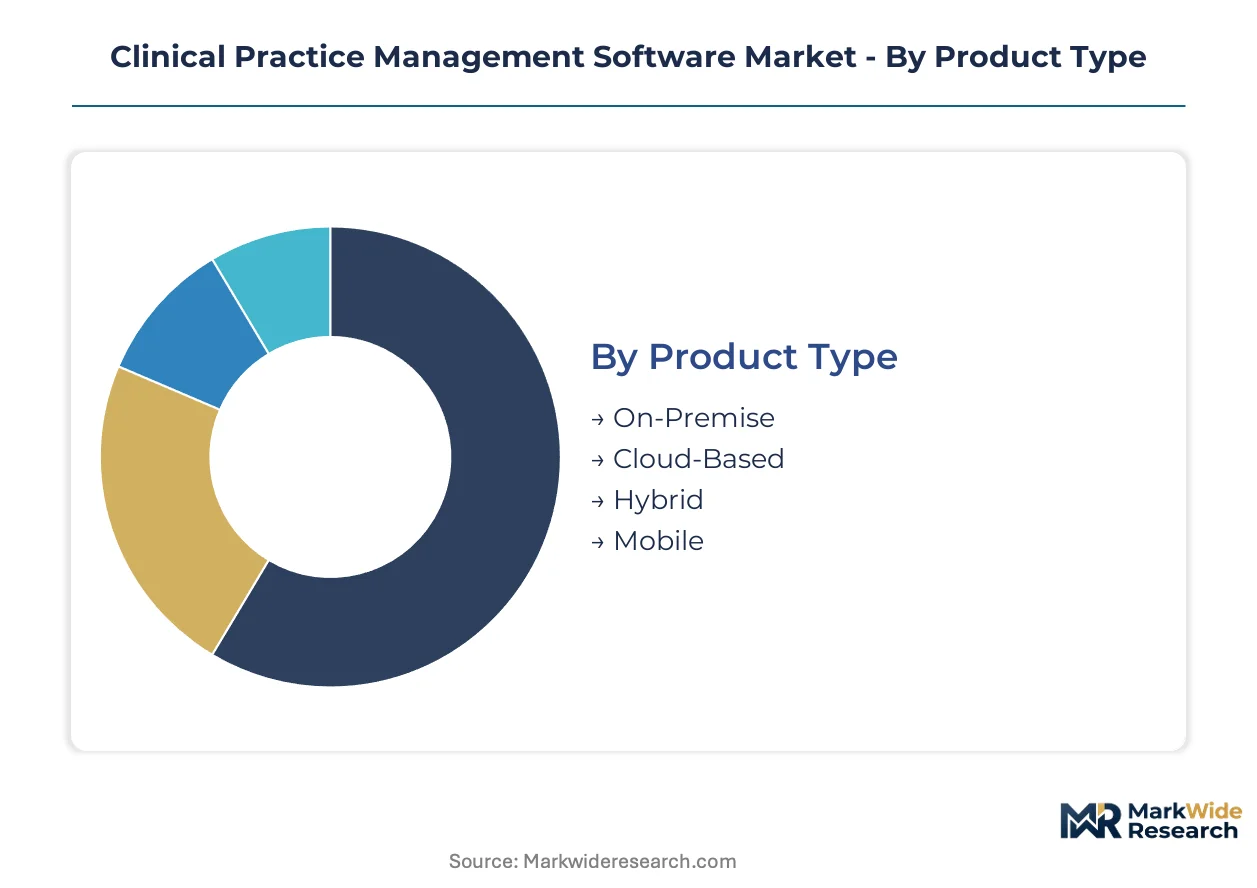
Clinical Practice Management Software vendors architect product portfolios around deployment flexibility, end-user workflow complexity, and interoperability depth. Segment boundaries increasingly blur as cloud-native platforms absorb AI capabilities and EHR vendors bundle adjacent functions.
Product Type:
Integration depth varies sharply: standalone installations demand heavy IT infrastructure, while cloud and mobile variants embed directly into broader health system architectures.
- On-Premise:Legacy server installations requiring dedicated hardware maintenance and internal security patching. Academic medical centers in the United States retain these systems due to Epic and Cerner integration dependencies and legacy data retention policies.
- Cloud-Based:Browser-accessible platforms with automatic HIPAA compliance updates and API-first architectures. Specialty clinics in Germany and India favor these for zero capital expenditure and HL7 FHIR-native interoperability.
- Hybrid:Split architectures keeping sensitive billing data on-premise while routing scheduling through cloud interfaces. Rural health networks in Texas deploy these to balance Medicaid audit requirements with telehealth connectivity.
- Mobile:Native iOS and Android applications for point-of-care scheduling and charge capture. Direct primary care practices in California adopt these for concierge workflow flexibility.
Cloud-Based leads volumes today; Mobile is gaining share fastest.
End User:
Procurement complexity scales with organizational size and reimbursement mix, from single-physician practices to multi-hospital IDNs.
- Hospitals:Enterprise-grade installations managing thousands of daily encounters across emergency, inpatient, and ambulatory settings. These systems must integrate with revenue cycle management and supply chain modules.
- Specialty Clinics:Procedure-focused platforms handling ASC scheduling, prior authorization automation, and implant inventory tracking. Ambulatory surgery centers in Florida and Arizona drive disproportionate investment here due to high claim denial sensitivity.
- Primary Care Providers:Patient-centered medical home platforms emphasizing preventive care registries and Medicare wellness visit workflows. Federally Qualified Health Centers in Mississippi require Medicaid eligibility verification integration.
- Laboratories:Specimen tracking and results-delivery systems with LIS interoperability and patient portal connectivity. Reference labs prioritize automated prior authorization for molecular diagnostics.
Specialty Clinics leads volumes today; Primary Care Providers is expanding most quickly.
Technology:
Capability layering determines pricing tiers and implementation timelines, with AI and ML features commanding premium positioning.
- Artificial Intelligence:Generative documentation engines and predictive no-show algorithms. EU AI Act conformity requirements are forcing CE marking investments for vendors selling into France and Germany.
- Machine Learning:Pattern recognition for claim denial prediction and revenue cycle optimization. These modules require 6-12 months of client-specific training data.
- Telehealth Solutions:Embedded video visits with automated coding for virtual check-ins and remote patient monitoring. Behavioral health integration demands split billing across CPT code categories.
- EHR Integration:HL7 FHIR-compliant data exchange with Epic, Cerner, and athenahealth ecosystems. SMART on FHIR app development talent scarcity delays implementations by 12-18 months.
EHR Integration leads volumes today; Artificial Intelligence shows the steepest expansion trajectory.
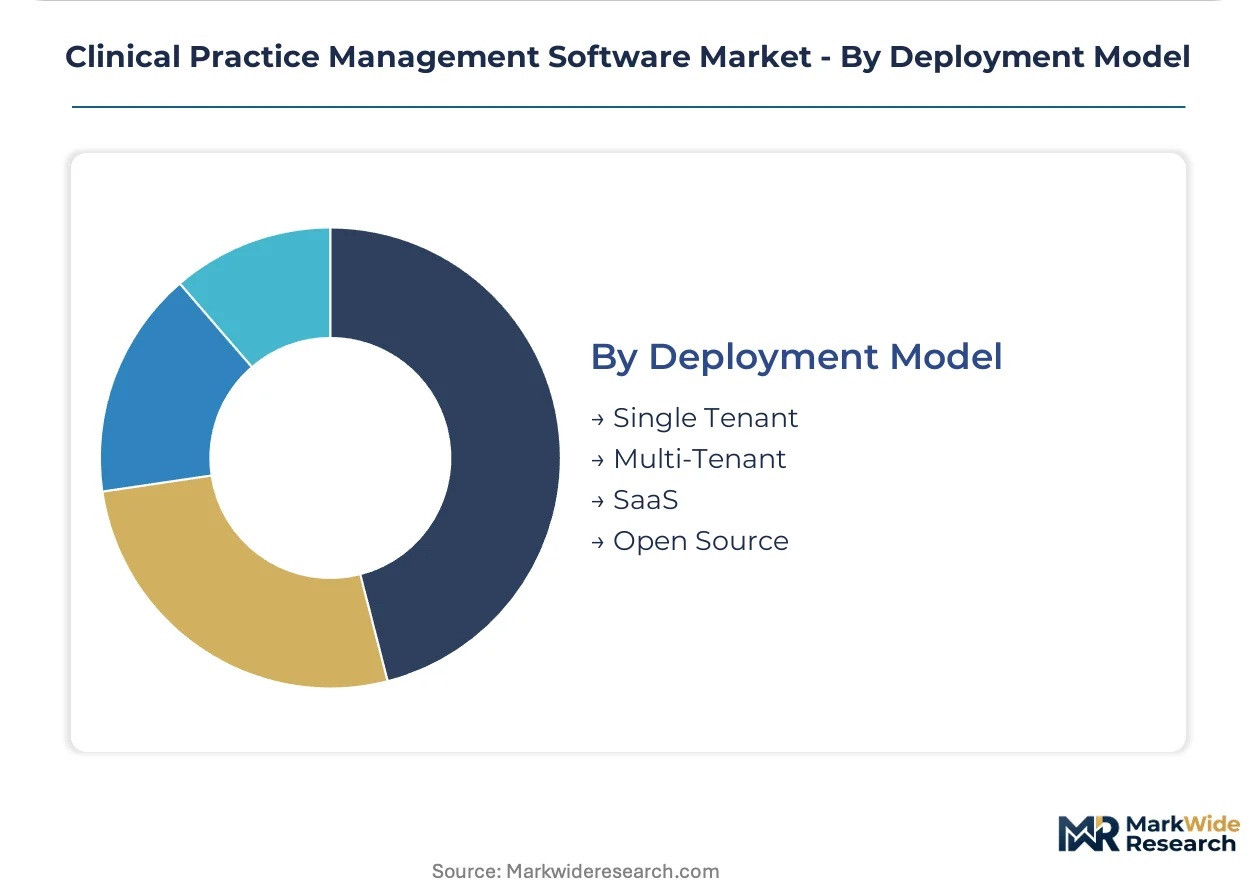
Deployment Model:
Infrastructure tenancy choices reflect data sovereignty requirements and vendor consolidation strategies.
- Single Tenant:Dedicated instance hosting for maximum customization and isolation. Large hospital systems in the United States demand these for HIPAA audit trail control.
- Multi-Tenant:Shared infrastructure with tenant-specific data partitioning. Lower per-seat costs attract independent physician associations.
- SaaS:Subscription pricing with automatic feature updates and regulatory compliance patches. India's Ayushman Bharat digitization initiative requires Hindi interface and Aadhaar integration capabilities.
- Open Source:Community-developed platforms with optional commercial support. These appeal to cost-constrained community health centers willing to self-maintain.
SaaS leads volumes today; Open Source is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors software innovation for clinical practice management, with academic medical centers driving HL7 FHIR adoption and cloud migration reshaping procurement patterns across concentrated metropolitan clusters.
United States
Federally Qualified Health Centers in Texas and Mississippi demand Medicaid-specialized billing systems, while the ONC 21st Century Cures Act information blocking rules compress vendor certification timelines. Epic and Cerner integration dependencies in academic medical centers sustain hybrid deployment models despite cloud migration pressure.
Germany
Specialty clinics in Bavaria and North Rhine-Westphalia favor zero-capital-expenditure SaaS platforms with automatic GDPR compliance updates. The EU AI Act imposes conformity assessment requirements on algorithmic billing features, forcing CE marking investments from vendors serving Frankfurt and Munich hospital networks.
India
Ayushman Bharat digitization of 150,000 health and wellness centers drives demand for Hindi-interface practice management software with Aadhaar integration. Karnataka and Telangana health tech clusters in Bangalore and Hyderabad are piloting cloud-native platforms for rural primary care connectivity.
United Kingdom
NHS England interoperability mandates accelerate HL7 FHIR adoption across London and Greater Manchester integrated care systems. GDPR and NHS Digital assurance frameworks shape procurement requirements, with private equity-backed specialty clinic chains in the Southeast driving SaaS subscription growth.
Canada
Provincial health authority consolidation in Ontario and British Columbia creates enterprise procurement opportunities for cloud-based scheduling and billing platforms. Health Canada medical device regulations intersect with software-as-a-medical-device guidance, extending vendor compliance timelines for AI-powered coding engines.
Clinical Practice Management Software Market Competitive Environment
Global majors compete with regional champions across interoperability depth and revenue-cycle specialization, producing a tiered structure where EHR-integrated suites face unbundled point solutions. Consolidation pressure concentrates around FDA 21 CFR Part 820 compliance costs and ONC certification timelines. Three archetypes dominate: academic medical center anchor platforms, cloud-native ambulatory specialists, and revenue-cycle pure-plays. M&A activity targets FHIR engineering talent and Medicaid billing expertise, while strategic partnerships with AWS and Azure accelerate multi-tenant infrastructure deployment.
Within the EHR-integrated tier, Epic and Cerner Corporation exemplify scale-driven positioning through deep academic medical center penetration and federal contract relationships. Athenahealth occupies a cloud-native position, representing the revenue-cycle specialization archetype with browser-accessible architecture. These three entities anchor competitive dynamics as health systems weigh single-platform consolidation against multi-vendor interoperability strategies.
| Leading Market Players |
|---|
| Athenahealth |
| Allscripts |
| eClinicalWorks |
| Cerner Corporation |
| Epic |
| NextGen Healthcare |
| Greenway Health |
| CareCloud |
| Kareo |
| Others |
Value Chain & Pricing Dynamics
AWS Reserved Instance pricing indices cascade through SaaS vendor cost structures, compressing margins for multi-tenant platforms while enabling aggressive per-seat pricing tiers that displace on-premise alternatives in Germany and India.
Pricing Analysis
Input-cost pass-through from hyperscaler cloud infrastructure reshapes vendor margin structures across deployment tiers. Three-tier pricing structure across enterprise, mid-market, and independent practice levels reflects integration depth and AI module inclusion. Certification grade under ONC Health IT Certification Program and HIPAA audit readiness drive price differentiation between compliant and non-compliant offerings. Pricing pressure stems from Epic and Cerner bundling practice management into base EHR contracts, forcing standalone vendors toward specialty workflow specialization. Independent physician associations exhibit highest price sensitivity, while academic medical centers prioritize interoperability over per-seat cost.
Supply Chain Analysis
India's PLI scheme for electronics manufacturing and data localization mandates under Digital Personal Data Protection Act are reshaping vendor hosting strategies and engineering talent sourcing. Cloud infrastructure supply concentrates in the United States, Ireland, and Singapore for primary data centers serving North American and European health systems. Software development draws from specialized health IT engineering pools in Bangalore, Hyderabad, and Greater Boston. Single-source vulnerability in FHIR implementation talent delays product roadmaps by 12-18 months. Distribution runs through direct enterprise sales teams for hospital systems and value-added resellers for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-powered revenue cycle automation, where automated coding accuracy commands premium pricing and reduces implementation friction for ambulatory surgery centers.
For Market Incumbents: To counter Epic and Cerner bundling strategies, deepen HL7 FHIR-native interoperability investments and acquire Medicaid billing specialists serving Federally Qualified Health Centers. Prioritize SMART on FHIR engineering capacity in Bangalore and Hyderabad clusters to compress development timelines against certification deadlines.
For New Entrants and Emerging Players: Rural health networks in Texas and Mississippi represent the most penetrable buyer archetype, lacking integrated billing systems and requiring cloud-native platforms with Medicaid eligibility verification. Behavioral health integration workflows offer whitespace for scheduling platforms handling split billing across CPT code categories. Pursue partnership-first go-to-market models with Federally Qualified Health Center networks rather than direct sales.
For Investors and Strategic Acquirers: Consolidation pressure builds where FDA 21 CFR Part 820 compliance costs and ONC certification timelines exhaust smaller vendor resources. Long-term viability favors platforms with established FHIR engineering teams and specialty clinic workflow depth. Monitor India's Ayushman Bharat digitization initiative as inflection indicator for emerging market platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Architecture | ONC interoperability mandates compress development timelines for HL7-compliant vendors. |
| Medicaid Billing Specialization | Federally Qualified Health Centers in Texas and Mississippi require eligibility verification integration. |
| AI Coding Engine Development | Automated claim denial reduction creates measurable ROI shortening specialty clinic sales cycles. |
| EU AI Act Conformity Pathway | CE marking investments become mandatory for algorithmic billing features in France and Germany. |
| Ayushman Bharat Localization | Hindi interface and Aadhaar integration capabilities unlock 150,000 health center digitization opportunity. |
Study Parameters
Direct dialogue with health system CIOs, revenue cycle directors, FHIR implementation engineers, and GPO contracts managers anchored primary insights, cross-referenced against ONC certification databases, FDA 510(k) filings, CMS Medicare cost reports, and hyperscaler healthcare vertical disclosures. Bottom-up and top-down triangulation validated segment sizing across deployment models and end-user categories.
Bottom-up modeling tracked cloud infrastructure costs, per-seat pricing trajectories, and implementation timeline data across the projection horizon. Segmentation dimensions included deployment model, organization size, specialty vertical, EHR integration complexity, and regional regulatory cluster. CAGRs derived from vendor revenue disclosures, health system procurement pipeline analysis, and cloud migration velocity indicators in Germany and India.
Underlying measurement precision varies by segment; cloud-based and SaaS deployment models carry tighter precision than legacy on-premise installations given disclosure transparency. Forecasts reflect assumptions around ONC certification timeline adherence and hyperscaler pricing stability. Cybersecurity incident frequency and information blocking enforcement intensity represent specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Global Hospital Asset Tracking and Inventory Management Systems Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Epharmacy Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market