
 Oman Insulin Drugs and Delivery Devices Market | 2026-2036
Oman Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Insulin Drugs and Delivery Devices Market Insights
Oman's national diabetes management guidelines is shifting procurement priorities toward temperature-stable insulin formulations across public health facilities. Novo Nordisk leverages its recombinant insulin manufacturing scale to sustain supply continuity for the Sultanate's hospital tenders. Julphar anchors regional production capabilities through its UAE-based biologics complex, competing on shorter lead times to Omani ports. Sanofi differentiates via its integrated pen-and-cartridge systems, occupying premium positions in private clinic channels.
Insulin drugs and delivery devices encompass recombinant human and analog insulin formulations supplied alongside syringes, pens, pumps, and inhalation systems for glycemic control in diabetes mellitus. These products require cold-chain distribution at 2-8°C for liquid formulations, with freeze-dried alternatives enabling ambient stability in remote deployment. Long-acting insulin formulations command structural priority in hospital formularies due to reduced dosing frequency and lower hypoglycemia risk. Pen-based delivery systems represent the fastest-growing delivery mode segment as home care patients transition from vial-and-syringe methods. Insulin pumps concentrate margin pools among specialized endocrinology clinics in Muscat and Salalah.
Oman's Ministry of Health and the Gulf Central Committee for Drug Registration shape market access through biologics licensing and import authorization requirements. The country's national pharmaceutical regulator enforces storage and handling standards that elevate barriers for non-cold-chain-compliant suppliers. CDSCO-aligned reference standards from India influence generic insulin approvals entering through Omani distributor networks. Stakeholders must monitor evolving reimbursement criteria for pump therapy as the Sultanate expands chronic disease coverage under its national health insurance framework.
Market Dynamics
Oman's Ministry of Health enforcement of stricter cold-chain storage protocols for biologics is restructuring procurement requirements across public health facilities, forcing suppliers to upgrade distribution infrastructure or exit hospital tenders.
Growth Catalysts
- Hospital tender centralization:The Ministry of Health is consolidating insulin procurement through Muscat's tertiary care centers, creating volume concentration that rewards suppliers with integrated cold-chain capabilities.
- SFDA-aligned registration pathways:Gulf Central Committee for Drug Registration harmonization with Saudi standards is accelerating biologics licensing timelines for regional manufacturers.
- Home care transition:Pen-based delivery systems are capturing patient preference as dosing convenience drives switching from vial-and-syringe methods in private clinic channels.
Market Restraints
- Refrigeration infrastructure gaps:Remote governorates lack 2-8°C storage continuity, limiting liquid insulin distribution to temperature-stable freeze-dried alternatives with higher unit economics.
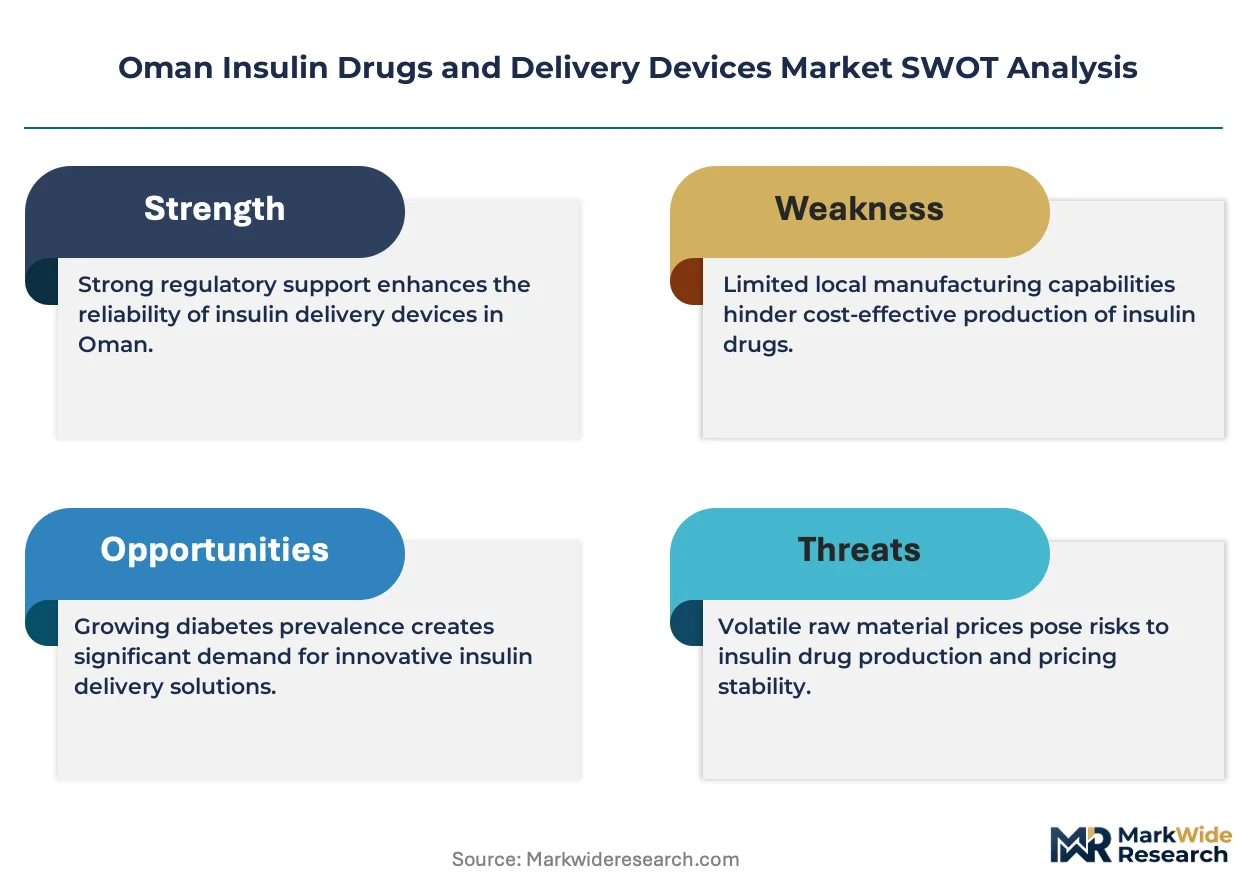
- Import dependency concentration:Over 90% of active pharmaceutical ingredients enter through Salalah and Sohar ports, creating single-point vulnerability for customs delays or shipping disruptions.
- Reimbursement ceiling rigidity:National health insurance framework pump therapy coverage criteria remain restrictive, capping addressable patient pools for advanced delivery devices.
Strategic Opportunities
- Dhofar Governorate penetration:Salalah's specialized endocrinology clinics remain undersupplied relative to diagnosed diabetes prevalence, offering first-mover positioning for localized distribution partnerships.
- Dual-cold-chain redundancy:Ambient-stable insulin formulations enable bypass of refrigeration requirements, opening rural health post access currently blocked by infrastructure constraints.
- Telemedicine integration:Remote glucose monitoring convergence with pen dose tracking is creating subscription-based chronic disease management bundles for private payers.
Industry Challenges
- Biologics handling certification scarcity:Licensed pharmacists with cold-chain compliance training are concentrated in Muscat, constraining expansion into secondary cities.
- Legacy vial-and-syringe inventory stranding:Public sector warehouses carry depreciating stockpiles as formularies prioritize pen systems, creating write-down pressure on distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Insulin Drugs and Delivery Devices Market |
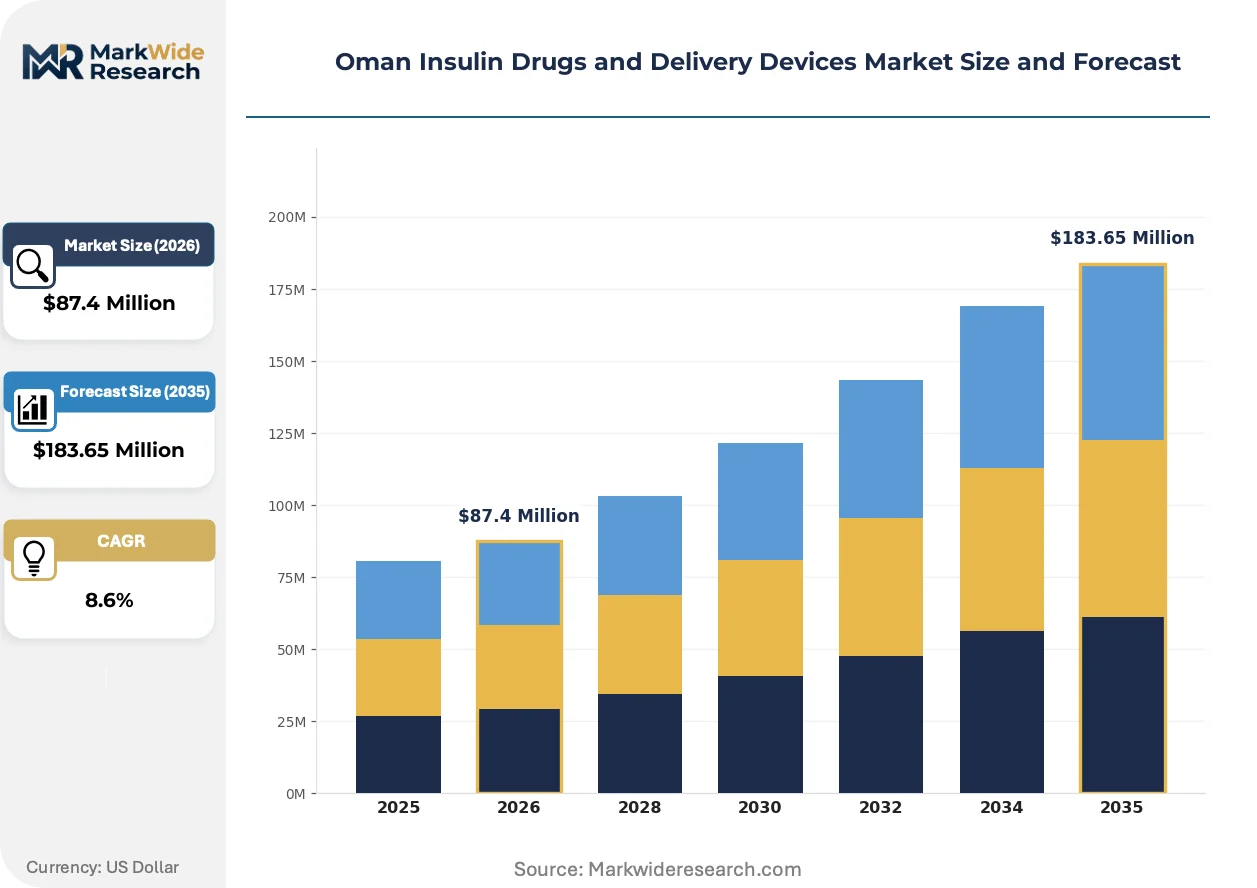
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $183.65 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Pre-Mixed Insulin, Insulin Delivery Devices End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Injection, Pen, Pump, Inhalation Formulation: Liquid, Powder, Freeze-Dried, Microencapsulation |
| Companies Covered | Novo Nordisk, Julphar, Novartis, Becton and Dickinson, Terumo, Sanofi, Eli Lilly, Medtronic, Roche, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Insulin Drugs and Delivery Devices Market Trends and Innovations
Connected delivery devices and formulation stability advances are compressing the gap between hospital-grade and home-administered insulin therapy, blurring traditional channel boundaries in Oman's diabetes care infrastructure.
Smart insulin pens with Bluetooth-enabled dose logging are decentralizing glycemic data capture from clinic-based HbA1c testing to real-time patient monitoring. Private endocrinology practices in Muscat are piloting these devices for high-frequency insulin users. This shift is decentralizing patient management accountability toward pharmacy networks capable of remote adherence coaching.
The Ministry of Health's biologics handling standards, modeled on CDSCO-aligned reference criteria, are mandating temperature excursion documentation across the distribution chain. Distributors must now deploy data loggers at every handoff point from port to patient. Hospital procurement committees are disqualifying suppliers lacking end-to-end cold-chain traceability, favoring integrated logistics operators over fragmented importer networks.
Patient self-administration preferences are fragmenting purchasing authority from physicians to pharmacists and direct-to-patient channels. Retail pharmacy chains in Seeb and Al Khuwair are capturing recurring pen cartridge refills through subscription models that bypass clinic inventory. This behavioral shift concentrates loyalty programs and adherence data in pharmacy networks rather than hospital records, reshaping supplier relationship investment priorities.
Oman Insulin Drugs and Delivery Devices Market Segmentation
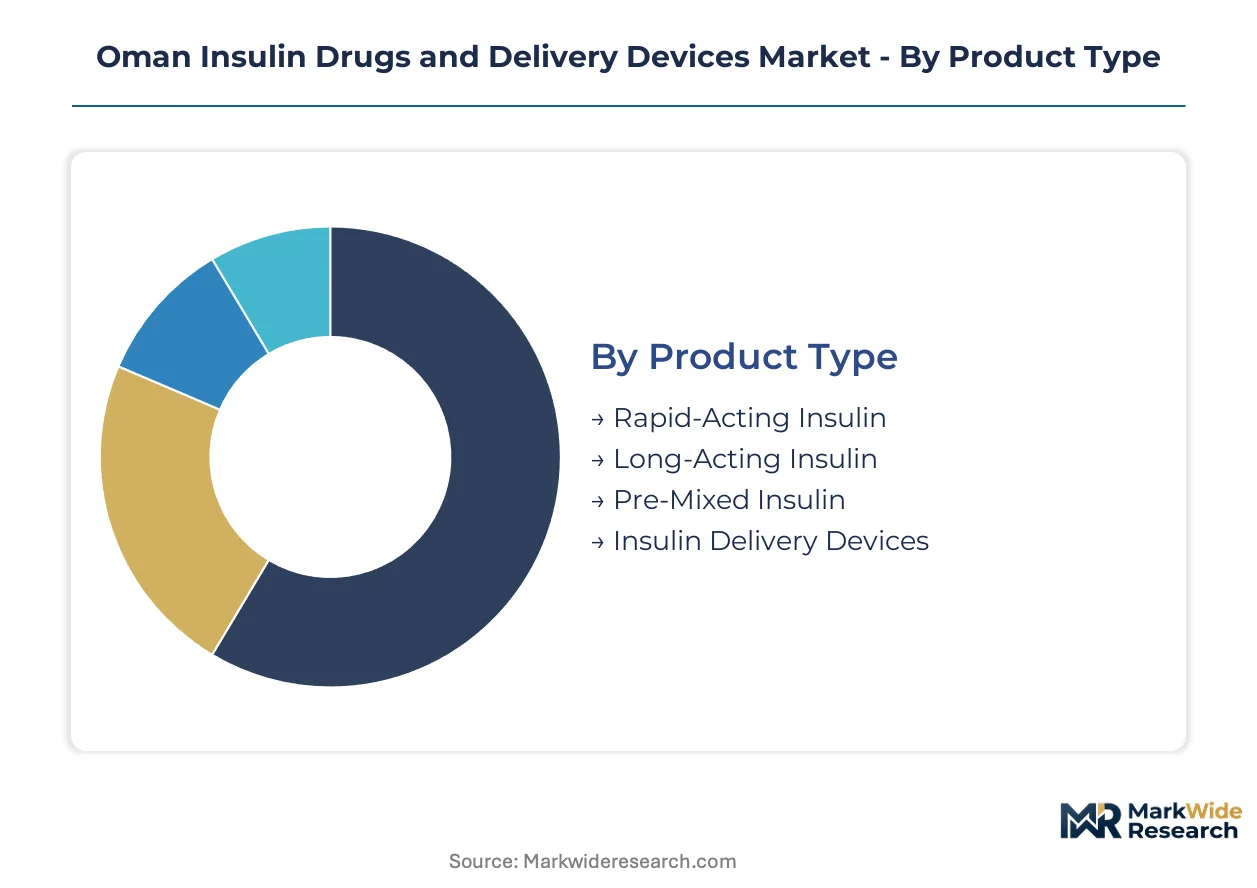
Insulin market segmentation in Oman reflects divergent procurement pathways between centralized hospital tenders and decentralized retail channels. Each dimension captures distinct buyer priorities: clinical efficacy drives formulary decisions, while convenience and cold-chain feasibility shape patient-level selection.
Product Type:
Hospital procurement committees prioritize glycemic stability and dosing flexibility when allocating tender volumes across insulin categories.
- Long-Acting Insulin:Basal insulin analogs provide 24-hour glucose control with reduced hypoglycemia risk. Muscat's tertiary care centers allocate the largest tender shares to this category, reflecting Ministry of Health emphasis on patient adherence through simplified dosing regimens.
- Rapid-Acting Insulin:Prandial formulations enable precise meal-time glucose management with rapid onset and short duration. Demand concentrates in specialized endocrinology clinics serving Type 1 diabetes patients requiring intensive insulin therapy protocols.
- Pre-Mixed Insulin:Fixed-ratio basal-bolus combinations suit patients with limited self-monitoring capacity.
- Insulin Delivery Devices:Pens, pumps, and syringes constitute the hardware layer of insulin therapy.
Volume sits with Long-Acting Insulin; growth tilts toward Insulin Delivery Devices as home administration expands.
End User:
Channel structure determines reimbursement pathways, cold-chain requirements, and supplier relationship intensity across Oman's healthcare system.
- Hospitals:Tertiary care centers in Muscat and regional hospitals manage the Sultanate's most complex diabetes cases through inpatient and outpatient services. These facilities command integrated cold-chain infrastructure and centralized procurement authority under Ministry of Health tenders.
- Home Care:Self-administered therapy shifts inventory ownership from institutions to patients, with retail pharmacies capturing recurring refill revenue through subscription models in Seeb and Al Khuwair.
- Clinics:Private endocrinology practices in Muscat and Salalah specialize in pump therapy and continuous glucose monitoring integration.
- Pharmacies:Retail networks serve as the final distribution node for pen cartridges and disposable syringes.
Procurement authority clusters at Hospitals; patient volume is migrating fastest toward Home Care.
Delivery Mode:
Patient dexterity, dosing frequency, and glycemic control targets guide device selection across Oman's diabetes population.
- Pen:Cartridge-based reusable and disposable pens dominate private clinic dispensing due to dose accuracy and portability. Bluetooth-enabled smart pens are piloting in Muscat practices to capture real-time adherence data.
- Injection:Traditional vial-and-syringe methods persist in public sector warehouses where legacy inventory creates write-down pressure as formularies shift toward pen systems.
- Pump:Continuous subcutaneous insulin infusion systems serve specialized Type 1 diabetes patients through Salalah's endocrinology clinics and Muscat's premium private channels.
- Inhalation:Pulmonary insulin delivery remains a niche alternative for needle-averse patients with specific physiological suitability.
Installed base remains concentrated in Injection; device transition is accelerating most quickly in Pen systems.
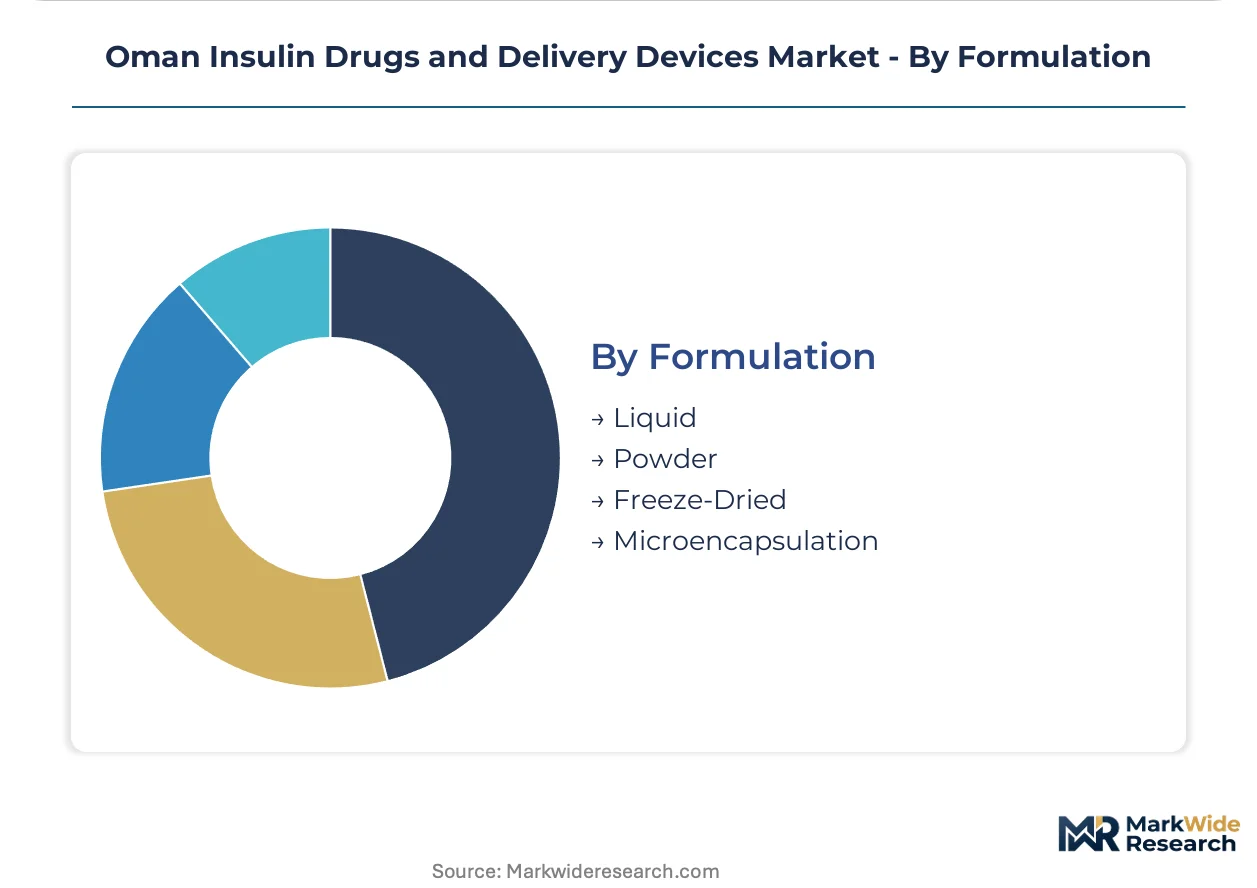
Formulation:
Temperature stability requirements determine distribution feasibility across Oman's varied climatic and infrastructure conditions.
- Liquid:Aqueous insulin solutions require uninterrupted 2-8°C cold chain from port to patient. Ministry of Health biologics handling standards mandate data logger documentation at every handoff, disqualifying suppliers lacking end-to-end traceability.
- Freeze-Dried:Lyophilized formulations enable ambient storage stability, opening rural health post access in Dhofar and Al Wusta governorates where refrigeration gaps block liquid insulin distribution.
- Powder:Dry powder insulin supports inhalation delivery with reduced thermal sensitivity.
- Microencapsulation:Encapsulated insulin technologies promise extended-release profiles and enhanced stability profiles.
Clinical preference favors Liquid; access expansion depends most heavily on Freeze-Dried alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Muscat anchors insulin procurement volume through its tertiary care centers, where the Ministry of Health concentrates cold-chain infrastructure and centralized tender authority for the Sultanate's diabetes management programs.
Muscat Governorate
Specialized endocrinology clinics in Seeb and Al Khuwair drive demand for pen-based delivery systems and continuous glucose monitoring integration. The Ministry of Health enforces biologics handling standards modeled on CDSCO-aligned reference criteria, mandating temperature excursion documentation across distribution chains. Retail pharmacy networks in the capital region capture recurring insulin cartridge refills through subscription models that bypass traditional clinic inventory pathways.
Dhofar Governorate
Salalah's endocrinology clinics serve Type 1 diabetes patients requiring intensive insulin therapy protocols, yet remain undersupplied relative to diagnosed prevalence rates. The Gulf Central Committee for Drug Registration harmonizes biologics licensing with Saudi SFDA standards, accelerating approvals for regional manufacturers seeking port access through Salalah. Localized distribution partnerships offer first-mover positioning as specialized diabetes care expands beyond Muscat's concentration.
Al Batinah Governorate
Secondary cities between Muscat and the UAE border manage growing diabetes patient loads through regional hospital networks with limited cold-chain redundancy. Freeze-dried insulin formulations enable ambient storage stability, opening rural health post access where refrigeration gaps block liquid insulin distribution. Port proximity to Sohar creates import pathway alternatives, though customs coordination remains concentrated through Muscat's regulatory clearance infrastructure.
Al Wusta Governorate
Remote central desert regions face the most acute refrigeration infrastructure gaps, constraining liquid insulin distribution to temperature-stable alternatives with higher unit economics. The national health insurance framework's restrictive pump therapy coverage criteria cap addressable patient pools for advanced delivery devices regardless of clinical suitability. Mobile health units and telemedicine integration are piloting remote glucose monitoring convergence with simplified pen dose tracking for dispersed populations.
Al Sharqiyah Governorate
Eastern coastal cities balance fishing industry demographics with emerging urban diabetes prevalence, creating mixed patient profiles between Type 2 lifestyle management and Type 1 intensive therapy needs. Julphar leverages its UAE-based biologics complex to compete on shorter lead times to Omani ports serving this region. Distributor networks must deploy data loggers at every handoff point from port to patient, disqualifying fragmented importer networks lacking end-to-end cold-chain traceability.
Oman Insulin Drugs and Delivery Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cold-chain certification and integrated delivery system capabilities, with hospital tender centralization rewarding suppliers possessing end-to-end biologics handling infrastructure. The vendor base stratifies into three tiers: multinational pharmaceutical manufacturers with recombinant insulin scale, regional biologics producers leveraging geographic proximity, and fragmented distributor networks facing disqualification under stricter Ministry of Health procurement protocols. Dominant competitive moves include strategic partnerships with logistics operators for cold-chain redundancy and portfolio diversification into temperature-stable formulations.
Within the multinational pharmaceutical tier, Novo Nordisk and Sanofi occupy positions exemplifying divergent strategic archetypes. Novo Nordisk represents the manufacturing-scale specialist with recombinant insulin production continuity sustaining Sultanate hospital tender participation. Sanofi anchors the integrated delivery system approach through pen-and-cartridge combinations capturing premium private clinic channels. Julphar sits within the regional proximity tier as a UAE-based biologics producer competing on abbreviated lead times to Omani port infrastructure.
| Leading Market Players |
|---|
| Novo Nordisk |
| Julphar |
| Novartis |
| Becton and Dickinson |
| Terumo |
| Sanofi |
| Eli Lilly |
| Medtronic |
| Roche |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees in Muscat's tertiary care centers concentrate purchasing authority for insulin delivery systems, anchoring contract-based long-term offtake agreements that reward suppliers with integrated cold-chain certification. This buyer concentration shifts pricing power toward volume-scaled manufacturers capable of meeting Ministry of Health biologics handling standards.
Pricing Analysis
Value-based pricing anchored to patient adherence outcomes shapes hospital formulary negotiations for long-acting insulin analogs. Three-tier pricing structure across premium, standard, and economy levels separates pen-and-cartridge systems from vial-and-syringe methods and freeze-dried alternatives. Cost compression in standard-tier liquid formulations is intensifying because cold-chain infrastructure investments are being amortized across tender volumes. Home care patients demonstrate highest price sensitivity due to out-of-pocket cartridge refill exposure, while specialized endocrinology clinics show lowest sensitivity for pump therapy integration.
Supply Chain Analysis
Dual-sourcing requirements embedded in Ministry of Health procurement protocols mandate multi-supplier qualification for recombinant insulin APIs. Manufacturing concentration rests on Denmark, France, and the UAE for finished formulations, with active pharmaceutical ingredients drawing from India and China. Single-source vulnerability concentrates at Salalah and Sohar ports where over 90 percent of biologics enter the Sultanate. Distribution runs through integrated logistics operators with end-to-end temperature traceability rather than fragmented importer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's insulin market sits in a device-transition phase where Bluetooth-enabled smart pens are displacing legacy vial-and-syringe methods across private clinic channels.
For Market Incumbents: Deploy cold-chain certification leverage to consolidate hospital tender participation as Ministry of Health standards disqualify fragmented distributors. Novo Nordisk and Sanofi should deepen backward integration into temperature-stable formulation R&D to offset refrigeration infrastructure gaps in Dhofar and Al Wusta governorates. The threat of regional biologics producers like Julphar compressing lead times requires defensive capacity positioning near Omani port infrastructure. For New Entrants and Emerging Players: SFDA-aligned registration pathways in the Gulf Central Committee for Drug Registration open a window for abbreviated biologics licensing of freeze-dried insulin alternatives. Dhofar Governorate's undersupplied endocrinology clinics represent the most penetrable geography, with Salalah's port access enabling localized distribution partnerships. A direct-to-patient subscription model through retail pharmacy networks bypasses hospital procurement concentration. For Investors and Strategic Acquirers: The window for entry favors logistics operators with dual-cold-chain redundancy capabilities over pure-play manufacturers. Mid-cap regional distributors possessing end-to-end temperature traceability infrastructure represent prime acquisition targets as procurement standards tighten. Watch Ministry of Health reimbursement criteria expansion for pump therapy as the inflection signal for advanced delivery device addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures tender volume concentration under Ministry of Health centralized procurement protocols. |
| Reimbursement Strategy | Aligns pump therapy coverage expansion with national health insurance framework chronic disease priorities. |
| Manufacturing Scale-Up | Builds recombinant insulin continuity for Sultanate hospital tender supply security. |
| Regulatory Approval Pathway | Accelerates biologics licensing through Gulf Central Committee for Drug Registration harmonization. |
| Software Companion Development | Integrates Bluetooth-enabled dose tracking with telemedicine chronic disease management bundles. |
Research Methodology
Ministry of Health tender databases, Gulf Central Committee for Drug Registration filings, and CDSCO-aligned reference standards formed the secondary backbone for this analysis. Primary interviews with hospital procurement managers, formulary directors at tertiary care centers, regulatory affairs leads, and retail pharmacy chain operators validated demand-side assumptions. Bottom-up and top-down triangulation reconciled patient volume estimates with tender award values across the analysis window.
Bottom-up modeling anchored forecasts to insulin patient prevalence by diabetes type, dosing regimen intensity, and device adoption curves. Segmentation dimensions included product type, end user channel, delivery mode, and formulation stability requirements. CAGRs were derived from volume-weighted average price trajectories and patient population growth assumptions. Forecast inputs incorporated cold-chain infrastructure deployment timelines and reimbursement policy evolution signals.
The model assumes a particular technology adoption path; alternative pathways for smart pen penetration would alter the outlook for pump therapy growth rates. Forecasts reflect assumptions about Ministry of Health procurement centralization continuity and SFDA-aligned registration pathway stability. Deviation in national health insurance pump therapy coverage criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Hyperinsulinemia Hypoglycaemia Treatment Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market