
 Femtech Market | 2026-2036
Femtech Market Size, Share, and Industry Trends Forecast 2026-2036
Femtech Market Analysis
Israeli digital health startups is consolidating around pregnancy monitoring and remote diagnostics. Flo Health, Inc. leverages machine learning to personalize cycle predictions across millions of active users. Elvie anchors the pelvic health hardware segment with connected devices for postpartum recovery. Maven Clinic positions its virtual care network to capture employer-sponsored fertility benefits.
Femtech encompasses software applications, wearable sensors, and connected medical devices engineered to monitor, diagnose, or manage female-specific physiological conditions including hormonal cycles, pregnancy, and pelvic floor function; these systems typically integrate biosensors sampling temperature, heart rate variability, and impedance data with cloud-based analytics platforms to deliver personalized health insights. Mobile Applications capture the broadest user base through subscription models for menstrual and fertility tracking, while Wearable Tech generates premium hardware margins through continuous biomonitoring. Telehealth Platforms are expanding fastest as synchronous video consultation integrates with asynchronous data streams from IoT Devices.
FDA software-as-medical-device pathways and HIPAA privacy frameworks shape product development timelines and data architecture requirements for US market entrants. The EU AI Act and MDR classification rules in Europe impose additional validation burdens on algorithmic diagnostic features. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring to determine geographic prioritization and partnership strategies.
Market Dynamics
Remote patient monitoring reimbursement codes are restructuring commercial viability across Femtech segments, as synchronous telehealth platforms integrate with asynchronous biometric streams from wearable sensors and connected medical devices.
Growth Catalysts
- Digital Health Reimbursement Frameworks:Germany's DiGA fast-track pathway accelerates app-based fertility tracking commercialization by enabling statutory health insurance coverage decisions within months rather than years.
- FDA Software-as-Medical-Device Pathways:De Novo and 510(k) clearances for algorithmic diagnostic features compress time-to-market for cycle prediction and pregnancy risk stratification tools.
- Employer-Sponsored Fertility Benefits:Large self-insured employers in the United States are expanding virtual care carve-outs for reproductive health, creating direct-to-enterprise demand channels independent of traditional healthcare systems.
Market Restraints
- Biometric Sensor Input Volatility:Temperature and impedance sensor accuracy degrades with skin tone variation and ambient conditions, constraining algorithmic reliability across diverse user populations.
- EU MDR Classification Burden:Algorithmic diagnostic features in fertility apps now face Class IIa or IIb medical device requirements, extending validation timelines and clinical evidence requirements.
- Data Localization Mandates:Health data residency requirements in Germany, France, and Saudi Arabia fragment cloud infrastructure economics and complicate multi-territory platform architectures.
Strategic Opportunities
- Menopause Management White Space:Hormonal transition symptom tracking and connected cooling devices remain underpenetrated relative to fertility and pregnancy segments, with limited specialized hardware entrants.
- AI Act Regulatory Tailwind:EU conformity assessment frameworks for high-risk AI systems create first-mover certification advantages for platforms that pre-validate algorithmic transparency and human oversight protocols.
- Pharmacy Distribution Integration:Retail pharmacy chains are piloting in-aisle connected device dispensing with telehealth referral loops, creating new patient acquisition channels beyond direct-to-consumer marketing.
Industry Challenges
- Clinical Evidence Generation Timelines:Prospective validation studies for cycle prediction accuracy require 12-24 month enrollment periods, compressing competitive response windows to algorithm improvements.
- Interoperability with Electronic Health Records:Health Level Seven and FHIR integration standards vary across US health system implementations, forcing redundant engineering for enterprise contracts.
- Biometric Data Consent Architecture:GDPR Article 9 special category processing requirements and HIPAA minimum necessary standards impose conflicting technical controls on cross-border data flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Femtech Market |
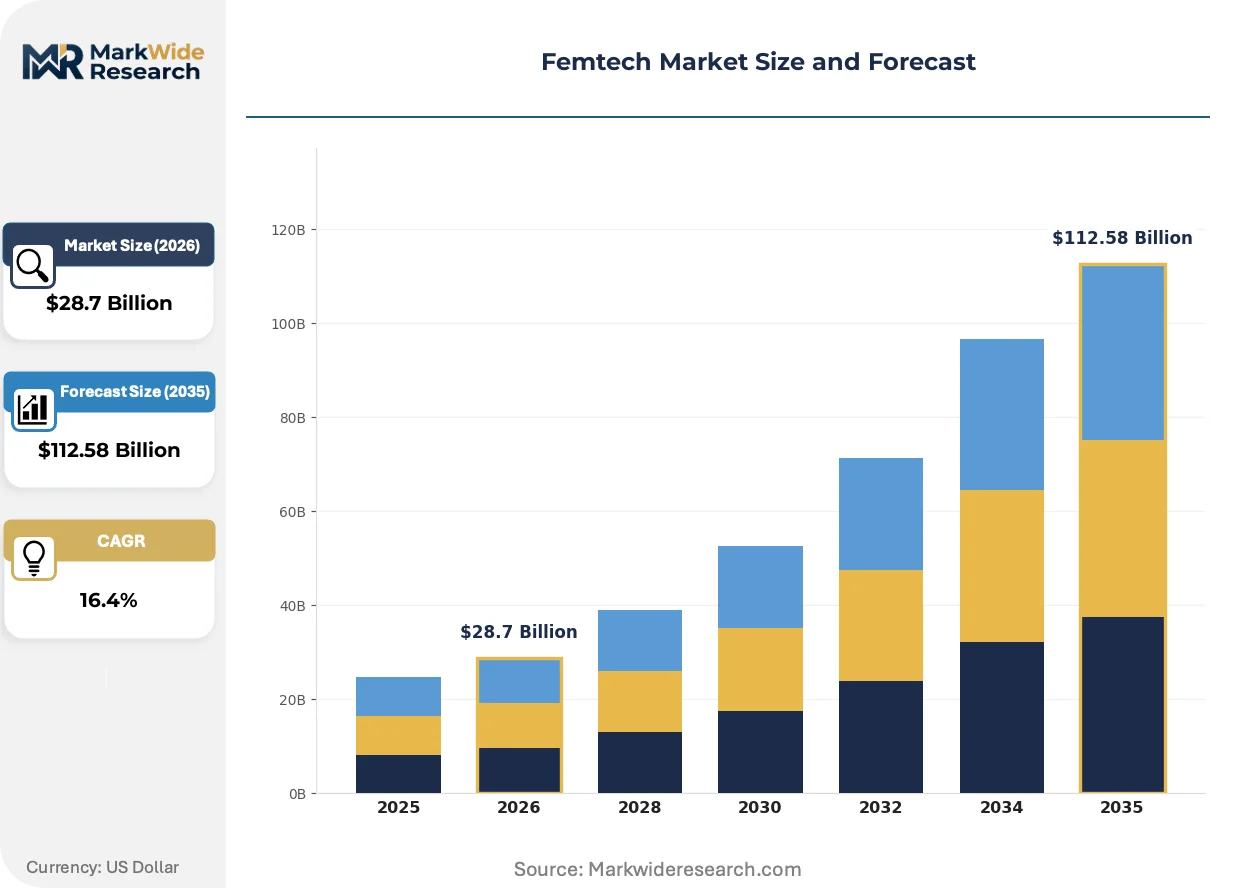
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $112.58 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
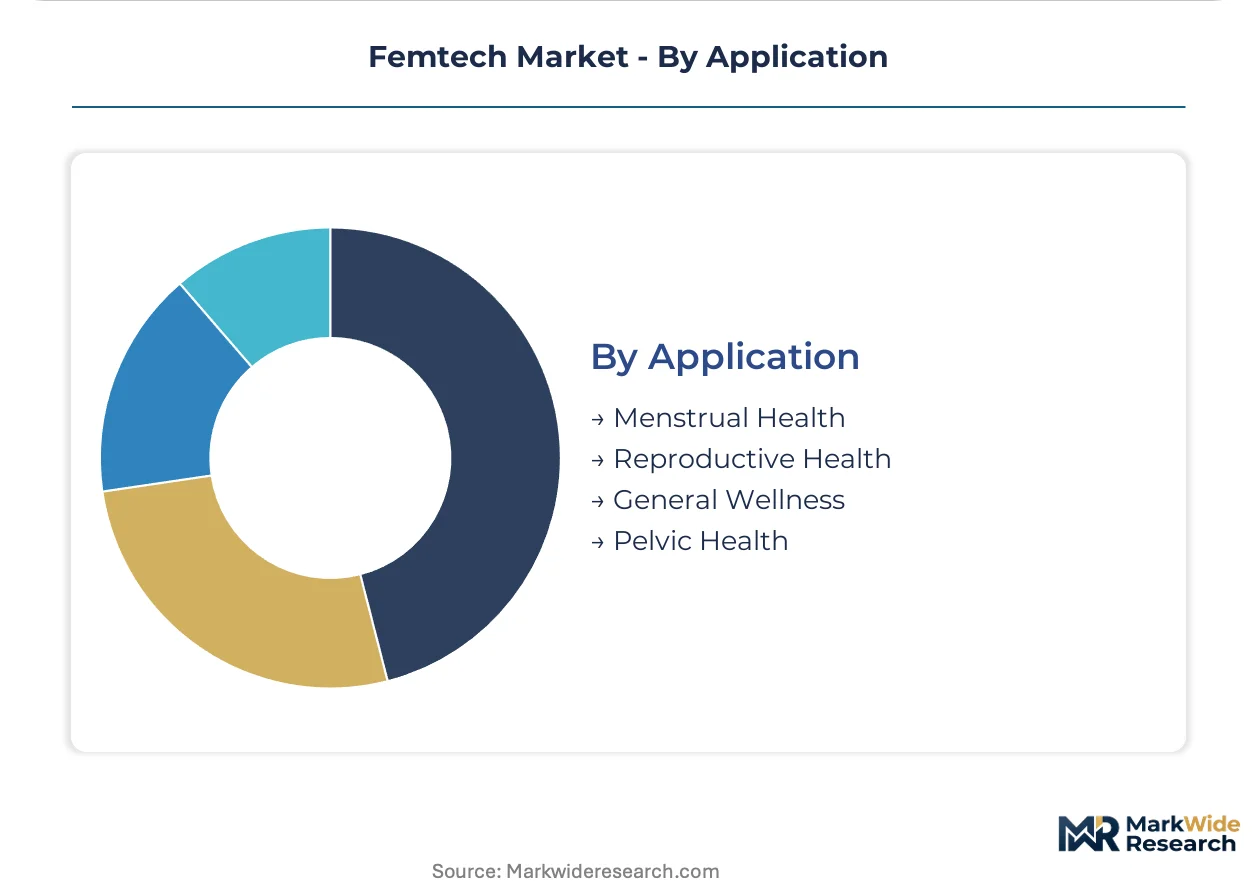
| Segmentation | Product Type: Menstrual Products, Fertility Solutions, Pregnancy Apps, Health Monitoring Devices Technology: Wearable Tech, Mobile Applications, IoT Devices, Telehealth Platforms End User: Individuals, Healthcare Providers, Clinics, Corporations Application: Menstrual Health, Reproductive Health, General Wellness, Pelvic Health |
| Companies Covered | Flo Health, Inc., Natural Cycles USA Corp, HeraMED, Clue by Biowink GmbH, iSono Health, Inc., Elvie, Maven Clinic, Allara Health, NUVO Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Femtech Market Emerging Trajectories
Continuous biomonitoring hardware is converging with cloud-native analytics platforms, compressing the latency between physiological signal capture and personalized intervention delivery across reproductive health use cases.
Photoplethysmography sensors embedded in ring and patch form factors are converging with machine learning-based cardiovascular inference models. Fertility-focused wearable manufacturers are adopting these modules for luteal phase confirmation and early pregnancy detection. This convergence is compressing the form factor and price differentiation between general wellness trackers and specialized Femtech hardware.
The EU AI Act's high-risk system classification for reproductive health algorithms is mandating conformity assessment procedures before market placement. Developers must now document training data provenance and implement human-in-the-loop oversight for diagnostic outputs. Femtech platforms with EU market ambitions are restructuring quality management systems and clinical governance frameworks to satisfy notified body expectations.
Subscription fatigue among direct-to-consumer health app users is pushing Femtech platforms toward pharmacy and employer benefit integrations as primary acquisition channels. Telehealth-enabled device bundling is displacing standalone app subscriptions in the United States, while German statutory insurance reimbursement creates preference for DiGA-listed applications. This channel rotation is most visible in fertility tracking, where employer-sponsored benefit administrators now curate approved vendor lists.
Femtech Market Segmentation
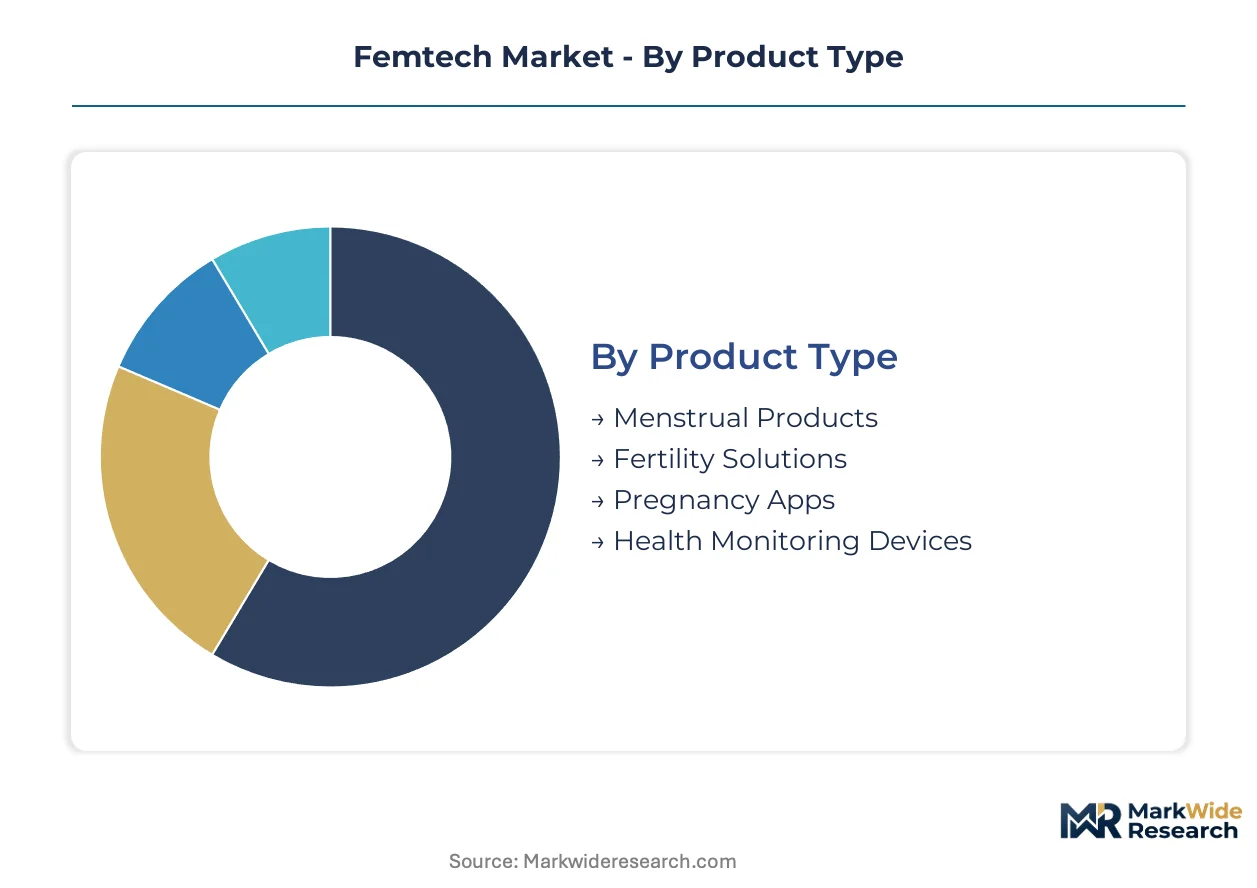
Femtech market segmentation reveals distinct buyer priorities across product categories, with reimbursement pathways and data architecture requirements reshaping commercial viability. Technology integration patterns and end-user procurement authority determine margin capture and partnership strategies for platform developers.
Product Type:
Buyers differentiate primarily by clinical validation requirements and hardware dependency, with enterprise purchasers demanding FDA-cleared diagnostic features while direct-to-consumer users prioritize subscription flexibility.
- Menstrual Products:Digital tracking applications and connected hygiene devices sample biomarkers including basal body temperature and cervical fluid impedance. Demand concentrates in Germany where DiGA reimbursement enables statutory health insurance coverage for app-based cycle monitoring.
- Fertility Solutions:Algorithmic ovulation prediction platforms integrate wearable sensor streams with cloud-based analytics for personalized conception timing. US employer-sponsored benefits administrators now curate approved vendor lists, creating direct-to-enterprise procurement channels.
- Pregnancy Apps:Remote monitoring platforms for gestational diabetes and hypertension risk stratification.
- Health Monitoring Devices:Connected pelvic floor trainers and postpartum recovery hardware with biosensor feedback loops.
Menstrual Products lead volumes today; Fertility Solutions is gaining share fastest.
Technology:
Margin structures diverge sharply between recurring software revenue and one-time hardware sales, with hybrid subscription-device bundles capturing highest lifetime value per user.
- Mobile Applications:Cloud-native cycle tracking and symptom logging platforms deploy machine learning for personalized health insights. German statutory insurance reimbursement creates preference for DiGA-listed applications over direct-to-consumer subscriptions.
- Wearable Tech:Continuous biomonitoring rings and patches sample photoplethysmography signals for cardiovascular inference during luteal phase. US healthcare providers expand adoption for remote reproductive health monitoring.
- IoT Devices:Connected medical devices with embedded biosensors for temperature and impedance measurement.
- Telehealth Platforms:Synchronous video consultation integrated with asynchronous biometric data streams.
Wearable Tech commands premium pricing today; Telehealth Platforms shows steepest expansion trajectory.
End User:
Procurement authority and budget scale separate individual subscribers from institutional purchasers, with enterprise contracts demanding interoperability certifications absent from consumer channels.
- Healthcare Providers:Hospital systems and physician practices integrating Femtech data into electronic health records through HL7 FHIR standards. US reimbursement codes for remote patient monitoring restructure commercial viability for provider-facing platforms.
- Corporations:Self-insured employers carving out virtual care benefits for reproductive health as talent retention instruments. Large US employers now contract directly with Femtech platforms, bypassing traditional health system intermediaries.
- Individuals:Direct-to-consumer subscribers purchasing monthly or annual app memberships.
- Clinics:Specialty fertility and women's health practices deploying connected devices for patient monitoring.
Individuals dominate subscriber counts today; Corporations is expanding most quickly.
Application:
Clinical evidence requirements and regulatory classification intensity vary by physiological condition monitored, with diagnostic claims triggering medical device pathways absent from general wellness positioning.
- Reproductive Health:Fertility tracking, ovulation prediction, and pregnancy risk stratification platforms face EU MDR Class IIa or IIb requirements for algorithmic diagnostic features. Extended validation timelines and clinical evidence requirements constrain competitive entry.
- Pelvic Health:Connected devices for postpartum recovery and pelvic floor dysfunction address underpenetrated hardware segments with limited specialized entrants.
- Menstrual Health:Cycle tracking and symptom management applications with wellness positioning.
- General Wellness:Broad health monitoring with female-specific interface adaptations.
Reproductive Health captures highest revenue concentration today; Pelvic Health presents the largest white space opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing Femtech commercialization activity toward jurisdictions with streamlined digital health pathways. The FDA's software-as-medical-device clearances attract algorithm developers seeking faster market access, while Germany's DiGA framework lures app-based platforms with statutory reimbursement guarantees.
United States
Employer-sponsored fertility benefits and remote patient monitoring reimbursement codes drive enterprise procurement. FDA De Novo and 510(k) pathways compress validation timelines for cycle prediction algorithms. Boston and San Francisco anchor venture-backed startup clusters developing AI-enabled diagnostic tools.
Germany
Statutory health insurance coverage decisions through the DiGA fast-track accelerate commercialization for app-based fertility tracking. The EU MDR and AI Act impose conformity assessment burdens on algorithmic diagnostic features. Berlin hosts the highest concentration of DiGA-listed Femtech applications in Europe.
Israel
Pregnancy monitoring and remote diagnostics specialization concentrates venture capital deployment. The country's national pharmaceutical regulator aligns with FDA recognition agreements for streamlined dual-market approvals. Tel Aviv anchors digital health startup density with strong hospital system pilot partnerships.
United Kingdom
NHS digital transformation programs create procurement channels for telehealth-enabled reproductive health platforms. MHRA post-Brexit regulatory autonomy enables tailored software-as-medical-device guidance. London concentrates Femtech venture activity with proximity to European market access.
India
Cost-sensitive menstrual health applications address large underpenetrated user bases in tier-2 and tier-3 cities. CDSCO medical device rules increasingly capture software with diagnostic claims. Bengaluru anchors health-tech engineering talent pools serving global platform development.
Femtech Market Vendor Landscape
United States producers anchor the venture-funded tier; European specialists hold regulatory-first positioning with DiGA and MDR pre-certification. The vendor base stratifies across three archetypes: algorithm-native platforms, connected hardware manufacturers, and virtual care networks. Consolidation pressure concentrates among fertility tracking applications with overlapping user bases. Dominant competitive moves include strategic partnerships with employer benefits administrators and backward integration into biosensor hardware design.
Within the algorithm-native tier, Flo Health, Inc. and Clue by Biowink GmbH occupy positions exemplifying scale-driven cycle prediction platforms; Elvie anchors the connected hardware archetype with pelvic floor training specialization. Maven Clinic represents the virtual care network model targeting enterprise procurement channels. These three companies illustrate the geographic and strategic diversification patterns visible across the competitive set.
| Leading Market Players |
|---|
| Flo Health, Inc. |
| Natural Cycles USA Corp |
| HeraMED |
| Clue by Biowink GmbH |
| iSono Health, Inc. |
| Elvie |
| Maven Clinic |
| Allara Health |
| NUVO Inc. |
| Others |
Supply Flow & Price Mechanics
Photoplethysmography sensor miniaturization is collapsing hardware cost curves while concentrating optical component sourcing among East Asian contract manufacturers, simultaneously compressing wearable price points and tightening supplier leverage over Femtech OEMs.
Pricing Analysis
Retailer markup layers in pharmacy distribution channels absorb 35-50% of end-user price realization for connected pelvic floor devices. Subscription-device hybrid models command premium positioning through FDA clearance tier differentiation, while direct-to-consumer app subscriptions face cost compression from German DiGA reimbursement alternatives. Employer benefits procurement exhibits lowest price sensitivity due to talent retention ROI framing, whereas individual subscribers in emerging markets demonstrate acute elasticity to monthly fee adjustments.
Supply Chain Analysis
German data localization mandates and Saudi health data residency rules are fragmenting cloud infrastructure sourcing, forcing multi-territory platform architectures with redundant hosting nodes. Taiwan and South Korea anchor photoplethysmography sensor wafer production, while China dominates lithium-polymer battery cell supply for wearable form factors. Single-source vulnerability concentrates in FDA-registered contract manufacturing organizations for Class II device assembly. Distribution runs through pharmacy chain partnerships and employer benefits administrators rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Femtech quality specifications are hardening around clinical validation depth as employer benefits administrators and German statutory insurers demand DiGA-listed or FDA-cleared platforms over wellness-positioned alternatives.
For Market Incumbents: Anchor defensive positioning through backward integration into biosensor hardware design, capturing margin from optical module sourcing currently concentrated among East Asian suppliers. Deepen clinical evidence libraries for algorithmic diagnostic features to extend EU MDR validation moats against emerging algorithm-native competitors. Prioritize HL7 FHIR interoperability certifications for US health system enterprise contracts. For New Entrants and Emerging Players: AI-enabled menopause symptom tracking offers the most penetrable white space, with limited specialized hardware entrants and minimal clinical evidence requirements compared to fertility segments. Target UK NHS digital transformation procurement channels for telehealth-enabled reproductive health platforms, leveraging MHRA regulatory autonomy for streamlined software-as-medical-device positioning. Deploy pharmacy distribution partnerships as primary patient acquisition channel to bypass saturated direct-to-consumer marketing. For Investors and Strategic Acquirers: Valuations sit cheapest among algorithm-native platforms without hardware revenue diversification, despite superior gross margin profiles. Long-term viability favors hybrid subscription-device models with regulatory pre-certification in multiple jurisdictions. Watch EU AI Act conformity assessment completion rates as inflection indicator for platform scalability and exit optionality.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Submission | German statutory insurance reimbursement compresses patient acquisition costs below direct-to-consumer CAC benchmarks. |
| FDA De Novo Clearance Pathway | Software-as-medical-device classification enables employer benefits channel entry with clinical credibility differentiation. |
| Photoplethysmography Module Integration | Continuous biomonitoring convergence collapses form factor differentiation between wellness and medical-grade wearables. |
| Pharmacy Distribution Partnership | In-aisle connected device dispensing with telehealth referral loops displaces standalone app subscription economics. |
| EU AI Act Conformity Assessment | High-risk system pre-certification creates first-mover advantage for algorithmic transparency in reproductive health diagnostics. |
Methodological Framework
Multiple input streams — executive interviews with Femtech platform CTOs, regulatory affairs leads at notified bodies, and employer benefits administrators — were reconciled against secondary validation from FDA 510(k) and De Novo clearance databases, DiGA directory listings, and CMS remote patient monitoring reimbursement code analyses. Bottom-up triangulation across product type, technology, and end-user segmentation dimensions was cross-checked against top-down market sizing from venture capital deployment tracking and health system procurement database extracts.
Historical revenue trajectories were cross-referenced against panel input from hospital purchasing committees and GPO contracts managers to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated deployment model, clinical validation tier, and regional regulatory pathway as primary dimensions. CAGRs were derived from algorithmic diagnostic feature adoption curves and employer-sponsored benefit expansion rates rather than extrapolated historical trends.
The model holds under stable FDA software-as-medical-device clearance timelines and sustained German DiGA reimbursement commitment; deviation in EU MDR classification stringency or data localization mandate expansion would shift platform economics and geographic prioritization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Digital Mhealth Solution Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Middle East and Africa Nurse Call Systems Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Hand Hygiene Monitoring System Market