
 Healthcare Survey Software Market | 2026-2036
Healthcare Survey Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Survey Software Market Insights
Cloud-native architecture is shifting the underlying cost structure of healthcare survey platforms away from legacy on-premise installations. Qualtrics leverages its enterprise-grade HIPAA-compliant infrastructure to anchor contracts with large hospital systems. SurveyMonkey competes through streamlined self-service tools that occupy the mid-market clinic segment. Alchemer differentiates by offering deep API extensibility for research organizations running longitudinal patient studies.
Healthcare survey software encompasses digital platforms engineered to capture, process, and analyze structured feedback from patients, clinicians, and institutional stakeholders, typically incorporating encryption protocols, role-based access controls, and real-time dashboards with sub-second query response times. These systems serve the commercial purpose of enabling evidence-based quality improvement, regulatory reporting, and population health research. Web-based solutions lead current deployment volumes due to minimal client-side maintenance and instant scalability across multi-site hospital networks. Mobile apps represent the fastest-growing product type as bedside tablet adoption and post-discharge SMS-linked surveys expand patient touchpoints. SaaS deployment models capture the dominant margin pool by converting capital expenditure into recurring revenue streams with embedded analytics upgrades.
FDA 21 CFR Part 11 and HIPAA Security Rule frameworks compel vendors to implement immutable audit trails, encrypted data transmission, and business associate agreements before accessing US healthcare procurement channels. EMA's Good Clinical Practice guidelines and GDPR data minimization principles shape European product roadmaps through mandatory consent workflows and cross-border data residency constraints. Stakeholders must monitor how emerging FDA guidance on artificial intelligence in clinical decision support extends validation requirements to algorithmic survey scoring tools.
Market Dynamics
Cloud-native architecture is compressing deployment timelines for patient experience platforms while FDA 21 CFR Part 11 validation requirements force vendors to rebuild audit-trail infrastructures from the ground up.
Growth Catalysts
- Regulatory digitization mandates:FDA's 21 CFR Part 11 framework compels US hospital networks to replace paper-based patient feedback systems with validated electronic records, creating immediate procurement windows for compliant vendors.
- Hospital consolidation waves:German hospital networks are centralizing IT procurement across multi-site systems, demanding unified survey infrastructure that spans inpatient, outpatient, and post-acute touchpoints.
- Bedside tablet proliferation:Point-of-care hardware deployments in US acute care facilities enable real-time patient experience capture at discharge, replacing retrospective mail-based surveys.
Market Restraints
- Validation cost concentration:FDA 21 CFR Part 11 compliance requires dedicated quality management systems and third-party audit costs that consume 15-25% of platform development budgets.
- Data residency fragmentation:GDPR cross-border transfer restrictions force vendors to maintain separate European cloud instances, duplicating infrastructure spend without proportional revenue expansion.
- Legacy system entrenchment:Epic and Cerner EHR integrations require proprietary HL7 FHIR connectors that limit vendor switching flexibility and extend sales cycles.
Strategic Opportunities
- Post-acute care white space:Skilled nursing facilities and home health agencies in the United States remain underserved by enterprise survey platforms, presenting greenfield deployment potential.
- AI-assisted sentiment analysis:Natural language processing tools are converging with structured survey instruments to extract qualitative insights from open-text patient comments at scale.
- EMA Good Clinical Practice alignment:European research organizations require longitudinal patient-reported outcome platforms that satisfy both EMA guidelines and GDPR consent workflows.
Industry Challenges
- Interoperability engineering scarcity:Vendors face acute shortages of HL7 FHIR integration specialists capable of building real-time bidirectional data flows with Cerner and Epic installations.
- Validation timeline compression:FDA software-as-a-medical-device guidance is extending 510(k) review periods for algorithmic survey scoring tools, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Survey Software Market |
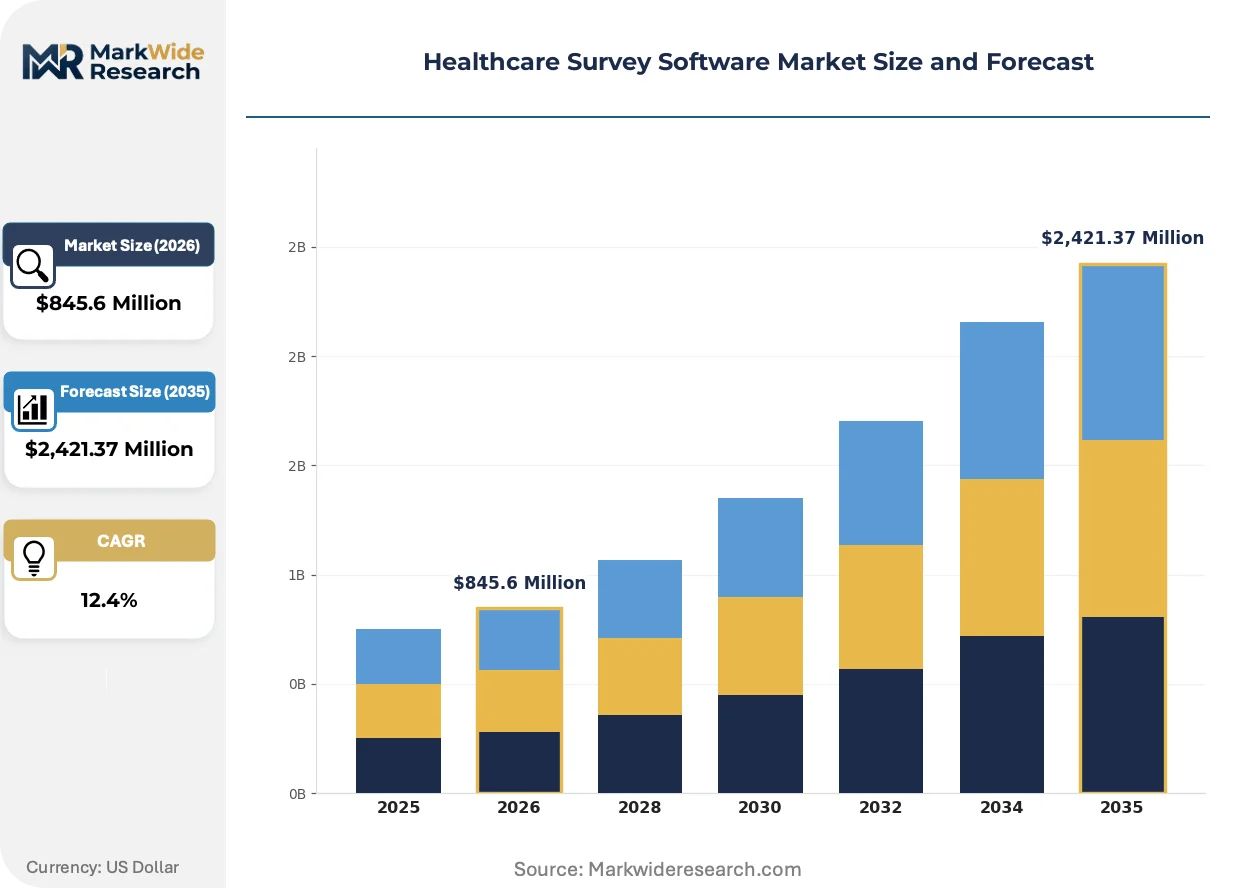
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $2,421.37 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based Solutions, Mobile Apps, Desktop Software, Analytics Tools End User: Hospitals, Clinics, Academic Institutions, Research Organizations Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS Functionality: Data Collection, Reporting Tools, Survey Design, Response Management |
| Companies Covered | Qualtrics, SurveyMonkey, Alchemer, SurveySparrow, QuestionPro, Zoho Survey, SoGoSurvey, Typeform, Voxco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Survey Software Market Trends and Innovations
Artificial intelligence is penetrating survey instrumentation at the scoring layer, forcing vendors to rearchitect platforms for algorithmic transparency and regulatory validation.
Voice-enabled survey capture is converging with ambient clinical intelligence to enable hands-free patient feedback collection during discharge workflows. US health systems deploying smart speaker infrastructure in patient rooms are piloting voice-first survey modalities that bypass literacy barriers. This convergence is compressing the gap between clinical encounter and experience data capture from days to minutes.
EMA's updated Good Clinical Practice guidelines now mandate electronic patient-reported outcome capture for all Phase III oncology trials, eliminating paper-based alternatives. European contract research organizations are retrofitting legacy platforms with ePRO modules to maintain trial eligibility. This regulatory shift disproportionately affects mid-size CROs without in-house validation expertise, driving outsourcing demand.
Subscription-based pricing models are displacing perpetual license structures across US hospital procurement departments. Health system CFOs favor operational expenditure treatment for survey platforms amid capital budget constraints from workforce inflation. This preference shift is most visible in California and Texas IDN consolidations, where multi-year SaaS contracts now dominate RFP evaluations.
Healthcare Survey Software Market Segmentation
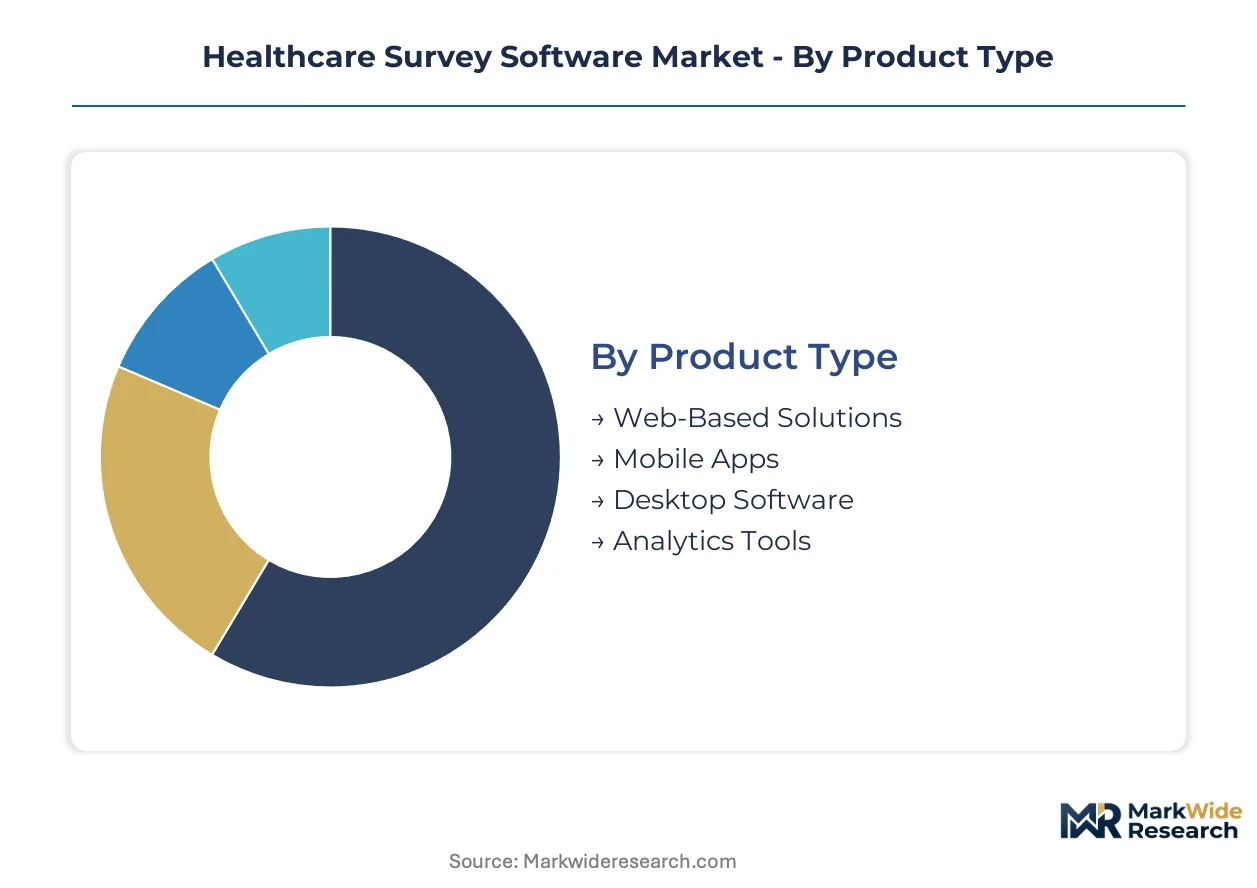
Segmentation in healthcare survey software reveals how procurement patterns diverge between integrated health systems requiring enterprise-grade validation and smaller providers prioritizing cost efficiency. Understanding these fault lines exposes where vendor margins concentrate and where platform architectures must adapt.
Product Type:
Integration depth varies sharply across product architectures, with standalone web platforms dominating multi-site deployments while embedded analytics modules penetrate existing EHR workflows.
- Web-Based Solutions:Browser-accessible platforms deliver HIPAA-compliant survey capture without client-side installation, minimizing IT overhead. Demand concentrates in United States hospital networks consolidating patient experience measurement across dozens of facilities, driven by FDA 21 CFR Part 11 digitization mandates eliminating paper-based alternatives.
- Mobile Apps:Native and progressive web applications enable bedside tablet deployment and SMS-linked post-discharge surveys. German hospital networks expanding point-of-care hardware investments favor these tools for real-time capture during discharge workflows, replacing retrospective mail-based instruments.
- Desktop Software:Legacy on-premise installations persist in research organizations requiring air-gapped environments for sensitive clinical trial data.
- Analytics Tools:Specialized visualization and statistical modules embed within broader platforms or operate as standalone business intelligence layers.
Volume placements concentrate in Web-Based Solutions; the faster expansion belongs to Mobile Apps.
End User:
Customer scale determines pricing architecture, with enterprise health systems absorbing validation costs that mid-market providers reject.
- Hospitals:Acute care facilities with 200+ beds drive the majority of contract value, requiring multi-departmental survey orchestration across inpatient, emergency, and surgical units. Epic and Cerner integration demands dominate procurement specifications, extending sales cycles but locking in long-term relationships.
- Clinics:Outpatient and ambulatory settings prioritize self-service deployment with minimal implementation support. SurveyMonkey and similar mid-market vendors capture this segment through streamlined pricing that converts capital expenditure to operational expenditure.
- Academic Institutions:Medical schools and teaching hospitals blend clinical quality measurement with research protocols, creating hybrid procurement requirements.
- Research Organizations:Contract research organizations and academic medical centers running longitudinal studies demand API extensibility and EMA Good Clinical Practice alignment for Phase III trial eligibility.
Revenue concentration sits with Hospitals; Clinics are gaining share fastest as SaaS pricing penetrates smaller provider networks.
Deployment Model:
Cost structure transformation favors recurring revenue models, though regulatory validation preserves niche demand for controlled on-premise environments.
- Cloud-Based:Multi-tenant architectures with automatic encryption and geographic redundancy now anchor mainstream procurement. California and Texas IDN consolidations favor multi-year cloud contracts converting upfront license fees to predictable operational expenditure.
- SaaS:Subscription tiers with embedded analytics upgrades displace perpetual licenses across United States health system CFO evaluations facing capital budget constraints from workforce inflation.
- On-Premise:Air-gapped installations persist where data residency requirements or internal security policies prohibit third-party hosting.
- Hybrid:Split configurations with sensitive data on-premise and analytics in cloud instances address GDPR cross-border transfer restrictions.
Contract volume flows toward Cloud-Based deployments; SaaS is climbing the fastest as procurement departments standardize subscription evaluation frameworks.
Functionality:
Workflow embedding depth separates commodity survey builders from platforms commanding premium pricing through clinical system integration.
- Data Collection:Core survey engines with branching logic and multi-language support form the baseline capability. HL7 FHIR bidirectional integration with Epic and Cerner distinguishes enterprise-grade offerings from standalone tools.
- Reporting Tools:Real-time dashboards with sub-second query response and role-based access controls anchor quality improvement workflows. FDA audit-trail requirements for immutable records push vendors toward validated infrastructure investments consuming substantial development budgets.
- Survey Design:Drag-and-drop builders with template libraries target mid-market users lacking dedicated research staff.
- Response Management:Automated follow-up protocols and non-response bias correction tools support longitudinal study retention.
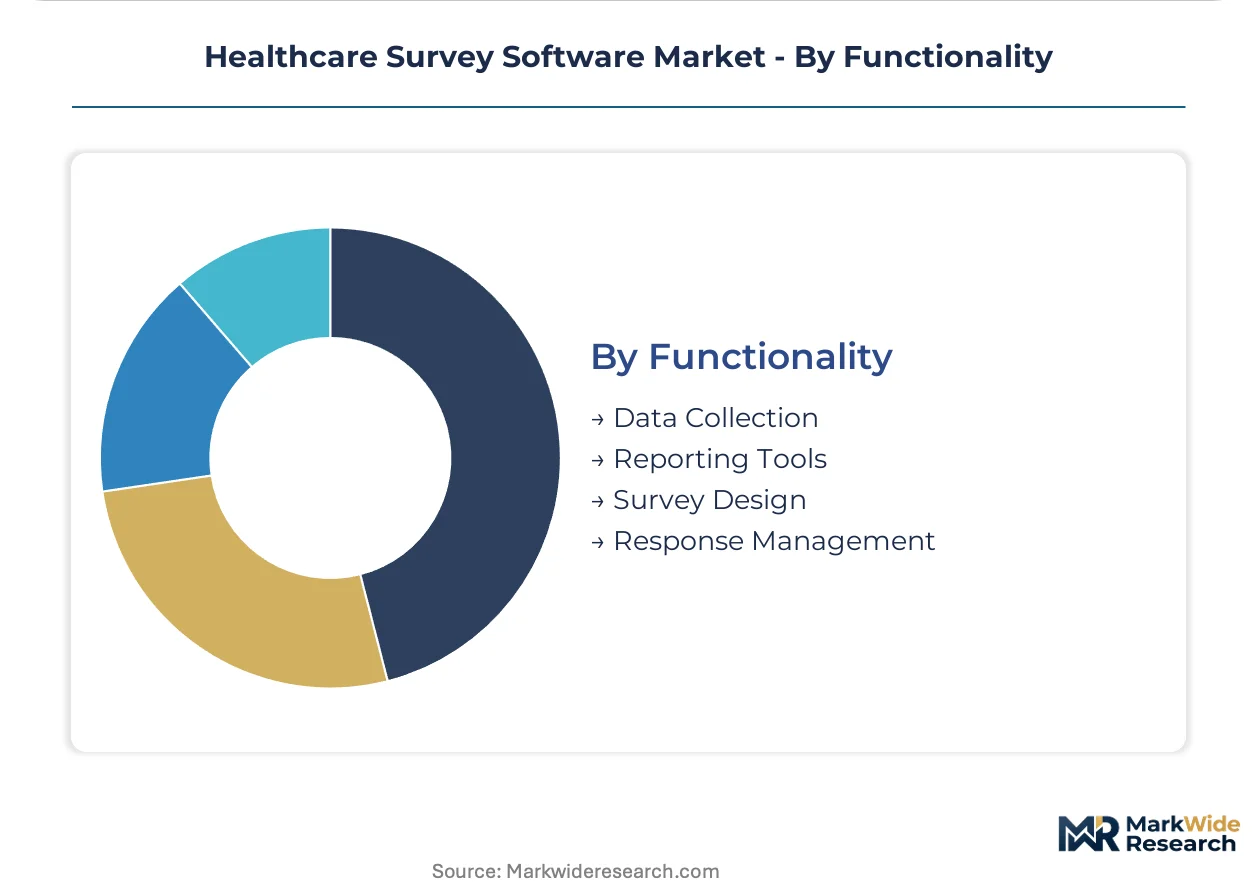
Platform investment concentrates in Data Collection modules; Reporting Tools are expanding most quickly as regulatory validation requirements deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for digital health innovation in Singapore and Tel Aviv are concentrating venture capital flows and vendor development centers for compliant survey platforms.
United States
Hospital network consolidation across California and Texas IDNs is driving multi-year SaaS procurement for patient experience platforms. FDA 21 CFR Part 11 digitization mandates are eliminating paper-based feedback systems in acute care facilities. The Greater Boston medical research corridor anchors demand for EMA-aligned longitudinal study platforms.
Germany
Hospital network centralization is unifying procurement across multi-site systems spanning inpatient and post-acute touchpoints. EMA Good Clinical Practice guidelines and GDPR consent workflows shape product roadmaps for European vendors. The Rhine-Ruhr metropolitan region concentrates CRO demand for validated electronic patient-reported outcome systems.
United Kingdom
NHS digital transformation programs are mandating real-time patient feedback capture across trust networks. GDPR data minimization principles and cross-border transfer restrictions force cloud instance localization. London's health tech cluster drives demand for API-extensible research platforms serving academic medical centers.
India
Hospital chain expansion in Maharashtra and Karnataka is creating demand for cost-efficient cloud survey tools with Hindi and regional language support. CDSCO digital health guidelines are emerging as a compliance reference for domestic software vendors. Hyderabad's pharmaceutical services corridor anchors contract research organization demand for affordable ePRO platforms.
Australia
State health department digitization initiatives in New South Wales and Victoria are standardizing patient experience measurement across public hospital networks. TGA software as a medical device guidance is extending validation requirements to algorithmic survey scoring tools. Melbourne's biomedical research precinct drives academic institution procurement for longitudinal study infrastructure.
Healthcare Survey Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise-grade validation requirements favoring established platforms while self-service tools capture mid-market expansion. The vendor base organizes into three tiers: HIPAA-compliant infrastructure providers, streamlined SaaS generalists, and API-first research specialists. Consolidation pressures concentrate around EHR integration capabilities and regulatory validation expertise. Dominant competitive moves include strategic partnerships with Cerner and Epic for HL7 FHIR connectivity, plus portfolio diversification into AI-assisted sentiment analysis modules.
Within the enterprise infrastructure tier, Qualtrics anchors contracts with large hospital systems through its validated audit-trail architecture. SurveyMonkey occupies a position among streamlined self-service providers targeting cost-conscious clinic networks. Alchemer exemplifies the API-first research specialist archetype serving longitudinal patient study requirements. These three entities collectively represent the strategic positioning spectrum: compliance-heavy enterprise anchoring, mid-market accessibility, and research-grade extensibility.
| Leading Market Players |
|---|
| Qualtrics |
| SurveyMonkey |
| Alchemer |
| SurveySparrow |
| QuestionPro |
| Zoho Survey |
| SoGoSurvey |
| Typeform |
| Voxco |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure spot pricing indices cascade through healthcare survey software supply chains, compressing margins for vendors without geographic redundancy while enabling aggressive SaaS-tiered pricing for hyperscale operators with dedicated server farms.
Pricing Analysis
Short lead-time premiums for validated audit-trail deployments command pricing multiples over standard cloud provisioning, while spot inventory discounts attract mid-market clinic buyers with flexible implementation windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by HIPAA compliance certification depth and Epic integration complexity. Cost compression in the economy tier is intensifying because SurveyMonkey and similar self-service platforms commoditized basic survey functionality. Hospital procurement committees exhibit the lowest price sensitivity due to regulatory validation requirements, while independent physician practices demonstrate acute elasticity to subscription cost increases.
Supply Chain Analysis
Regional distribution centers for healthcare cloud infrastructure concentrate in Northern Virginia, Frankfurt, and Singapore, creating hub-and-spoke patterns for data residency compliance. Software development talent pools concentrate in the United States, Germany, and India, with Hyderabad and Bengaluru anchoring offshore engineering for cost-efficient platform maintenance. Raw material dependencies center on semiconductor components for point-of-care tablet hardware, encryption module licensing, and API gateway services. Single-source vulnerability rests with Epic and Cerner proprietary HL7 FHIR connector specifications that limit vendor switching flexibility. Distribution runs through direct enterprise sales teams for hospital networks and digital marketplaces for clinic segment penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare survey software has become a vertical-integration race into EHR connectivity layers, with vendors pursuing proprietary HL7 FHIR integration depth as the decisive downstream lever for procurement lock-in.
For Market Incumbents: Lock in hospital network relationships through exclusive Cerner and Epic integration partnerships that embed survey platforms within clinical workflow layers. Invest in FDA 21 CFR Part 11 validation infrastructure as a competitive moat against self-service challengers. Pursue backward integration into AI-assisted sentiment analysis modules to capture premium pricing for algorithmic scoring tools. For New Entrants and Emerging Players: Capture the post-acute care white space in United States skilled nursing facilities and home health agencies where enterprise platform penetration remains minimal. Target German hospital network consolidation waves by offering GDPR-native cloud instances with EMA Good Clinical Practice alignment. Lead with API-first positioning to attract contract research organizations running longitudinal patient-reported outcome studies. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size SaaS vendors with validated healthcare infrastructure but constrained sales reach in the United States and German markets. Long-term viability hinges on regulatory certification durability rather than feature velocity. Watch FDA software-as-a-medical-device guidance evolution as the critical inflection signal for algorithmic survey scoring tool valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic and Cerner HL7 FHIR connectivity embeds survey tools within clinical workflows, extending contract duration. |
| Strategic Partnership | Hospital system partnerships with IDN procurement committees convert capital expenditure to multi-year SaaS recurring revenue. |
| Acquisition of Specialist Firm | AI-assisted sentiment analysis capabilities differentiate premium offerings from commoditized survey builders. |
| Geographic Expansion | GDPR-native cloud instances in Frankfurt capture German hospital network consolidation procurement. |
| Product Launch | FDA-validated audit-trail architectures unlock United States acute care facility procurement mandates. |
Research Methodology
Multi-period observation of hospital procurement database entries and GPO contract awards anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement data, hospital procurement databases, and EMA Good Clinical Practice guideline updates. Bottom-up facility-level deployment tracking and top-down vendor revenue triangulation converged on market size estimates.
Input-output matrices mapped deployment model adoption patterns, organization size tiers, vertical specialization depth, and regional regulatory clusters across the projection horizon. CAGRs emerged from segmented growth rate analysis applied to baseline penetration data. Forecast inputs incorporated FDA software-as-a-medical-device guidance trajectory and German hospital network consolidation velocity as healthcare-specific demand drivers.
The model holds under stable regulatory validation timelines and continued IDN consolidation; deviation in FDA 510(k) review period extension or GDPR enforcement intensity would shift vendor competitive positioning. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Global Pharmacy Management System Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
IP-Based Nurse Call System Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Patient Self-Service Kiosks Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Post-Acute Transition Care Coordination Platform Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
Pharma Management Software Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Healthcare IT Consulting Services Market