
 Global Pharmacy Management System Market | 2026-2036
Global Pharmacy Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmacy Management System Market Foresight
Subscription-based software maintenance is consolidating vendor revenue models across pharmacy IT. McKesson Corporation leverages its distribution network to bundle management platforms with supply contracts. Omnicell anchors its position through automated dispensing integration that tightens hospital pharmacy workflows. Epicor Software Corporation specializes in mid-market independent pharmacies with modular deployment options.
A pharmacy management system coordinates prescription processing, inventory tracking, billing workflows, and regulatory reporting through centralized digital infrastructure, typically integrating barcode verification and real-time insurance adjudication to reduce dispensing errors. Cloud-based deployment leads adoption as retail pharmacy chains prioritize remote access and reduced server overhead, while regulatory compliance modules command premium pricing due to DSCSA and EU Falsified Medicines Directive traceability mandates. Prescription processing functions remain the most mature segment, though reporting and analytics capabilities are expanding fastest as pharmacies seek population health insights.
The FDA enforces Drug Supply Chain Security Act serialization requirements that compel pharmacies to upgrade tracking infrastructure, while EMA's Falsified Medicines Directive mandates similar verification standards across European member states. HIPAA in the United States and GDPR in Europe impose parallel data governance obligations that shape system architecture and vendor liability frameworks. Stakeholders must monitor how emerging AI-driven clinical decision support tools trigger new FDA software-as-medical-device classification pathways that could reshape platform certification requirements.
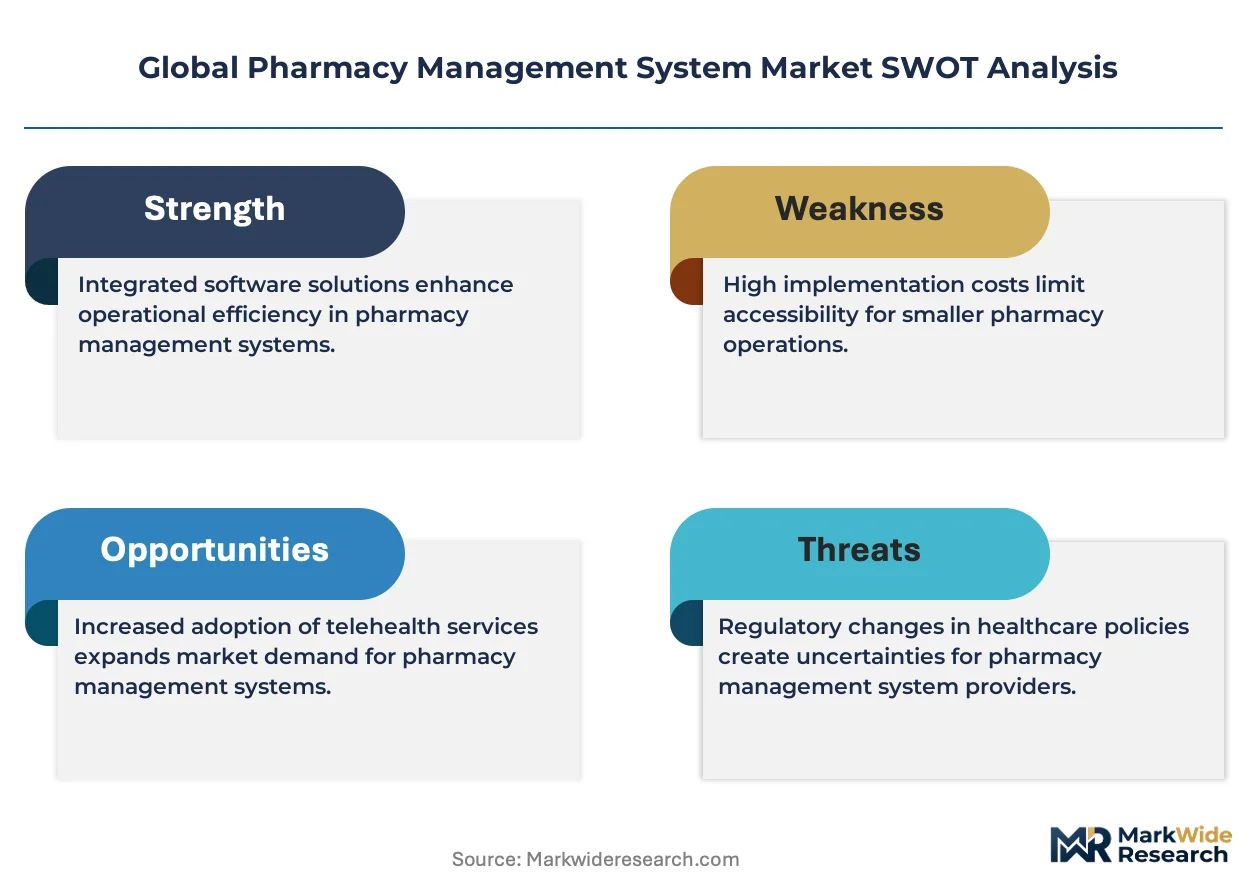
Market Dynamics
Cloud migration is compressing vendor margins while expanding addressable pharmacy segments, as subscription economics replace perpetual license revenue and force incumbents to rebuild service architectures for multi-tenant delivery.
Growth Catalysts
- FDA DSCSA serialization mandates:Pharmacies must deploy track-and-trace infrastructure by 2024-2028 deadlines, forcing system upgrades and creating replacement demand across independent and chain operators.
- Automated dispensing integration:Hospital pharmacies are tightening workflows through robotic cabinet synchronization, driving premium module attach rates for inventory management platforms.
- Japan's aging pharmacy workforce:Labor shortages in Tokyo and Osaka prefectures accelerate automation adoption to maintain dispensing volumes without proportional staff expansion.
Market Restraints
- HIPAA-GDPR compliance friction:Dual jurisdiction data governance obligations impose architectural constraints that slow feature deployment and inflate legal review costs for cross-border vendors.
- Legacy server infrastructure:Rural independent pharmacies retain on-premise Windows-based systems with sunk capital, creating sticky resistance to cloud subscription conversion.
- Specialized pharmacist IT skills:Shortage of pharmacy informatics talent limits successful implementation velocity, particularly for clinical decision support module activation.
Strategic Opportunities
- India's Ayushman Bharat expansion:Government-funded health coverage creates volume pressure on retail pharmacies, generating demand for scalable inventory and billing automation in tier-2 cities.
- AI-driven clinical decision support:Convergence of machine learning algorithms with drug interaction databases enables premium pricing for medication therapy management modules.
- EU Falsified Medicines Directive verification:Remaining member state implementation gaps create upgrade windows for compliance-focused vendors through 2025.
Industry Challenges
- HL7 FHIR integration complexity:Hospital pharmacies face prolonged implementation timelines connecting pharmacy management systems to electronic health record platforms, delaying go-live revenue recognition.
- Cybersecurity certification delays:HITRUST and SOC 2 audit backlogs extend vendor sales cycles as health system procurement committees mandate attestation completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmacy Management System Market |
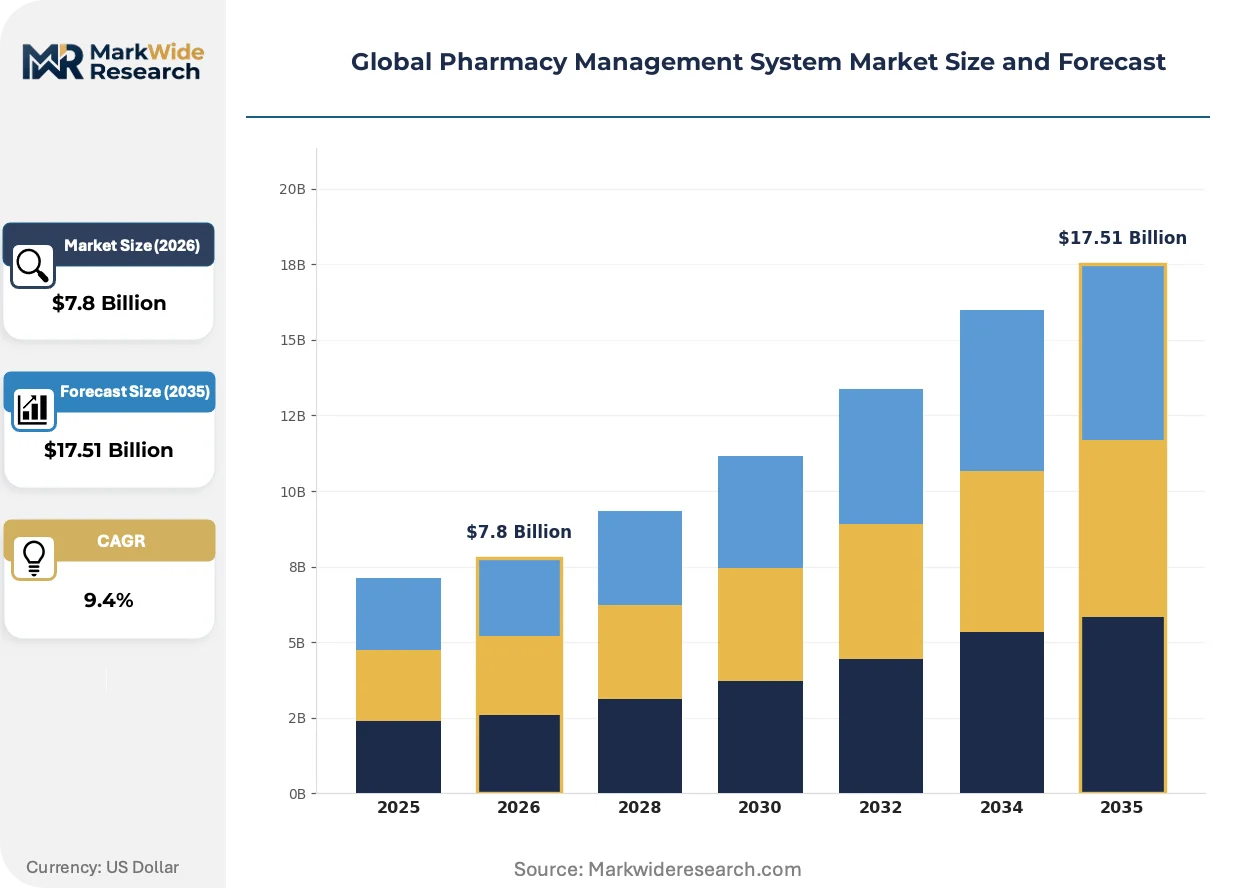
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, Virtual Solution Offering: Inventory Management, Prescription Processing, Billing & Invoicing, Reporting & Analytics, Patient Management, Regulatory Compliance Application: Retail Pharmacies, Hospital Pharmacies, Mail-Order Pharmacies, Long-Term Care Pharmacies, Clinical Pharmacies End User: Pharmacists, Pharmacy Technicians, Healthcare Providers, Insurance Firms, Medication Distributors |
| Companies Covered | Datascan, Epicor Software Corporation, McKesson Corporation, PrimeRx, Omnicell, Cerner Corporation, Liberty Software, SoftWriters, Allscripts Healthcare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmacy Management System Market Shifts & Advancements
Real-time data architectures are displacing batch processing across pharmacy operations, enabling instantaneous inventory visibility and dynamic formulary management that reshape competitive service expectations.
Artificial intelligence is rewriting prescription validation workflows. Retail chains in Germany deploy natural language processing to flag dosing anomalies during data entry, compressing pharmacist verification time by automating routine checks. This capability is enabling same-day prescription fulfillment guarantees that differentiate chain positioning against independent competitors.
EMA's Falsified Medicines Directive verification requirements are mandating barcode-to-cloud authentication at dispensing. European hospital pharmacies must integrate national medicine verification systems by country-specific deadlines, forcing middleware investments that bridge legacy inventory databases with EU central repositories. Germany and France lead compliance spending, while Southern European markets lag in infrastructure readiness.
Subscription unbundling is fragmenting traditional software procurement. Mid-market independent pharmacies in the United States now purchase core dispensing modules separately from analytics and compliance add-ons, reversing historical all-in-one licensing. This pattern concentrates in Texas and Florida metropolitan clusters where pharmacy management cooperatives negotiate modular terms.
Global Pharmacy Management System Market Segmentation
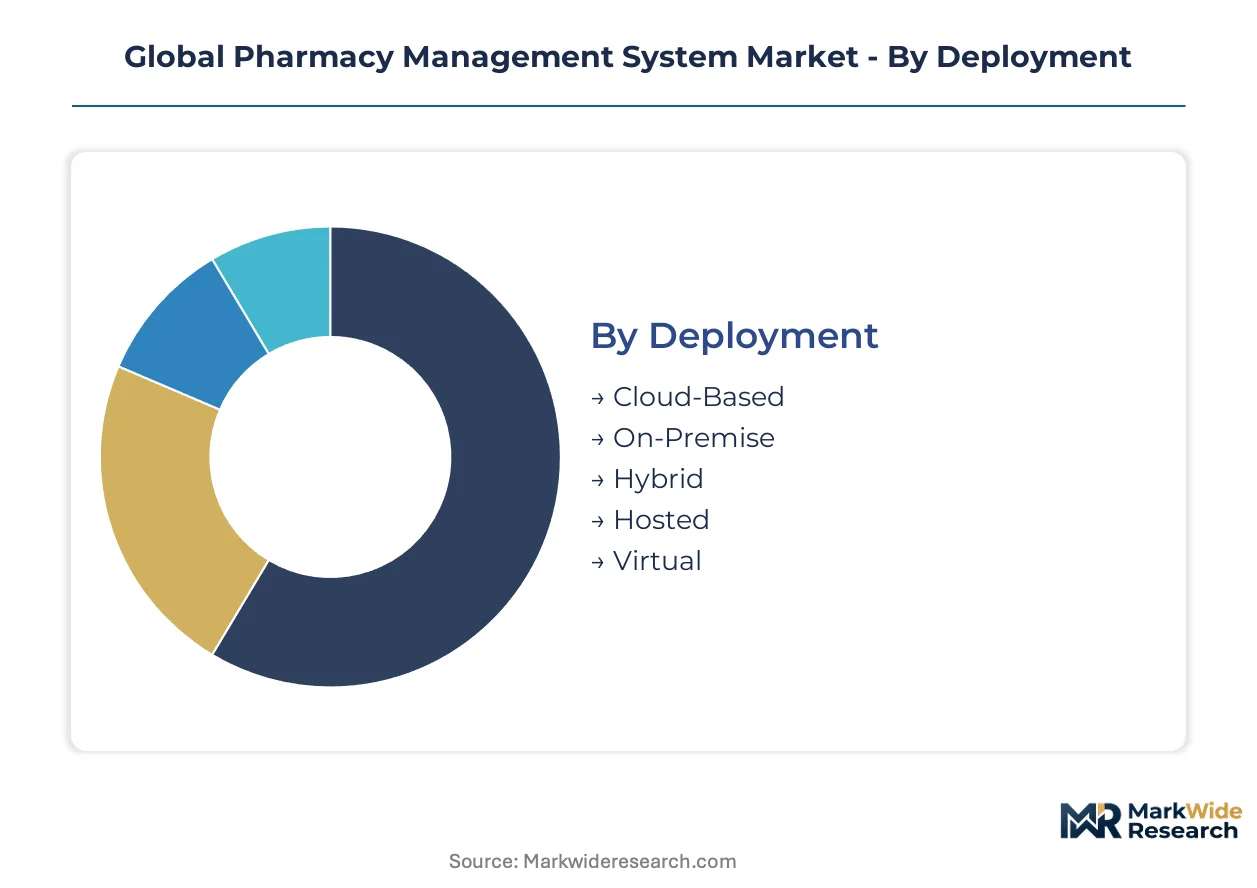
Pharmacy management systems fragment across deployment architectures, functional modules, and care settings. Understanding these divides clarifies where vendor R&D concentrates and which customer profiles drive replacement cycles versus greenfield installations.
Deployment:
Customization versus standardization tension runs deepest here—cloud platforms prioritize multi-tenant efficiency while on-premise installations preserve site-specific configuration control.
- Cloud-Based:Multi-tenant SaaS architectures with automatic FDA DSCSA compliance updates and remote accessibility for retail chains. United States demand concentrates among CVS Health and Walgreens-scale operators seeking centralized formulary governance across thousands of locations.
- On-Premise:Local server installations with full data sovereignty and customizable workflow engines. German hospital pharmacies favor this model under strict BSI IT-Grundschutz cybersecurity frameworks that mandate on-site audit trails.
- Hybrid:Split architectures keeping sensitive patient data local while pushing inventory analytics to cloud endpoints.
- Hosted:Vendor-managed private clouds with dedicated single-tenant infrastructure.
- Virtual:Desktop virtualization delivering centralized application streams to thin-client pharmacy workstations.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations bridging legacy infrastructure with modern analytics demands.
Solution Offering:
Functional depth correlates directly with customer scale—independent pharmacies purchase modules à la carte while health systems negotiate enterprise bundles.
- Inventory Management:Real-time stock visibility with automated reorder points and expiration date tracking. Hospital pharmacies in Japan deploy these modules to offset Tokyo-area staffing shortages through robotic cabinet synchronization.
- Prescription Processing:Core dispensing workflows integrating barcode verification, insurance adjudication, and label generation. This remains the most mature segment with near-universal penetration among United States retail operators.
- Billing & Invoicing:Claims submission engines with denial management and patient copay calculation.
- Reporting & Analytics:Population health dashboards and medication adherence tracking for value-based contracts.
- Patient Management:Medication therapy management documentation and adherence monitoring portals.
- Regulatory Compliance:DSCSA serialization tracking and EU FMD verification with premium pricing attached to audit-ready traceability.
Prescription Processing commands the largest installed base. Reporting & Analytics is climbing the fastest as United States pharmacies seek Medicare Star Rating optimization.
Application:
Workflow intensity and regulatory exposure vary dramatically across care settings, shaping module prioritization and implementation complexity.
- Retail Pharmacies:High-volume dispensing with drive-through integration and loyalty program connectivity. Chains in Florida and Texas metropolitan clusters lead cloud migration to support 24-hour operations.
- Hospital Pharmacies:Complex formulary management with automated dispensing cabinet integration and clinical decision support. German university hospitals drive premium attach rates for compliance modules under EMA traceability mandates.
- Mail-Order Pharmacies:Batch processing workflows with centralized fulfillment and postal logistics integration.
- Long-Term Care Pharmacies:Multi-facility packaging and administration record systems for nursing home networks.
- Clinical Pharmacies:Ambulatory care integration with provider workflow embedding and specialty medication protocols.
Hospital Pharmacies absorb the highest per-site software spend. Retail Pharmacies deliver the steepest expansion trajectory through independent-to-chain consolidation.
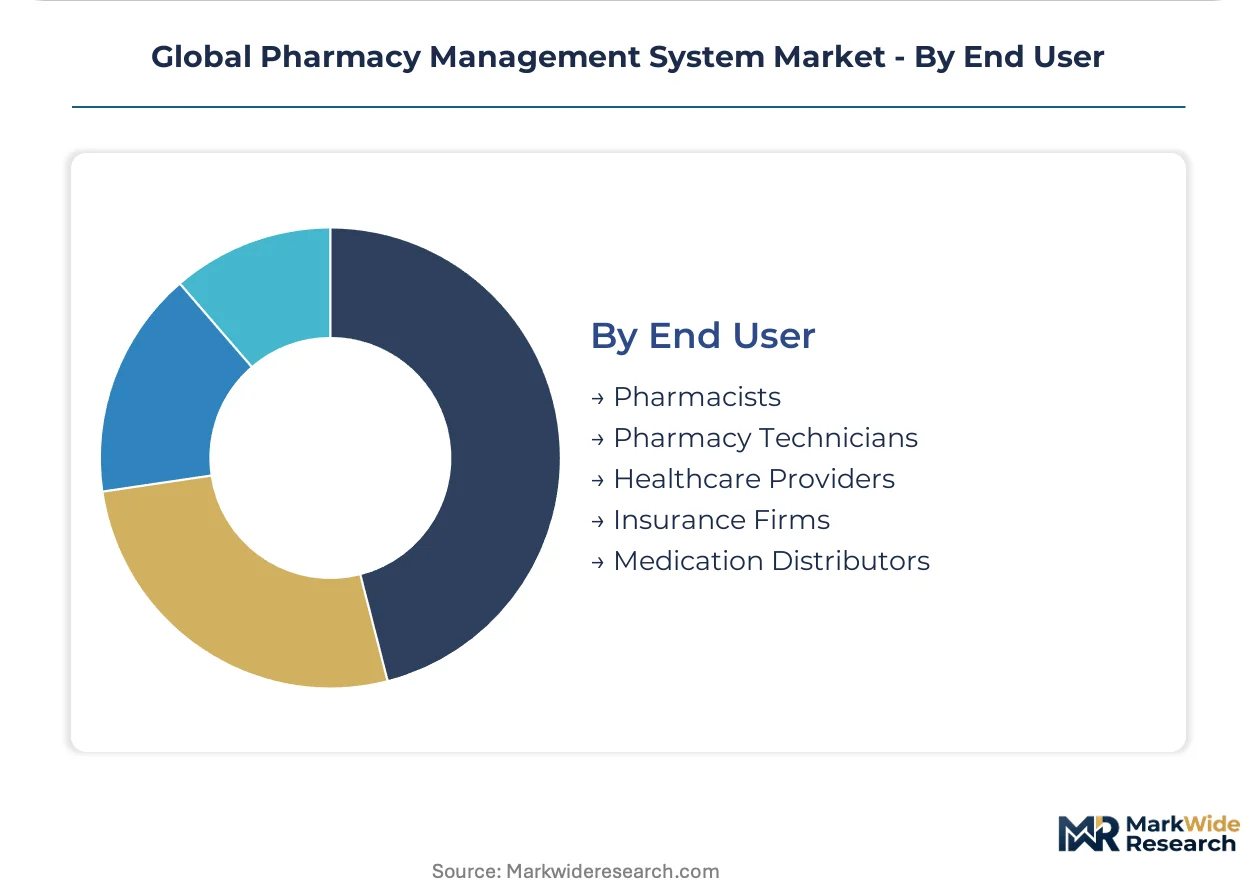
End User:
Role-based permission architectures and interface complexity stratify sharply across user types, from technician data entry to clinical pharmacist decision support.
- Pharmacists:Clinical verification interfaces with drug interaction alerts and therapeutic substitution protocols. United States demand intensifies for medication therapy management documentation tools supporting provider status reimbursement.
- Pharmacy Technicians:Streamlined data entry and inventory handling modules with reduced cognitive load for high-throughput tasks. Japan's aging workforce accelerates automation-friendly interface design for technician roles.
- Healthcare Providers:EHR-embedded prescribing and formulary visibility at the point of care.
- Insurance Firms:Prior authorization integration and real-time benefit verification endpoints.
- Medication Distributors:Supply chain visibility portals for shortage management and allocation protocols.
Pharmacist-facing modules dominate current revenue. Technician-oriented automation tools are gaining share fastest as labor constraints tighten across developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmacy automation intensity exceeds Japan's cloud migration velocity, while India's government-funded coverage expansion creates volume pressure distinct from developed-market replacement cycles. National regulators and demographic pressures shape divergent upgrade timelines across these concentrated markets.
United States
FDA DSCSA serialization deadlines through 2028 compel retail chains and independents alike to replace legacy inventory infrastructure. HIPAA data governance obligations constrain cross-border vendor architectures, inflating legal review costs for European software providers. Texas and Florida metropolitan clusters lead cloud subscription adoption as pharmacy cooperatives negotiate modular procurement terms.
Germany
EMA Falsified Medicines Directive verification requirements drive middleware investments bridging legacy databases with EU central repositories. BSI IT-Grundschutz cybersecurity frameworks mandate on-site audit trails that preserve on-premise installation preferences among university hospitals. Bavarian hospital pharmacies absorb premium module attach rates for compliance-focused traceability systems.
Japan
Tokyo and Osaka prefectures face acute pharmacy workforce aging that accelerates robotic cabinet synchronization and technician-automation interfaces. PMDA consultation frameworks shape clinical decision support module certification pathways. Kanto region retail chains deploy cloud-based dispensing to maintain volume without proportional staff expansion.
India
Ayushman Bharat government-funded health coverage generates demand for scalable inventory and billing automation in tier-2 cities beyond established metro infrastructure. CDSCO traceability guidelines for domestic pharmaceuticals create compliance preparation windows. Maharashtra and Karnataka pharmacy networks modernize rapidly to handle beneficiary volume surges.
Global Pharmacy Management System Market Competitive Landscape
Top-tier vendors anchor enterprise health system contracts, while mid-market specialists serve independent pharmacy cooperatives through modular deployment options. The vendor base stratifies across three functional tiers: distribution-integrated platforms, automated dispensing specialists, and SaaS-native challengers. Consolidation pressure intensifies as subscription economics compress margins and force incumbents toward multi-tenant service rebuilds. Dominant competitive moves include strategic bundling of management platforms with supply contracts and portfolio diversification into clinical decision support modules.
Within the distribution-integrated tier, McKesson Corporation and Omnicell exemplify divergent anchoring strategies—one leveraging supply chain proximity, the other tightening hospital workflows through hardware-software convergence. Epicor Software Corporation occupies a distinct position serving mid-market independents with deployment flexibility that larger health system vendors rarely match. These three company structures represent the archetype spectrum from conglomerate-integrated to specialized modular.
| Leading Market Players |
|---|
| Datascan |
| Epicor Software Corporation |
| McKesson Corporation |
| PrimeRx |
| Omnicell |
| Cerner Corporation |
| Liberty Software |
| SoftWriters |
| Allscripts Healthcare Solutions |
| Others |
Supply & Pricing Matrix
Certification-tier divergence between DSCSA-compliant cloud platforms and legacy on-premise systems manifests in both subscription pricing and supply chain sourcing strategies. Premium pricing attaches to FDA-validated serialization modules while commodity tiers serve rural independents with stripped-down dispensing functionality, with vendor procurement of compliant middleware components tracing distinct geographic pathways.
Pricing Analysis
Capacity additions in India's tier-2 software development centers are reshaping price floors for mid-market SaaS offerings. Three-tier pricing structure across premium, standard, and economy levels dominates, with DSCSA certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from cloud migration compressing perpetual license margins. Independent pharmacy cooperatives in Texas and Florida exhibit highest price sensitivity, while German university hospitals absorb premium module attach rates with minimal negotiation.
Supply Chain Analysis
Domestic-content mandates in India's Ayushman Bharat procurement guidelines are reshaping vendor sourcing for beneficiary-facing modules. Software development capacity concentrates in India, the United States, and Germany, with middleware components drawing from Taiwan semiconductor foundries and South Korean memory suppliers. Supply chain risk centers on single-source vulnerability for FDA-validated serialization engines. Distribution runs through direct enterprise sales for hospital systems and pharmacy cooperative aggregators for independent retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pharmacy Management System Market functions as a stable compounder anchored by regulatory compliance deadlines that mandate systematic upgrade cycles regardless of economic conditions.
For Market Incumbents: Extend cloud-native architectures into hybrid configurations that preserve on-premise data sovereignty for German hospital clients while capturing analytics subscription revenue. Consolidate position through backward integration into automated dispensing hardware, countering SaaS-native challengers threatening mid-market share. DSCSA deadline clustering creates replacement window concentration risk demanding inventory buffer strategies. For New Entrants and Emerging Players: FDA DSCSA serialization mandates in the United States open a window for compliance-focused point solutions that bridge legacy Windows-based systems with cloud traceability repositories. Target India's tier-2 city pharmacy networks modernizing for Ayushman Bharat volume surges, where incumbent footprint remains shallow. Pursue cooperative procurement channel partnerships rather than direct health system sales to bypass extended HITRUST certification cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where subscription economics compress margins below sustainable service delivery thresholds for single-product vendors. Five-to-ten year viability favors platforms with automated dispensing integration or distribution network bundling that creates captive demand. Monitor FDA software-as-medical-device classification pathways for AI-driven clinical decision support as inflection indicator for platform certification cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR connectivity with Epic and Cerner EHR systems accelerates hospital pharmacy procurement cycles. |
| Regulatory Compliance Module Development | FDA DSCSA and EMA FMD validation investments command premium pricing from chain operators facing 2024-2028 deadlines. |
| Strategic Partnership | Pharmacy cooperative alliances in Texas and Florida metropolitan clusters enable modular subscription unbundling. |
| Acquisition of Specialist Firm | Robotic dispensing cabinet vendors provide hardware-software convergence that tightens hospital workflow integration. |
| Geographic Expansion | Maharashtra and Karnataka pharmacy networks in India modernize rapidly to handle Ayushman Bharat beneficiary volumes. |
Research Methodology
Multiple input streams — pharmacy informatics directors, hospital purchasing committee members, software vendor product managers, and regulatory affairs specialists — were reconciled against FDA DSCSA guidance documents, EMA FMD implementation reports, CMS Medicare pharmacy claims data, and vendor SEC filings. Bottom-up installation base estimates across deployment architectures and care settings were triangulated with top-down market sizing derived from healthcare IT expenditure benchmarks.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution offering module, care setting application, and end-user role, with regional regulatory cluster and pharmacy scale tier as cross-cutting variables. CAGRs were derived from installation base growth rates weighted by average revenue per user trajectories, incorporating PMDA consultation timelines for Japan and CDSCO traceability guideline preparation windows for India as industry-specific forecast inputs.
Revisions become necessary when FDA software-as-medical-device reclassification actions, EU AI Act implementation scope determinations, or major cybersecurity framework updates materialize beyond current guidance parameters. Forecasts reflect documented assumptions regarding regulatory deadline adherence and cloud migration velocity among independent pharmacy segments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
E-Prescribing Market
Healthcare IT
ECG Management Systems Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Asia Pacific Healthcare IT Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Healthcare Contact Center Solution Market