
 Clinical Data Analytics Market | 2026-2036
Clinical Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Data Analytics Market Intelligence
Direct enterprise sales channels serving large health systems is fragmenting as cloud-native entrants bypass traditional procurement cycles. IQVIA leverages its real-world evidence repositories to anchor long-term contracts with pharmaceutical sponsors. SAS Institute competes through specialized statistical computing tools that dominate academic medical center workflows. Oracle Corporation extends its database dominance into clinical cloud infrastructure, tightening integration between electronic health records and analytics engines.
Clinical data analytics encompasses the systematic application of statistical algorithms, machine learning models, and natural language processing to structured and unstructured health information, operating across data velocities from batch retrospective studies to real-time patient monitoring streams. Software Solutions and Cloud Services together command the largest revenue share as health systems migrate on-premise data warehouses to HIPAA-compliant cloud environments. Predictive Analytics represents the fastest-expanding application segment, driven by hospital demand for readmission risk scoring and sepsis early warning systems that reduce costly adverse events.
FDA interoperability mandates under the 21st Century Cures Act and HIPAA security rule enforcement by the Office for Civil Rights together elevate compliance costs for vendors while creating barrier-to-entry advantages for established platforms. The ONC's information blocking regulations further compel health data liquidity, reshaping how analytics firms access and monetize clinical datasets. Stakeholders must monitor evolving FDA guidance on artificial intelligence and machine learning-based medical devices, as algorithmic clinical decision support tools face intensifying scrutiny that will determine market access trajectories.
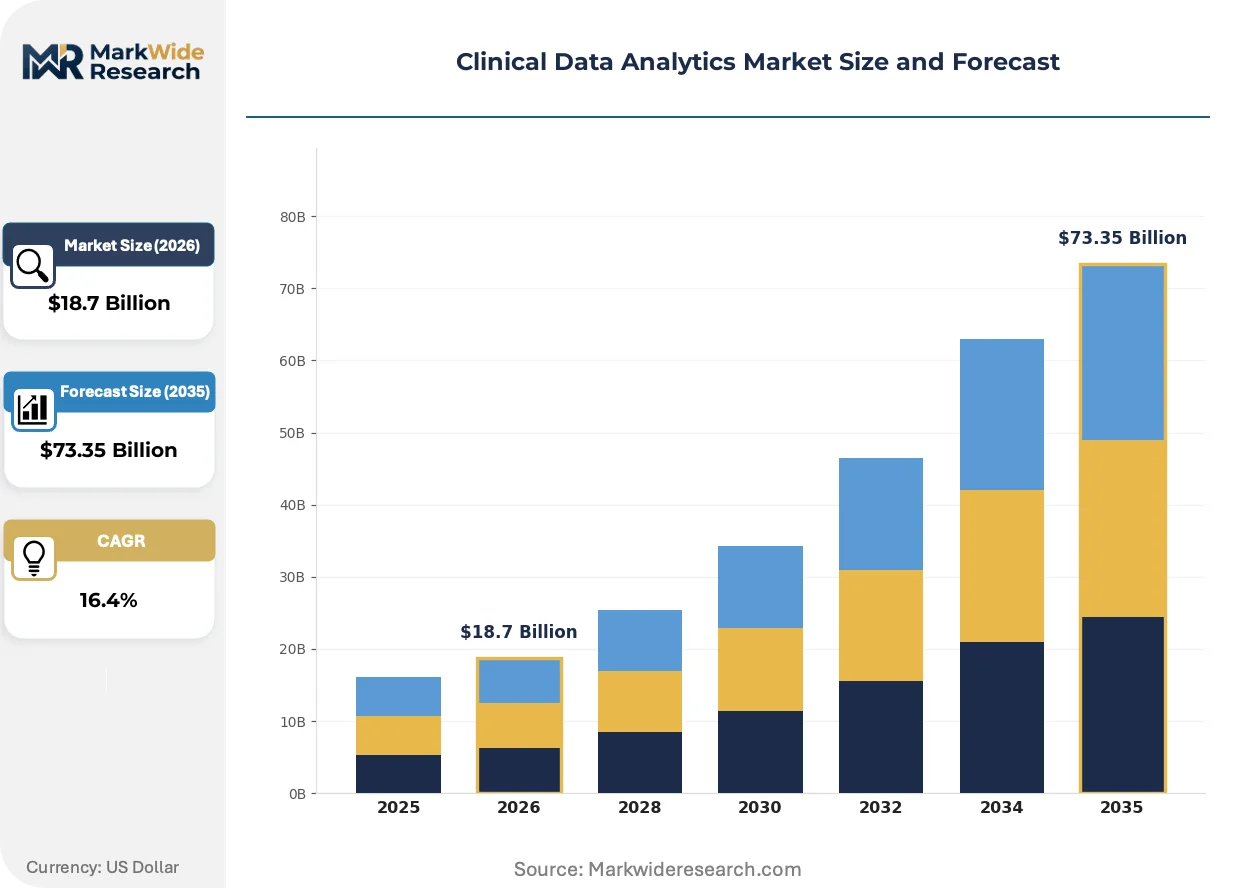
Market Dynamics
FDA's 21st Century Cures Act interoperability mandates are forcing health systems to dismantle data silos, accelerating vendor consolidation around platforms that can ingest real-time streams from disparate EHR architectures.
Growth Catalysts
- Interoperability Mandates:The 21st Century Cures Act compels health data exchange standards that create procurement pull for integrated analytics platforms across US hospital networks.
- Sepsis Early Warning Systems:Hospital demand for predictive algorithms that flag deteriorating patients before clinical decompensation reduces ICU transfers and length-of-stay penalties.
- Cloud Migration:Health systems are retiring on-premise data warehouses for HIPAA-compliant cloud environments that scale compute resources to match research cohort sizes.
Market Restraints
- HIPAA Compliance Costs:Office for Civil Rights enforcement of security rule provisions elevates vendor audit burdens and liability insurance premiums.
- Technical Debt in Legacy EHRs:Proprietary data formats in entrenched electronic health record systems resist standardization, fragmenting analytics workflows.
- Talent Scarcity:Health systems compete with technology firms for data scientists trained in both clinical domain knowledge and machine learning engineering.
Strategic Opportunities
- Real-World Evidence Expansion:Pharmaceutical sponsors seek long-term contracts for post-market surveillance analytics that satisfy FDA safety monitoring requirements.
- Federated Learning Architectures:Privacy-preserving computation across institutional boundaries enables multi-site research without centralizing protected health information.
- Natural Language Processing:Unstructured clinical notes contain diagnostic nuance absent from structured billing codes, creating extraction value for quality measurement vendors.
Industry Challenges
- Algorithmic Bias Auditing:Clinical decision support tools require continuous validation across demographic subgroups to prevent disparate impact in care recommendations.
- Integration Complexity:Analytics platforms must interface with dozens of point-of-care devices and departmental information systems, each with distinct data schemas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Data Analytics Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud Services, Consulting, Analytics Tools End User: Hospitals, Research Institutions, Pharmaceutical Companies, Diagnostic Labs Technology: Machine Learning, Natural Language Processing, Data Visualization, Blockchain Application: Patient Management, Clinical Trials, Real-World Evidence, Predictive Analytics |
| Companies Covered | IQVIA, Optum, SAS Institute, Health Catalyst, Cerner Corporation, IBM Corporation, Oracle Corporation, Allscripts Healthcare Solutions, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Data Analytics Market Strategic Shifts & Innovations
Generative artificial intelligence is compressing documentation burdens while regulatory frameworks scramble to govern algorithmic clinical tools. Three developments are restructuring competitive positioning.
Federated learning architectures are collapsing the traditional trade-off between data privacy and statistical power. Academic medical centers in Germany and the Netherlands are deploying cross-border computation nodes that train models without transferring patient records. This architecture is collapsing the monopoly advantages of institutions with the largest single-site datasets.
The EU AI Act's risk classification system for medical device software is reshaping development roadmaps. High-risk clinical decision support tools now face conformity assessment requirements that extend time-to-market by twelve to eighteen months. European health technology firms are responding by bifurcating product portfolios between assistive documentation tools and autonomous diagnostic algorithms.
Subscription-based platform licensing is displacing perpetual software purchases in health system procurement. Chief information officers in US integrated delivery networks now prioritize vendors offering usage-based pricing that aligns costs to active analyst seats. This shift is most visible in multi-hospital systems consolidating analytics contracts under enterprise master service agreements.
Clinical Data Analytics Market Segmentation
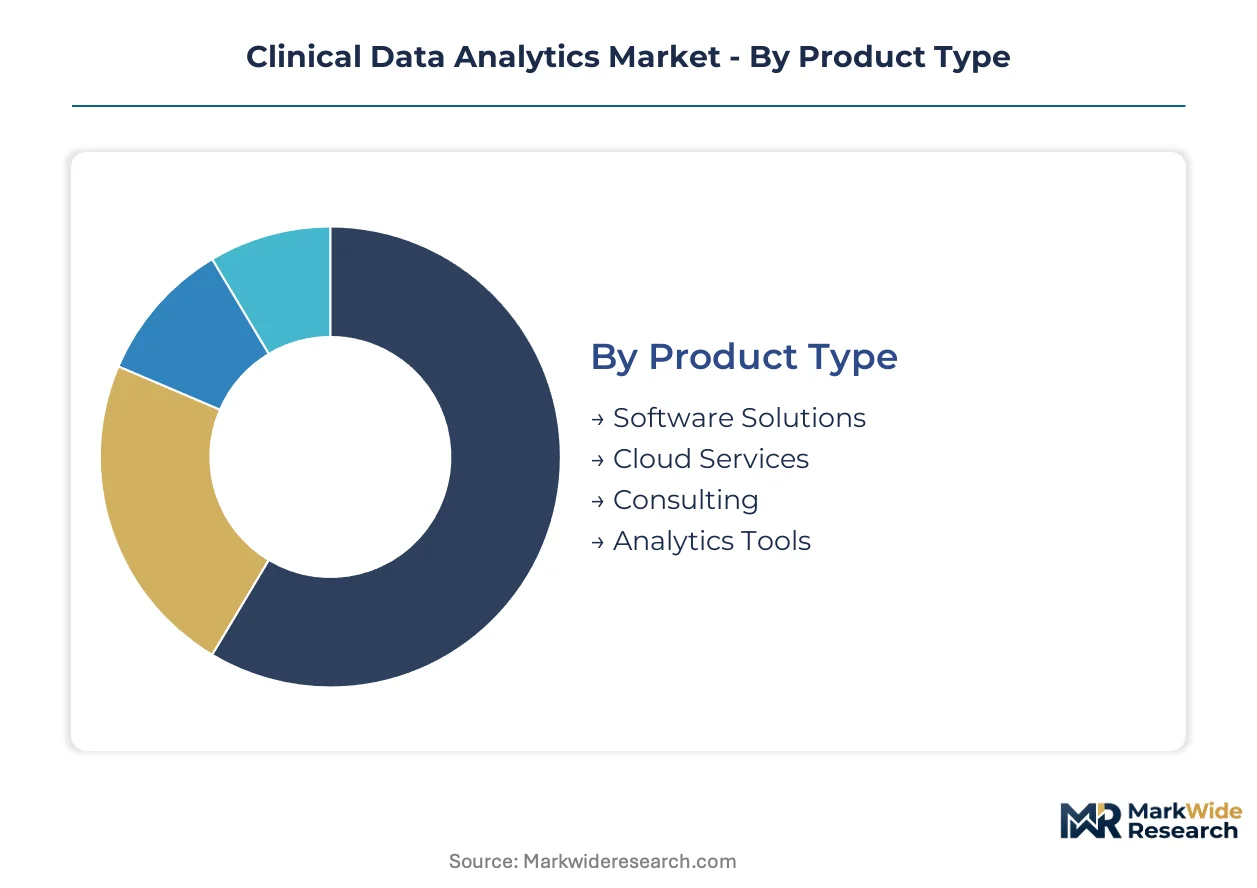
Segmentation in clinical data analytics reveals how procurement patterns diverge across technical maturity and regulatory exposure. Health systems prioritize segments with embedded compliance architectures, while pharmaceutical sponsors gravitate toward modules that accelerate regulatory submission timelines.
Product Type:
After-sales service intensity varies sharply across product categories, with cloud-native platforms demanding continuous security patching and legacy software requiring periodic re-certification.
- Software Solutions:On-premise statistical computing suites anchor workflows at academic medical centers with stringent data residency requirements. Research-intensive hospitals in the United States drive procurement for modules integrating with FDA-validated clinical trial management systems.
- Cloud Services:HIPAA-compliant infrastructure-as-a-service offerings scale compute resources elastically to match research cohort sizes. Pharmaceutical companies expanding real-world evidence programs favor vendors with Business Associate Agreements that streamline Office for Civil Rights audit preparedness.
- Consulting:Implementation partners configure interoperability layers between proprietary EHR architectures and analytics engines.
- Analytics Tools:Point solutions for specific clinical domains—sepsis detection, readmission risk—deploy rapidly with minimal integration overhead.
Software Solutions holds the largest share; momentum sits with Cloud Services.
End User:
Cost tier differentiation separates enterprise-scale deployments from departmental pilots, with procurement authority concentrating in consolidated health system headquarters.
- Hospitals:Integrated delivery networks deploy predictive analytics across emergency departments and intensive care units to reduce CMS penalty exposure. Academic medical centers in Germany and the Netherlands federate learning models across institutional boundaries without centralizing protected health information.
- Pharmaceutical Companies:Sponsors anchor long-term contracts around post-market surveillance platforms that satisfy FDA safety monitoring mandates. Real-world evidence repositories command premium pricing when linked to regulatory submission acceleration.
- Research Institutions:Principal investigators license specialized statistical tools through grant-funded procurement cycles.
- Diagnostic Labs:Molecular testing facilities integrate analytics engines with laboratory information management systems to automate quality control workflows.
Hospitals dominate current procurement volume; pharmaceutical contracts show the steepest expansion trajectory.
Technology:
Application maturity determines deployment risk, with established statistical methods facing lower validation burdens than emerging algorithmic approaches.
- Machine Learning:Supervised learning models trained on retrospective EHR data power readmission risk scores and deterioration indices. FDA guidance on artificial intelligence-based medical devices intensifies scrutiny of algorithmic clinical decision support tools, extending validation timelines for autonomous diagnostic applications.
- Natural Language Processing:Clinical note extraction captures diagnostic nuance absent from structured billing codes. Quality measurement vendors in the United States deploy NLP to automate HEDIS abstraction from unstructured provider documentation.
- Data Visualization:Interactive dashboards translate complex statistical outputs into actionable intelligence for clinical leadership.
- Blockchain:Distributed ledger architectures enable immutable audit trails for multi-site clinical trial data provenance.
Machine Learning commands the largest installed base; Natural Language Processing is gaining share fastest.
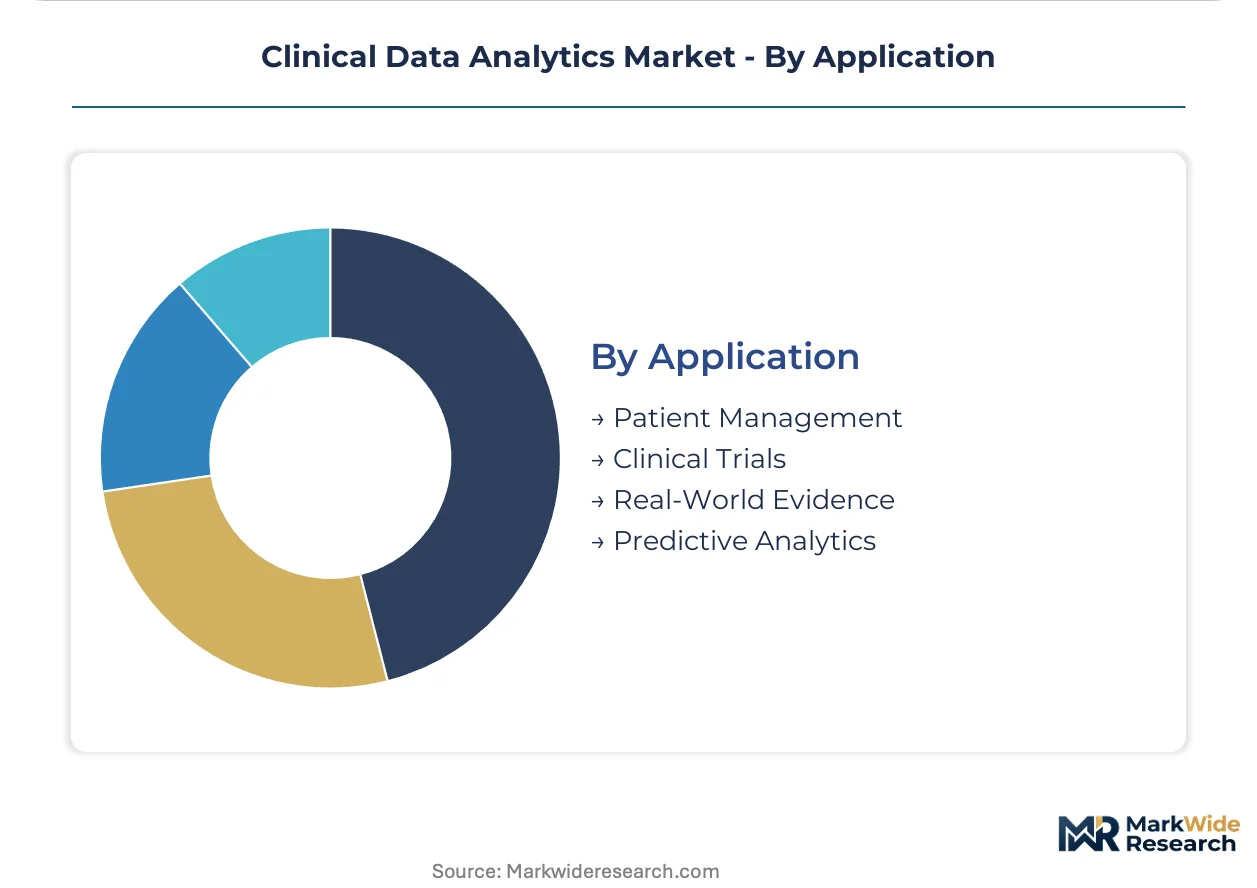
Application:
Customer type specialization separates acute care optimization from research-oriented use cases, with distinct regulatory pathways governing each.
- Predictive Analytics:Real-time algorithms flag patient deterioration before clinical decompensation, reducing ICU transfers and length-of-stay penalties. Hospital demand concentrates in sepsis early warning systems that satisfy Joint Commission core measure requirements.
- Real-World Evidence:Post-market surveillance analytics aggregate disparate data sources to characterize drug safety profiles across heterogeneous populations. EMA's expanded mandate for risk management plans elevates sponsor investment in observational study infrastructure.
- Patient Management:Care coordination platforms integrate analytics with population health registries to stratify chronic disease risk.
- Clinical Trials:Protocol optimization tools simulate enrollment feasibility and site selection using historical performance data.
Predictive Analytics leads by revenue; Real-World Evidence shows the strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in clinical data analytics concentrates in the United States, where health system consolidation drives enterprise-scale contracts, while European markets fragment under divergent national reimbursement schemes and stricter algorithmic governance.
United States
Hospital network mergers in Texas and Florida create procurement leverage for integrated analytics platforms spanning hundreds of facilities. The FDA's 21st Century Cures Act interoperability mandates compel EHR vendors to open data interfaces, accelerating vendor consolidation. The Boston-Cambridge corridor anchors pharmaceutical R&D analytics demand, with sponsors contracting real-world evidence platforms for post-market surveillance.
Germany
Academic medical centers in Berlin and Heidelberg federate learning models across institutional boundaries without centralizing patient records. The EU AI Act's high-risk classification system extends conformity assessment timelines for clinical decision support tools. The Munich-Stuttgart axis hosts precision medicine consortia deploying privacy-preserving computation for multi-site oncology research.
United Kingdom
NHS integrated care systems consolidate analytics procurement under regional headquarters in Manchester and Birmingham. NHS Digital's interoperability standards reshape vendor requirements for population health management platforms. The London-Oxford-Cambridge golden triangle concentrates AI health startups navigating MHRA guidance on software-as-a-medical-device.
China
Hospital groups in Shanghai and Guangzhou deploy predictive analytics for patient flow optimization in overcrowded tertiary facilities. NMPA guidance on AI-enabled medical devices intensifies scrutiny of algorithmic clinical tools, extending registration timelines. The Beijing-Tianjin-Hebei cluster anchors national health data infrastructure projects integrating provincial EHR systems.
India
Corporate hospital chains in Mumbai and Bengaluru license cloud analytics platforms for medical tourism quality accreditation. CDSCO's software medical device regulations create compliance barriers for imported clinical decision support tools. The Hyderabad-Chennai corridor hosts health technology development centers serving Middle Eastern and African hospital networks.
Clinical Data Analytics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying statistical engines and NLP modules. The vendor landscape stratifies between full-stack health cloud providers and point-solution vendors for specific clinical domains. Three archetypes dominate: EHR-anchored platforms extending into analytics, independent analytics pure-plays, and pharmaceutical services firms bundling real-world evidence capabilities. Consolidation accelerates through acquisition of machine learning startups and long-term strategic partnerships with academic medical centers.
Within the pharmaceutical services tier, IQVIA and Optum exemplify data asset monetization through long-term sponsor contracts. SAS Institute occupies a position among statistical computing specialists serving academic research workflows. These three entities represent contrasting strategic postures: IQVIA leverages real-world evidence repositories, Optum integrates payer-provider data advantages, and SAS Institute anchors on methodological rigor in regulated research environments.
| Leading Market Players |
|---|
| IQVIA |
| Optum |
| SAS Institute |
| Health Catalyst |
| Cerner Corporation |
| IBM Corporation |
| Oracle Corporation |
| Allscripts Healthcare Solutions |
| Koninklijke Philips |
| Others |
Cost & Logistics Intelligence
Single-source dependency on HIPAA-compliant cloud infrastructure providers determines both pricing tier spreads and supply chain shape, as health systems face escalating audit burdens that compress margins for vendors lacking established Business Associate Agreements while rewarding platforms with pre-certified security architectures.
Pricing Analysis
Configured-to-order pricing for enterprise analytics deployments commands premiums of 40-60% above standard SaaS tiers, reflecting the integration complexity of proprietary EHR architectures and the compliance overhead of custom data residency requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by after-sales service intensity, with premium tiers embedding dedicated implementation teams and ongoing regulatory update subscriptions. Cost compression in standard tiers is intensifying because cloud-native entrants bypass traditional procurement cycles with usage-based models. Pharmaceutical sponsors show least price sensitivity, prioritizing regulatory submission acceleration over per-seat costs.
Supply Chain Analysis
Upstream feedstock for clinical data analytics platforms centers on computational infrastructure and specialized talent pools rather than physical commodities. Cloud compute capacity concentrates in the United States, Ireland, and Singapore, where hyperscaler data centers anchor HIPAA and GDPR-compliant hosting. The supply chain draws from machine learning engineering labor markets, proprietary EHR data access agreements, and FDA-validated algorithm repositories. Single-source vulnerability sits with narrow pools of data scientists possessing both clinical domain knowledge and statistical computing expertise. Distribution runs through direct enterprise sales teams serving consolidated health system headquarters and long-term strategic partnerships with pharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical data analytics functions as a service-attach opportunity where recurring cloud infrastructure and continuous compliance monitoring layers expand faster than perpetual software licenses, embedding vendors deeper into health system operational workflows.
For Market Incumbents: Insulate platform positions by deepening backward integration into proprietary real-world evidence repositories that pharmaceutical sponsors cannot replicate, while accelerating certification investments for EU AI Act high-risk classification to extend time-to-market advantages over emerging entrants. Channel control through exclusive GPO contracts with consolidated US hospital networks creates switching costs that cloud-native disruptors struggle to overcome. For New Entrants and Emerging Players: Establish a beachhead in federated learning infrastructure for academic medical centers in Germany and the Netherlands, where privacy-preserving computation demand outpaces incumbent platform capabilities. Target mid-tier diagnostic labs in India seeking quality accreditation analytics for medical tourism markets, deploying rapid-deployment sepsis detection modules with minimal EHR integration overhead as the initial go-to-market wedge. For Investors and Strategic Acquirers: FDA guidance on artificial intelligence-based medical devices reshapes the acquisition landscape by extending validation timelines for autonomous diagnostic tools and elevating the value of pre-cleared algorithm portfolios. Five-to-ten-year viability favors targets with embedded clinical workflow integrations rather than point-solution vendors vulnerable to EHR-anchored platform consolidation. Monitor Office for Civil Rights enforcement patterns as the signal to watch for compliance cost inflection that will determine which vendor business models achieve sustainable unit economics.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Infrastructure Deployment | Enables multi-site research without centralizing protected health information, collapsing monopoly advantages of large single-site datasets. |
| EU AI Act Conformity Assessment Investment | Extends time-to-market for high-risk clinical decision support tools, creating barrier-to-entry advantages for pre-certified platforms. |
| Real-World Evidence Repository Expansion | Pharmaceutical sponsors anchor long-term contracts around post-market surveillance platforms satisfying FDA safety monitoring mandates. |
| Natural Language Processing Module Development | Quality measurement vendors automate HEDIS abstraction from unstructured clinical notes, capturing diagnostic nuance absent from billing codes. |
| Hospital System Partnership Consolidation | Integrated delivery networks in Texas and Florida create procurement leverage for enterprise master service agreements spanning hundreds of facilities. |
Research Approach
Cross-validation between primary interviews with health system CIOs, pharmaceutical regulatory affairs leads, biomedical informaticists, and GPO contracts managers anchors the qualitative findings, while secondary validation draws from FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and EHR vendor interoperability disclosures. Bottom-up sizing of individual health system deployments triangulates against top-down pharmaceutical R&D spending allocations to ensure segment-level consistency.
Calibration against historical adoption curves for cloud migration in regulated industries shapes the analytical framework across the analysis window, with segmentation modeling spanning deployment model, organization size, clinical application domain, integration complexity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted penetration rates and vendor-reported seat expansions, incorporating FDA guidance timeline uncertainty and EU AI Act implementation pacing as industry-specific forecast inputs.
Stress conditions across Office for Civil Rights enforcement intensity, hyperscaler pricing volatility, and health system merger momentum were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IQVIA and Optum real-world evidence contract disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Clinical Trials Outsourcing Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Global Clinical Trials Matching Software Market
Clinical Research
Clinical Trials Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
Asia-Pacific Contract Research Organization Market
Clinical Research
Atopic Dermatitis Clinical Trials Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Global Clinical Trial Supply Market
Clinical Research
Real-World Evidence Analytics Market