
 Medical Specimen Tracking System Market | 2026-2036
Medical Specimen Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Specimen Tracking System Market Intelligence
Real-time traceability standards are rotating toward ISO 15189-aligned specimen management protocols across clinical networks. Thermo Fisher Scientific leverages its diagnostic automation portfolio to anchor cloud-integrated tracking deployments in North American health systems. Brooks Automation, Inc. specializes in cryogenic logistics control, sustaining competitive differentiation in biorepository specimen custody chains.
A medical specimen tracking system comprises hardware-software infrastructure that records chain-of-custody data through barcode or RFID tagging, typically operating at temperature ranges from ambient to minus 150 degrees Celsius for biologics. Its primary purpose is eliminating specimen misidentification errors that currently account for a substantial share of laboratory quality failures worldwide. RFID Solutions command premium positioning due to non-line-of-sight readability in high-throughput laboratory environments, while Software Platforms capture recurring revenue through subscription-based middleware integration with LIS and EMR architectures. Diagnostic Laboratories represent the fastest-growing end-user category as outsourced testing volumes expand and accreditation bodies mandate auditable specimen audit trails.
FDA 21 CFR Part 11 electronic record requirements and the EU In Vitro Diagnostic Regulation (IVDR) enforce validated tracking documentation for patient-linked specimens, directly elevating system procurement priority in regulated markets. HIPAA in the United States and GDPR in Europe impose data residency and access-log constraints on cloud-hosted specimen records, favoring hybrid technology deployments with local encryption gateways. Stakeholders must evaluate interoperability readiness against forthcoming EHR connectivity mandates and emerging AI-driven predictive analytics modules that will redefine system specification requirements.
Market Dynamics
Cloud-native specimen tracking architectures are forcing wholesale replacement of on-premise laboratory information systems as health systems consolidate data infrastructure and face escalating cybersecurity mandates.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic record validation requirements for specimen audit trails are accelerating procurement of compliant tracking platforms in US clinical laboratories.
- RFID temperature logging:Cryogenic biorepositories are deploying passive RFID sensors for minus 150 degrees Celsius chain-of-custody verification without line-of-sight scanning constraints.
- Diagnostic laboratory consolidation:Large reference labs in Germany and Japan are mandating centralized specimen tracking to achieve ISO 15189 accreditation across multi-site networks.
Market Restraints
- Capital intensity:Full RFID infrastructure deployment including readers, tags, and middleware integration requires substantial upfront investment that freezes mid-tier hospital budgets.
- Cloud data residency:HIPAA and GDPR constraints on cross-border specimen record storage are fragmenting vendor architectures and inflating compliance engineering costs.
- Legacy LIS lock-in:Proprietary data formats from entrenched laboratory information system vendors create technical friction for third-party tracking middleware adoption.
Strategic Opportunities
- AI predictive analytics:Machine learning modules for specimen transit time forecasting are creating new subscription revenue layers atop core tracking software platforms.
- India laboratory modernization:CDSCO-mandated quality system upgrades for diagnostic chains are opening procurement windows for automated tracking systems in Tier-1 cities.
- Blockchain audit trails:Immutable chain-of-custody documentation is emerging as a competitive differentiator for biorepository custody contracts in precision medicine.
Industry Challenges
- Interoperability engineering:Mapping specimen tracking data flows across disparate EMR, LIS, and biobank management systems demands scarce HL7 FHIR integration specialists.
- Validation timelines:FDA software-as-a-medical-device classification uncertainties are extending commercialization cycles for cloud-hosted tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Specimen Tracking System Market |
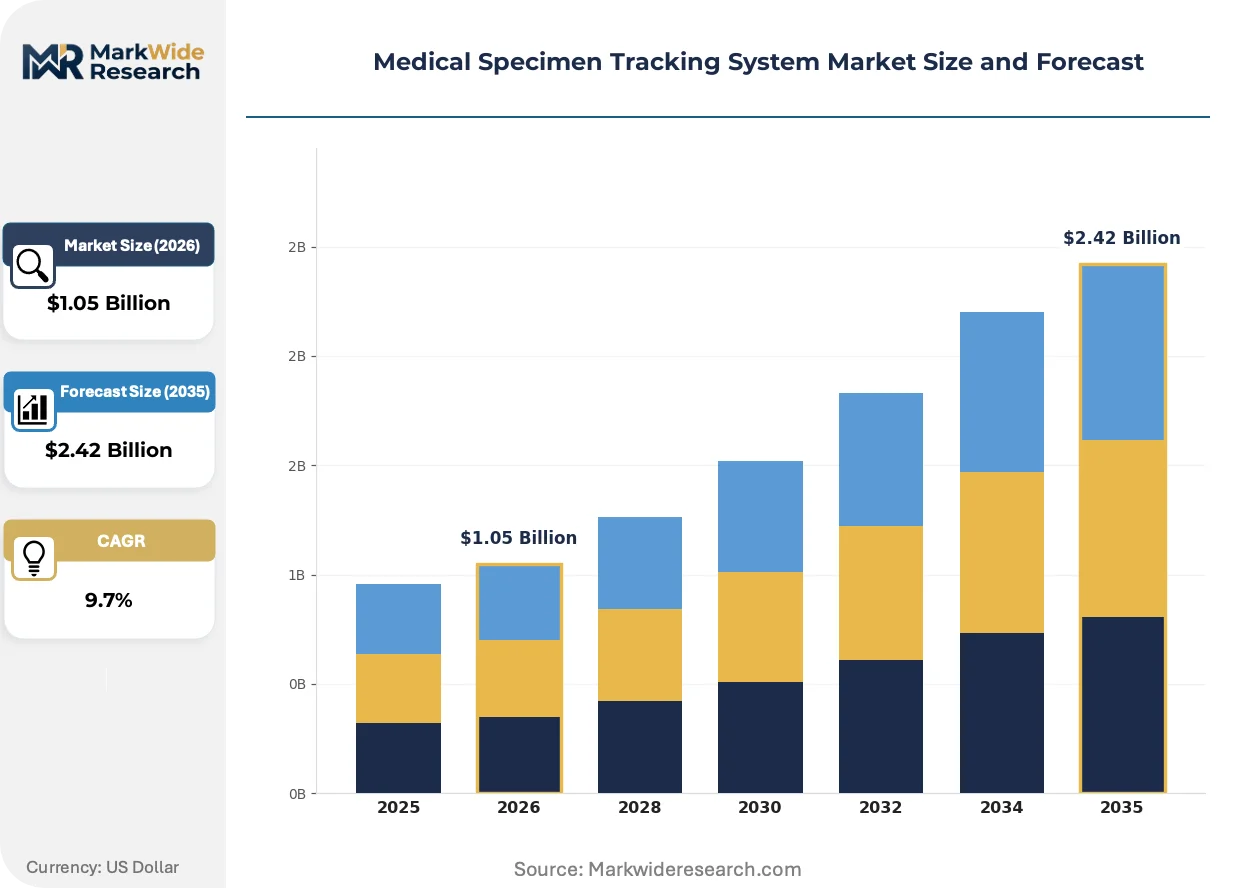
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.42 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barcode Systems, RFID Solutions, Software Platforms, Mobile Applications End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks Technology: Cloud-Based, On-Premises, Hybrid Solutions, Web-Based Interfaces Application: Patient Samples, Blood Samples, Tissue Samples, Fluid Samples |
| Companies Covered | Cryoport Systems, LLC, LabConnect, GAO RFID Inc., Agilent Technologies, Peak Technologies, RMS Omega Technologies, Brooks Automation, Inc., Thermo Fisher Scientific, BioIT Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Specimen Tracking System Market Strategic Shifts & Innovations
Specimen tracking technology is pivoting from passive barcode documentation toward active environmental sensing and predictive logistics, reshaping how laboratories manage biological material integrity across distributed networks.
Passive UHF RFID tags with embedded temperature sensors are displacing traditional barcode-plus-logger combinations in high-throughput clinical laboratories. Major health systems in the United States are deploying these tags for ambient-to-cryogenic specimen monitoring. The displacement is compressing total cost of ownership for automated tracking while eliminating manual temperature logging labor.
EU In Vitro Diagnostic Regulation traceability mandates are forcing specimen tracking system vendors to reengineer audit trail architectures for patient-linked sample documentation. Diagnostic laboratories operating across European member states must demonstrate validated chain-of-custody records for regulatory inspections. Germany and France are witnessing accelerated procurement of IVDR-compliant platforms as notified body certification deadlines approach.
Subscription-based middleware pricing is replacing perpetual license models as health systems prioritize operational expenditure flexibility over capital deployment. Diagnostic laboratory chains in Japan are negotiating multi-year service agreements that bundle software, hardware, and compliance support. This shift is visible most acutely among outsourced testing providers seeking to align tracking costs with specimen volume fluctuations.
Medical Specimen Tracking System Market Segmentation
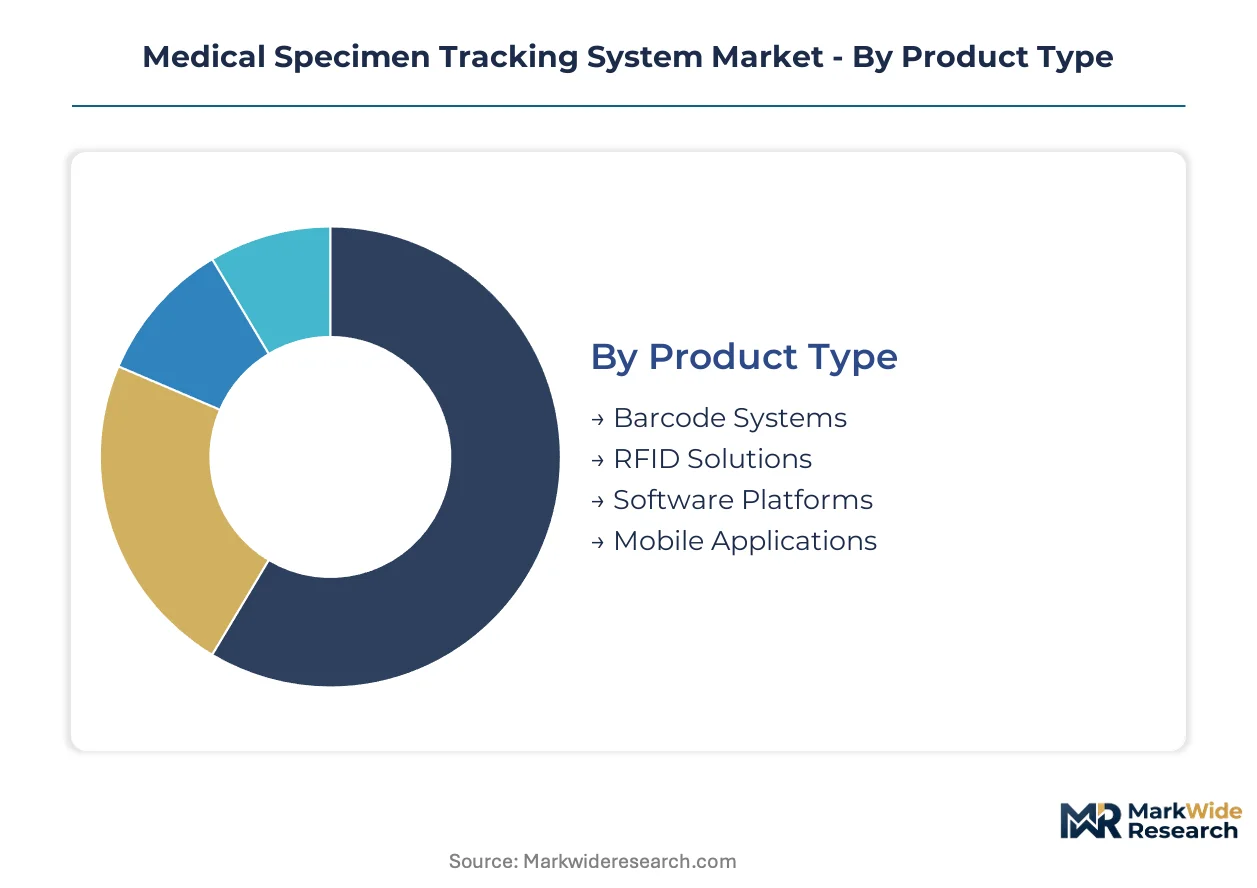
Segmentation reveals how procurement priorities diverge across specimen handling workflows. Tracking infrastructure investments cluster around technologies that eliminate manual reconciliation errors while satisfying chain-of-custody audit requirements for regulated biological materials.
Product Type:
Margin pools concentrate in integrated hardware-software bundles that command recurring subscription revenue and reduce total cost of ownership through automation.
- Barcode Systems:Linear and 2D symbology readers dominate mid-tier hospital laboratories seeking proven reliability at moderate capital outlay. Demand concentrates in German diagnostic networks modernizing under IVDR traceability mandates where barcode-plus-logger combinations satisfy initial compliance requirements.
- RFID Solutions:Passive UHF tags with embedded temperature sensors enable non-line-of-sight reading across cryogenic biorepositories. United States health systems deploy these for minus 150 degrees Celsius specimen monitoring, eliminating manual scanning labor while maintaining FDA 21 CFR Part 11 audit trails.
- Software Platforms:Middleware integrating laboratory information systems with enterprise resource planning architectures.
- Mobile Applications:Smartphone-based specimen receipt and transit confirmation tools for courier networks.
The dominant share belongs to Barcode Systems, while RFID Solutions is closing the gap fastest.
End User:
Customer concentration patterns reflect where specimen throughput volumes justify automated infrastructure deployment against labor cost savings.
- Hospitals:Acute care networks with centralized laboratory services anchor initial tracking system procurement. United States health systems consolidate multi-site specimen logistics under single platform architectures to achieve HIPAA-compliant audit standardization.
- Diagnostic Laboratories:Reference testing chains with high daily specimen volumes drive demand for throughput-optimized automation. Outsourced providers in Japan negotiate multi-year service agreements bundling hardware, software, and compliance support to align costs with volume fluctuations.
- Research Institutions:Academic medical centers and contract research organizations managing longitudinal biobank collections.
- Blood Banks:Transfusion services requiring temperature-verified chain-of-custody for platelet and plasma units.
Diagnostic Laboratories command the largest revenue pool, with Research Institutions expanding most quickly as precision medicine biorepositories multiply.
Technology:
Architecture decisions hinge on data residency constraints and cybersecurity maturity rather than pure functional capability.
- Cloud-Based:Vendor-hosted platforms with subscription pricing reduce capital deployment requirements. HIPAA and GDPR constraints on cross-border specimen record storage fragment vendor architectures, inflating compliance engineering costs for multi-national laboratory chains.
- On-Premises:Locally installed software with perpetual licensing maintains data sovereignty for security-sensitive institutions. German university hospitals favor these deployments to satisfy regional data protection authority requirements for patient-linked genetic material.
- Hybrid Solutions:Local encryption gateways with cloud analytics processing.
- Web-Based Interfaces:Browser-accessible dashboards for remote specimen status monitoring.
Cloud-Based architectures lead current procurement, though Hybrid Solutions are gaining share fastest among European laboratories navigating GDPR complexity.
Application:
Specimen category determines environmental monitoring specifications and regulatory documentation intensity.
- Patient Samples:Diagnostic specimens requiring patient identity linkage and clinical result correlation. United States clinical laboratories prioritize these workflows under FDA enforcement of 21 CFR Part 11 electronic record validation for specimen audit trails.
- Blood Samples:Whole blood, serum, and plasma units with temperature-sensitive stability windows. Japanese blood services deploy automated tracking to maintain cold chain integrity across collection-to-processing intervals.
- Tissue Samples:Surgical pathology specimens with formalin fixation tracking requirements.
- Fluid Samples:Cerebrospinal, amniotic, and other body fluids with limited stability durations.
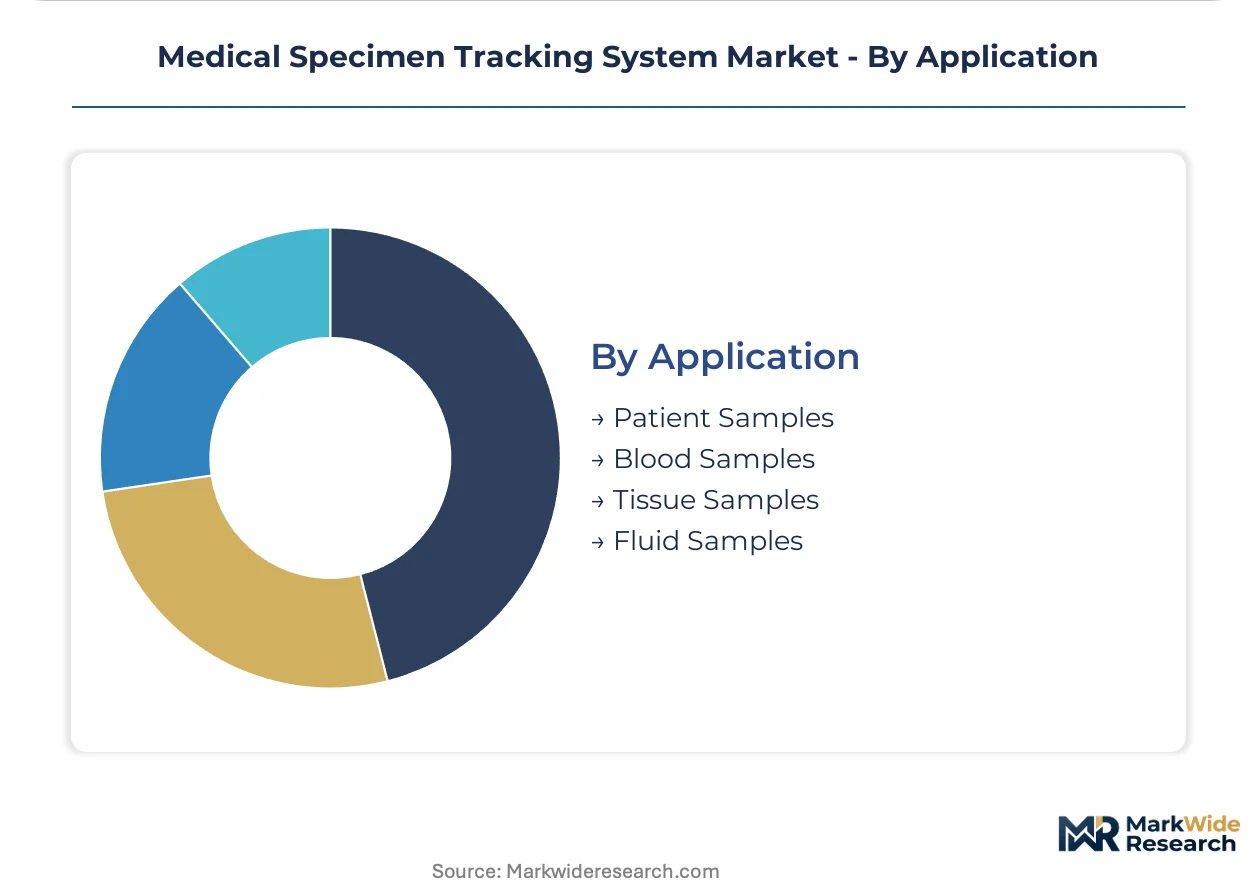
Patient Samples represent the largest application segment, while Tissue Samples show the steepest expansion trajectory as cancer biobanking accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor deployment concentrates in the United States, Germany, and Japan where laboratory infrastructure modernization intersects with stringent regulatory mandates for specimen traceability.
United States
Hospital consolidation and reference laboratory expansion drive procurement of cloud-integrated tracking platforms. FDA 21 CFR Part 11 enforcement mandates validated electronic audit trails for patient-linked specimens, elevating compliance-engineered systems in procurement evaluations. The Boston-Cambridge biotech corridor anchors cryogenic biorepository deployments for precision medicine research.
Germany
Diagnostic laboratory chains modernize under EU IVDR traceability requirements that demand auditable chain-of-custody documentation. ISO 15189 accreditation mandates across multi-site networks accelerate centralized specimen tracking procurement. The Rhine-Ruhr metropolitan region hosts dense clusters of reference laboratories deploying RFID-enabled temperature monitoring for high-throughput workflows.
Japan
Outsourced testing volume expansion and blood service modernization create demand for subscription-based tracking middleware. PMDA quality system requirements and METI digital health initiatives favor cloud-native architectures with local encryption gateways. The Kanto region surrounding Tokyo concentrates diagnostic laboratory chain headquarters negotiating multi-year service agreements.
India
CDSCO-mandated quality system upgrades for diagnostic chains open procurement windows in Tier-1 cities. National accreditation body requirements for laboratory quality management drive initial barcode-plus-logger deployments. Mumbai and Bengaluru anchor diagnostic network modernization as private laboratory chains expand specimen processing capacity.
United Kingdom
NHS pathology network consolidation prioritizes interoperable tracking systems across merged laboratory services. GDPR data residency constraints favor hybrid cloud deployments with local specimen record storage. The Oxford-Cambridge-London golden triangle concentrates biorepository infrastructure investment for genomic medicine initiatives.
Medical Specimen Tracking System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the specimen tracking ecosystem. The market exhibits tiered concentration with integrated diagnostic automation vendors occupying premium positions while specialized RFID hardware providers compete on deployment flexibility. Three archetypes dominate: full-stack laboratory automation suppliers, cryogenic logistics specialists, and middleware-focused software vendors. Competitive maneuvering centers on strategic partnerships with LIS vendors and geographic expansion through reference laboratory chain contracts.
Within the full-stack automation tier, Thermo Fisher Scientific and Agilent Technologies occupy positions representing end-to-end diagnostic infrastructure integration. Brooks Automation, Inc. exemplifies the cryogenic logistics specialist archetype, anchoring competitive differentiation in biorepository custody chains where temperature-verified chain-of-custody commands premium positioning. These three companies collectively illustrate how vendor strategy diverges between horizontal platform breadth and vertical workflow depth.
| Leading Market Players |
|---|
| Cryoport Systems, LLC |
| LabConnect |
| GAO RFID Inc. |
| Agilent Technologies |
| Peak Technologies |
| RMS Omega Technologies |
| Brooks Automation, Inc. |
| Thermo Fisher Scientific |
| BioIT Solutions |
| Others |
Cost & Logistics Intelligence
Passive UHF RFID tags with embedded temperature sensors are displacing traditional barcode-plus-logger combinations across clinical laboratories, simultaneously shifting supply geography toward East Asian semiconductor fabrication hubs and compressing hardware pricing tiers through economies of scale in sensor manufacturing.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across the Medical Specimen Tracking System Market, separating validated cloud-hosted platforms with compliance engineering from basic barcode systems lacking electronic audit trail capabilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling, with diagnostic laboratory chains in Japan negotiating multi-year subscription agreements that align costs with specimen volume fluctuations. Cost compression in mid-tier hospital budgets is intensifying because capital intensity for full RFID infrastructure deployment freezes procurement decisions. Reference laboratories demonstrate the lowest price sensitivity due to ISO 15189 accreditation mandates, while mid-tier acute care networks exhibit highest sensitivity to upfront hardware expenditure.
Supply Chain Analysis
Inventory lead times for passive UHF RFID tags with cryogenic-rated temperature sensors extend six to eight months due to concentrated semiconductor fabrication capacity in Taiwan, South Korea, and China. Component sourcing draws from specialized substrate manufacturers in Germany for cryogenic adhesive formulations and Japanese precision sensor foundries for minus 150 degrees Celsius operational ratings. Single-source vulnerability concentrates in UHF chip fabrication where three suppliers dominate global medical-grade tag production. Distribution runs through laboratory automation integrators who bundle hardware procurement with middleware deployment services, creating channel control points that influence final system pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among consolidated diagnostic laboratory chains in Germany and Japan, fragmenting vendor pricing leverage as multi-site networks negotiate enterprise-wide platform contracts.
For Market Incumbents: Secure reference laboratory chain contracts in the Kanto and Rhine-Ruhr regions before IVDR and PMDA certification deadlines harden procurement specifications. Defend against cloud-native middleware entrants by embedding AI predictive analytics modules that create switching costs through accumulated specimen transit data. Prioritize HL7 FHIR integration specialist recruitment to address interoperability engineering scarcity that delays third-party tracking middleware adoption. For New Entrants and Emerging Players: Anchor in India's Tier-1 city diagnostic network modernization where CDSCO-mandated quality system upgrades outpace incumbent vendor deployment capacity. Target biorepository custody contracts in the Boston-Cambridge precision medicine corridor where blockchain audit trail capabilities command premium positioning against established cryogenic logistics providers. Pursue smartphone-based mobile application deployment for courier networks as the lowest-capital entry vector into specimen tracking workflows. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed laboratory information system vendors seeking diagnostic automation tuck-ins to complete platform breadth. Five-to-ten year viability hinges on cloud-native architecture migration completion before FDA software-as-a-medical-device classification uncertainties resolve. Monitor FDA validation timeline announcements as the inflection signal distinguishing compliant platform valuations from stranded legacy system investments.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables HIPAA-compliant subscription pricing for US health systems consolidating data infrastructure. |
| RFID Temperature Sensor Integration | Eliminates manual scanning labor in Brooks Automation cryogenic biorepository deployments. |
| HL7 FHIR Interoperability Certification | Addresses scarcity of integration specialists mapping specimen data across EMR and LIS architectures. |
| Blockchain Audit Trail Development | Creates competitive differentiation for biorepository custody contracts in precision medicine research. |
| AI Predictive Analytics Module Launch | Generates recurring subscription revenue layers atop core tracking software platforms in Japan. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with laboratory directors, biomedical engineers, GPO contracts managers, and diagnostic chain procurement leads. Secondary validation drew from FDA 510(k) filings, EU IVDR notified body certification databases, CMS Medicare laboratory payment data, and hospital procurement system records. Bottom-up triangulation across installed base estimates and top-down validation against diagnostic laboratory capital expenditure disclosures anchored volume and value projections.
Across the analysis window, forecasts segment by product type, end user, deployment technology, and specimen application category. CAGRs were derived from logistic diffusion modeling of automated tracking adoption rates against regulatory compliance deadline schedules. Cryogenic biorepository expansion trajectories and cloud platform subscription renewal rates provided industry-specific forecast inputs.
Material uncertainties — FDA software-as-a-medical-device classification resolutions, GDPR data residency enforcement variations, and semiconductor supply chain disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory timeline adherence and health system consolidation continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Veterinary Dental Software Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
E-Prescribing Market
Healthcare IT
Operating Room Software Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Interactive Patient Care Systems Market
Healthcare IT
High-Value Healthcare Asset Tracking and Recovery Platforms Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Global Accountable Care Solutions Market