
 Patient Access Solutions Market | 2026-2036
Patient Access Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Access Solutions Market Intelligence
Platform licensing revenue is tilting toward cloud-native eligibility and prior authorization engines as health systems abandon legacy bolt-on modules. Epic Systems Corporation leverages its dominant EHR footprint to embed access workflows directly into clinical documentation streams. Oracle sustains competitive pressure through Cerner-derived provider-payer data exchanges that unify enrollment and benefits verification. McKesson Corporation anchors its position via RelayHealth connectivity layers that span pharmacy, provider, and payer endpoints.
Patient access solutions encompass software platforms and services that automate insurance eligibility confirmation, prior authorization submission, patient financial enrollment, and benefits verification across healthcare encounters. These systems integrate EDI transactions, real-time API connections to payer databases, and rules engines that match clinical orders to medical necessity criteria, reducing administrative denials and accelerating revenue capture. Cloud-based delivery mode leads installed growth as health systems prioritize API-first architectures that scale across multi-facility networks without on-premise maintenance burdens. AI Integration within the technology segment attracts the fastest capability investment, particularly natural language processing tools that extract prior authorization requirements from unstructured payer policies. Pharmaceutical Companies as an end-user category represents an emerging margin pool as manufacturers fund access platforms to navigate specialty drug channel complexity and patient assistance program enrollment.
FDA 21st Century Cures Act information blocking enforcement and CMS interoperability mandates shape product roadmaps by requiring standardized API access to patient data and prior authorization decisions. HIPAA transaction code sets and state-level surprise billing regulations further dictate workflow automation requirements for out-of-network eligibility transparency. Stakeholders must monitor evolving state Medicaid agency procurement patterns and federal prior authorization standardization timelines to calibrate platform investment priorities.
Market Dynamics
Payer-provider data friction is compressing revenue cycle timelines and forcing health systems toward real-time eligibility engines that embed directly into clinical workflows. This structural pressure eliminates batch-processing delays that previously consumed 72-hour windows.
Growth Catalysts
- CMS Prior Authorization Rulemaking:Federal mandates for electronic prior authorization APIs create procurement urgency among hospital systems seeking compliance deadlines. Health IT budgets reallocate toward automated submission platforms.
- Cloud-native architecture migration:Health systems abandon on-premise EDI gateways for API-first platforms that scale across multi-facility networks without infrastructure replication costs.
- Specialty pharmaceutical channel complexity:Biologics manufacturers fund patient access platforms to navigate hub enrollment, copay assistance, and benefits verification for high-cost therapies.
Market Restraints
- Payer API fragmentation:Thousands of distinct payer endpoints require custom integration mappings that inflate implementation timelines and technical debt for platform vendors.
- HIPAA transaction standard rigidity:X12 EDI formats constrain real-time data exchange flexibility, forcing expensive translation layers between modern REST APIs and legacy batch systems.
- Skilled health IT labor scarcity:Shortages of EHR integration specialists and FHIR developers extend deployment cycles and elevate professional services costs.
Strategic Opportunities
- FDA 21st Century Cures Act enforcement:Information blocking penalties accelerate demand for interoperable patient access platforms that surface financial data alongside clinical records.
- AI-powered policy extraction:Natural language processing tools that parse unstructured payer medical necessity criteria represent unpenetrated capability territory for prior authorization automation.
- Pharmaceutical manufacturer direct contracting:Drug companies bypass traditional hub vendors to license white-label patient access platforms for specialty therapy launches.
Industry Challenges
- Legacy EHR integration complexity:Health systems running decade-old Epic or Cerner instances require costly middleware to connect modern cloud eligibility engines to rigid data architectures.
- State Medicaid variability:Fifty distinct prior authorization formularies and submission protocols force platform vendors to maintain jurisdiction-specific rules engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Access Solutions Market |
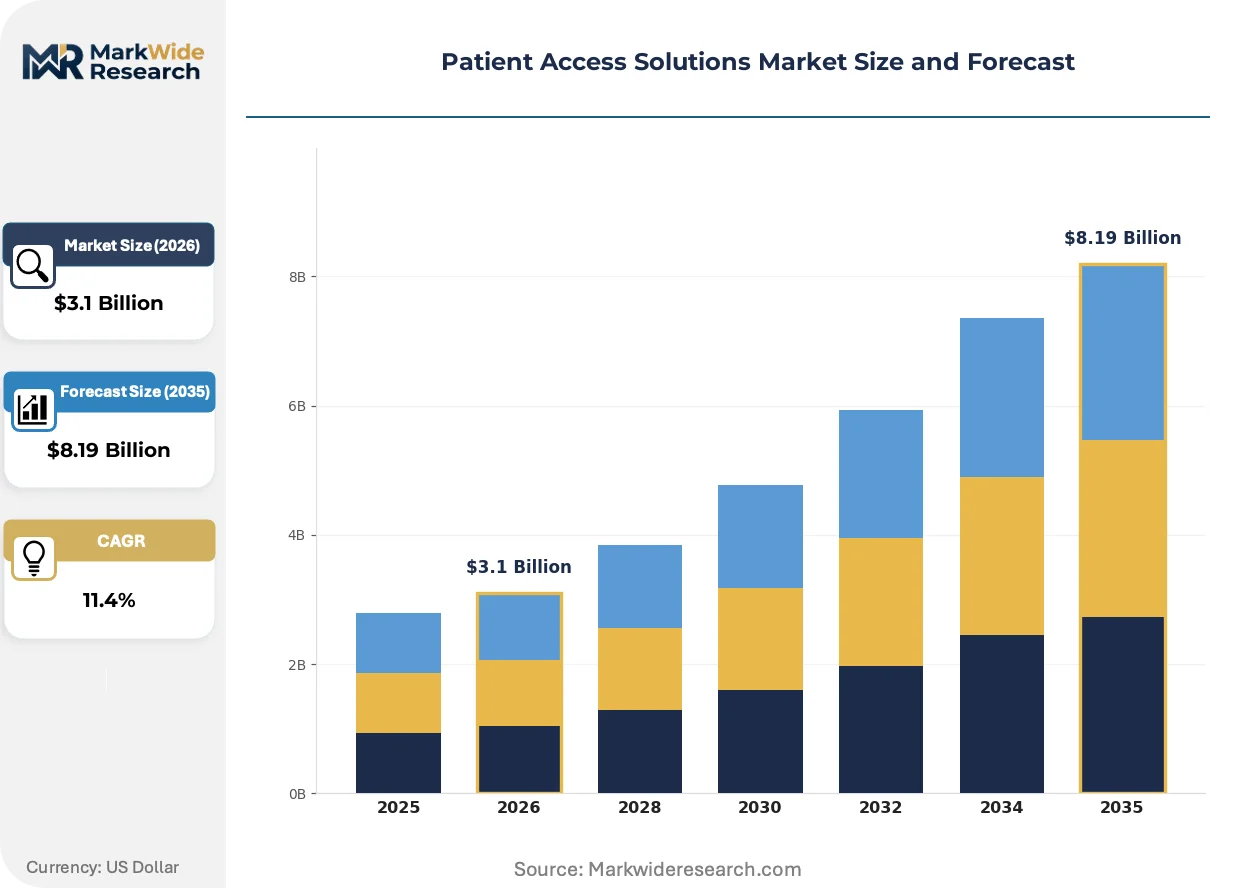
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $8.19 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eligibility Verification, Prior Authorization, Patient Enrollment, Benefits Verification Delivery Mode: Cloud-Based, On-Premise, Hybrid, Mobile End User: Healthcare Providers, Payers, Pharmaceutical Companies, Patients Technology: AI Integration, Machine Learning, APIs, Data Analytics |
| Companies Covered | Epic Systems Corporation, Oracle, McKesson Corporation, Allscripts Healthcare Solutions, Athenahealth, Optum, eClinicalWorks, NextGen Healthcare, R1, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Access Solutions Market Strategic Shifts & Innovations
Real-time data exchange architectures are displacing batch-processed eligibility verification, compressing administrative cycles from days to seconds. This shift reconfigures vendor competitive advantage around API reliability rather than EDI volume throughput.
Containerized microservices architectures are virtualizing patient access infrastructure, enabling health systems to deploy eligibility engines, prior authorization bots, and benefits verification modules as discrete, scalable components. Hospital IT departments adopt Kubernetes-orchestrated deployments that isolate failure domains and accelerate feature releases. This modular approach is virtualizing the traditional monolithic revenue cycle platform market, allowing best-of-breed vendors to displace integrated suite incumbents.
CMS interoperability mandates and state-level surprise billing regulations are forcing transparency into out-of-network eligibility and cost estimation workflows. Payers must expose machine-readable provider directories and real-time benefit data through standardized APIs. Hospital systems in Texas, California, and Florida—states with high out-of-network utilization—face the steepest compliance deadlines and are prioritizing platforms with built-in price estimation tools.
Hospital procurement committees now demand outcome-based contracting for patient access platforms, tying vendor payments to measurable denial rate reductions or prior authorization approval velocity. This displaces traditional per-transaction pricing models that rewarded volume regardless of clinical or financial outcomes. Integrated delivery networks with centralized revenue cycle operations lead this shift, using their consolidated purchasing power to extract performance guarantees from platform vendors.
Patient Access Solutions Market Segmentation
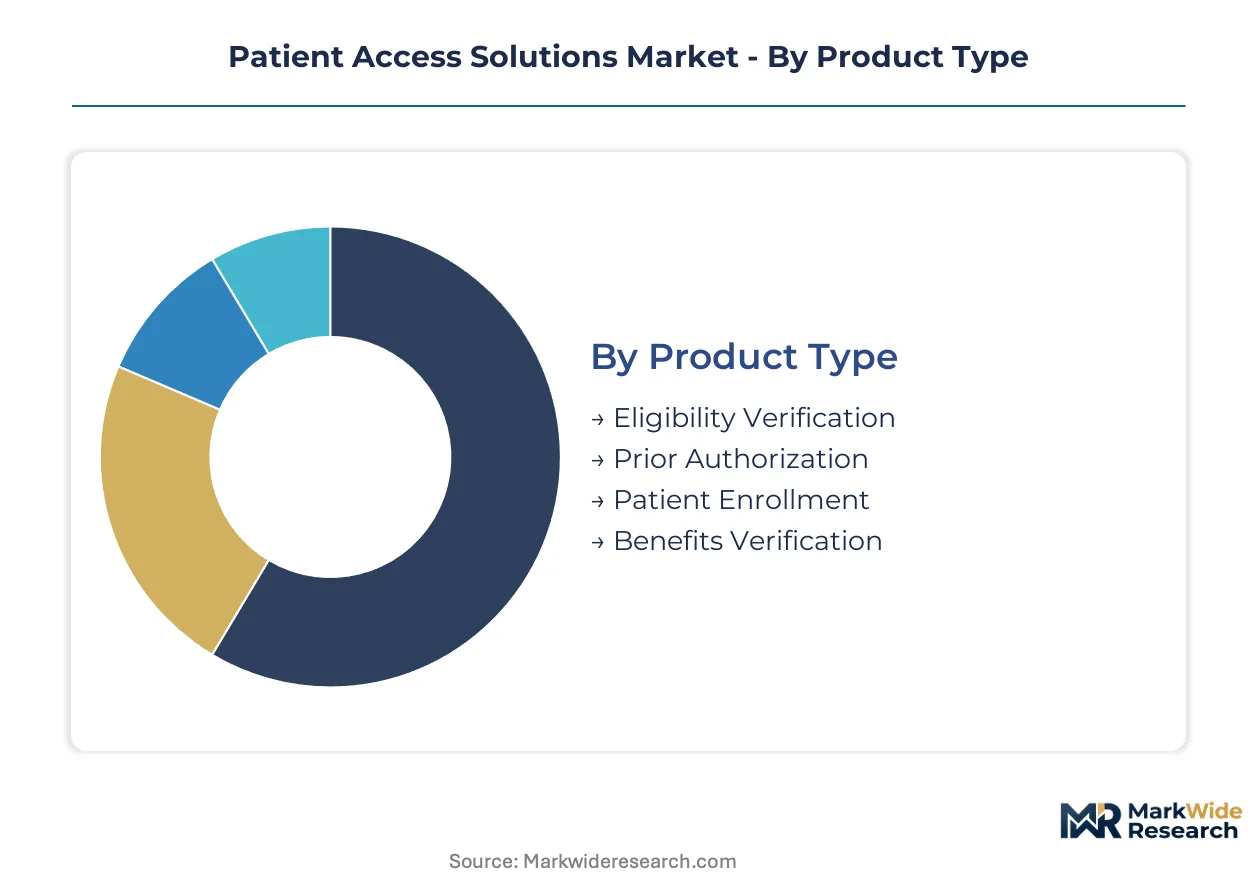
Patient access solutions fragment across product architectures, deployment models, and stakeholder workflows. Each segmentation axis reveals distinct procurement patterns and margin structures that shape vendor positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with prior authorization modules demanding continuous rules-engine updates while eligibility verification stabilizes faster post-deployment.
- Prior Authorization:Automated submission engines map clinical orders against payer medical necessity criteria through real-time API connections. Hospital systems in Texas and Florida concentrate procurement here due to state-specific formulary complexity and high denial-rate environments.
- Eligibility Verification:Real-time insurance confirmation systems validate coverage status, copay obligations, and deductible accumulation at point of service. Demand clusters among integrated delivery networks automating multi-facility revenue cycles, driven by CMS mandates for instantaneous benefit transparency.
- Patient Enrollment:Financial assistance and charity care qualification workflows streamline uninsured patient onboarding.
- Benefits Verification:Out-of-network cost estimation tools support surprise billing compliance requirements.
Prior authorization holds the largest share; momentum sits with eligibility verification.
Delivery Mode:
Cost tier stratification separates enterprise health system deployments from smaller provider implementations, with infrastructure investment thresholds determining cloud versus on-premise adoption.
- Cloud-Based:API-first platforms deploy eligibility engines and prior authorization bots through containerized microservices architectures. Health systems across the United States prioritize these solutions to eliminate data center maintenance and scale across distributed facility networks without infrastructure replication.
- Hybrid:Mixed deployments retain sensitive patient financial data on-premise while routing payer transactions through cloud gateways. Regional hospital chains with legacy EHR investments favor this architecture to phase migration without disrupting established workflows.
- On-Premise:Self-hosted EDI gateways persist among security-sensitive government payers and closed health systems.
- Mobile:Point-of-care applications extend prior authorization submission to physician smartphones and tablets.
Cloud-based deployment dominates current procurement; hybrid configurations are climbing the fastest as transition-risk-averse systems seek intermediate paths.
End User:
Customer type determines pricing elasticity and contract structure, with pharmaceutical manufacturers accepting outcome-based terms unavailable to constrained hospital capital budgets.
- Healthcare Providers:Hospital systems and physician practices automate revenue cycle touchpoints from scheduling through claim submission. Academic medical centers with complex specialty pharmacy operations drive premium platform investment to manage prior authorization for biologics and cell therapies.
- Pharmaceutical Companies:Drug manufacturers license white-label patient access platforms to navigate hub enrollment, copay assistance, and benefits verification for high-cost specialty therapies. This segment expands most quickly as manufacturers bypass traditional hub vendors for direct technology control.
- Payers:Health plans deploy prior authorization intake systems to manage provider submission volume and automate medical necessity determination.
- Patients:Direct-to-consumer cost estimation tools support price transparency navigation.
Healthcare providers retain the largest installed base; pharmaceutical companies represent the steepest expansion trajectory.
Technology:
Technology maturity separates proven infrastructure from emerging capability investments, with AI-powered policy extraction attracting venture funding while established API connectivity dominates near-term revenue.
- APIs:Standardized REST and FHIR interfaces enable real-time data exchange between provider EHRs, payer databases, and clearinghouse networks. These connections form the technical foundation for CMS-mandated prior authorization automation and information blocking compliance.
- AI Integration:Natural language processing tools parse unstructured payer medical necessity policies to extract prior authorization requirements without manual rules-engine programming. Health systems with high specialty pharmacy volume pilot these capabilities to reduce denial appeal labor.
- Machine Learning:Predictive models forecast authorization approval probability and optimal submission timing.
- Data Analytics:Denial pattern recognition and revenue cycle performance dashboards support operational improvement.
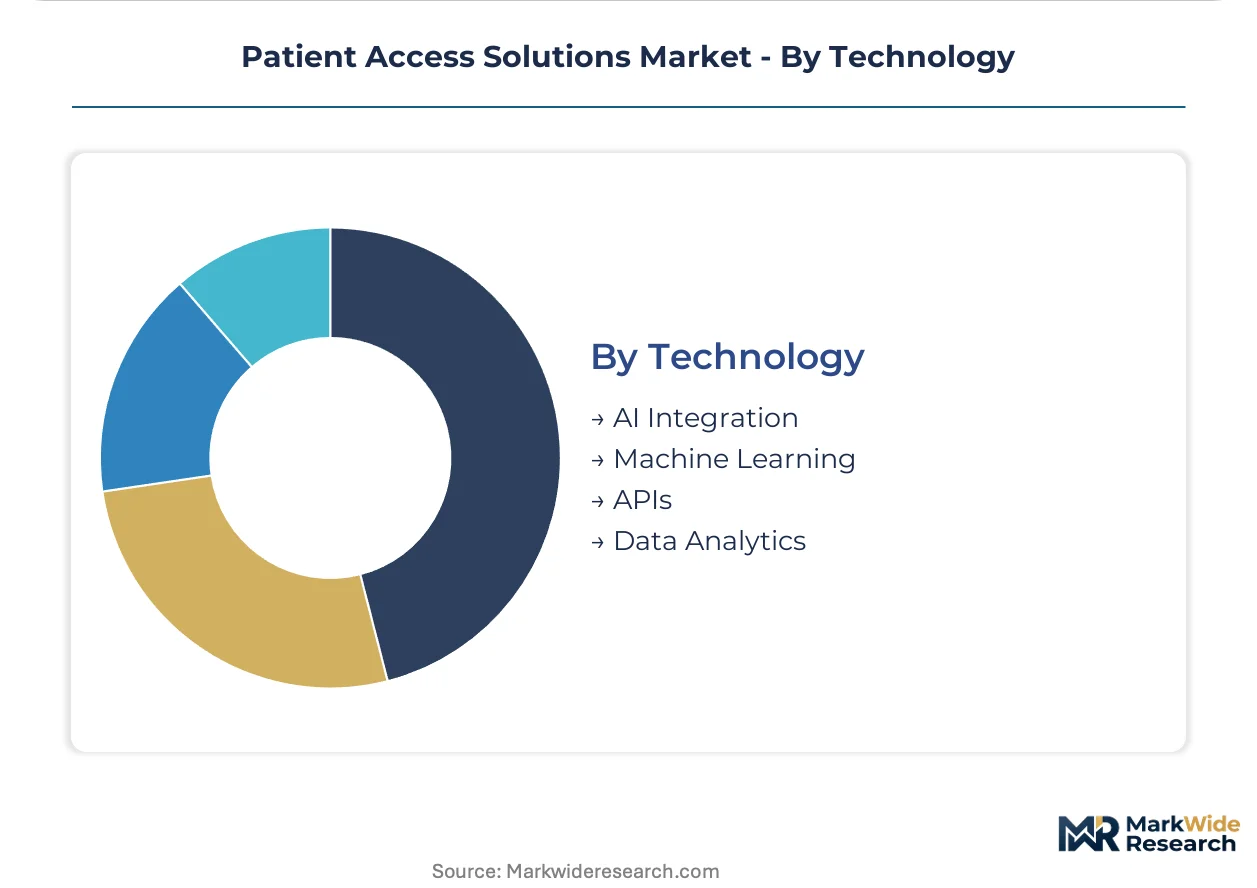
API infrastructure commands the largest share; AI integration is gaining share fastest as automation targets shift from transaction processing to cognitive task substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient access solutions consumption patterns diverge sharply by geography. The United States concentrates procurement around revenue cycle automation, while European health systems prioritize interoperability compliance. Asian markets emphasize cost-efficient eligibility verification for expanding insurance coverage.
United States
Hospital systems and integrated delivery networks drive demand for real-time prior authorization engines. CMS interoperability mandates and the FDA's 21st Century Cures Act enforcement accelerate platform consolidation. Texas and Florida health systems lead procurement volume due to complex state Medicaid formularies and high out-of-network utilization.
Germany
Statutory health insurance funds require standardized API connectivity for electronic prior authorization submission. The country's national pharmaceutical regulator enforces strict data exchange protocols under EU medical device regulations. Berlin and Munich hospital networks pilot AI-powered policy extraction tools to reduce administrative denial rates.
United Kingdom
NHS trusts automate eligibility verification to manage patient financial enrollment across mixed public-private care pathways. The country's national health technology regulator mandates FHIR-based interoperability for all new health IT procurements. London and Greater Manchester integrated care systems deploy cloud-native platforms to unify revenue cycle operations across multiple hospital sites.
Japan
Universal health coverage expansion creates demand for automated benefits verification at point of service. METI promotes standardized medical data exchange formats to reduce administrative friction. Tokyo and Osaka metropolitan hospital clusters invest in API-first eligibility engines to handle aging-population patient volume.
India
Private hospital chains deploy patient access platforms to manage cashless insurance claim processing for expanding middle-class coverage. The country's national pharmaceutical regulator enforces increasing data standardization for health IT systems. Maharashtra and Karnataka health technology corridors attract platform vendors targeting tier-1 city hospital networks.
Patient Access Solutions Market Key Industry Players
Capability concentration sits with specialized revenue cycle vendors; scale advantage sits with integrated health IT conglomerates. The market exhibits tiered competition between EHR-embedded platforms and standalone eligibility engines. Three archetypes dominate: EHR-native workflow embedders, cloud-native API specialists, and pharmaceutical channel navigators. M&A activity concentrates on acquiring FHIR development talent and payer connectivity assets.
Within the EHR-native tier, Epic Systems Corporation and Oracle exemplify platform consolidation through clinical workflow integration. McKesson Corporation anchors the connectivity-layer archetype with pharmacy-provider-payer spanning infrastructure. These three occupy positions that reflect divergent strategic bets on where patient access automation value accrues.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle |
| McKesson Corporation |
| Allscripts Healthcare Solutions |
| Athenahealth |
| Optum |
| eClinicalWorks |
| NextGen Healthcare |
| R1 |
| Others |
Cost & Logistics Intelligence
Boston's health technology corridor concentrates cloud-native platform development capacity, anchoring the supply of API-first eligibility engines that health systems deploy across multi-facility networks. This geographic clustering of FHIR development talent and payer connectivity infrastructure shapes downstream pricing power for vendors serving hospital procurement committees.
Pricing Analysis
Long-term SaaS subscription contracts with outcome-based performance clauses dominate health system procurement, displacing per-transaction models that rewarded volume regardless of denial rate outcomes. Price differentiation rests on FHIR certification tier and embedded AI policy extraction capabilities, with academic medical centers accepting premium tiers for specialty pharmacy automation. Cost compression in the mid-market intensifies as regional hospital chains consolidate purchasing through GPO contracts. Integrated delivery networks exhibit lowest price sensitivity due to centralized revenue cycle operations, while independent physician practices face acute budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts hardware components for on-premise EDI gateway installations, accelerating cloud migration decisions. Software development draws from India for back-end engineering, the United States for FHIR architects, and Ireland for European regulatory compliance localization. Single-source vulnerability concentrates in payer API endpoint connectivity, where clearinghouse networks maintain exclusive data exchange relationships. Distribution runs through direct enterprise sales teams supplemented by channel partners serving mid-market provider segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation, with centralized procurement committees extracting performance guarantees that reshape vendor margin structures across the patient access solutions landscape.
For Market Incumbents: Build switching-cost moats through deep EHR workflow embedding that makes replacement economically prohibitive for health systems. Acquire FHIR development talent pools in Boston and Dublin to defend against cloud-native API specialists. Anchor position via exclusive payer connectivity agreements that emerging entrants cannot replicate without multi-year investment horizons. For New Entrants and Emerging Players: Pursue white-label platform licensing to pharmaceutical manufacturers launching specialty therapies, bypassing saturated hospital procurement channels. Target state Medicaid agency contracts in Texas and Florida where formulary complexity creates incumbent vulnerability. Lead with AI-powered policy extraction pilots that demonstrate measurable prior authorization approval velocity gains. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native API specialists with proven FHIR implementations over legacy EDI gateway vendors. Long-term viability hinges on regulatory compliance automation capabilities spanning CMS mandates and state-level surprise billing regulations. Acquisition targets should exhibit concentrated payer connectivity assets and containerized microservices architecture. Monitor FDA 21st Century Cures Act enforcement intensity as inflection signal for interoperability platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Certification Investment | CMS interoperability mandates require standardized API access for prior authorization automation compliance. |
| AI Policy Extraction Development | Natural language processing reduces manual rules-engine programming for payer medical necessity criteria. |
| Pharmaceutical Manufacturer Partnership | Specialty drug launches fund white-label patient access platforms bypassing traditional hub vendors. |
| Cloud-Native Architecture Migration | Kubernetes-orchestrated deployments eliminate data center maintenance burdens for distributed hospital networks. |
| Payer Connectivity Acquisition | Exclusive clearinghouse relationships create defensive moats against emerging API-first competitors. |
Research Approach
Desk research of FDA 510(k) filings, CMS rulemaking dockets, and hospital procurement databases preceded structured interviews with revenue cycle executives, EHR integration specialists, payer prior authorization managers, and pharmaceutical access program directors. Primary fieldwork validated secondary findings against operational deployment timelines and budget allocation patterns. Bottom-up sizing of platform licensing revenue triangulated against top-down health IT expenditure estimates from GPO contract analysis.
Fixed assumptions held regulatory compliance deadlines and cloud migration adoption curves constant across the projection horizon, while payer API fragmentation timelines and AI capability maturation varied across scenario branches. Segmentation modeling incorporated product architecture, deployment mode, end-user category, and technology maturity dimensions. CAGRs derived from weighted average of historical health IT software growth patterns and segment-specific procurement pipeline visibility.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or federal health IT reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding CMS enforcement timelines and payer API standardization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Aged Care Software Market
Healthcare IT
Femtech Market
Healthcare IT
Healthcare Business Collaboration Tools Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Europe Outpatient Software Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
Cancer Patient Registry Software Market
Healthcare IT
Veterinary Practice Management Software Market