
 Healthcare Business Collaboration Tools Market | 2026-2036
Healthcare Business Collaboration Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Business Collaboration Tools Market Analytics
Nursing workforce shortages across hospital networks is reorganizing how care teams coordinate digitally, forcing administrators to prioritize asynchronous communication platforms. Microsoft leverages its Teams ecosystem to anchor enterprise health system deployments. Cisco Systems competes through hardened security architectures that sustain trust among risk-averse IT departments.
Healthcare business collaboration tools encompass software and hardware systems that enable real-time information exchange among clinical, administrative, and operational stakeholders, typically integrating end-to-end encryption, role-based access controls, and HL7 FHIR interoperability protocols to ensure patient data flows securely across disparate care settings. Messaging Platforms dominate current deployment volumes among understaffed nursing units seeking rapid escalation pathways, while Cloud-Based Solutions capture the fastest expansion trajectory as hospitals retire legacy on-premises infrastructure. Project Management Software occupies narrower but higher-margin niches within pharmaceutical clinical trial operations where timeline precision directly affects regulatory submission windows.
FDA guidance on cybersecurity in medical devices and HIPAA enforcement actions on unsecured messaging together elevate procurement scrutiny, compelling vendors to embed audit trails and business associate agreements as standard features rather than premium add-ons. EMA's evolving digital health framework and Japan's METI push for healthcare data standardization further fragment compliance requirements across multinational deployments. Stakeholders must weigh interoperability certification timelines against the operational cost of maintaining fragmented communication stacks.
Market Dynamics
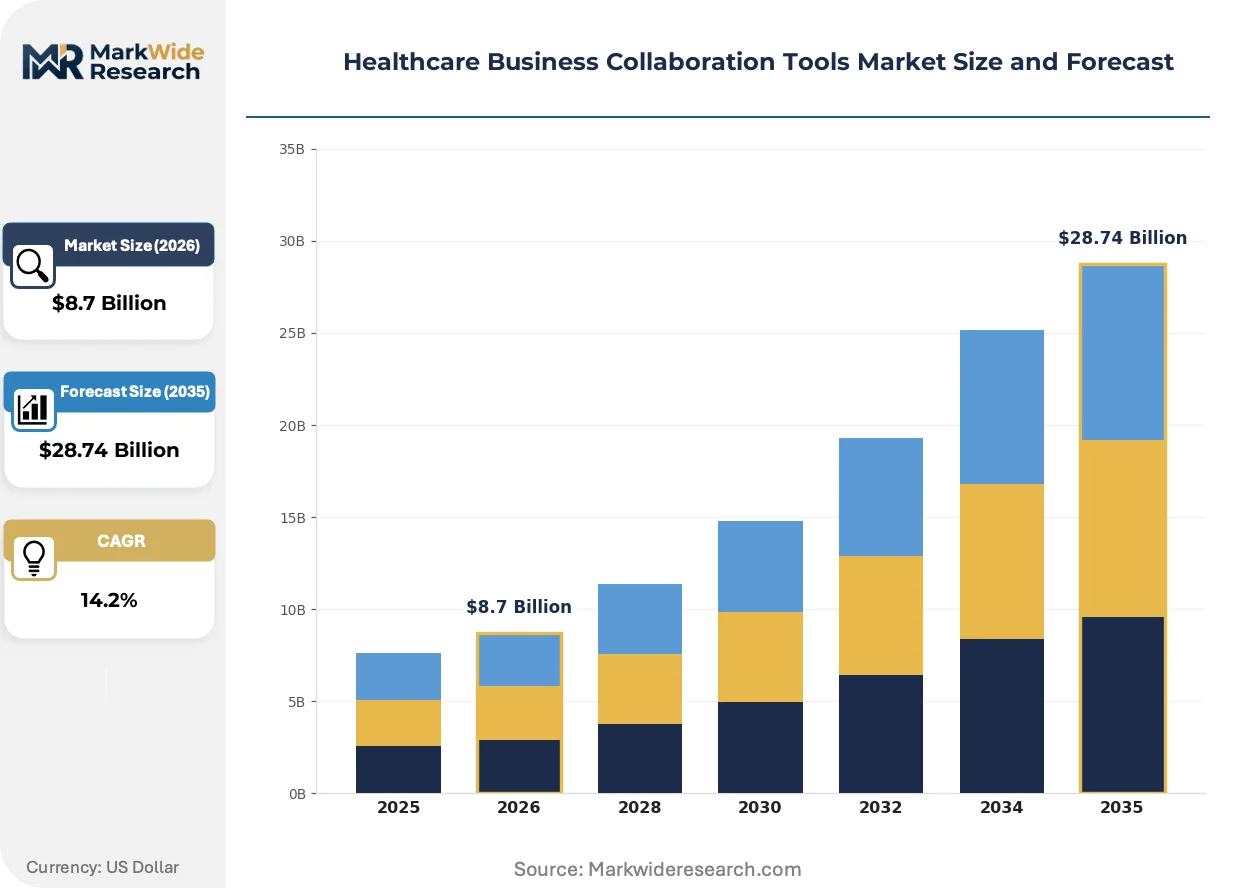
Hospital network consolidation and cloud migration mandates are restructuring procurement priorities, forcing IT departments to retire siloed on-premises systems in favor of interoperable platforms that satisfy HIPAA audit requirements while supporting distributed nursing workflows.
Growth Catalysts
- HIPAA enforcement escalation:The Office for Civil Rights has intensified penalties for unsecured patient data transmission, compelling health systems to replace consumer-grade messaging with encrypted clinical communication platforms.
- HL7 FHIR interoperability mandates:Federal push for standardized data exchange protocols is accelerating replacement of legacy HL7 v2 interfaces, opening procurement windows for integrated collaboration suites.
- Nursing workforce compression:Staffing shortages across acute care facilities are driving demand for asynchronous communication tools that reduce bedside interruption burden and enable remote specialist consultation.
Market Restraints
- Multi-jurisdictional compliance costs:Vendors must simultaneously satisfy HIPAA business associate agreements, FDA cybersecurity guidance for connected devices, and emerging state-level privacy laws, inflating development overhead.
- Legacy infrastructure lock-in:Decades-old EHR installations with proprietary APIs create integration friction that extends deployment timelines and elevates total cost of ownership.
- Cybersecurity insurance premiums:Ransomware targeting health systems has spiked carrier rates for cyber liability coverage, squeezing IT budgets and delaying collaboration tool refresh cycles.
Strategic Opportunities
- Post-acute care extension:Skilled nursing facilities and home health agencies remain underpenetrated by enterprise-grade collaboration platforms, presenting greenfield deployment potential.
- AI-enabled clinical decision support:Convergence of natural language processing with secure messaging workflows offers pathway to ambient documentation and automated care coordination alerts.
- Medicaid managed care expansion:State-level program growth is extending collaboration tool procurement authority to federally qualified health centers previously excluded from hospital system contracts.
Industry Challenges
- Interoperability certification backlog:ONC certification queues for FHIR-based applications are extending vendor time-to-revenue by six to twelve months.
- Clinical informatics talent scarcity:Health systems compete for limited specialists capable of bridging EHR configuration, workflow redesign, and change management.
- Third-party risk management complexity:Each collaboration platform integration requires vendor security assessments, business associate agreement negotiations, and ongoing compliance monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Business Collaboration Tools Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Conferencing, Messaging Platforms, Project Management Software, Document Collaboration End User: Healthcare Providers, Pharmaceutical Companies, Research Institutions, Health Insurance Technology: Cloud-Based Solutions, On-Premises Servers, Mobile Applications, Integrated Systems Application: Patient Engagement, Team Collaboration, Telemedicine, Data Sharing |
| Companies Covered | Microsoft, IBM, Google, Cisco Systems, Oracle, Zoho Corporation, Teladoc Health, Spok, TigerConnect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Business Collaboration Tools Market Evolving Landscape
Real-time communication architectures are fragmenting into modular, API-first components that decouple messaging infrastructure from EHR interfaces. This decomposition is redrawing competitive boundaries between pure-play collaboration vendors and EHR incumbents.
Containerized microservices for clinical messaging are decomposing monolithic on-premises deployments into cloud-native function blocks. Health systems in the Southeast United States are piloting these architectures to reduce vendor lock-in. The shift is compressing upgrade cycles from multi-year releases to continuous delivery pipelines.
FDA's 2023 cybersecurity guidance for premarket submissions now requires software bills of materials and vulnerability disclosure programs for connected clinical communication tools. Device manufacturers must demonstrate secure-by-design practices across third-party component libraries. Surgical suites and intensive care units face the steepest compliance burden given their concentration of networked medical devices.
Subscription pricing for collaboration platforms is displacing perpetual license models as health systems prioritize operational expenditure flexibility. Chief information officers in integrated delivery networks now favor seat-based SaaS contracts with annual renewal options. This preference is most pronounced among mid-sized hospital systems navigating uncertain reimbursement environments.
Healthcare Business Collaboration Tools Market Segmentation
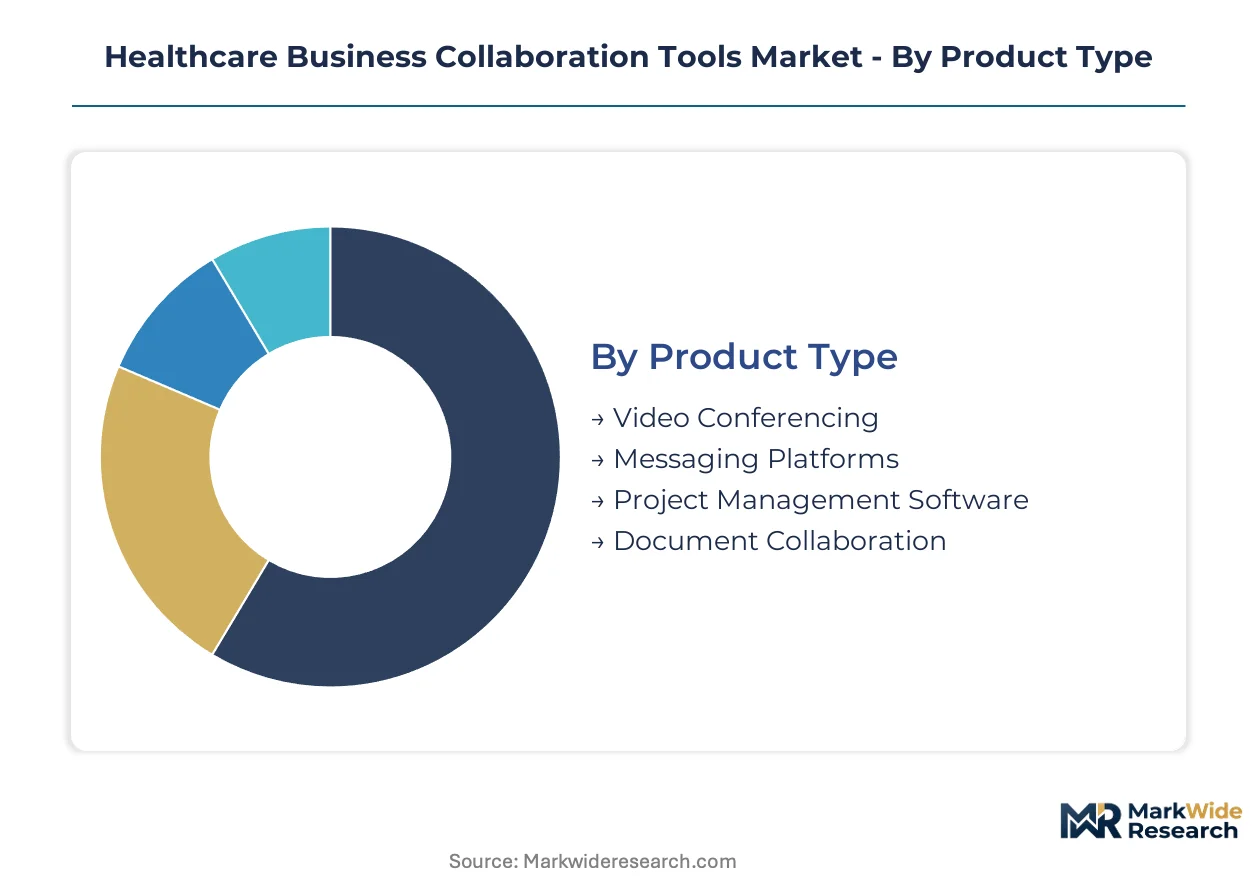
Segmentation in healthcare collaboration tools reveals how procurement authority fragments across IT infrastructure, clinical workflows, and regulatory exposure. Hospital networks prioritize HIPAA-compliant messaging while pharmaceutical sponsors demand project management precision for trial timelines.
Product Type:
Messaging Platforms command the deepest margin pools through recurring seat-based subscriptions and rapid deployment cycles. Video Conferencing and Document Collaboration compete on infrastructure intensity and integration complexity respectively.
- Messaging Platforms:Asynchronous encrypted communication systems with role-based access controls and audit trails. Demand concentrates in understaffed nursing units across US hospital networks seeking rapid escalation pathways without bedside interruption.
- Project Management Software:Timeline-critical workflow orchestration with Gantt visualization and regulatory milestone tracking. Pharmaceutical clinical trial operations in North American integrated delivery networks drive premium pricing where submission window precision affects FDA approval schedules.
- Video Conferencing:HIPAA-compliant real-time audiovisual infrastructure with waiting room controls and session recording. Telemedicine expansion and remote specialist consultation requirements sustain procurement momentum.
- Document Collaboration:Concurrent editing platforms with version control and granular permission architecture. Health system consolidation creates demand for standardized policy templates across merged entities.
Messaging Platforms hold installed capacity. Project Management Software is rotating up the share rankings.
End User:
Procurement volume concentrates in acute care facilities with the largest staff bases and strictest audit requirements. Pharmaceutical sponsors and research institutions operate on longer sales cycles but generate higher contract values per seat.
- Healthcare Providers:Hospital networks, physician practices, and ambulatory surgery centers requiring real-time coordination across distributed care teams. Cloud migration mandates and HIPAA enforcement escalation are accelerating replacement of consumer-grade consumer tools with encrypted clinical platforms.
- Pharmaceutical Companies:Sponsors managing multi-site clinical trials with regulatory submission dependencies. Document collaboration and project management modules capture premium pricing where timeline precision directly affects FDA approval windows.
- Research Institutions:Academic medical centers and contract research organizations with dual clinical and publication workflows. Grant-funded procurement creates budget cyclicality distinct from operational IT spending.
- Health Insurance:Payers coordinating prior authorization, utilization review, and care management across provider networks. Interoperability demands for HL7 FHIR data exchange shape platform selection criteria.
Healthcare Providers anchor current deployment volumes. Pharmaceutical Companies are gaining procurement authority fastest.
Technology:
Cloud architectures are displacing capital-intensive on-premises installations as health systems prioritize operational expenditure flexibility and continuous update delivery. Mobile and integrated deployments follow cloud adoption patterns.
- Cloud-Based Solutions:Multi-tenant SaaS architectures with automatic security patching and elastic scaling. US health systems retiring legacy infrastructure are unlocking interoperability gains through API-first deployment models.
- On-Premises Servers:Single-tenant hardware installations with direct physical control over data residency. Risk-averse IT departments in certain hospital networks sustain demand despite higher total cost of ownership.
- Mobile Applications:Native iOS and Android clients with offline synchronization and biometric authentication. Nursing workforce mobility requirements drive bedside adoption for asynchronous communication.
- Integrated Systems:Pre-built connectors to Epic, Cerner, and Meditech EHR environments with embedded workflow triggers. ONC certification requirements extend vendor time-to-revenue but lock in switching costs.
Cloud-Based Solutions capture the steepest expansion trajectory. On-Premises Servers retain defensive positions in select risk-averse accounts.
Application:
Team Collaboration generates the broadest addressable base across clinical and administrative users. Patient Engagement and Telemedicine applications carry higher regulatory visibility and cybersecurity scrutiny.
- Team Collaboration:Cross-functional coordination spanning nursing, pharmacy, laboratory, and administrative departments. Staffing shortages across acute care facilities are reorganizing how care teams coordinate digitally.
- Telemedicine:Virtual visit delivery with synchronous video, asynchronous messaging, and remote monitoring integration. Reimbursement parity expansion and rural access mandates sustain deployment growth.
- Patient Engagement:Portal-based communication, appointment scheduling, and care plan adherence tools. HIPAA business associate agreements and state privacy law compliance inflate vendor development overhead.
- Data Sharing:Inter-organizational exchange for care transitions, referrals, and population health management. HL7 FHIR interoperability mandates are accelerating replacement of legacy HL7 v2 interfaces.
Team Collaboration dominates current seat counts. Telemedicine is climbing the fastest in procurement priority rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States integrated delivery networks while European procurement cycles stretch vendor cash conversion timelines. German hospital systems extract steeper discount tiers through centralized purchasing cooperatives. Japanese clinical communication platforms command premium seat rates reflecting METI data standardization compliance costs.
United States
Hospital network consolidation and cloud migration mandates drive procurement volume toward interoperable platforms. HIPAA enforcement escalation by the Office for Civil Rights compels replacement of consumer-grade messaging with encrypted clinical alternatives. The Southeast United States pilots containerized microservices architectures to reduce vendor lock-in.
Germany
University hospital networks prioritize GDPR-compliant collaboration suites with embedded audit trails. The country's national data protection authority enforces strict cross-border data residency requirements for patient information. Bavaria's medical technology cluster anchors development of HL7 FHIR-certified integration modules.
Japan
Aging demographics and rural hospital closures accelerate demand for remote specialist consultation platforms. METI pushes healthcare data standardization through interoperability frameworks that fragment compliance requirements. Tokyo's academic medical centers pilot AI-enabled clinical decision support embedded within secure messaging workflows.
United Kingdom
NHS digital transformation programs consolidate procurement authority at integrated care system level. The country's health data regulator mandates business associate agreements for all patient-facing collaboration tools. London's health tech corridor concentrates vendor development centers targeting European EMA compliance pathways.
Canada
Provincial health authority consolidation creates procurement scale for enterprise-grade collaboration deployments. Health Canada and the country's national privacy commissioner jointly enforce cybersecurity standards for connected clinical devices. Ontario's hospital networks lead cloud migration adoption among publicly funded health systems.
Healthcare Business Collaboration Tools Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the healthcare collaboration tools market. The vendor base organizes into three strategic tiers: cloud-native specialists with API-first architectures, legacy infrastructure incumbents with embedded EHR relationships, and telemedicine-anchored platforms with vertical workflow depth. Dominant competitive moves include strategic partnerships with hospital network purchasing cooperatives and portfolio diversification into post-acute care extensions.
Among technology conglomerates with healthcare verticalization, Microsoft and Cisco Systems occupy positions representing divergent security-versus-ecosystem value propositions. IBM exemplifies the hybrid cloud integration archetype serving risk-averse IT departments. Specialist clinical communication vendors including TigerConnect and Spok sit within the HIPAA-compliant messaging tier, while Zoho Corporation represents the cost-optimized SaaS alternative gaining traction among smaller physician practices.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Cisco Systems |
| Oracle |
| Zoho Corporation |
| Teladoc Health |
| Spok |
| TigerConnect |
| Others |
Value Network & Pricing Analysis
HIPAA business associate agreement certification gates both vendor qualification and price tiering simultaneously, forcing collaboration platform suppliers to absorb compliance audit costs before accessing hospital network procurement lists while enabling certified vendors to command recurring-revenue premiums over uncertified alternatives.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise deployments from standard SaaS seat packages. Seat-based subscription models dominate, with pricing differentiation driven by HL7 FHIR certification tier and after-sales implementation support depth. Cost compression in mid-market health systems is intensifying because nursing workforce shortages extend sales cycles and elevate pilot-to-contract conversion costs. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks with consolidated purchasing authority show lowest.
Supply Chain Analysis
Inbound logistics costs for cloud infrastructure hardware face intermittent pressure from Asia-Pacific port congestion and trans-Pacific container availability constraints. Software development labor concentrates in the United States, India, and Ireland. Component dependencies include AWS/Azure/GCP compute instances, encryption chipset modules, and biometric authentication SDKs. Single-source vulnerability sits with hyperscaler concentration for hosting infrastructure. Distribution runs through direct enterprise sales teams and hospital group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare business collaboration tools function as a service-attach opportunity where recurring-revenue layers from ongoing compliance monitoring and workflow optimization consulting expand faster than initial platform licensing.
For Market Incumbents: Compound defensive positioning by deepening embedded EHR integration partnerships with Epic and Cerner while acquiring clinical informatics consultancies to address talent scarcity threatening implementation timelines. Threat from cloud-native entrants with API-first architectures demands accelerated ONC certification investment to lock in switching costs.
For New Entrants and Emerging Players: Anchor in post-acute care white space where skilled nursing facilities and home health agencies remain underpenetrated by enterprise-grade platforms. Medicaid managed care expansion at state level creates procurement authority entry points. Go-to-market angle: AI-enabled ambient documentation modules that reduce nursing documentation burden.
For Investors and Strategic Acquirers: FDA's 2023 cybersecurity guidance for premarket submissions reshapes the acquisition landscape by elevating software bill of materials capabilities to due-diligence priority. Long-term viability favors vendors with demonstrated secure-by-design practices and vulnerability disclosure programs. Target acquisition archetype: clinical communication specialists with existing hospital network purchasing cooperative relationships. Signal to watch: ONC certification queue clearance rates as inflection indicator for vendor time-to-revenue compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic and Cerner embedded workflow triggers lock hospital system switching costs. |
| Strategic Partnership | Hospital group purchasing organization contracts compress customer acquisition expense. |
| Acquisition of Specialist Firm | Clinical informatics consultancies address implementation talent scarcity. |
| Geographic Expansion | Post-acute care extension unlocks skilled nursing facility greenfield deployments. |
| Product Launch | AI-enabled ambient documentation modules reduce nursing workforce documentation burden. |
Research Methodology
A standing panel of hospital CIOs, nursing informatics directors, GPO contracts managers, and biomedical engineers provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation against CMS Medicare reimbursement data, hospital procurement databases, FDA 510(k) filings, and ONC certification records. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates.
Consistency checks validated outputs against external benchmarks including hyperscaler healthcare vertical revenue disclosures and EHR vendor collaboration module attachment rates. Segmentation dimensions modeled encompass deployment model, health system size tier, EHR integration complexity, and regional regulatory cluster. CAGRs derived from logistic adoption curve fitting against nursing workforce compression indicators and cloud migration mandate timelines.
Material uncertainties — HIPAA enforcement escalation intensity, ONC certification queue duration, cybersecurity insurance premium trajectory — sit outside the modeled envelope. Forecasts reflect assumptions about interoperability mandate adherence and reimbursement parity stability. Practitioners should keep alternative scenarios live as federal healthcare data exchange rulemaking evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Healthcare HR Software Market
Healthcare IT
Commercial Pharmaceutical Analytics Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Global Emergency Department Information System Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
US Dental Clearing Houses Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market