
 Reusable Barrels Market | 2026-2036
Reusable Barrels Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Barrels Market Analysis
EU REACH substance restrictions is pivoting the cost-of-entry calculus for barrel suppliers serving European chemical and pharmaceutical end users. Kelvin Cooperage leverages generations of stave-matching expertise to sustain premium positioning in spirits maturation. Rocky Mountain Barrel Company anchors North American supply through geographic dominance in whiskey-barrel refurbishment. Exotic Barrels differentiates via specialization in custom-toast profiles for craft distilleries.
Reusable barrels are cylindrical containers engineered from oak staves with steel hoop reinforcement, stainless steel, high-density polyethylene, or aluminum, typically rated for liquid containment between 50L and 400L and designed for multi-cycle deployment across storage, transport, dispensing, or mixing operations. Steel barrels dominate chemical and pharmaceutical logistics due to UN-certified stack strength and compatibility with hazardous material handling, while plastic variants gain share in agricultural and food-grade applications where weight reduction and corrosion immunity offset lower thermal tolerance. By functionality, transport-configured barrels with integrated pallet bases and sealed bung systems command margin premiums over basic storage units, reflecting the structural value of multimodal compatibility.
FDA food-contact substance regulations and EPA hazardous waste container standards govern material selection and interior coating protocols in the United States, while EU REACH and CE marking frameworks dictate chemical migration limits and traceability across European reuse pools. These layered compliance requirements elevate testing burdens for cross-border barrel fleets, effectively segmenting supply between regionally certified producers and limiting arbitrage opportunities. Stakeholders must monitor evolving extended producer responsibility frameworks that could shift end-of-life recovery costs from users back to original barrel manufacturers.
Market Dynamics
REACH substance restrictions in Europe are compressing supplier margins while simultaneously elevating entry barriers for cross-border barrel fleets, forcing regional certification specialization that fragments global supply pools.
Growth Catalysts
- EU REACH compliance mandates:Chemical migration limits for barrel interiors are redirecting pharmaceutical logistics demand toward certified refurbishment networks in Germany and France.
- Stainless-steel cask adoption:Spirits producers in Kentucky and Scotland are expanding orders for reusable stainless variants that withstand higher toast cycles than traditional oak.
- Craft brewing cluster density:Microbrewery expansion in Colorado and Oregon sustains localized barrel pooling systems that reduce per-unit transport costs.
Market Restraints
- Oak stave supply volatility:French and American white oak harvest fluctuations create input cost instability for cooperage-dependent refurbishment operations.
- Regional certification silos:FDA food-contact rules and EU REACH frameworks lack mutual recognition, preventing arbitrage across Atlantic barrel fleets.
- High-density polyethylene thermal limitations:Plastic barrel variants face substitution pressure in hot-climate chemical transport where temperature tolerance falls below steel alternatives.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging EU directives on end-of-life recovery costs could shift liability from users back to original manufacturers, creating refurbishment service revenue streams.
- Circular economy procurement mandates:Corporate sustainability targets in Germany and the Netherlands are embedding reusable asset requirements into chemical logistics contracts.
- RFID-enabled fleet tracking:Integration of sensor technology with barrel management systems is opening predictive maintenance contracts for high-turnover beverage clients.
Industry Challenges
- Cooperage skill scarcity:Stave-matching and hoop-driving expertise is concentrating among aging workforces in Kentucky and Speyside without adequate apprenticeship pipeline replacement.
- Multi-jurisdiction certification timelines:Cross-border barrel fleets face 12-18 month approval cycles to satisfy both FDA and EFSA food-contact requirements simultaneously.
- Legacy ERP integration friction:Pooling operators struggle to synchronize barrel tracking data with client inventory management systems built on disparate software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Barrels Market |
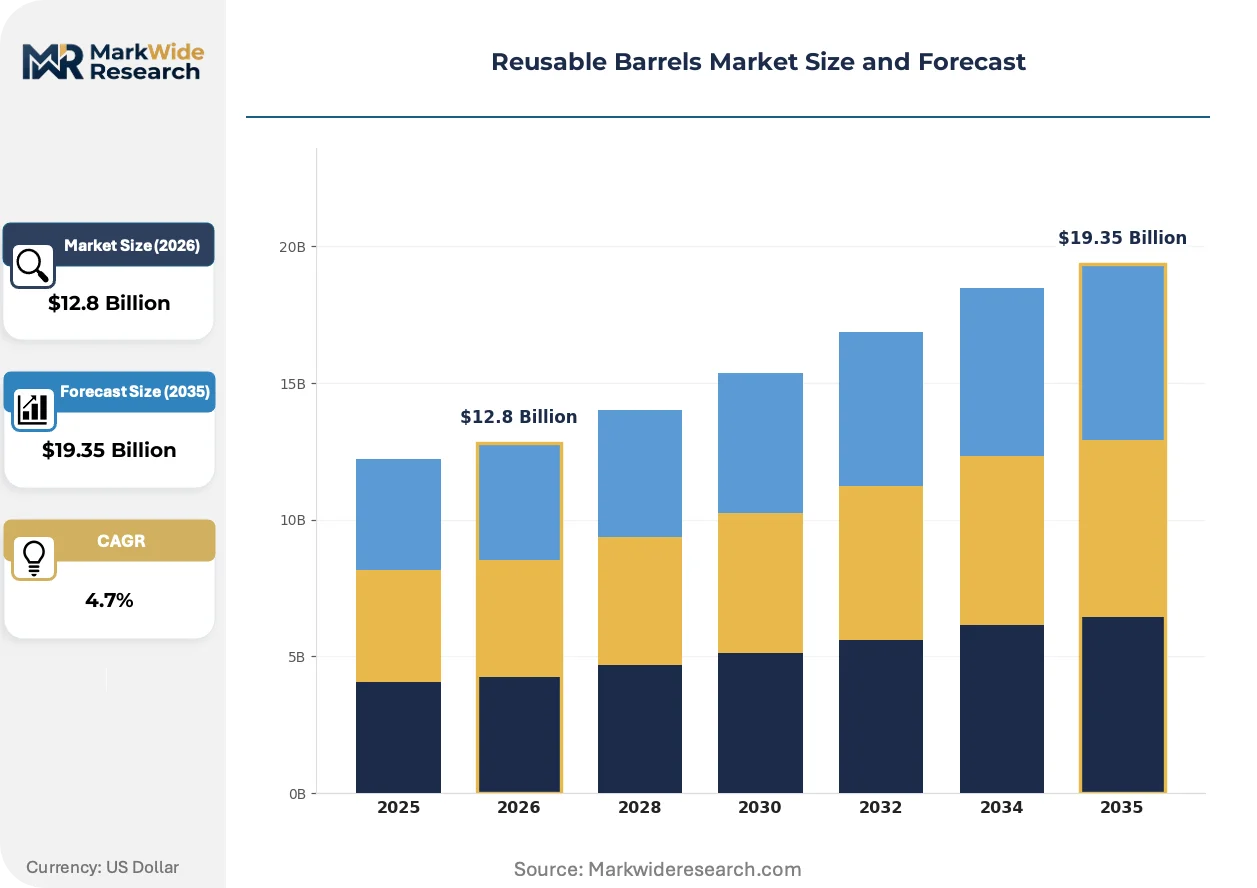
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Plastic, Fiber, Aluminum Functionality: Storage, Transport, Dispensing, Mixing End User: Food & Beverage, Chemicals, Pharmaceuticals, Agriculture Capacity: 50L, 100L, 200L, 400L |
| Companies Covered | Red Head Barrels, Exotic Barrels, Kentucky Bourbon Barrel, Esty Inc., Mystic Barrels, Rocky Mountain Barrel Company, Annandale Distillery, Kelvin Cooperage, Country Connection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Barrels Market Emerging Trajectories
Laser-based stave inspection and blockchain traceability protocols are compressing quality assurance cycles while redefining liability structures across multi-user barrel networks.
Machine vision systems for internal stave defect detection are automating refurbishment grading decisions that previously required manual cooper assessment. Kentucky-based spirits maturation facilities are deploying these systems at throughput rates exceeding 400 barrels per shift. This technology is automating quality variance reduction that previously generated 8-12% rejection rates in high-volume refurbishment contracts.
EU F-Gas Regulation phase-down schedules are accelerating demand for natural refrigerant-compatible stainless steel barrels in pharmaceutical cold chains. German chemical logistics operators face 2027 compliance deadlines that disqualify certain gasket materials previously standard in multi-use containers. Biopharma distribution networks spanning Belgium and the Netherlands are retrofitting existing fleets with alternative sealing compounds ahead of enforcement windows.
Asset-as-a-service contracting is displacing outright barrel purchases among mid-sized craft distilleries in Colorado and Tennessee. Leasing arrangements bundle refurbishment, transport, and compliance certification into per-cycle fees that convert fixed capital to operating expenditure. This model concentrates most visibly among whiskey producers with annual maturation volumes below 50,000 barrels seeking balance sheet flexibility.
Reusable Barrels Market Segmentation
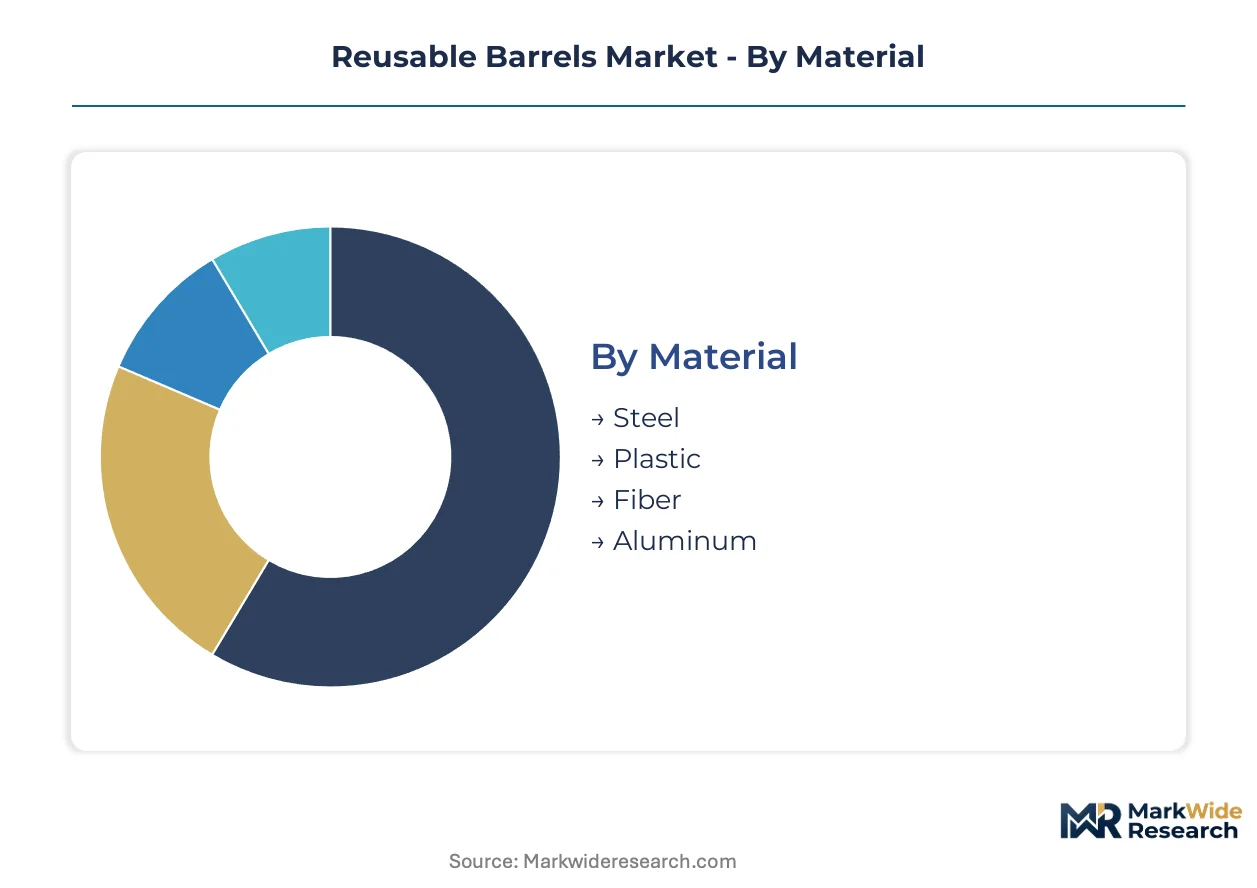
Reusable barrel procurement decisions pivot on material compatibility with contents, cycle frequency, and regulatory exposure. Distinct segment boundaries determine refurbishment economics and fleet management complexity across chemical, pharmaceutical, and beverage logistics networks.
Material:
Upgrade cycles vary sharply by material durability and corrosion resistance, with steel barrels commanding extended service intervals that reshape total cost-of-ownership calculations.
- Steel:Carbon and stainless variants deliver UN-certified stack strength for hazardous chemical transport. Pharmaceutical cold chains in Germany and Belgium specify stainless grades compatible with EU F-Gas Regulation gasket requirements. Steel sits at the top of the volume ranking, with aluminum climbing the fastest.
- Plastic:High-density polyethylene barrels reduce tare weight for agricultural chemical distribution. Thermal limitations below 60°C restrict deployment in hot-climate transport corridors, constraining substitution momentum against metal alternatives.
- Fiber:Fiber-reinforced composite barrels serve niche applications demanding corrosion immunity without metallic conductivity. Chemical processors in the Netherlands deploy these for electrostatic-sensitive formulations.
- Aluminum:Lightweight aluminum variants gain traction in aviation fuel logistics and premium beverage dispensing where weight reduction justifies material cost premiums. Kentucky craft distilleries specify aluminum for mobile tasting room deployments.
Steel dominates installed base volumes while aluminum expands most quickly in weight-sensitive applications.
Functionality:
Functional configuration dictates structural reinforcement requirements and determines whether barrels qualify for multimodal transport certification.
- Storage:Basic storage barrels prioritize interior coating integrity over structural mobility features. Wine and spirits maturation facilities in France and Spain deploy oak and stainless variants for multi-year aging cycles without transport stress.
- Transport:Transport-configured units integrate pallet bases, corner castings, and sealed bung systems for intermodal compatibility. UN certification for dangerous goods handling commands margin premiums of 15-25% over storage-grade equivalents.
- Dispensing:Dispensing barrels incorporate tap systems, level indicators, and contamination barriers for direct-use applications. German chemical logistics hubs specify these for just-in-time manufacturing supply.
- Mixing:Mixing barrels feature reinforced baffle plates and agitation-compatible geometries. Agricultural cooperatives in Iowa and Illinois deploy these for fertilizer blending operations.
Transport functionality captures the largest revenue share, with mixing applications gaining traction in agricultural processing.
End User:
End-use sector requirements fragment certification standards and determine acceptable refurbishment cycle counts.
- Food & Beverage:FDA food-contact and EFSA compliance govern interior surface protocols for brewing, distilling, and wine production. Kentucky and Speyside maturation facilities drive demand for toasted oak and stainless variants with traceable provenance.
- Chemicals:REACH substance restrictions and EPA hazardous waste container standards mandate material traceability. German Rhine-based logistics operators maintain dense reuse networks serving BASF and Bayer supply chains.
- Pharmaceuticals:EMA and FDA pharmaceutical packaging directives require validated cleaning protocols and batch-level documentation. Belgian biopharma distribution networks specify stainless steel with alternative sealing compounds ahead of F-Gas compliance deadlines.
- Agriculture:Corrosion resistance and weight reduction priorities favor plastic and coated steel variants. Colorado and Oregon microbrewery clusters sustain localized pooling systems that reduce per-unit transport expenditure.
Food and beverage generates the highest refurbishment frequency, with pharmaceuticals commanding the strictest certification overhead.
Capacity:
Capacity selection balances handling efficiency against batch-size flexibility and storage footprint constraints.
- 50L:Compact 50L barrels serve craft distillery tasting programs and specialty chemical sampling. Limited economies of scale restrict deployment to high-value, low-volume contents.
- 100L:Mid-scale 100L units bridge craft production and commercial volumes. Colorado brewing cooperatives standardize on this capacity for rotational sour beer programs.
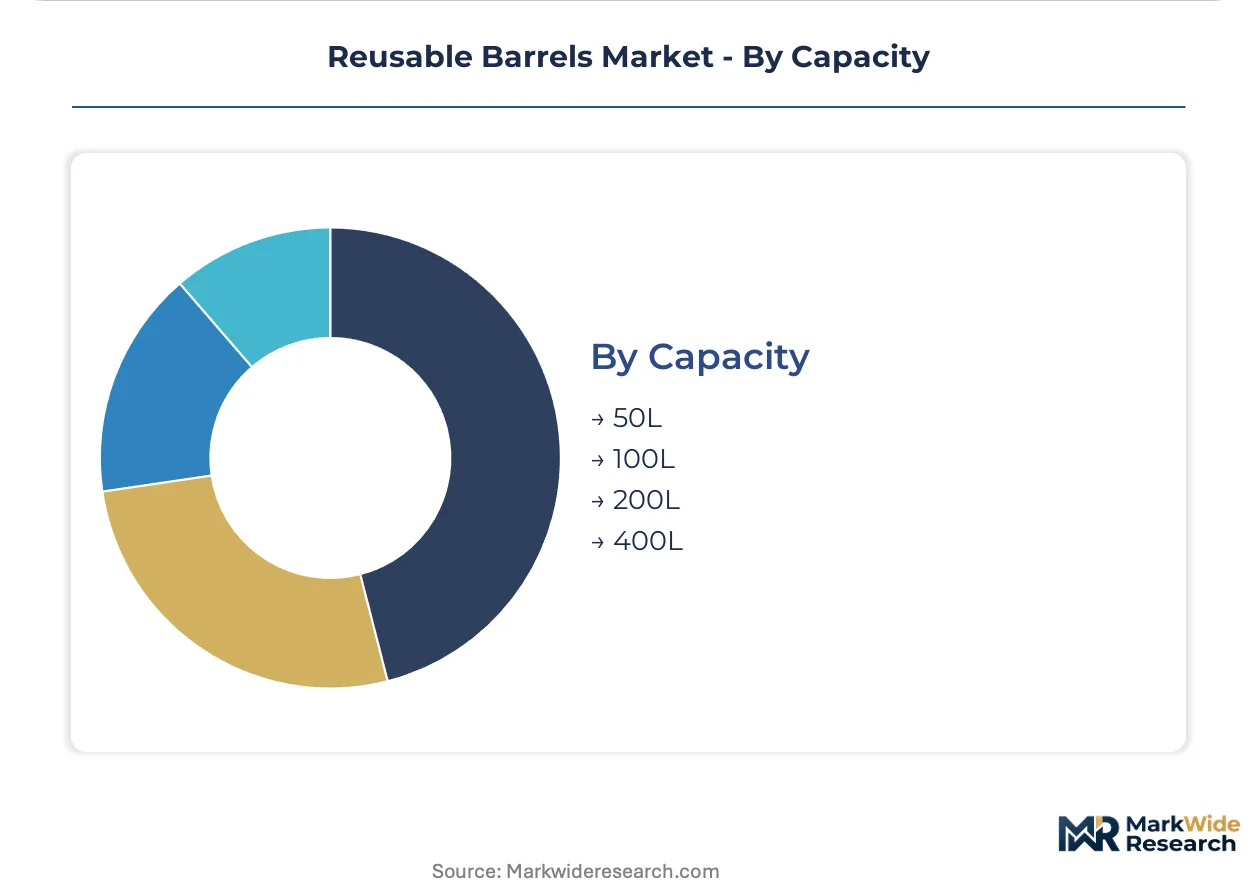
- 200L:Standard 200L dimensions align with global palletization norms and dominate chemical logistics. UN certification testing protocols center on this capacity class, streamlining cross-border fleet interoperability.
- 400L:Maximal 400L variants reduce handling costs for bulk wine and spirits maturation. French cooperages near Bordeaux specialize in these dimensions for château contract work.
200L capacity anchors global volume, with 100L variants expanding most quickly in craft beverage segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cooperage artisans in Kentucky and Speyside anchor the global talent pool for stave-matching and hoop-driving expertise, with apprenticeship pipelines narrowing across both regions. German chemical logistics hubs and French wine cooperages sustain dense refurbishment networks that concentrate barrel reuse economics. Regulatory fragmentation between FDA food-contact rules and EU REACH frameworks prevents arbitrage across Atlantic supply pools.
United States
Spirits maturation facilities in Kentucky and Tennessee drive demand for toasted oak and stainless-steel variants with traceable provenance. FDA food-contact substance regulations govern interior coating protocols for brewing and distilling operations. Colorado and Oregon microbrewery clusters sustain localized barrel pooling systems that reduce per-unit transport expenditure.
Germany
Rhine-based chemical logistics operators maintain dense reuse networks serving pharmaceutical and industrial supply chains. EU REACH substance restrictions and F-Gas Regulation phase-down schedules mandate alternative sealing compounds ahead of 2027 compliance deadlines. Distillery clusters near Speyside-style cooperages sustain premium refurbishment capacity for spirits producers.
France
Cooperages near Bordeaux specialize in 400L capacity variants for château contract work in bulk wine maturation. EFSA food-contact compliance governs interior surface protocols for multi-year aging cycles. French white oak harvest fluctuations create input cost instability for cooperage-dependent operations serving domestic and export markets.
United Kingdom
Speyside maturation facilities anchor Scotch whisky barrel demand with requirements for multi-cycle oak deployment. CE marking frameworks dictate chemical migration limits and traceability across European reuse pools. Scottish cooperages concentrate stave-matching expertise among aging workforces without adequate apprenticeship pipeline replacement.
Belgium
Biopharma distribution networks spanning Belgium and the Netherlands specify stainless steel with alternative sealing compounds for cold chain logistics. EMA pharmaceutical packaging directives require validated cleaning protocols and batch-level documentation. Antwerp-based chemical logistics operators retrofit existing fleets with F-Gas-compliant gasket materials ahead of enforcement windows.
Reusable Barrels Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material categories and end-use segments. The vendor base stratifies between steel fabricators serving chemical logistics, oak cooperages anchored in spirits maturation, and plastic molding operations targeting agricultural applications. Three archetypes dominate: heritage cooperages with generational stave-matching expertise, regional refurbishment networks with dense pooling infrastructure, and materials-science specialists developing alternative sealing compounds. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for EU F-Gas Regulation compliance deadlines.
Within the heritage cooperage tier, Kelvin Cooperage and Kentucky Bourbon Barrel exemplify multi-generational stave-matching operations that sustain premium positioning in spirits maturation. Rocky Mountain Barrel Company anchors North American supply through geographic dominance in whiskey-barrel refurbishment. Exotic Barrels occupies a specialist position through custom-toast profile capabilities for craft distillery segments. These three represent distinct archetype endpoints: generational expertise, regional scale concentration, and customization depth.
| Leading Market Players |
|---|
| Red Head Barrels |
| Exotic Barrels |
| Kentucky Bourbon Barrel |
| Esty Inc. |
| Mystic Barrels |
| Rocky Mountain Barrel Company |
| Annandale Distillery |
| Kelvin Cooperage |
| Country Connection |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down schedules gate qualified supply for pharmaceutical cold chain barrels while simultaneously restricting premium-tier pricing access to refurbishment networks with certified alternative sealing compounds. This environmental mandate concentrates pricing power among German and Belgian operators who completed retrofit investments ahead of compliance deadlines, leaving uncertified competitors exposed to margin compression in standard-tier segments.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across the reusable barrel market. Asset-as-a-service contracting bundles refurbishment, transport, and compliance certification into per-cycle fees that convert fixed capital to operating expenditure for craft distilleries, while transactional spot purchases dominate chemical logistics procurement. Price differentiation hinges on UN certification tier and after-sales service bundling, with transport-configured units commanding premiums over storage-grade equivalents. Cost compression in standard-tier oak refurbishment is intensifying because French and American white oak harvest fluctuations create input cost instability. Agricultural cooperatives exhibit highest price sensitivity due to volume procurement and plastic barrel substitution options, while pharmaceutical cold chain operators show lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Certification and qualification gating fragments supply access across Atlantic markets, with FDA food-contact rules and EU REACH frameworks lacking mutual recognition. Geographic supply concentration centers on the United States, Germany, and France, where Kentucky cooperages, Rhine-based chemical logistics hubs, and Bordeaux-area wine cooperages anchor refurbishment capacity. Raw material dependencies rest on French and American white oak stave supply, stainless steel grades compatible with F-Gas Regulation gasket requirements, and high-density polyethylene resin for agricultural variants. Single-source vulnerability in specialized cooperage labor creates structural risk, as stave-matching expertise concentrates among aging workforces without adequate apprenticeship pipeline replacement. Distribution runs through regional refurbishment networks and asset-pooling operators serving beverage and chemical end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reusable barrel market reads as a late-cycle quality story, with spirits producers in Kentucky and Scotland shifting demand toward premium stainless-steel variants that withstand higher toast cycles and deliver traceable provenance.
For Market Incumbents: Lock in refurbishment network density across German chemical logistics corridors and Speyside-style cooperage clusters to defend against emerging asset-as-a-service platforms. Prioritize backward integration into stave supply through long-term contracts with French and American white oak harvesters, mitigating input cost volatility that threatens margin stability in oak-dependent segments. For New Entrants and Emerging Players: Enter via RFID-enabled fleet tracking and predictive maintenance contracts for high-turnover beverage clients, where legacy ERP integration friction creates white-space opportunity. Target Colorado and Oregon microbrewery clusters with localized pooling systems that reduce per-unit transport expenditure, leveraging circular economy procurement mandates embedding reusable asset requirements into chemical logistics contracts as the go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional refurbishment networks with dense pooling infrastructure because EU extended producer responsibility frameworks could shift end-of-life recovery costs from users back to original manufacturers, creating service revenue concentration opportunities. Focus acquisition screening on heritage cooperages with generational stave-matching expertise and certified refurbishment capacity ahead of F-Gas compliance enforcement. Watch for inflection upon publication of EU implementing guidance on manufacturer liability for barrel end-of-life recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in Alternative Sealing Compounds | German and Belgian operators secure F-Gas Regulation compliance ahead of enforcement windows. |
| Backward Integration into White Oak Stave Supply | Kentucky cooperages mitigate French and American harvest fluctuation exposure through captive sourcing. |
| RFID-Enabled Fleet Tracking Deployment | Predictive maintenance contracts open recurring revenue streams among high-turnover beverage clients. |
| Asset-as-a-Service Platform Launch | Craft distilleries in Colorado and Tennessee convert fixed capital to operating expenditure through leasing. |
| Regional Refurbishment Network Roll-up | Consolidation captures extended producer responsibility framework revenue concentration in EU markets. |
Methodological Framework
Bottom-up beverage and chemical logistics modeling reconciled against top-down steel and oak cooperage capacity tracking forms the analytical core of this study. Primary interviews with barrel pooling operators, distillery procurement managers, chemical logistics coordinators, and cooperage artisans were combined with secondary validation from FDA food-contact substance filings, ECHA REACH substance restriction databases, EU F-Gas Regulation implementation notices, and customs trade data on barrel imports. Triangulation between demand-side order flow analysis and supply-side refurbishment capacity assessments ensures cross-verification of volume and value estimates.
Historical trendline analysis across material substitution patterns and certification requirement evolution informs the projection framework. Segmentation dimensions modeled include material durability tier, functional configuration, end-use regulatory exposure, and geographic certification cluster. CAGRs were derived from fitted trend extrapolation adjusted for identified inflection drivers, with spirits maturation cycle frequency and pharmaceutical cold chain expansion serving as key industry-specific forecast inputs throughout the modeling period.
Inputs from EMA pharmaceutical packaging directives and FDA food-contact rulemaking were available through the study window; gaps in real-time barrel fleet utilization data from private pooling operators introduce uncertainty bands around transport-configuration demand estimates. Forecasts reflect documented assumptions regarding REACH substance restriction enforcement timing and F-Gas Regulation phase-down adherence. A model refresh is warranted upon material change in EU extended producer responsibility framework implementation or significant white oak harvest disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Reusable Straw Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Curbside Recyclable Packaging Market