
 Reusable Wrap Market | 2026-2036
Reusable Wrap Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Wrap Market Outlook
Market Context with Strategic Players
The capital-intensity divergence between small-batch beeswax producers and scaled silicone manufacturers is reorganizing competitive dynamics across the reusable wrap sector. Bee's Wrap, LLC leverages its Vermont-based cotton sourcing and domestic coating infrastructure to sustain premium positioning in North American health stores. Stasher competes through direct-to-consumer channel control and patented platinum silicone technology that extends product lifespan claims. Abeego Designs Inc. differentiates via hemp-blend substrates and food-grade wax formulations that anchor its presence in Canadian specialty retail.
Technical Definition and Structural Segments
Reusable wrap denotes pliable food storage substrates—typically organic cotton infused with beeswax, tree resin, and jojoba oil, or medical-grade silicone molded into sealable forms—engineered to replace disposable plastic film through hundreds of wash-reuse cycles. These products serve commercial and residential kitchens by creating breathable, moisture-resistant barriers that extend produce freshness without synthetic polymer waste. Beeswax-based sheets occupy the largest share of material-type value, while silicone bags capture the fastest expansion in product-form terms as bakeries and cafeterias adopt leak-proof alternatives. Roll formats dominate household purchasing through health stores and online channels, though pre-cut sheet assortments generate higher per-unit margins in specialty shops.
Regulatory Frame and Forward-Looking Close
The EU Single-Use Plastics Directive and REACH chemical compliance frameworks compel manufacturers to certify biodegradability thresholds and exclude petroleum-derived coatings from products sold within member states. France's AGEC anti-waste law and the UK's Plastic Packaging Tax further shape demand by penalizing virgin plastic use in food service procurement. The US EPA and state-level extended producer responsibility bills in California and New York create parallel compliance obligations for brands distributing across multiple jurisdictions. Stakeholders must monitor evolving wax sourcing traceability requirements and silicone recycling infrastructure investments as regulatory stringency tightens across primary demand centers.
Market Dynamics
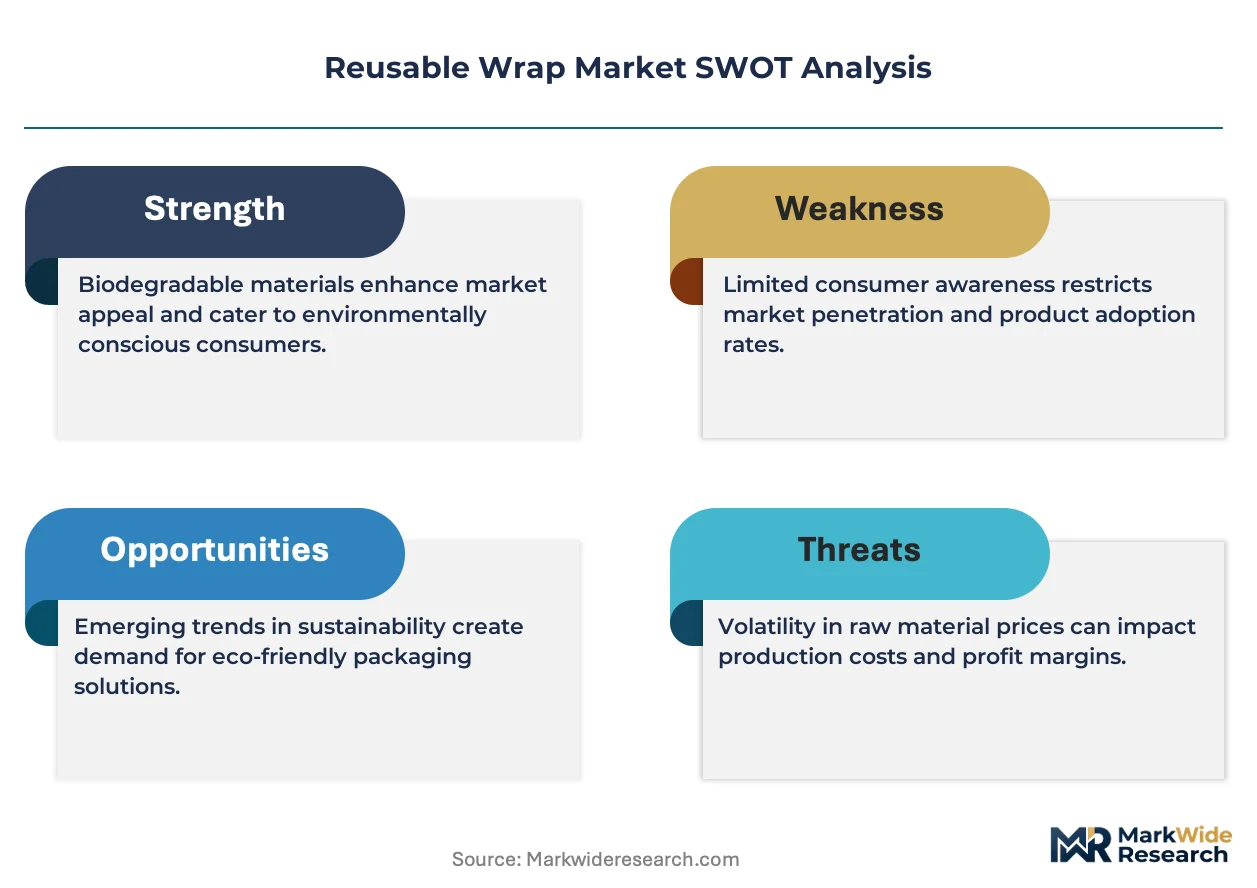
Municipal plastic bans are compressing demand for disposable film while concentrating purchasing power among zero-waste retailers, forcing substrate suppliers to certify biodegradability under REACH and state-level extended producer responsibility frameworks.
Growth Catalysts
- EU Single-Use Plastics Directive:Member states enforce mandatory reduction targets for food-contact plastics, redirecting food service procurement toward certified beeswax and silicone alternatives.
- Urban zero-waste retail expansion:Health stores and package-free shops in France, the United Kingdom, and the Netherlands stock reusable wraps as core inventory, normalizing household adoption.
- Cotton substrate innovation:Organic and hemp-blend fabrics improve pliability and wash durability, extending product lifespan claims and justifying premium positioning.
Market Restraints
- Beeswax supply volatility:Colony collapse disorder and climate stress on pollinator populations create input cost instability for natural wax coatings.
- Silicone manufacturing concentration:Medical-grade platinum silicone production clusters in East Asian chemical hubs, exposing brands to freight cost spikes and tariff exposure.
- Performance gaps versus plastic film:Beeswax wraps lack hermetic sealing for liquid storage, limiting substitution in commercial food processing and institutional catering.
Strategic Opportunities
- German municipal enforcement gaps:Smaller cities lag Berlin and Hamburg in plastic ban implementation, creating a window for distributor education and retail onboarding.
- Commercial bakery segment:Leak-proof silicone bags replace disposable containers for dough proofing and ingredient storage, opening volume contracts.
- France AGEC anti-waste law:Mandatory plastic reduction targets in public procurement create obligated demand from school cafeterias and hospital food service.
Industry Challenges
- REACH biodegradability certification timelines:Laboratory testing for wax coating breakdown extends product launch cycles by six to twelve months.
- Silicone recycling infrastructure gaps:End-of-life collection and reprocessing networks remain underdeveloped, complicating circular economy claims.
- Coating formulation IP disputes:Tree resin and jojoba oil blend patents create licensing friction between established brands and new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Wrap Market |
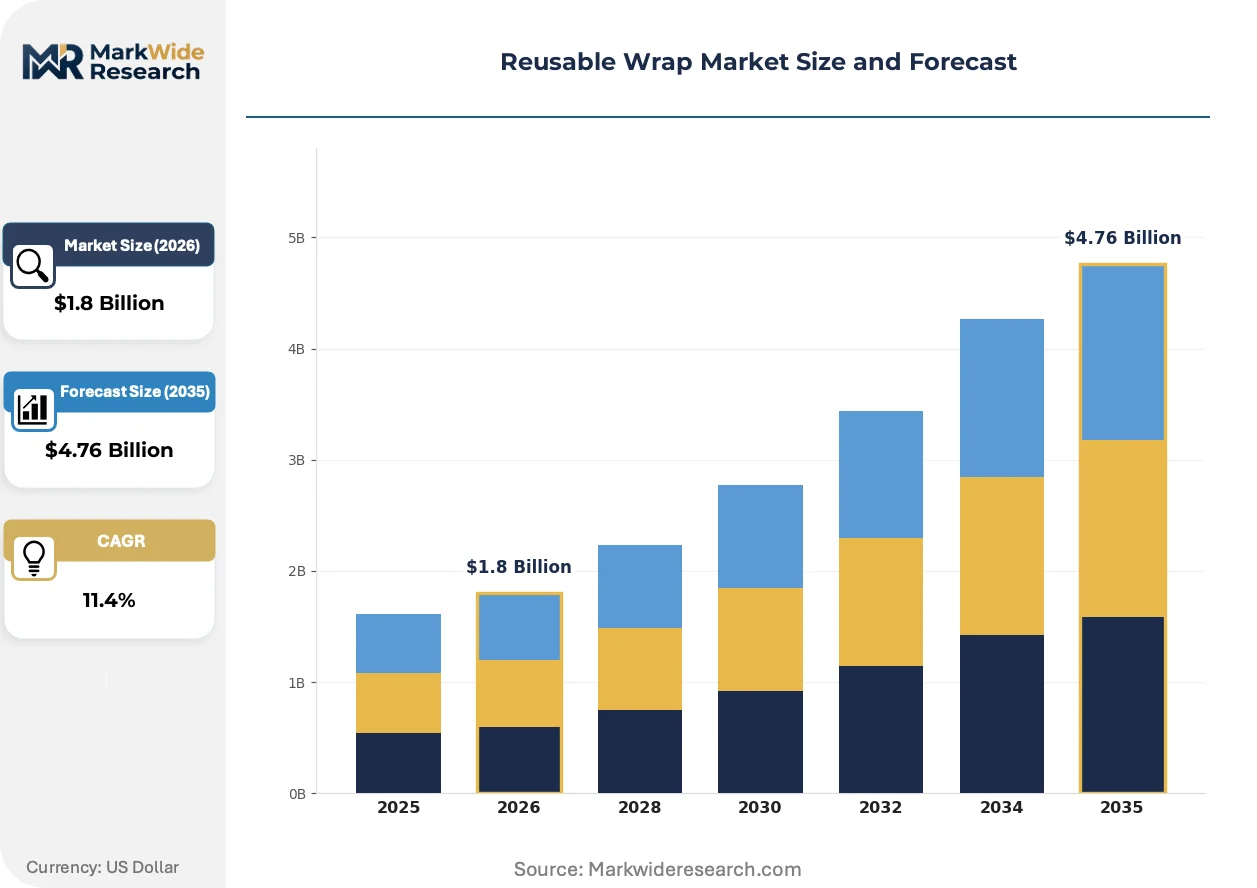
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cotton, Beeswax, Silicone, Hemp End User: Households, Bakeries, Restaurants, Cafeterias Product Form: Rolls, Sheets, Bags, Covers Sales Channel: Online, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Bee's Wrap, LLC, Abeego Designs Inc., The Beeswax Wrap Company Ltd, U-Konserve, Keep Leaf, ONYA LIFE, Stasher, Food Huggers, Re-Wrap-It, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Wrap Market Strategic Shifts
Material science advances and regulatory compliance automation are compressing product development cycles while expanding addressable use cases beyond household kitchens into commercial food preparation.
Plant-based polymer coatings derived from rice bran and candelilla wax are displacing traditional beeswax formulations in vegan-certified product lines. Specialty retailers and direct-to-consumer brands adopt these alternatives to capture ethical consumer segments. The shift is fragmenting raw material sourcing strategies and forcing suppliers to maintain multi-wax inventory positions.
REACH chemical compliance automation tools now embed batch-level traceability into manufacturing execution systems. Producers upload coating ingredient data directly to ECHA portals, accelerating market access documentation. Small-batch manufacturers in Vermont and British Columbia deploy these platforms to compete with scaled competitors on regulatory speed.
Food service buyers now specify certified compostable end-of-life pathways in procurement tenders, replacing price-per-unit metrics. Distributors respond by bundling take-back programs with volume contracts. This pattern is most visible in Dutch hospital systems and French public school catering networks.
Reusable Wrap Market Segmentation
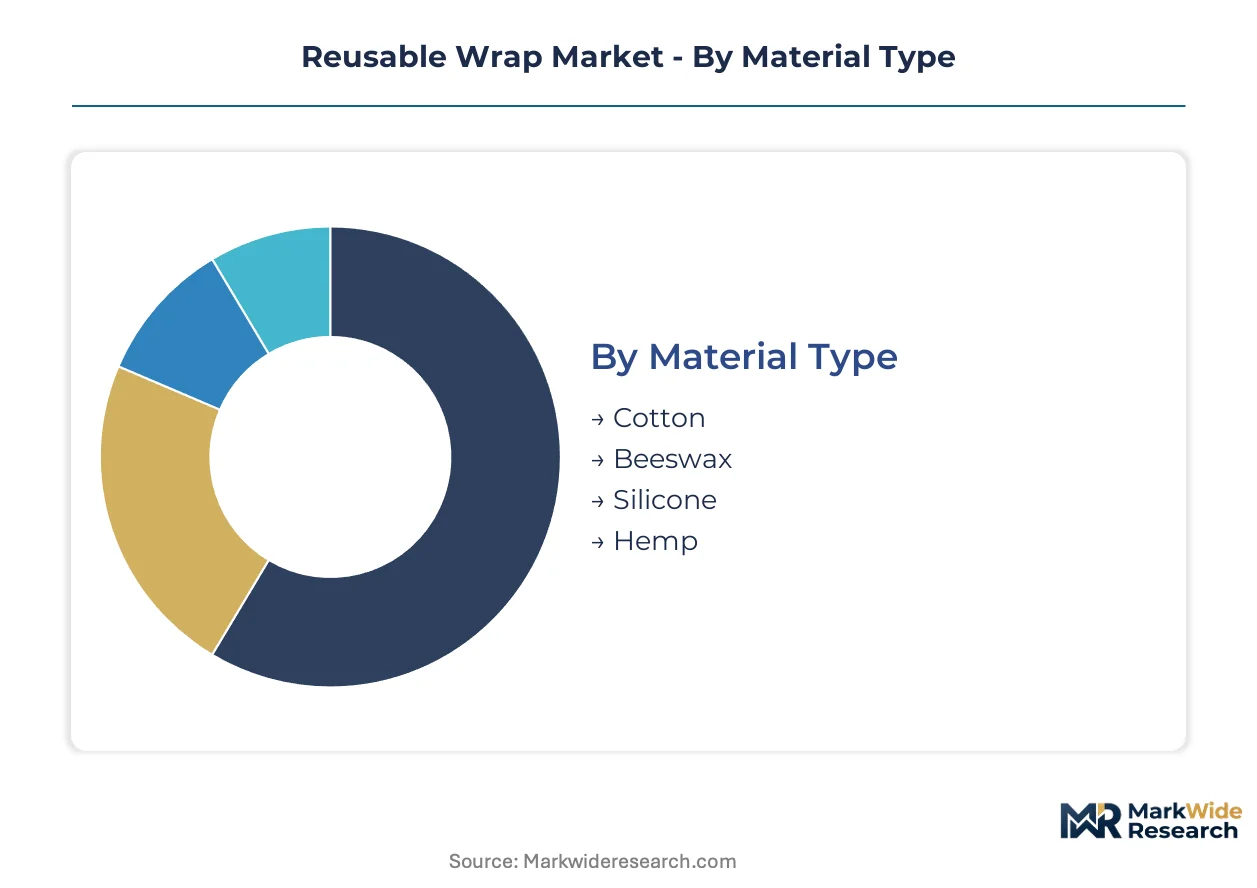
Segmentation in reusable wraps reveals how substrate chemistry, institutional procurement patterns, and retail channel economics create distinct competitive arenas. Manufacturers must align formulation investments with specific buyer workflows rather than pursuing universal product architectures.
Material Type:
Channel mix varies sharply by substrate: beeswax and hemp formulations flow predominantly through health stores and specialty shops where certification storytelling commands premium pricing, while silicone concentrates in online direct-to-consumer channels and supermarket household aisles where volume scale offsets lower per-unit margins.
- Beeswax:Organic cotton substrates infused with beeswax, tree resin, and jojoba oil create breathable, moldable barriers suited for produce and cheese storage. Demand clusters in German municipalities enforcing EU Single-Use Plastics Directive mandates, where zero-waste retailers stock certified biodegradable alternatives as core inventory.
- Silicone:Medical-grade platinum-cured silicone molded into sealable bags delivers hermetic closure for liquid storage and sous-vide applications. Bakeries and institutional cafeterias in France and the Netherlands specify these for dough proofing and ingredient containment, driven by AGEC anti-waste law procurement requirements and REACH compliance automation.
- Cotton:Uncoated or lightly treated organic cotton provides entry-level reusability for bread and dry goods. French health stores and UK package-free shops stock these as gateway products for households transitioning from plastic film.
- Hemp:Bast fiber blends offer superior wash durability and antimicrobial properties for high-frequency commercial use. Canadian specialty retailers and Vermont-based producers favor hemp for its lower water intensity versus conventional cotton cultivation.
Beeswax dominates installed base. Silicone is where expansion concentrates.
End User:
Cost tier stratification separates household purchasers seeking per-use economy from institutional buyers amortizing procurement across thousand-cycle lifespans.
- Households:Individual consumers purchasing 3-6 wrap assortments for weekly meal prep and produce storage. Urban clusters in Amsterdam, London, and Paris drive volume through zero-waste retail networks normalizing plastic-free kitchen transitions.
- Bakeries:Commercial dough proofing and ingredient staging operations requiring temperature-stable, reusable containment. French artisan bakeries and Dutch wholesale baking cooperatives specify silicone bags for fermentation workflows, replacing disposable pails and single-use film.
- Restaurants:Fine-dining and fast-casual kitchens using wraps for mise en place organization and herb preservation. Berlin and Hamburg establishments lead adoption under municipal plastic ban enforcement exceeding national minimums.
- Cafeterias:Institutional food service in schools, hospitals, and corporate dining facilities. French public school systems and Dutch hospital networks mandate certified compostable storage under AGEC and extended producer responsibility frameworks.
Households anchor volume throughput. Cafeterias are climbing the fastest on regulatory obligation.
Product Form:
Margin structure inverts between formats: rolls and sheets generate manufacturing efficiency through standardized cutting, while bags and covers command assembly premiums for zipper mechanisms and elastic edging.
- Rolls:Continuous substrate on cardboard cores enabling custom sizing for irregular produce and container shapes. UK and Netherlands online channels and health stores stock these as starter SKUs for household trial.
- Sheets:Pre-cut rectangles in standardized dimensions for sandwiches, cheese blocks, and half-fruit coverage. Specialty shops in France and Germany favor assortments for gift packaging and premium positioning.
- Bags:Three-dimensional silicone or coated fabric constructions with pinch-seal or slide-lock closures. Commercial bakery procurement in France and institutional cafeteria tenders in the Netherlands specify leak-proof certification for liquid and dough containment.
- Covers:Elastic-edged bowl and dish lids stretching to fit multiple container diameters. German household consumers adopt these for refrigerator organization under municipal waste reduction education campaigns.
Rolls capture household penetration. Bags are gaining share fastest on commercial contract expansion.
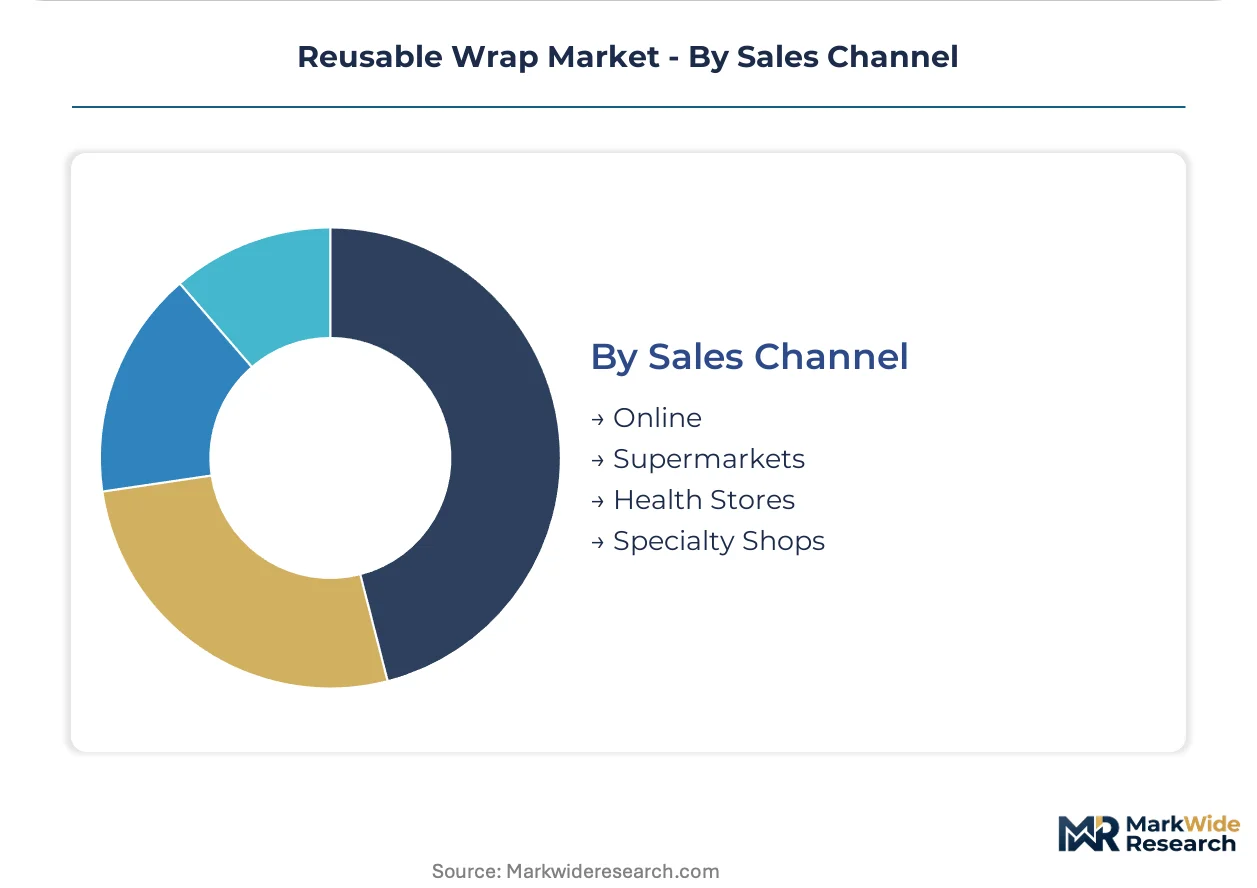
Sales Channel:
Geographic concentration of zero-waste retail infrastructure in France, the United Kingdom, and the Netherlands shapes channel performance more than e-commerce logistics alone.
- Online:Direct-to-consumer platforms and marketplace listings enabling subscription replenishment and educational content delivery. Silicone bag brands leverage this channel for lifecycle messaging and take-back program enrollment.
- Supermarkets:Mass retail placement in household goods aisles adjacent to traditional plastic film. UK supermarket chains and French hypermarkets stock entry-price cotton and beeswax SKUs for mainstream adoption.
- Health Stores:Independent and chain natural goods retailers with trained staff explaining coating chemistry and wash-care protocols. Amsterdam, London, and Paris zero-waste shop networks drive premium beeswax and hemp blend turnover.
- Specialty Shops:Kitchenware boutiques and eco-lifestyle concept stores curating aesthetic assortments for gift purchasing. Berlin and Hamburg specialty retailers emphasize local coating production and EU regulatory compliance documentation.
Health Stores dominate premium throughput. Online is where steepest expansion trajectory concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German and French urban clusters where municipal enforcement of EU plastic bans outpaces Southern European adoption curves. North American markets trade volume scale against thinner margins as mass retail penetration accelerates. Asia-Pacific demand remains nascent, concentrated in Australian health-store networks and Japanese specialty retail.
Germany
Berlin and Hamburg municipal authorities enforce plastic reduction mandates exceeding national minimums, redirecting restaurant procurement toward certified beeswax alternatives. The EU Single-Use Plastics Directive compliance deadlines pressure smaller cities to accelerate enforcement. Bavarian zero-waste retail cooperatives in Munich anchor premium product distribution through trained staff education programs.
France
Parisian package-free shop networks normalize household transitions from disposable film through curated starter assortments. The AGEC anti-waste law mandates plastic reduction targets in public school and hospital food service procurement. Lyon and Marseille specialty retailers emphasize local coating production traceability to differentiate premium positioning.
United Kingdom
London health-store clusters drive turnover for hemp-blend and organic cotton substrate variants. The Plastic Packaging Tax penalizes virgin plastic use in food service, redirecting bakery procurement toward silicone alternatives. Manchester and Birmingham supermarket chains stock entry-price SKUs adjacent to traditional plastic film aisles.
Netherlands
Amsterdam zero-waste retail infrastructure leads European household penetration rates for reusable wrap starter kits. Extended producer responsibility frameworks compel distributors to bundle take-back programs with volume cafeteria contracts. Rotterdam hospital networks specify certified compostable end-of-life pathways in procurement tenders.
United States
Vermont-based coating infrastructure sustains premium positioning in domestic health-store channels. California and New York state-level extended producer responsibility bills create parallel compliance obligations for multi-jurisdiction brands. Pacific Northwest specialty retailers emphasize domestic cotton sourcing narratives to justify price premiums against mass-market imports.
Reusable Wrap Market Competitive Environment
Concentration sits with small-batch natural substrate specialists competing against scaled silicone manufacturers with direct-to-consumer channel control. The vendor base splits between Vermont and British Columbia beeswax coating operations and East Asian medical-grade silicone fabricators. Three archetypes dominate: heritage craft producers, venture-backed silicone scale players, and private-label commodity suppliers. Competitive moves center on REACH compliance automation investments and zero-waste retail exclusivity contracts.
Within the heritage craft tier, Bee's Wrap, LLC and Abeego Designs Inc. exemplify geographic anchoring strategies that leverage Vermont and Canadian coating infrastructure for premium positioning. Stasher occupies the scale-driven silicone archetype with patented platinum-cured technology and direct-to-consumer lifecycle messaging. The Beeswax Wrap Company Ltd represents UK-based specialty retail distribution models focused on urban zero-waste shop networks.
| Leading Market Players |
|---|
| Bee's Wrap, LLC |
| Abeego Designs Inc. |
| The Beeswax Wrap Company Ltd |
| U-Konserve |
| Keep Leaf |
| ONYA LIFE |
| Stasher |
| Food Huggers |
| Re-Wrap-It |
| Others |
Value Chain & Pricing Dynamics
Plant-based polymer coatings displacing traditional beeswax formulations are simultaneously fragmenting raw material sourcing geography and compressing formulation cost premiums as suppliers maintain multi-wax inventory positions to serve vegan-certified product lines.
Pricing Analysis
The customization-premium spread between configured-to-order silicone bags and standard beeswax sheet assortments anchors a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—REACH-compliant coatings command 15-30% uplifts over uncertified alternatives—and volume scale in institutional procurement. Cost compression in silicone tiers is intensifying because medical-grade platinum-cured production concentrates in East Asian chemical hubs exposed to freight cost spikes. Household purchasers through health stores exhibit highest price sensitivity, while French public school systems under AGEC mandates show lowest sensitivity due to regulatory obligation.
Supply Chain Analysis
China and South Korea anchor medical-grade platinum silicone fabrication, while Vermont and British Columbia sustain beeswax coating operations for premium substrate producers. Raw material dependencies draw from cotton cultivation in Turkey and India, tree resin harvesting in Portugal, and jojoba oil extraction from Arizona and Argentina. Single-source vulnerability in East Asian silicone production creates exposure to tariff shifts and logistics chokepoints. Distribution runs through zero-waste retail cooperatives in Amsterdam and Paris, direct-to-consumer platforms for silicone brands, and supermarket household aisles for entry-price cotton SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in REACH compliance automation expertise and certified biodegradability testing capacity is concentrating competitive advantage among producers with embedded regulatory affairs capabilities rather than pure manufacturing scale.
For Market Incumbents: Compound channel control through exclusive zero-waste retail contracts in Berlin and Hamburg while accelerating backward integration into organic cotton sourcing to defend against private-label commodity entrants. Invest in coating formulation IP to preempt licensing disputes around tree resin and jojoba oil blends that threaten margin erosion. For New Entrants and Emerging Players: Differentiate on vegan-certified plant-based polymer coatings to capture ethical consumer segments underserved by heritage beeswax producers. Target German municipal enforcement gaps in smaller cities lagging Berlin and Hamburg for distributor education and retail onboarding. Pursue direct-to-consumer launch with subscription replenishment models to bypass established health store gatekeepers. For Investors and Strategic Acquirers: The market sits at a regulatory-obligation acceleration phase that favors vertically integrated producers with captive coating infrastructure and multi-jurisdiction compliance capabilities. Long-term viability over the next decade hinges on circular economy claims supported by silicone recycling infrastructure investments and take-back program scale. Acquisition target archetype: mid-cap silicone manufacturers with hospital network procurement relationships and ECHA portal integration expertise. The signal to watch is French AGEC procurement tender volume shifts toward certified compostable end-of-life pathway requirements.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Automation Investment | ECHA portal integration accelerates product launch cycles by six to twelve months for small-batch producers. |
| Zero-Waste Retail Exclusivity Contract | Amsterdam and Paris shop networks normalize household adoption through trained staff education programs. |
| Plant-Based Polymer Formulation Launch | Rice bran and candelilla wax alternatives capture vegan-certified segments fragmenting traditional beeswax demand. |
| Take-Back Program Bundling | Dutch hospital systems and French school cafeterias mandate certified compostable end-of-life pathways in procurement. |
| Backward Integration into Cotton Sourcing | Vermont-based domestic sourcing narratives justify price premiums against mass-market imports in Pacific Northwest specialty retail. |
Study Parameters
Initial hypotheses were tested against primary input from zero-waste retail buyers, coating formulation chemists, food service procurement managers, and regulatory affairs specialists at ECHA-registered producers, and refined through secondary validation against EU Single-Use Plastics Directive implementation reports, REACH certification databases, French AGEC procurement tender records, and customs trade data on beeswax and silicone imports. Bottom-up demand modeling across household, bakery, restaurant, and cafeteria segments triangulated with top-down market sizing from production capacity disclosures.
Variance decomposition across material type, end user, product form, and sales channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory enforcement timelines. Industry-specific forecast inputs incorporated colony collapse disorder impact assessments on beeswax supply and municipal plastic ban implementation velocity across German cities.
Material uncertainties—pollinator population stress, East Asian silicone production concentration, and REACH biodegradability certification timeline extensions—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and zero-waste retail network expansion rates. Recalibration cycles align with material shifts in EU directive implementation deadlines and municipal procurement obligation activation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Greenwrap Market
Reusable Packaging
Reusable Packaging Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Curbside Recyclable Packaging Market
Reusable Packaging
Refillable and Reusable Packaging Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Brazil Returnable Transport Packaging Market
Reusable Packaging
Micro-Packaging Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Reusable Produce Mesh Bag Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Reusable Consumer Packaging Market